
 Asia-Pacific Tequila Market | 2026-2036
Asia-Pacific Tequila Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Tequila Market Insights
Denominación de Origen Protegida certification is collapsing as a market-access gate, forcing non-authentic agave spirits to rebrand outside the tequila category. Diageo leverages its vertical integration from Jalisco agave fields through bottling to secure supply continuity across Australian and Japanese ports. Jose Cuervo anchors its position through century-old brand equity and controlled distribution into Asia-Pacific duty-free corridors. Patrón differentiates via small-batch tahona production and premium positioning in Singapore's rooftop bar circuit.
Tequila is a distilled spirit manufactured from Weber blue agave juice, fermented and double-distilled to 35-55% ABV, with aging duration determining color, tannin profile, and price tier. Blanco commands volume leadership across Asia-Pacific supermarkets due to lower price points and cocktail versatility, while Extra Añejo captures margin concentration in Tokyo and Melbourne collector markets. Duty-Free Shops represent the fastest-growing distribution channel as post-pandemic travel recovery funnels affluent Chinese and Korean tourists toward premium spirits purchases. Millennials sustain category expansion through social-media-driven discovery of craft margarita variations and agave-based alternatives to whisky.
Australia's Food Standards Code, Japan's National Tax Agency liquor labeling rules, and China's General Administration of Customs import documentation requirements collectively shape product registration timelines and front-label compliance costs. Becle and Brown-Forman navigate these frameworks through dedicated regulatory affairs teams in Sydney and Shanghai, pre-clearing NOM registry documentation before container shipment. Stakeholders must monitor evolving e-commerce alcohol licensing in Southeast Asian markets, where platform-specific permits now determine whether online retail can fulfill last-mile delivery legally.
Market Dynamics
Japan's National Tax Agency liquor labeling reforms and Australia's Food Standards Code revisions are compressing product registration timelines, forcing importers to pre-clear NOM documentation before container shipments reach Sydney and Yokohama ports.
Growth Catalysts
- Post-pandemic travel recovery:Duty-free corridors in Singapore Changi and Seoul Incheon are funneling affluent Chinese and Korean tourists toward premium spirits purchases, expanding the airport retail channel.
- Australia's craft cocktail bar sector:Bartenders in Melbourne and Sydney are driving agave spirit adoption through menu innovation and tequila-based alternatives to whisky cocktails.
- Japan's high-end izakaya chains:Premium on-premise venues in Tokyo are normalizing Extra Añejo consumption through collector-oriented bottle programs and aged expression flights.
Market Restraints
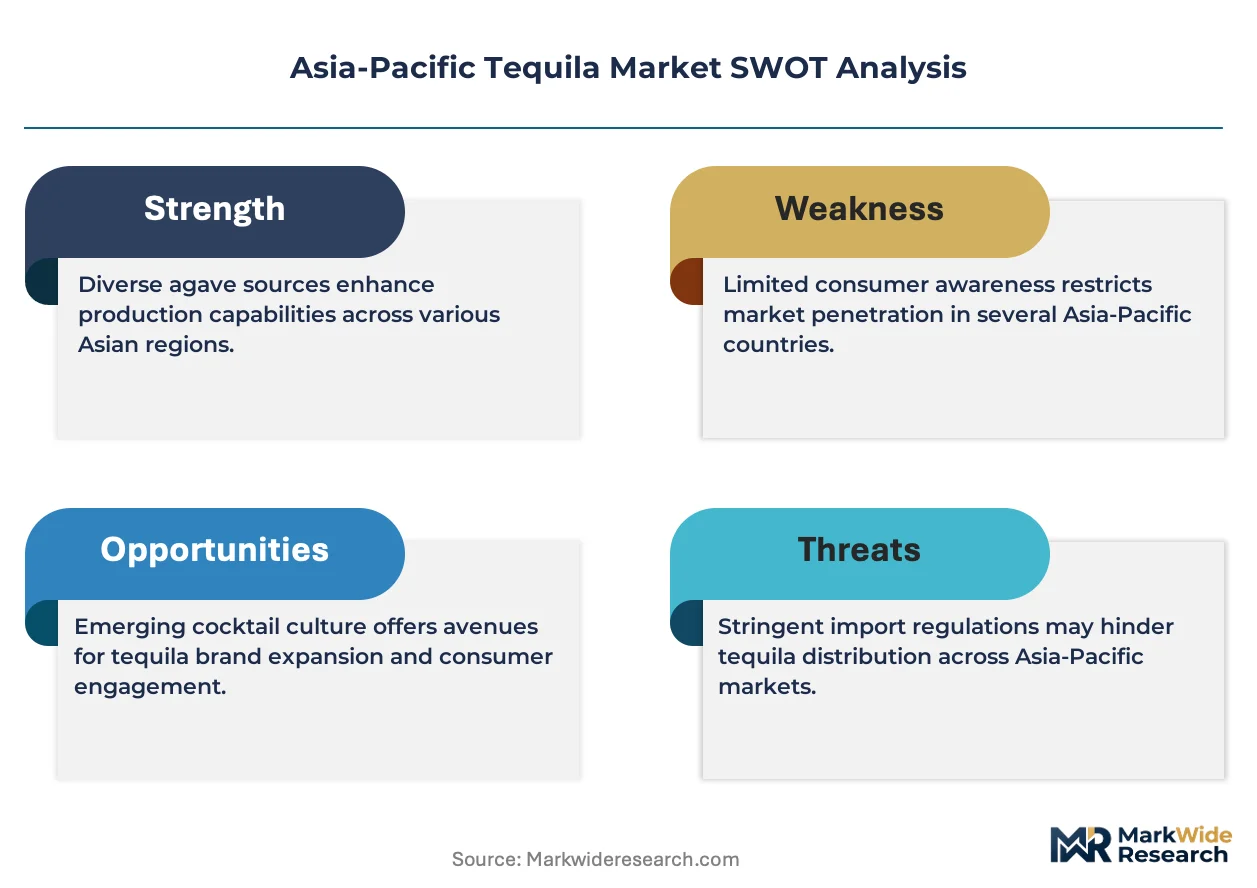
- Agave supply concentration:Weber blue agave cultivation concentrates in Jalisco, Mexico, exposing Asia-Pacific importers to harvest cycle volatility and price spikes.
- China's import documentation requirements:The General Administration of Customs mandates extensive front-label compliance costs that extend product registration timelines by 4-6 months.
- Denominación de Origen Protegida certification barriers:Non-authentic agave spirits face forced rebranding outside the tequila category, limiting portfolio expansion options for diversified spirits distributors.
Strategic Opportunities
- Southeast Asian e-commerce licensing evolution:Platform-specific permits in Thailand and Vietnam are creating new direct-to-consumer channels for brands that secure alcohol delivery licenses.
- Millennial social-media discovery:Instagram and TikTok-driven craft margarita variations are accelerating category education among first-time buyers in Australia and South Korea.
- Small-batch tahona production differentiation:Traditional stone-wheel crushing methods command premium positioning in Singapore's rooftop bar circuit and Melbourne collector markets.
Industry Challenges
- Regulatory affairs talent scarcity:Dedicated compliance teams capable of navigating simultaneous Australian, Japanese, and Chinese frameworks remain concentrated in Sydney and Shanghai, creating hiring bottlenecks.
- Dual inventory management complexity:Blanco volume leadership in supermarkets requires different warehousing protocols than Extra Añejo collector allocations, straining distributor logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Tequila Market |
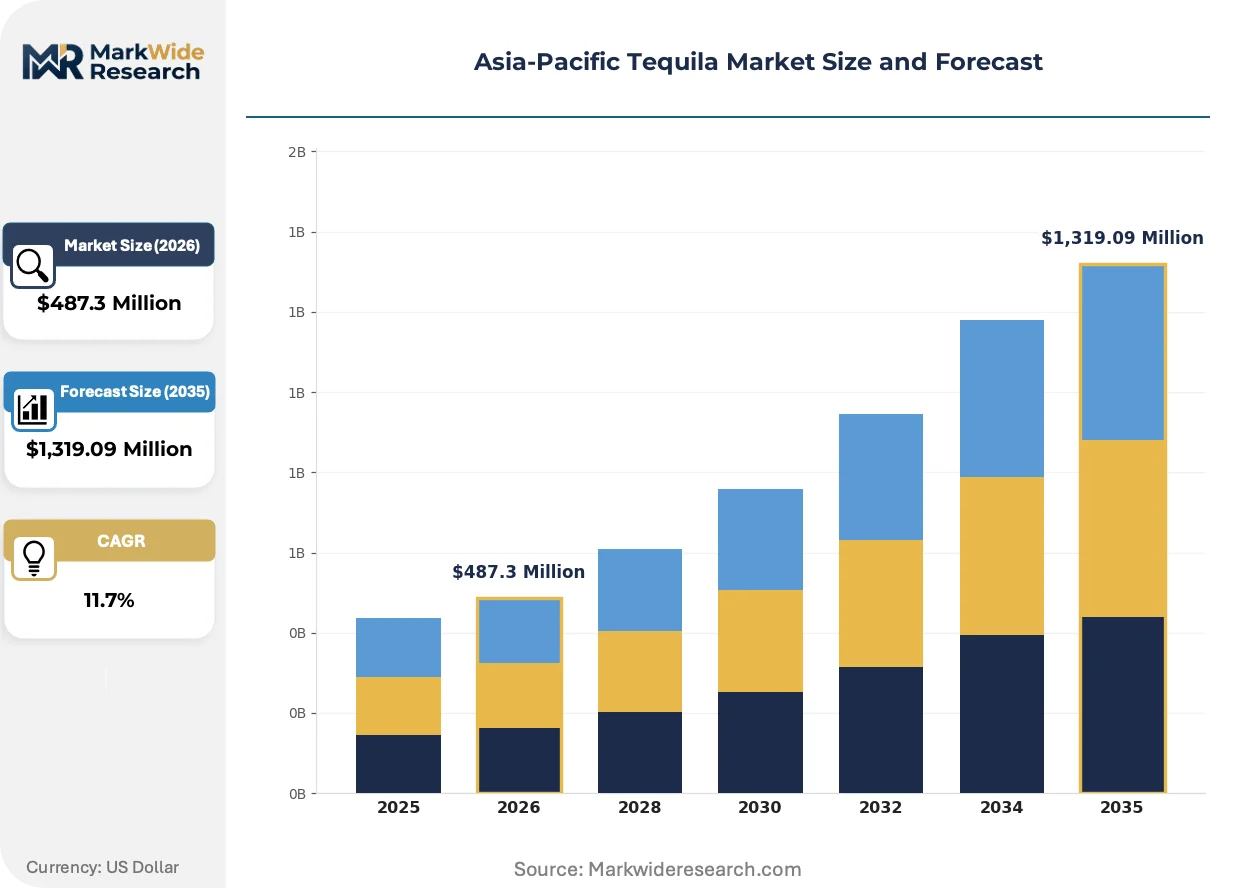
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blanco, Reposado, Añejo, Extra Añejo Distribution Channel: Online Retail, Supermarkets, Liquor Stores, Duty-Free Shops Consumer Type: Millennials, Gen Z, Affluent Buyers, Casual Drinkers Occasion: Celebrations, Parties, Casual Gatherings, Dinner Events |
| Companies Covered | Don Julio, Bacardi Limited, Diageo, Becle, Pernod Ricard, Jose Cuervo, Sauza, Brown-Forman, Patrón, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Tequila Market Trends and Innovations
Traditional production methods and digital traceability systems are converging to reshape how Asia-Pacific buyers authenticate provenance and justify premium pricing for aged expressions.
Tahona stone-wheel crushing is displacing roller-mill extraction in premium positioning strategies. Small-batch producers are adopting this labor-intensive method to differentiate viscosity and mouthfeel profiles. Singapore's rooftop bar circuit and Tokyo's high-end izakaya chains are absorbing these expressions at 40% price premiums over roller-mill equivalents, compressing margin structures for volume-focused competitors.
Australia's Food Standards Code now mandates stricter allergen labeling for agave spirits containing additives. This regulatory tightening is forcing importers to reformulate flavored expressions or segregate product lines by compliance tier. The craft cocktail bar sector in Melbourne and Sydney faces the steepest reformulation costs, while unflavored Blanco and Reposado categories navigate the transition with minimal disruption.
Chinese and Korean tourists are compressing their duty-free purchasing cycles into single-trip bulk acquisitions rather than gradual discovery. This behavioral shift is reshaping inventory planning for Singapore Changi and Seoul Incheon retailers, who must now stock deeper aged-expression reserves ahead of travel peak seasons. Tokyo's Narita Airport has responded by expanding dedicated tequila boutique footprints within its luxury spirits concourse.
Asia-Pacific Tequila Market Segmentation
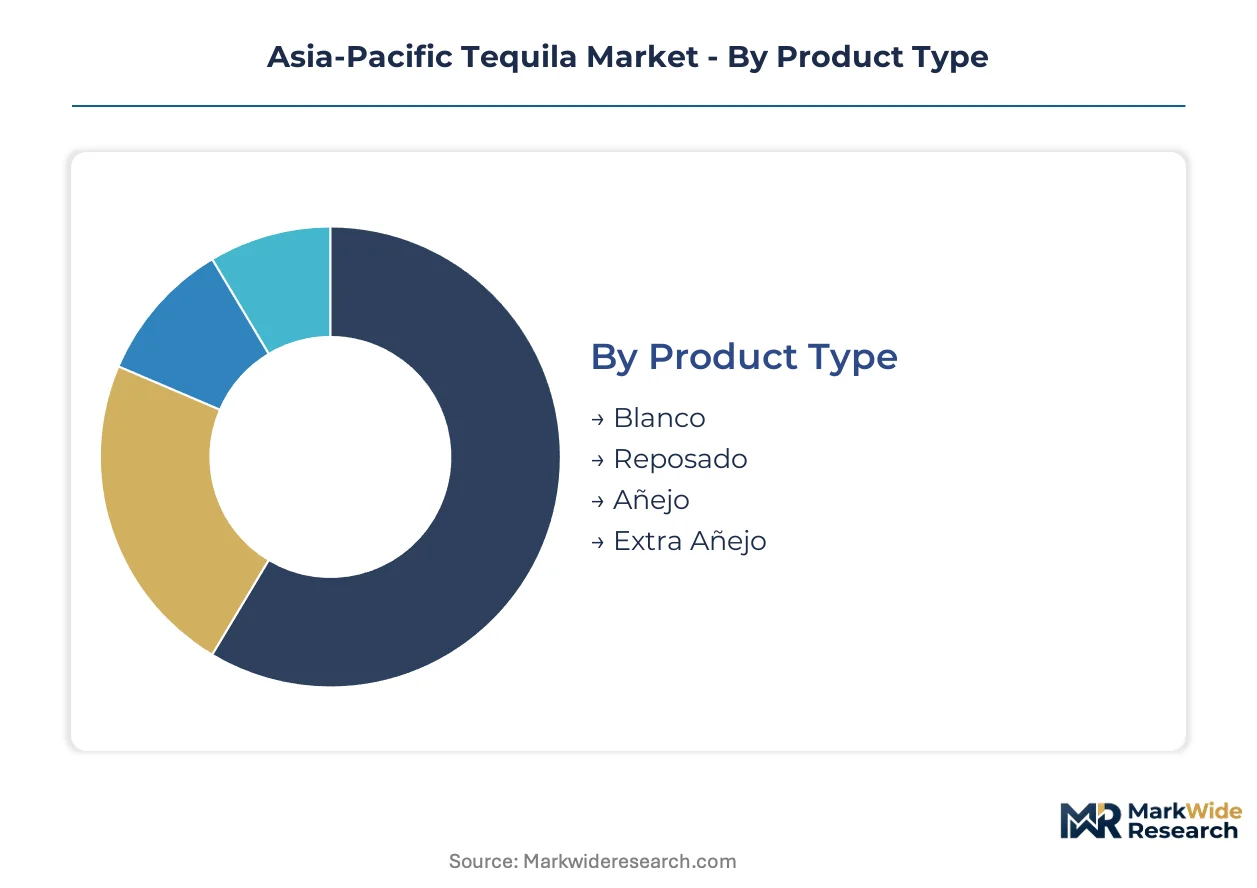
Margin concentration in Asia-Pacific tequila diverges sharply across aging tiers and purchase occasions, with premium expressions commanding collector premiums while unaged variants drive volume throughput. Understanding these segment boundaries enables distributors to align inventory allocation with distinct consumption rituals across Australian cocktail bars, Japanese izakaya chains, and Southeast Asian duty-free corridors.
Product Type:
Margin pools concentrate most heavily in aged expressions where extended barrel time justifies price premiums, while unaged variants sustain cash flow through higher turnover velocity.
- Blanco:Unaged tequila bottled immediately after distillation preserves raw agave character and citrus-forward aromatics. Australian supermarkets and Melbourne craft cocktail bars absorb this category for margarita bases and high-volume service, constrained by thin per-unit margins that demand scale logistics.
- Extra Añejo:Aged minimum three years in oak barrels, developing concentrated tannin structures and amber coloration. Tokyo collector markets and Singapore rooftop venues drive adoption through bottle programs and aged-expression flights, capturing the steepest margin premiums across the category.
- Reposado:Two-to-twelve month oak aging balances agave purity with subtle vanilla notes. Japanese izakaya chains favor this tier for food-pairing versatility.
- Añejo:One-to-three year maturation delivers pronounced caramel and spice profiles. Duty-free retailers in Seoul Incheon stock deeper reserves for Korean tourist bulk acquisition.
The dominant share belongs to Blanco, while Extra Añejo is closing the gap fastest.
Distribution Channel:
Channel selection determines regulatory burden intensity, with physical retail facing stricter labeling compliance than digital alternatives.
- Duty-Free Shops:Airport retail corridors in Singapore Changi and Seoul Incheon funnel affluent Chinese and Korean tourists toward premium spirits purchases. Post-pandemic travel recovery has compressed purchasing cycles into single-trip bulk acquisitions, forcing deeper aged-expression inventory ahead of peak seasons.
- Supermarkets:Australian chains dominate volume throughput for unaged expressions, leveraging standardized shelving and lower compliance overhead than on-premise channels.
- Online Retail:Platform-specific alcohol licenses in Thailand and Vietnam enable direct-to-consumer fulfillment where last-mile delivery laws permit.
- Liquor Stores:Independent Australian retailers and Japanese specialist shops curate premium portfolios for enthusiast discovery.
Duty-Free Shops command the steepest expansion trajectory, while Online Retail faces licensing fragmentation that varies by Southeast Asian market.
Consumer Type:
Purchase behavior splits between ritual-driven collectors and occasion-responsive casual buyers, with social media accelerating category education among younger demographics.
- Millennials:Instagram and TikTok discovery of craft margarita variations sustains category expansion across Australia and South Korea. This cohort demonstrates highest price elasticity for premium positioning and strongest responsiveness to small-batch provenance storytelling.
- Affluent Buyers:Concentrated in Tokyo and Singapore, this segment absorbs Extra Añejo allocations through collector-oriented bottle programs and vertical tastings.
- Gen Z:Entry-level experimentation concentrates in Australian university cities and Seoul nightlife districts.
- Casual Drinkers:Occasion-responsive purchases favor Blanco in supermarket and duty-free contexts.
Millennials anchor volume growth, though Affluent Buyers concentrate margin capture most intensely.
Occasion:
Consumption context dictates format preference, with formal dining driving aged expression adoption while informal gatherings sustain unaged volume.
- Dinner Events:Japanese high-end izakaya chains and Melbourne fine-dining venues normalize Extra Añejo and Añejo pairings through structured tasting menus. Australia's Food Standards Code allergen labeling mandates have forced reformulation of flavored expressions served in these contexts.
- Celebrations:Lunar New Year and wedding seasons across Chinese and Korean diaspora communities concentrate bulk purchasing in duty-free corridors.
- Parties:Sydney and Seoul nightlife venues drive Blanco throughput for shot service and rapid cocktail production.
- Casual Gatherings:Home consumption in Australian suburbs favors Reposado for sipping versatility.
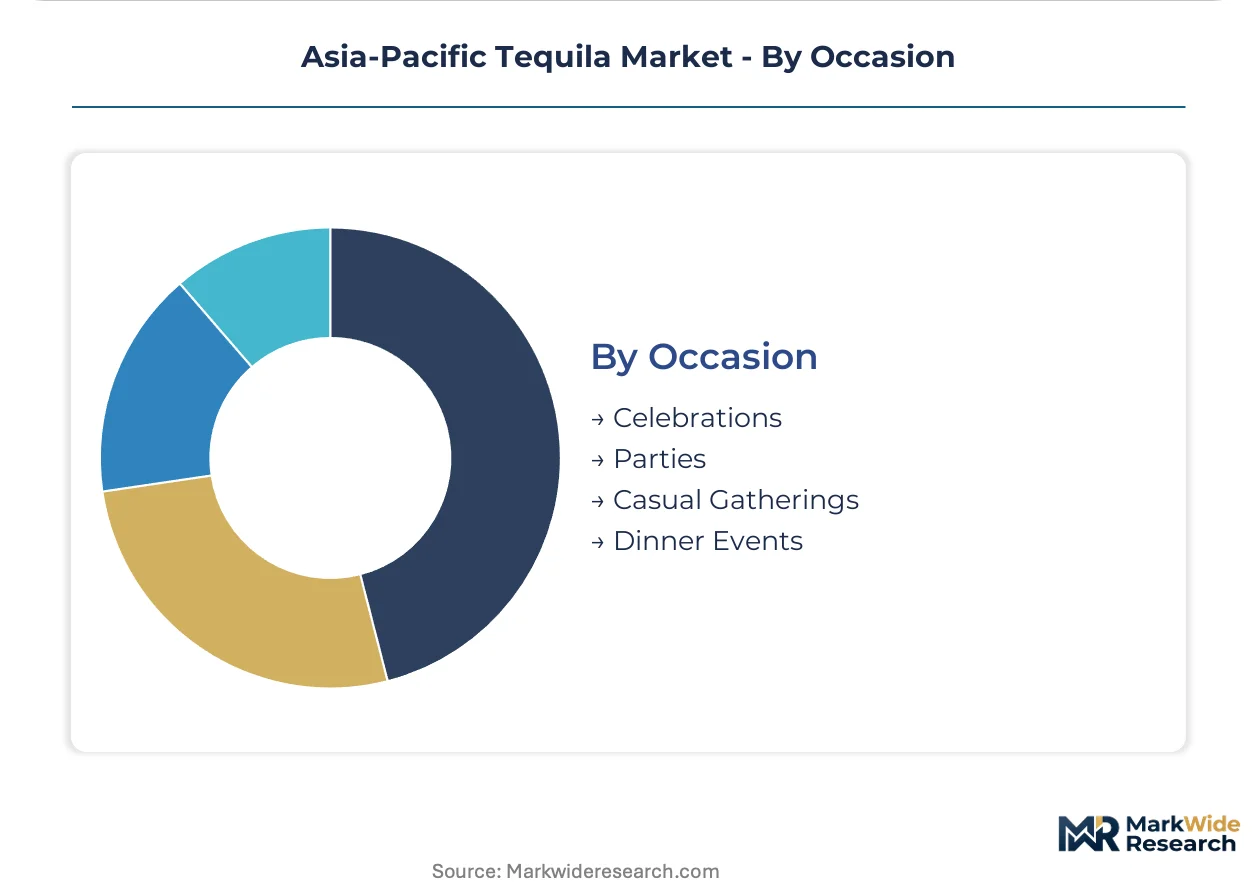
Dinner Events command the highest per-occasion spend, while Celebrations deliver the most concentrated seasonal demand spikes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's Food Standards Code and Japan's National Tax Agency liquor labeling reforms are compressing product registration timelines across the region. Importers now pre-clear NOM documentation before containers reach Sydney and Yokohama ports.
Australia
Melbourne and Sydney craft cocktail bars drive agave spirit adoption through menu innovation. The Food Standards Code mandates stricter allergen labeling for spirits containing additives. Independent retailers in Victoria curate premium portfolios for enthusiast discovery.
Japan
Tokyo's high-end izakaya chains normalize Extra Añejo consumption through collector-oriented bottle programs. National Tax Agency liquor labeling rules shape import compliance costs and front-label requirements. Osaka's premium on-premise venues absorb small-batch tahona expressions at significant price premiums.
South Korea
Seoul nightlife districts concentrate entry-level Gen Z experimentation with Blanco expressions. The Ministry of Food and Drug Safety (MFDS) regulates alcohol advertising and import documentation. Duty-free retailers at Incheon International Airport stock deeper aged-expression reserves for tourist bulk acquisition.
Singapore
Rooftop bars in the Central Business District command premium positioning for traditional production method tequilas. The country's strict food safety and labeling standards enforce compliance through the Singapore Food Agency. Changi Airport's luxury spirits concourse has expanded dedicated tequila boutique footprints ahead of travel peak seasons.
China
Affluent Chinese tourists compress duty-free purchasing into single-trip bulk acquisitions at overseas airports. The General Administration of Customs mandates extensive front-label documentation that extends registration timelines. Shanghai's regulatory affairs teams pre-clear NOM registry documentation for container shipments.
Asia-Pacific Tequila Market Competitive Landscape
Player mix skews toward vertically integrated multinational spirits conglomerates with captive agave supply chains. Market structure concentrates around heritage brand equity holders and premium positioning specialists. Two strategic archetypes dominate: Jalisco-origin houses with century-old distribution networks, and global portfolio companies leveraging duty-free corridor access. Competitive moves center on regulatory pre-clearance investments in Sydney and Shanghai, plus small-batch production differentiation for rooftop bar circuits.
Within the heritage-origin tier, Jose Cuervo anchors brand equity through controlled distribution into Asia-Pacific duty-free corridors. Diageo exemplifies vertical integration from Jalisco agave fields through bottling to secure supply continuity across Australian and Japanese ports. Patrón occupies a position emphasizing traditional tahona production methods for premium positioning in Singapore and Melbourne collector markets.
| Leading Market Players |
|---|
| Don Julio |
| Bacardi Limited |
| Diageo |
| Becle |
| Pernod Ricard |
| Jose Cuervo |
| Sauza |
| Brown-Forman |
| Patrón |
| Others |
Pricing and Supply Chain Analysis
Tahona stone-wheel crushing displacing roller-mill extraction simultaneously concentrates premium production in Jalisco highlands and compresses margin structures for volume-focused competitors unable to absorb labor-intensive methods.
Pricing Analysis
Cost-plus contracts indexed to agave harvest cycles dominate procurement between Jalisco growers and Asia-Pacific importers. Three-tier pricing structure across Extra Añejo, Reposado, and Blanco levels stratifies by aging duration and oak barrel provenance. Pricing pressure stems from Weber blue agave supply volatility in Mexico's Jalisco region. Supermarket buyers in Australia exhibit highest price sensitivity, while Tokyo collector markets absorb premiums with minimal elasticity.
Supply Chain Analysis
Jalisco, Mexico anchors Weber blue agave cultivation while Australia and Japan concentrate import bottling and distribution infrastructure. Raw material dependencies center on mature agave piñas, American oak barrels, and glass bottle sourcing from China. Single-source vulnerability in Jalisco harvest cycles exposes Asia-Pacific distributors to price spikes and allocation constraints. Distribution runs through controlled duty-free corridors at Singapore Changi and Seoul Incheon, with secondary channels via Australian supermarket chains and Japanese specialist retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific tequila demand tracks post-pandemic travel recovery as affluent Chinese and Korean tourists compress duty-free purchasing into single-trip bulk acquisitions.
For Market Incumbents: Fortify supply continuity through backward integration into Jalisco agave field ownership or long-term offtake agreements with certified growers. Lock in NOM registry documentation pre-clearance capabilities ahead of Australian Food Standards Code and Japan National Tax Agency labeling reforms. Prioritize regulatory affairs talent concentration in Sydney and Shanghai compliance hubs. For New Entrants and Emerging Players: Denominación de Origen Protegida certification fast-tracks through Mexico's CRT registry enable legitimate market access against forced-rebranding competitors. Target Southeast Asian e-commerce licensing white space in Thailand and Vietnam where platform-specific alcohol delivery permits remain underpenetrated. Lead with small-batch tahona production storytelling for Singapore rooftop bar circuit penetration. For Investors and Strategic Acquirers: The market sits at a recovery acceleration phase that favors vertically integrated heritage brands with captive agave supply and established Asia-Pacific duty-free relationships. Long-term viability hinges on regulatory pre-clearance infrastructure and collector-market aged-expression allocation capabilities. Watch agave harvest cycle reports from Jalisco as inflection indicators for margin compression or expansion windows.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Clearance Investment | Dedicated Sydney and Shanghai compliance teams compress product registration timelines before container arrivals. |
| Small-Batch Production Differentiation | Tahona stone-wheel methods command 40% price premiums in Singapore rooftop bars and Melbourne collector markets. |
| Duty-Free Corridor Expansion | Changi Airport and Incheon boutique footprints capture compressed tourist bulk purchasing cycles. |
| E-Commerce Licensing Securement | Platform-specific permits in Thailand and Vietnam unlock direct-to-consumer fulfillment channels. |
| Agave Supply Backward Integration |
Research Methodology
A standing panel of agave spirit importers, Australian craft cocktail bar owners, Japanese izakaya chain beverage directors, and Singapore duty-free retail buyers provided ongoing calibration throughout primary fieldwork. Secondary validation drew from Australia Food Standards Code filings, Japan National Tax Agency liquor labeling guidance, China General Administration of Customs import documentation requirements, and Korea MFDS alcohol advertising regulations. Bottom-up volume modeling triangulated against top-down category spend estimates.
Consistency checks validated outputs against customs clearance timelines, airport retail inventory turnover patterns, and on-premise menu adoption rates across the projection horizon. Segmentation dimensions modeled include aging tier, distribution channel, consumer archetype, and occasion type. CAGRs derived from weighted average of historical trajectory and demand elasticity assumptions. Forecast inputs incorporated agave harvest cycle reports and travel recovery passenger volume indices.
Decision-makers should treat outputs as directional under sustained post-pandemic travel recovery and stable Jalisco agave supply assumptions; material deviation in either would warrant model refresh. Specific risks include regulatory tightening in Southeast Asian e-commerce licensing and extended drought impacts on Weber blue agave maturation. Recalibration cycles align with material shifts in travel corridor passenger volumes and Mexican agricultural ministry harvest forecasts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
North America Alcoholic Beverages Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
Built-In Wine Coolers Market
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
Kegs Market
Alcoholic Beverages
Global Wine Coolers Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
Airport Duty-Free Liquor Market
Alcoholic Beverages
White Spirits Market
Alcoholic Beverages
Canned Cocktails Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Germany Alcohol E-Commerce Market
Alcoholic Beverages
South America Beer Market