
 Home Brewing Systems Market | 2026-2036
Home Brewing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Home Brewing Systems Market Foresight
The capital-intensity divergence between automated platform developers and traditional kettle manufacturers is reorganizing competitive tiers in home brewing equipment. LG Electronics leverages its consumer electronics supply chain to dominate connected brewing appliances with integrated app ecosystems. Blichmann Engineering sustains premium positioning through stainless steel fabrication depth and in-house kettle production. PicoBrew competes on recipe-cloud subscription models that extend beyond hardware margins into recurring revenue streams.
Home brewing systems encompass electrically heated or manually operated vessels, fermentation tanks, and temperature-controlled environments designed to produce beer, cider, or kombucha in non-commercial volumes, typically ranging from one to fifteen gallons per batch. Automated variants incorporate PID temperature controllers, pump-driven recirculation, and IoT connectivity to replicate professional brewhouse parameters for amateur brewers. All-in-One systems capture the largest installed base among hobbyists seeking compact footprint and simplified cleaning protocols, while conical fermenters represent the fastest-growing component segment as brewers prioritize yeast harvesting and clarity control. Electric brewing technology anchors the premium tier through precise mash temperature stepping, though manual kettle systems retain volume leadership in entry-level price bands where cost sensitivity dominates purchase decisions.
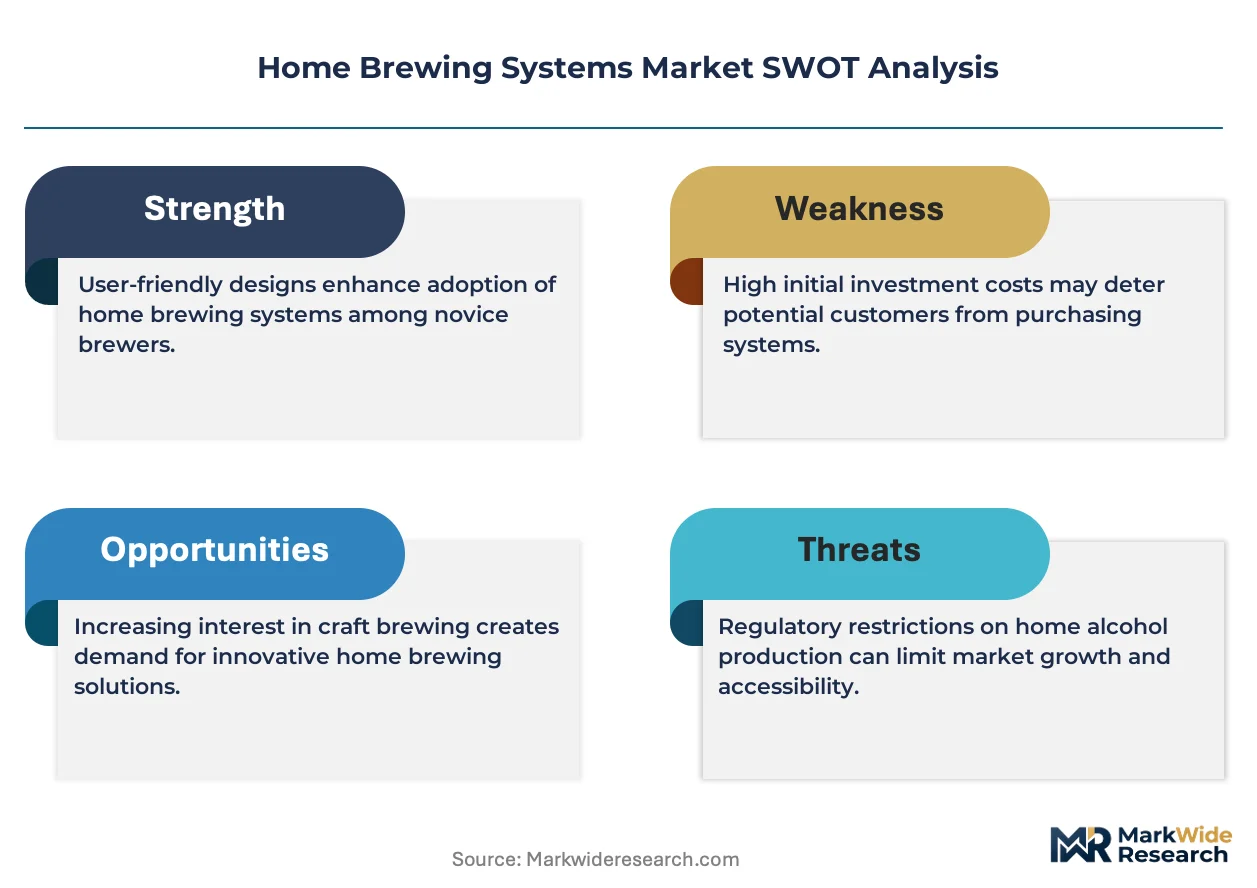
US home brewing equipment falls under FDA food-contact substance regulations and NSF/ANSI standards for beverage equipment sanitation, while EU manufacturers navigate EFSA migration limits and CE marking for electrical safety in kitchen appliances. REACH compliance on stainless steel surface coatings and RoHS restrictions on electronic components directly shape material selection and import feasibility for cross-border suppliers. Stakeholders must monitor evolving energy-efficiency labeling requirements and emerging state-level appliance efficiency standards that could alter electric system cost structures and market access conditions.
Market Dynamics
Automated electric brewing platforms are compressing manual kettle margins by embedding PID controllers and IoT connectivity as standard features, forcing traditional fabricators to absorb electronics supply chain complexity or retreat to entry-level price tiers.
Growth Catalysts
- EFSA Migration Limits:EU food-contact material standards under EFSA and REACH compliance are accelerating equipment replacement cycles as hobbyists upgrade to certified stainless steel systems that guarantee leachate safety during fermentation.
- Recipe-Cloud Subscriptions:Connected brewing appliances are generating recurring revenue streams through digital recipe marketplaces, transforming hardware vendors into platform operators with sustained customer engagement beyond initial purchase.
- Yeast Harvesting Demand:Conical fermenters are capturing hobbyist preference in Germany and the US as brewers prioritize clarity control and repitching economics, driving component-level premiumization within All-in-One configurations.
Market Restraints
- Stainless Steel Volatility:Nickel and chromium price swings in commodity markets directly compress fabrication margins for kettle manufacturers dependent on 304-grade sheet supply from concentrated Asian mills.
- Electronics Component Concentration:PID controller and sensor supply chains cluster in East Asian manufacturing hubs, exposing automated system assemblers to single-source risks for temperature probe assemblies.
- RoHS Compliance Friction:EU restrictions on lead and cadmium in electronic components force redesign cycles for legacy circuit boards, delaying product launches for kettle-to-automation converts.
Strategic Opportunities
- Underpenetrated Urban Clusters:Apartment-dwelling hobbyists in Tokyo and Seoul represent whitespace for compact countertop systems under ten-liter capacity that bypass space and ventilation constraints.
- Energy-Efficiency Labeling:Emerging state-level appliance efficiency standards in California and New York create first-mover advantage for heat-pump-integrated brewing systems that qualify for utility rebate programs.
- Kombucha Crossover:SCOBY fermentation protocols are attracting non-beer hobbyists to temperature-controlled platforms originally designed for wort, expanding addressable demand beyond traditional homebrew demographics.
Industry Challenges
- Embedded Systems Talent Gap:Kettle fabricators attempting automation transitions face acute shortages of firmware engineers capable of integrating Bluetooth stacks and cloud APIs into food-safe enclosures.
- NSF/ANSI Certification Timelines:Beverage equipment sanitation validation for US market entry requires six-to-twelve-month laboratory testing cycles that delay revenue recognition for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Brewing Systems Market |
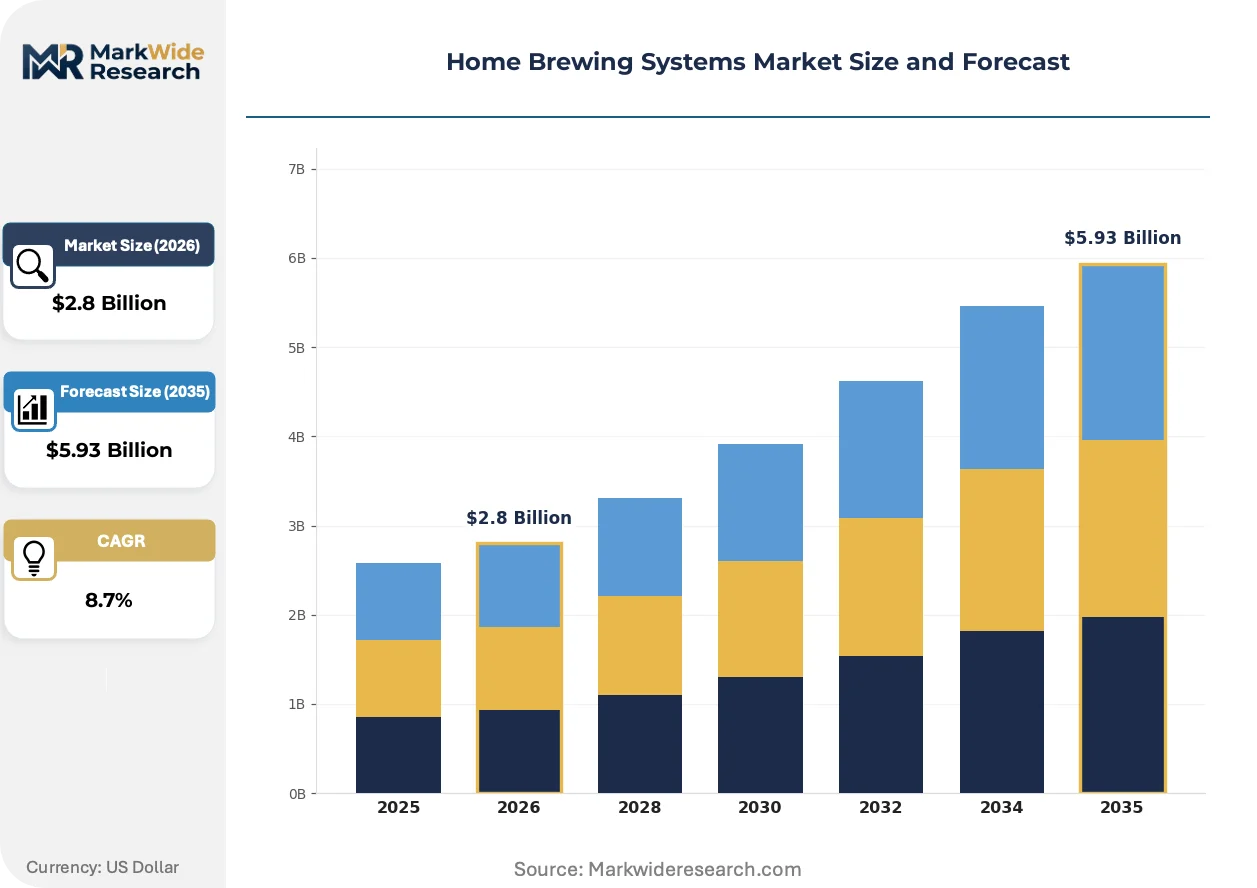
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-in-One Systems, Kettle Systems, Conical Fermenters, Portable Systems End User: Hobbyists, Small Commercial Breweries, Homebrewing Clubs, Culinary Schools Component: Brewing Kettles, Fermentation Tanks, Kegs, Cooling Systems Technology: Electric Brewing, Manual Brewing, Automated Brewing, Hybrid Systems |
| Companies Covered | BREWIE, MINIBREW, Speidel Tank und Behalterbau GmbH, Spike Brewing, BEERMKR, Blichmann Engineering, Brew Driver, PicoBrew, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Brewing Systems Market Shifts & Advancements
Modular component architectures and fermentation monitoring sensors are rewriting equipment upgrade economics. Vendors now compete on ecosystem lock-in rather than vessel durability alone.
Grainfather-style integrated mash tuns with built-in recirculation pumps are decomposing the traditional three-vessel brewhouse into single-unit appliances. Serious hobbyists in Australia and the UK are adopting these systems at accelerating rates. This consolidation is compressing demand for standalone hot liquor tanks and separate lautering equipment.
REACH enforcement on stainless steel surface coatings is tightening migration testing protocols for electropolished interiors. German manufacturers face mandatory third-party verification of chromium oxide layer stability. Premium conical fermenter lines destined for EU distribution are responding with laser-etched batch traceability and expanded alloy certification documentation.
Direct-to-consumer assembly is fragmenting traditional retail channel dominance. Specialty homebrew shops in Portland and Denver are losing equipment attachment rates to manufacturer-owned subscription services. This disintermediation is most visible among millennial first-time buyers who prioritize video tutorial integration over hands-on dealer support.
Home Brewing Systems Market Segmentation
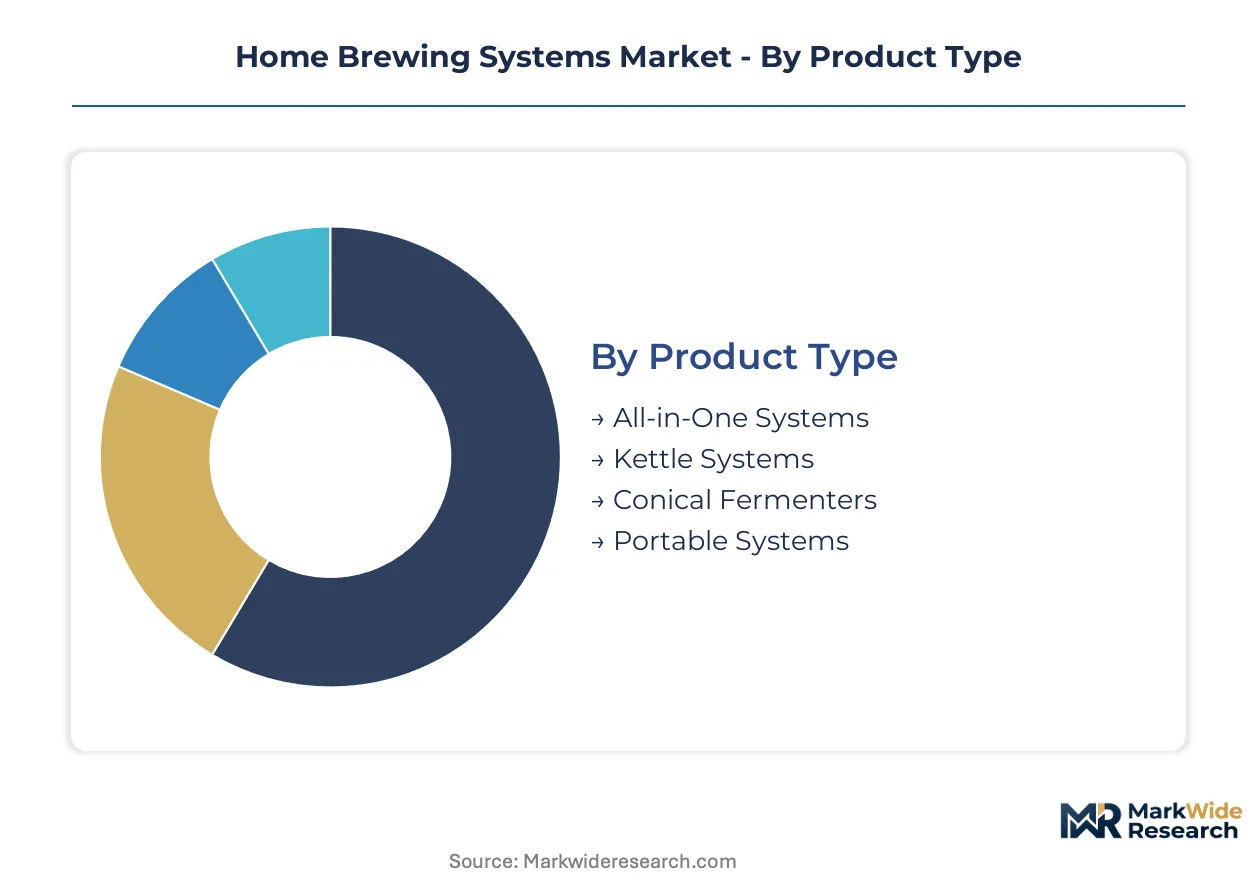
Equipment configuration and user sophistication create distinct demand pockets across the home brewing landscape. Segment boundaries blur as kettle manufacturers add automation modules and hobbyist platforms attract commercial microbreweries seeking pilot-scale testing.
Product Type:
All-in-One Systems dominate domestic hobbyist markets in Germany and the US, while Kettle Systems retain export strength through Southeast Asian craft beer incubators.
- All-in-One Systems:Integrated mash tun, recirculation pump, and heating element housed in single stainless steel enclosure. Demand concentrates in apartment-dwelling hobbyists across Tokyo, Seoul, and Berlin where space constraints and ventilation limitations favor compact footprints.
- Kettle Systems:Standalone heated vessels requiring manual transfer between mash, lauter, and boil stages. Traditional three-vessel configurations sustain volume leadership in entry-level price bands across India and Brazil where cost sensitivity dominates purchase decisions.
- Conical Fermenters:Temperature-controlled vessels with yeast harvesting valves. Australian and UK serious hobbyists prioritize clarity control and repitching economics, driving premium component sales.
- Portable Systems:Collapsible or battery-powered units for outdoor brewing. Compact designs address camping and festival applications in New Zealand and Colorado mountain towns.
All-in-One Systems hold the largest share; momentum sits with Conical Fermenters.
End User:
Cost tier stratification separates equipment investment thresholds, with culinary institutions commanding premium stainless steel specifications and hobbyist clubs negotiating volume discounts.
- Hobbyists:Individual consumers brewing one to fifteen gallon batches for personal consumption. German hobbyists accelerate replacement cycles under EFSA migration limit enforcement, upgrading to certified stainless steel systems.
- Small Commercial Breweries:Microbreweries using home-scale equipment for recipe development and pilot batches. US craft beer startups leverage these systems for TTB formula approval before scaling to production brewhouses.
- Homebrewing Clubs:Collective purchasing groups sharing equipment and bulk ingredient orders. Club density in Portland and Denver drives seasonal demand spikes for demonstration-grade automated systems.
- Culinary Schools:Hospitality programs incorporating fermentation science into curricula. Institutions in Switzerland and France specify NSF/ANSI-certified sanitation protocols for student laboratory environments.
Hobbyists anchor volume; Small Commercial Breweries generate the steepest expansion trajectory.
Component:
Supply concentration in Asian stainless steel mills shapes procurement patterns, with fermentation tank fabricators facing longer lead times than kettle suppliers.
- Brewing Kettles:Heated vessels for wort production ranging from five to twenty gallon capacities. 304-grade sheet supply from concentrated mills exposes fabricators to nickel and chromium price volatility.
- Fermentation Tanks:Sealed environments for yeast-driven sugar conversion. Conical variants with bottom-dump valves represent the fastest-climbing component category as brewers prioritize yeast harvesting.
- Kegs:Pressurized serving and conditioning vessels. Cornelius-style ball-lock configurations dominate US homebrew exchange networks.
- Cooling Systems:Immersion chillers and glycol circulation units for temperature crash. Heat-pump-integrated designs qualify for California and New York utility rebate programs.
Brewing Kettles retain installed base leadership; Fermentation Tanks are gaining share fastest.
Technology:
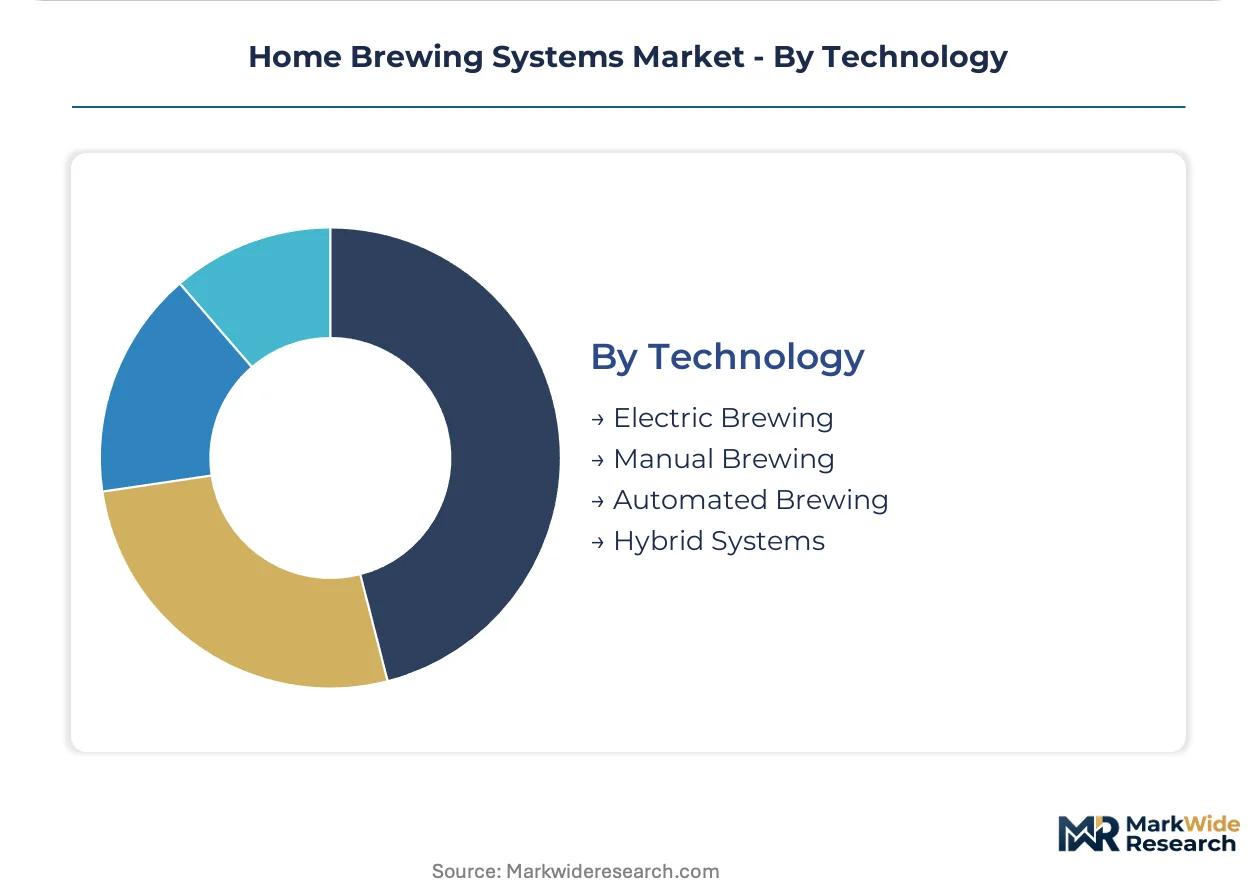
Maturity gradients separate established manual methods from emerging connected platforms, with firmware capabilities becoming the primary vendor differentiator.
- Electric Brewing:Resistive or induction heating with precise wattage control. PID temperature controllers enable mash stepping accuracy that anchors the premium equipment tier.
- Manual Brewing:Propane or stovetop heating without electronic intervention. Entry-level price bands in cost-sensitive markets sustain this category's volume position.
- Automated Brewing:IoT-connected systems with recipe-cloud integration and remote monitoring. Firmware engineering scarcity constrains kettle fabricators attempting automation transitions.
- Hybrid Systems:Modular architectures allowing manual override of automated functions. Serious hobbyists in Australia and the UK adopt these for flexibility across recipe complexity.
Manual Brewing maintains broadest penetration; Automated Brewing climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and US markets where certification premiums offset stainless steel volatility, while Southeast Asian craft beer incubators absorb entry-level kettle volumes at compressed margins.
United States
Hobbyist clubs in Portland and Denver drive seasonal demand spikes for demonstration-grade automated systems. FDA food-contact substance regulations and NSF/ANSI standards govern equipment sanitation protocols. California and New York state-level appliance efficiency standards create first-mover advantage for heat-pump-integrated brewing systems qualifying for utility rebate programs.
Germany
EFSA migration limits and REACH compliance accelerate equipment replacement cycles as hobbyists upgrade to certified stainless steel systems. The country's national food safety regulator enforces mandatory third-party verification of chromium oxide layer stability. Bavarian manufacturers respond with laser-etched batch traceability and expanded alloy certification documentation for premium conical fermenter lines.
Australia
Grainfather-style integrated mash tuns with built-in recirculation pumps attract serious hobbyists seeking single-unit appliance consolidation. The national therapeutic goods regulator maintains beverage equipment standards that align with EU migration testing protocols. Melbourne and Sydney homebrewing communities anchor demand for clarity-controlled fermentation systems with yeast harvesting capabilities.
Japan
Apartment-dwelling hobbyists in Tokyo represent whitespace for compact countertop systems under ten-liter capacity that bypass space and ventilation constraints. METI energy-efficiency labeling programs shape electric system cost structures and market access conditions. Osaka-based specialty retailers face disintermediation pressure from manufacturer-owned subscription services targeting millennial first-time buyers.
Brazil
Traditional three-vessel kettle configurations sustain volume leadership in entry-level price bands where cost sensitivity dominates purchase decisions. ANVISA food-contact material standards create compliance friction for imported automated systems. São Paulo craft beer incubators leverage home-scale equipment for recipe development before scaling to production brewhouses.
Home Brewing Systems Market Competitive Landscape
Concentration sits with consumer electronics conglomerates and precision fabrication specialists who command premium positioning through supply chain control and materials expertise. The vendor base spans three tiers: multinational appliance manufacturers with integrated app ecosystems, stainless steel fabricators with in-house kettle production depth, and connected-platform operators monetizing recipe-cloud subscriptions. Strategic moves center on backward integration into sensor supply chains and geographic expansion into underpenetrated urban clusters.
Within the premium fabrication tier, Speidel Tank und Behalterbau GmbH exemplifies German engineering depth in vessel construction, while Blichmann Engineering occupies a position among North American precision metalworkers. PicoBrew represents the connected-platform archetype, anchoring the subscription-revenue vector that extends beyond hardware margins. These three companies collectively illustrate the competitive divergence between materials-led and software-led market positioning.
| Leading Market Players |
|---|
| BREWIE |
| MINIBREW |
| Speidel Tank und Behalterbau GmbH |
| Spike Brewing |
| BEERMKR |
| Blichmann Engineering |
| Brew Driver |
| PicoBrew |
| LG Electronics |
| Others |
Supply & Pricing Matrix
Capacity utilization in Asian stainless steel mills directly shapes price floors for kettle fabricators, compressing margins at entry tiers while automated system assemblers absorb electronics premiums through subscription bundling. Scale concentration in 304-grade sheet production creates asymmetric pricing power between manual kettle suppliers and platform operators with captive component sourcing.
Pricing Analysis
The customization-premium spread separates configured-to-order conical fermenters with laser-etched traceability from standard All-in-One systems. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA certification grade and NSF/ANSI validation status as primary differentiation drivers. Cost compression in manual kettle tiers is intensifying because Brazilian and Indian buyers prioritize volume scale over feature depth. Hobbyist clubs in Portland and Denver exhibit least price sensitivity, while first-time apartment brewers in Tokyo drive economy tier velocity.
Supply Chain Analysis
China and South Korea anchor PID controller and temperature probe assembly production, with Taiwan feeding precision sensor substrates. German and Italian stainless steel fabricators draw from concentrated Asian mills for 304-grade sheet, exposing kettle manufacturers to nickel and chromium commodity volatility. Single-source vulnerability in East Asian electronics hubs threatens automated system assemblers during component allocation cycles. Distribution runs through direct-to-consumer subscription channels and specialty homebrew retailers, with manufacturer-owned platforms disintermediating traditional dealers among millennial first-time buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery driven by EFSA-mandated equipment replacement cycles in Germany, where migration limit enforcement accelerates certified stainless steel upgrades. The replacement wave creates temporary demand elevation above trendline hobbyist adoption.
For Market Incumbents: Secure firmware engineering talent through acquisition of connected-platform specialists before kettle-to-automation transitions stall. Lock in multi-year 304-grade sheet offtake agreements with Asian mills to buffer nickel price volatility. Defend against PicoBrew-style subscription competitors by embedding recipe-cloud functionality into existing hardware lines.
For New Entrants and Emerging Players: Video tutorial integration gaps among legacy fabricators create entry points for millennial-first-buyer acquisition. Target compact countertop systems under ten-liter capacity for Tokyo and Seoul apartment clusters where ventilation constraints block traditional kettle adoption. Launch through manufacturer-owned subscription services rather than specialty retail channels to bypass established dealer networks.
For Investors and Strategic Acquirers: Precision metalworkers with in-house kettle production and EFSA certification depth represent prime acquisition targets before consolidation accelerates. Long-term viability hinges on backward integration into sensor supply chains and platform ecosystem lock-in. Watch for heat-pump-integrated system qualification in California and New York utility rebate programs as inflection signal for energy-efficiency tier premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Recipe-Cloud Platform Integration | Transforms hardware vendors into recurring-revenue operators with sustained PicoBrew-style engagement. |
| EFSA Certification Investment | Unlocks German replacement cycle demand through third-party chromium oxide layer verification. |
| Backward Integration into Sensors | Reduces single-source exposure to East Asian PID controller allocation constraints. |
| Compact System Development | Captures Tokyo and Seoul whitespace where space and ventilation limitations block traditional equipment. |
| Direct-to-Consumer Subscription Launch | Bypasses Portland and Denver specialty retailer disintermediation through manufacturer-owned video tutorial integration. |
Research Methodology
A spread of perspectives from equipment fabricators, fermentation specialists, homebrew club organizers, and culinary school procurement managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with stainless steel mill procurement leads and electronics component distributors with secondary validation through FDA food-contact substance filings, EFSA migration limit documentation, and NSF/ANSI certification records. Bottom-up unit economics for All-in-One and conical fermenter configurations were triangulated against top-down market sizing from trade customs data and regional hobbyist population estimates.
Segmentation dimensions modeled include product configuration, end-user sophistication tier, component category, and heating technology type across the projection horizon. CAGRs were derived from installed base replacement velocity, new hobbyist adoption curves, and premium tier expansion patterns. Forecast inputs incorporated EFSA enforcement timelines, REACH compliance cost pass-through assumptions, and utility rebate program qualification thresholds for heat-pump-integrated systems.
Material uncertainties — nickel and chromium commodity swings, RoHS redesign delays for legacy circuit boards, and firmware engineering scarcity — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and electronics supply chain normalization. Recalibration cycles align with material shifts in EU food-contact material enforcement and state-level appliance efficiency standard adoptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Wine Filling Machine Market
Alcoholic Beverages
US Wine Market
Alcoholic Beverages
Pressurized Wine Filter System Market
Alcoholic Beverages
Global Food-Grade Alcohol Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Premium Wine Cooler Market
Alcoholic Beverages
North America Craft Beer Market
Alcoholic Beverages
Beer Line Cooling System Market
Alcoholic Beverages
White Wine Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
South America Wine Market
Alcoholic Beverages
Global Bourbon Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Ethyl Alcohol (Ethanol) Market