
 Tonic Wine Market | 2026-2036
Tonic Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Tonic Wine Market Analysis
Herbal extracts and natural bittering agents is restructuring cost structures across tonic wine portfolios, reducing reliance on synthetic additives while elevating raw material standards. Wincarnis leverages its century-old formulation heritage to sustain premium positioning in British Commonwealth markets. Buckfast Tonic Wine anchors volume through monastic production credentials and deep Scottish distribution control. Diageo competes by extending its spirits expertise into fortified wine adjacencies with scaled manufacturing efficiency.
Tonic wine denotes a fortified wine infused with herbal extracts, quinine, and vitamins, historically formulated to deliver restorative properties with alcohol content typically ranging from 14% to 17% ABV. The beverage serves commercial purposes as both a standalone aperitif and a cocktail mixer in on-trade environments. Herbal tonic wine captures the fastest-growing position within product type segmentation as wellness-oriented consumers gravitate toward botanical complexity and perceived functional benefits. Retail outlets and online consumers represent the most dynamic end-user channels, diverging from the mature on-trade base where bars and restaurants face slower traffic recovery.
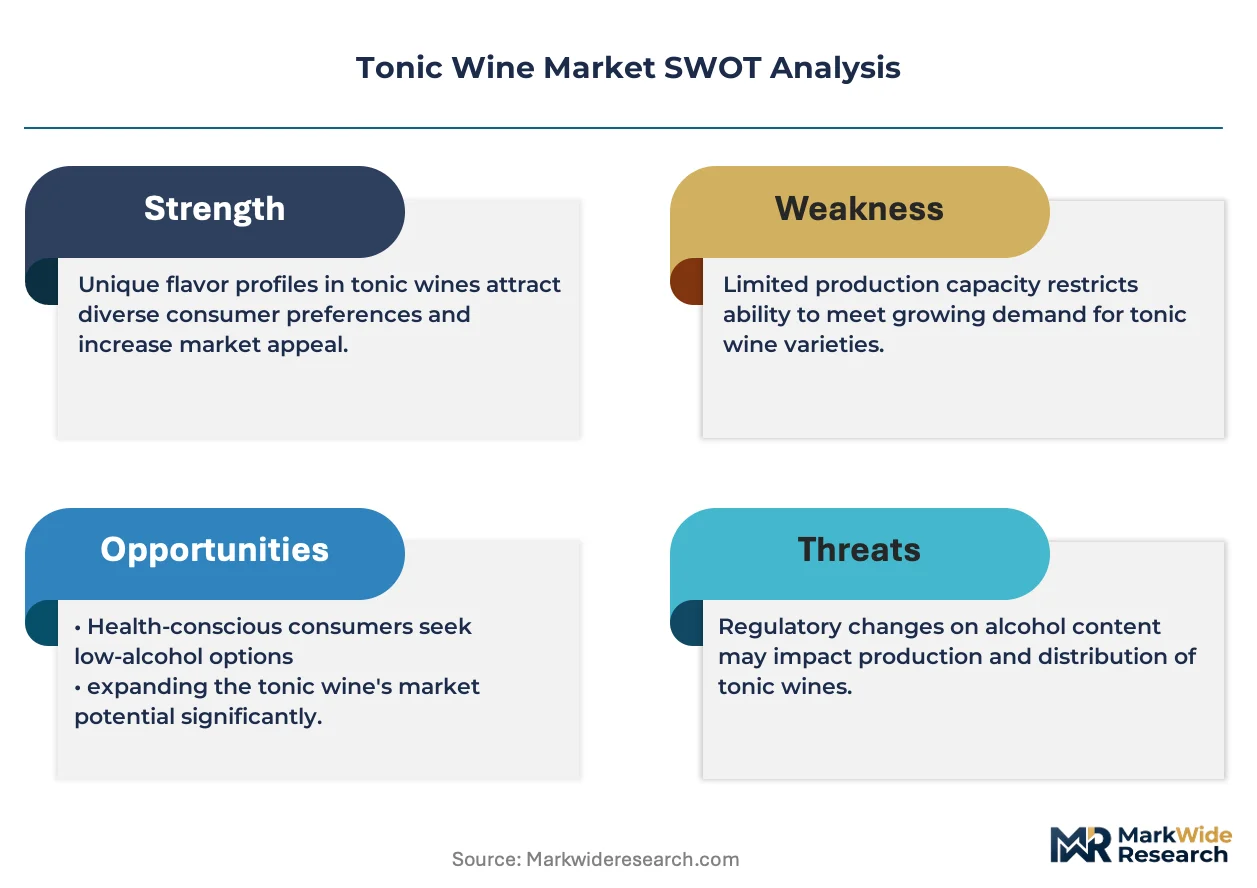
The UK's Food Standards Agency and the EU's EFSA govern additive approvals and health claim restrictions that directly constrain tonic wine labeling and cross-border marketing. REACH compliance on chemical constituents in flavoring compounds adds formulation costs for producers serving European markets. Stakeholders must monitor evolving alcohol duty structures and low-alcohol threshold definitions that could recategorize products and trigger reformulation investments.
Market Dynamics
The EU's F-Gas Regulation is forcing tonic wine producers to abandon traditional glass bottling in favor of sustainable packaging alternatives, compressing margins while accelerating material innovation across European supply chains.
Growth Catalysts
- Urban millennial premiumization:United Kingdom city centers are absorbing higher price points as heritage positioning resonates with wellness-conscious drinkers seeking botanical authenticity.
- REACH compliance maturation:ECHA chemical safety standards have stabilized flavoring compound approval pathways, reducing regulatory uncertainty for reformulated herbal extract portfolios.
- Monastic production credentialing:Scotland's controlled distribution networks leverage ecclesiastical heritage to secure repeat purchase loyalty in on-trade channels.
Market Restraints
- Quinine supply concentration:Cinchona bark sourcing depends on limited Andean cultivation zones, exposing producers to climatic volatility and geopolitical disruption.
- Alcohol duty threshold rigidity:United Kingdom Treasury definitions of low-alcohol categories create reformulation cost barriers for products near the 14% ABV boundary.
- Synthetic additive substitution pressure:Consumer preference for natural bittering agents eliminates cost advantages of artificial quinine alternatives.
Strategic Opportunities
- English retail channel expansion:Supermarket and specialist off-licence networks in Manchester and Birmingham remain underdeveloped relative to Scottish penetration rates.
- EFSA health claim pathway navigation:Botanical functional benefit documentation could unlock approved positioning statements for vitamin-fortified variants.
- Direct-to-consumer platform development:Subscription models bypass traditional wholesale markups while capturing urban millennial data for personalization.
Industry Challenges
- Herbal extract standardization expertise:Formulation chemistry talent capable of stabilizing natural bittering agents commands premium compensation in competitive beverage labor markets.
- Legacy bottling asset stranding:Glass furnace investments face accelerated depreciation as F-Gas compliance deadlines approach.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tonic Wine Market |
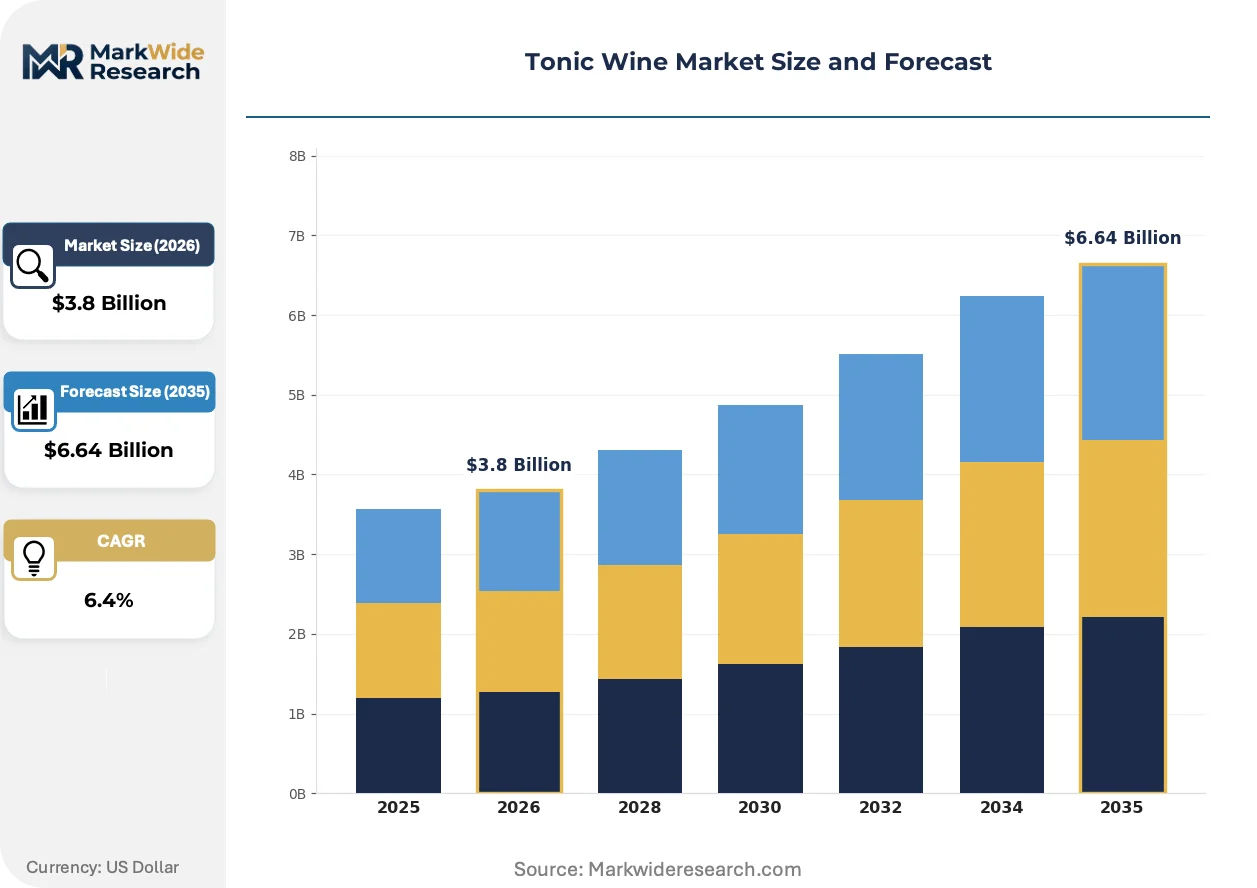
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Tonic Wine, White Tonic Wine, Herbal Tonic Wine, Sparkling Tonic Wine End User: Bars, Restaurants, Retail Outlets, Online Consumers Packaging Type: Bottles, Cans, Tetra Packs, Kegs Distribution Channel: Direct Sales, Wholesalers, E-commerce, Supermarkets |
| Companies Covered | Wincarnis, Pernod Ricard, Buckfast Tonic Wine, E&J Gallo Winery, Campari Group, Magnum Tonic Wine, Diageo, Bacardi Limited, Sanatogen Tonic Wine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tonic Wine Market Emerging Trajectories
Formulation transparency and packaging material substitution are compressing traditional production timelines while elevating consumer scrutiny of ingredient provenance across Commonwealth markets.
Precision fermentation for botanical compound replication is decentralizing supply chain control away from traditional cinchona cultivation regions. Scottish blenders are adopting laboratory-derived quinine alternatives to hedge against Andean harvest volatility. This biotechnology is decentralizing raw material sourcing decisions toward controlled manufacturing environments.
REACH chemical safety dossier requirements are extending documentation obligations to flavoring compound suppliers throughout European value chains. ECHA substance evaluation timelines now determine product launch windows for reformulated variants. Herbal tonic wine categories face the steepest compliance cost escalation due to complex extract matrices requiring individual substance registration.
Wellness-oriented consumers are demanding unbundled ingredient disclosure that exceeds minimum labeling mandates. United Kingdom retailers are responding with shelf-edge QR codes linking to full botanical sourcing documentation. England's metropolitan supermarkets lead this transparency escalation, pressuring heritage brands to retrofit legacy packaging with digital traceability infrastructure.
Tonic Wine Market Segmentation
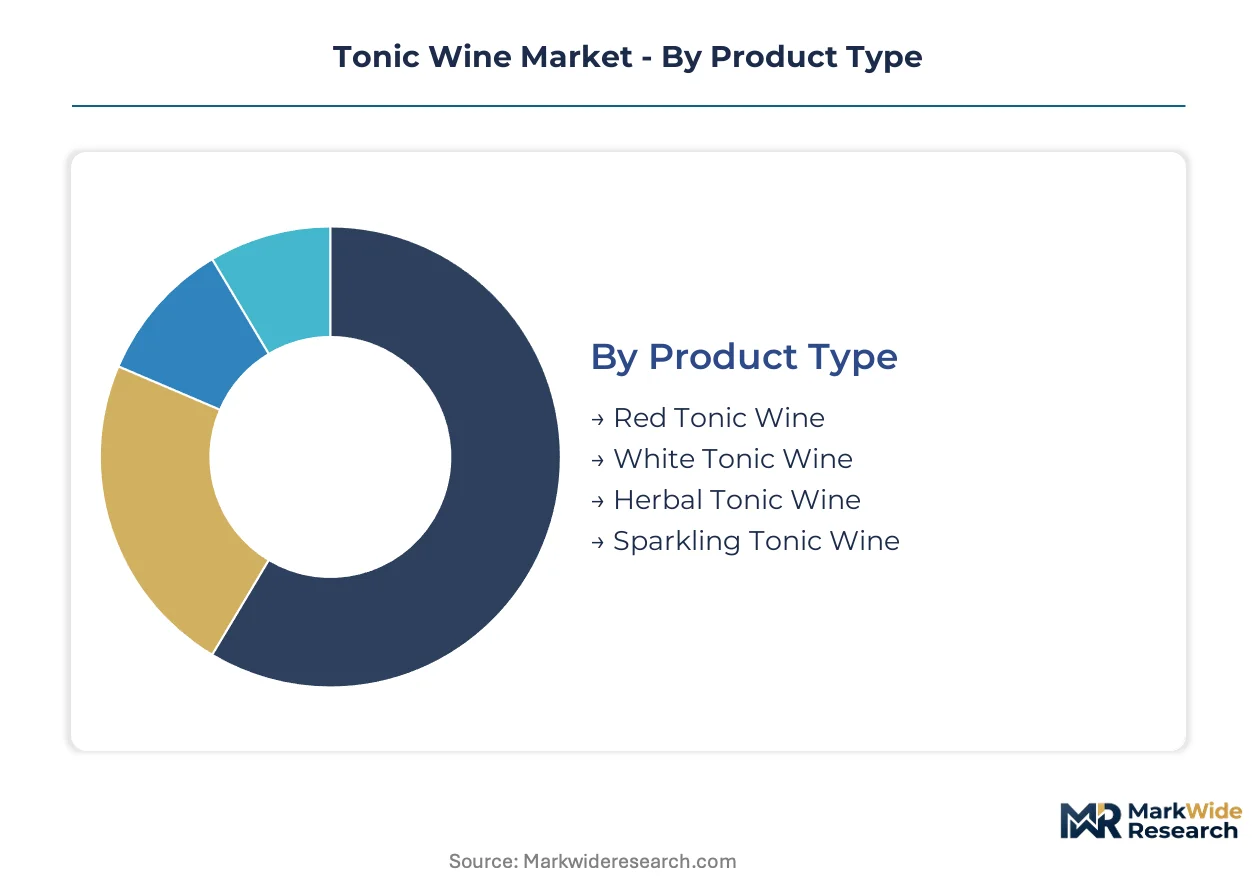
Tonic wine producers face divergent margin pressures across product formats and channel structures. Segmentation clarity reveals where formulation investments concentrate versus where packaging economics dominate purchasing decisions.
Product Type:
Supply concentration for herbal extracts and natural bittering agents is restructuring production economics across all four product categories.
- Herbal Tonic Wine:Formulated with complex botanical matrices including cinchona-derived quinine, gentian root, and vitamin fortification. Urban millennials in Manchester and Birmingham absorb premium pricing for wellness-positioned variants with transparent ingredient provenance. Scotland's on-trade channels favor this category for cocktail applications requiring layered bitterness profiles.
- Red Tonic Wine:Traditional fortified wine base with caramel coloring and synthetic or natural bittering agents. England's heritage retail outlets sustain volume through repeat purchase loyalty among established consumer cohorts. EFSA health claim restrictions constrain functional positioning despite vitamin fortification common in formulations.
- White Tonic Wine:Lighter body profile targeting summer consumption occasions and mixer applications.
- Sparkling Tonic Wine:Carbonated variant capturing occasion-based demand in celebratory settings.
Today's leader: Red Tonic Wine. Tomorrow's challenger: Herbal Tonic Wine.
End User:
Channel cost-to-serve economics are diverging sharply as on-trade recovery lags off-trade expansion.
- Retail Outlets:Supermarkets and specialist off-licences in England's metropolitan corridors absorb higher SKU density as heritage brands retrofit packaging with QR-enabled traceability infrastructure. Manchester and Birmingham networks remain underdeveloped relative to Scottish penetration, creating expansion headroom.
- Online Consumers:Subscription models bypass traditional wholesale markups while capturing urban millennial data for personalization. Direct-to-consumer platforms face lower REACH documentation burdens per unit than bulk wholesale shipments into EU markets.
- Bars:On-trade volume concentration in Scottish cities leverages monastic production credentials for repeat loyalty.
- Restaurants:Slower traffic recovery post-pandemic compresses listing fees and promotional investment returns.
Off-trade channels are expanding most quickly. On-trade retains pricing power where heritage positioning commands cocktail menu placement.
Packaging Type:
Material substitution timelines vary dramatically by format as F-Gas compliance deadlines approach.
- Bottles:Glass furnace investments face accelerated depreciation across European supply chains. Traditional bottling assets strand as producers abandon conventional glass for sustainable alternatives compliant with EU F-Gas Regulation.
- Cans:Aluminum formats gain share in convenience-oriented retail channels. Lightweight logistics reduce transport costs for online consumer shipments while meeting shelf-edge sustainability expectations in English supermarkets.
- Tetra Packs:Aseptic carton technology suits volume-oriented supermarket listings with extended shelf-life requirements.
- Kegs:Reusable stainless steel systems serve high-throughput bars in Scottish on-trade networks with established return logistics.
Glass bottling still dominates installed capacity. Aluminum cans are climbing the fastest as material innovation accelerates.
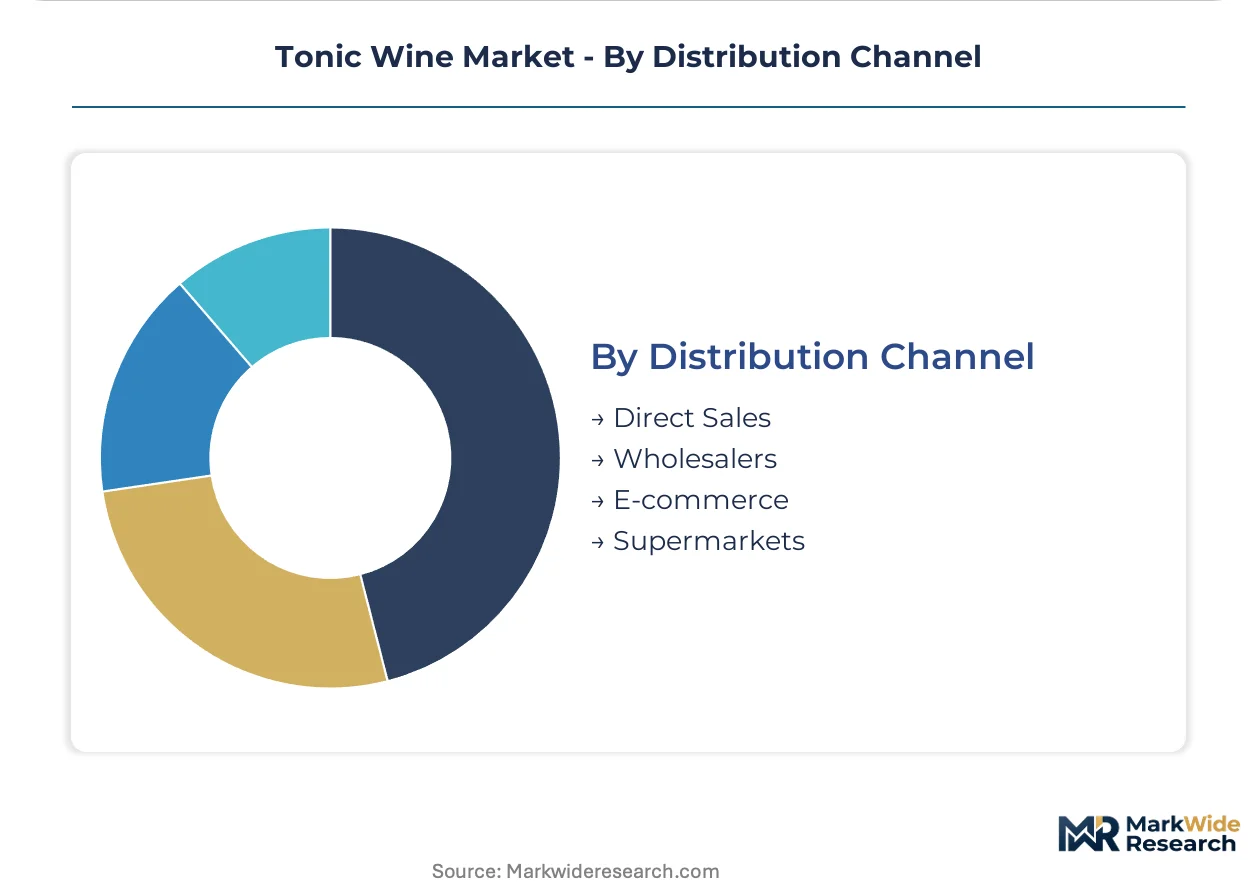
Distribution Channel:
Margin capture potential splits between control-oriented direct models and scale-oriented wholesale structures.
- E-commerce:Proprietary platforms enable subscription personalization while capturing first-party consumer data. REACH compliance costs per unit decline as direct shipments reduce batch complexity versus diversified wholesale portfolios.
- Supermarkets:England's metropolitan retailers demand shelf-edge QR codes linking to full botanical sourcing documentation. Transparency escalation pressures heritage brands to retrofit legacy packaging infrastructure.
- Direct Sales:Monastic producers in Scotland leverage ecclesiastical heritage for controlled on-trade distribution with limited wholesale dilution.
- Wholesalers:Traditional intermediaries retain volume concentration in rural English markets with fragmented retail landscapes.
Wholesale networks still move the most volume. E-commerce is gaining share fastest where urban millennial targeting justifies platform investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scotland's monastic production corridors anchor continental demand concentration for tonic wine, with ecclesiastical heritage credentialing sustaining premium positioning across Commonwealth distribution networks.
United Kingdom
Urban millennial premiumization in Manchester and Birmingham absorbs elevated price points for botanical-positioned variants. The Food Standards Agency governs additive approvals and health claim restrictions that constrain cross-border labeling strategies. England's metropolitan supermarkets deploy shelf-edge QR codes linking to full ingredient provenance documentation.
Germany
Specialist off-licence networks in Bavaria and North Rhine-Westphalia absorb heritage-brand SKU density for wellness-oriented consumers. ECHA substance evaluation timelines determine product launch windows for reformulated herbal extract portfolios. Hamburg's beverage distribution clusters retrofit legacy packaging with digital traceability infrastructure.
France
Île-de-France cocktail bars favor layered bitterness profiles for aperitif applications requiring botanical complexity. ANSM and CNIL frameworks govern additive transparency and consumer data handling in direct-to-consumer channels. Lyon and Marseille on-trade venues leverage monastic production credentials for repeat purchase loyalty.
Italy
Lombardy and Piedmont retail channels concentrate volume for traditional fortified wine bases with caramel coloring and natural bittering agents. EFSA health claim restrictions constrain functional positioning despite vitamin fortification common in formulations. Milan's metropolitan supermarkets pressure heritage brands toward unbundled ingredient disclosure.
Spain
Catalonia and Madrid convenience-oriented channels absorb aluminum format growth for lightweight logistics and sustainability positioning. REACH compliance on chemical constituents in flavoring compounds adds formulation costs for producers serving European markets. Barcelona's beverage innovation clusters accelerate material substitution away from traditional glass bottling.
Tonic Wine Market Vendor Landscape
Global majors compete with regional champions across heritage credentialing and distribution control dimensions, producing a tiered structure where monastic producers anchor ecclesiastical authenticity while spirits conglomerates leverage scaled manufacturing efficiency. The vendor base splits between ecclesiastical heritage specialists, diversified beverage conglomerates extending into fortified wine adjacencies, and regional tonic wine houses with century-old formulation libraries. Dominant competitive moves include portfolio diversification into herbal extract variants and geographic expansion through controlled distribution networks in underdeveloped English retail corridors.
Within the ecclesiastical heritage tier, Buckfast Tonic Wine and Wincarnis exemplify monastic production credentialing that secures repeat purchase loyalty in Scottish on-trade channels. Among diversified beverage conglomerates, Diageo occupies a position representing scaled spirits expertise applied to fortified wine manufacturing efficiency. These three anchors demonstrate how competitive positioning splits between authenticity-derived premium pricing and volume-oriented operational leverage across Commonwealth markets.
| Leading Market Players |
|---|
| Wincarnis |
| Pernod Ricard |
| Buckfast Tonic Wine |
| E&J Gallo Winery |
| Campari Group |
| Magnum Tonic Wine |
| Diageo |
| Bacardi Limited |
| Sanatogen Tonic Wine |
| Others |
Supply Flow & Price Mechanics
The EU's F-Gas Regulation gates qualified supply access and premium-tier pricing power, forcing producers to absorb sustainable packaging transition costs or forfeit shelf placement in England's metropolitan supermarkets. Buyers with verified botanical traceability infrastructure command price premiums while legacy bottlers face margin compression from stranded glass furnace assets.
Pricing Analysis
Input-cost pass-through from cinchona bark and herbal extract procurement anchors pricing dynamics across tonic wine portfolios. Three-tier pricing structure across heritage-premium, standard-fortified, and economy-mixer levels separates monastic-credentialed variants from commodity-positioned alternatives. Pricing pressure intensifies in standard tiers as synthetic additive substitution costs converge with natural bittering agent premiums. Urban millennials in Manchester and Birmingham exhibit lowest price sensitivity for wellness-positioned herbal variants, while rural English retail channels resist premium absorption.
Supply Chain Analysis
Dual-sourcing requirements for quinine compounds now mandate Andean cultivation zone qualification alongside laboratory-derived alternatives. Supply concentration in Peru, Ecuador, and controlled fermentation facilities in Scotland creates geographic dependency for botanical inputs. Cinchona bark harvest volatility and REACH compliance documentation burdens constitute primary structural risks. Distribution runs through monastic-controlled networks in Scottish on-trade channels and supermarket wholesale structures in England's metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tonic wine margins expand through premium-tier absorption of herbal extract cost escalation, with wellness-positioned variants capturing urban millennial willingness to pay for transparent botanical provenance.
For Market Incumbents: Lock in ecclesiastical heritage credentialing through controlled distribution networks before laboratory-derived quinine alternatives commoditize botanical authenticity. Invest in QR-enabled traceability infrastructure to defend shelf placement against supermarket transparency mandates. Vertical integration into precision fermentation capabilities hedges against Andean supply disruption. For New Entrants and Emerging Players: Underserved urban millennials in Birmingham and Manchester retail corridors present white-space capture opportunity through subscription-based direct-to-consumer platforms. Specialist off-licence networks in these metropolitan areas remain underpenetrated relative to Scottish benchmarks. E-commerce fulfillment with reduced REACH documentation burdens per unit offers lower regulatory cost-to-serve than wholesale market entry. For Investors and Strategic Acquirers: Roll-up economics work for regional tonic wine houses with century-old formulation libraries because heritage brand consolidation captures repeat purchase loyalty in fragmented Commonwealth distribution. Five-to-ten year viability hinges on herbal extract standardization expertise acquisition. Watch EFSA health claim pathway approvals as inflection signal for vitamin-fortified variant premiumization potential.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Brand Acquisition | Consolidation of monastic production credentials secures Scottish on-trade channel control against spirits conglomerate encroachment. |
| Precision Fermentation Integration | Laboratory-derived quinine alternatives reduce Andean supply dependency while meeting ECHA substance evaluation timelines. |
| Direct-to-Consumer Platform Launch | Subscription models capture urban millennial data in Manchester and Birmingham while bypassing wholesale margin dilution. |
| Sustainable Packaging Transition | Aluminum and aseptic carton formats satisfy EU F-Gas Regulation compliance for England's supermarket shelf-edge requirements. |
| EFSA Health Claim Navigation | Botanical functional benefit documentation unlocks approved positioning statements for vitamin-fortified premium tier expansion. |
Methodological Framework
Bottom-up retail channel modeling reconciled against top-down production volume tracking forms the analytical core of this study. Primary interviews with brand managers at heritage tonic wine houses, category buyers at English supermarket chains, and procurement leads at herbal extract suppliers combined with secondary validation from customs records, Food Standards Agency additive approval filings, and ECHA substance registration databases. Triangulation across stakeholder inputs and documentary sources ensures segment-level precision.
Historical trendline analysis of fortified wine shipment volumes and price realization patterns informed projection framework construction across the analysis window. Segmentation dimensions modeled include product type, packaging material, distribution channel structure, and metropolitan versus rural retail geography. CAGRs derive from regression-adjusted growth rate synthesis incorporating herbal extract cost trajectory assumptions and regulatory compliance cost escalation curves.
Underlying measurement precision varies by segment; retail outlet and online consumer channels carry tighter precision than fragmented on-trade bar and restaurant categories. Forecasts reflect documented assumptions regarding REACH compliance maturation and F-Gas Regulation implementation timelines. Deviation in Andean cinchona harvest yields or EFSA health claim pathway rulings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
Irish Whiskey Market
Alcoholic Beverages
F-Style Jugs Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Global Red Wine Market
Alcoholic Beverages
Canada Wine Coolers Market
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Canned Alcoholic Beverages Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
South Africa Beverages Market
Alcoholic Beverages
Lager Market
Alcoholic Beverages
Asia Pacific Beer Market
Alcoholic Beverages
Alcoholic Ice Cream Market