
 N-Hexyl Alcohol Market | 2026-2036
N-Hexyl Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
N-Hexyl Alcohol Market Analysis
Aftermarket solvent recovery services is fragmenting as specialty chemical houses build in-house purification loops. BASF SE leverages backward integration into C6 alcohol feedstocks to secure margin pools that previously flowed to third-party refiners. Sasol anchors its position through Fischer-Tropsch-derived hexanol streams, while Eastman Chemical Company competes on acetaldehyde condensation chemistry with tight purity controls.
N-hexyl alcohol is a six-carbon primary aliphatic alcohol with molecular formula C6H14O, typically produced via ethylene oligomerization or natural fatty alcohol reduction, serving as a critical intermediate for ester synthesis and surfactant manufacturing. Industrial grade material dominates volume throughput in solvent and additive applications where specification tolerance is widest. Pharmaceutical grade commands premium positioning due to impurity thresholds below 0.1 percent, while cosmetic grade growth tracks clean-label emollient demand across European and Asian formulation labs.
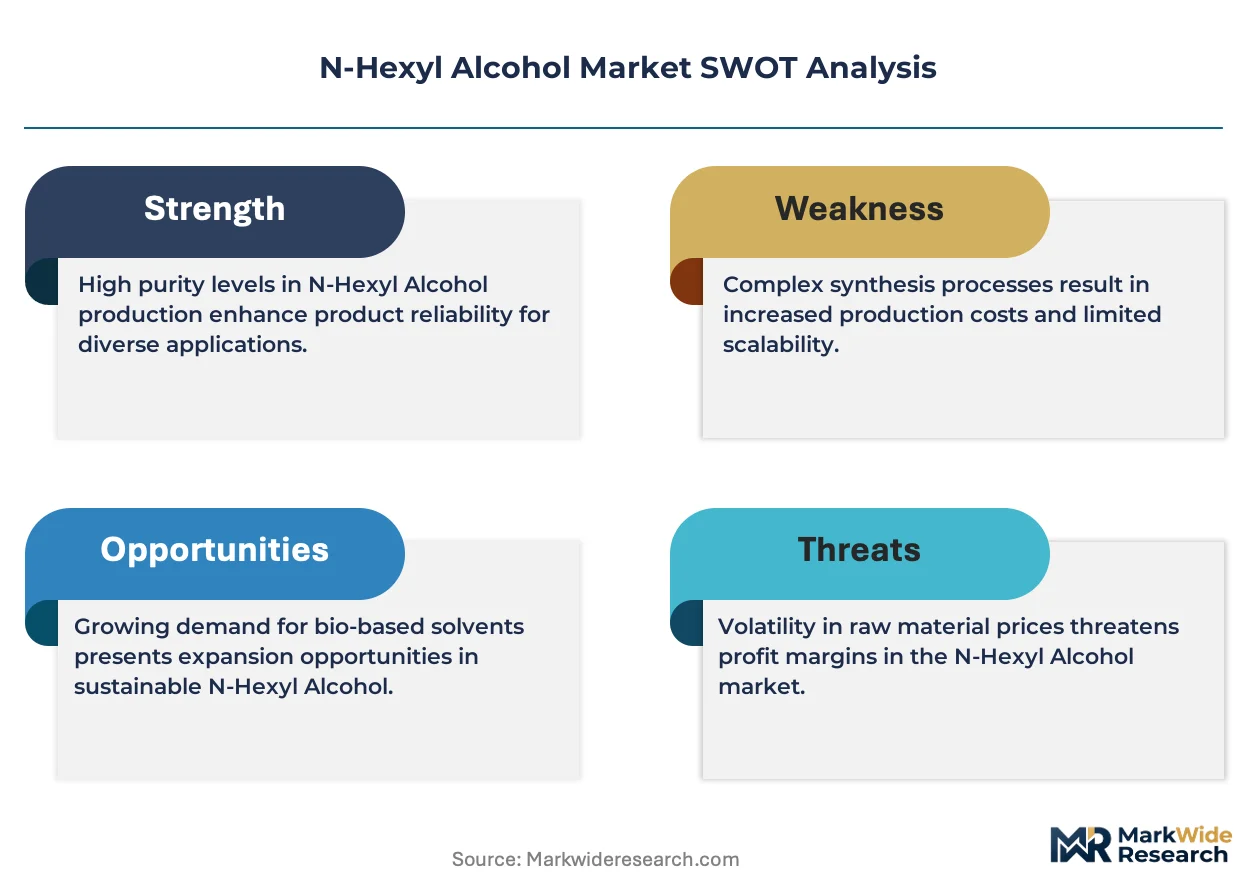
EPA oversight under the Toxic Substances Control Act governs manufacturing emissions and new chemical notifications for n-hexyl alcohol derivatives in United States commerce. REACH registration requirements in Europe mandate full toxicological dossiers for C6 alcohol imports above one tonne annually, tightening market access for non-compliant suppliers. ECHA substance evaluation protocols continue pushing substitution assessments toward lower-toxicity alternatives, compelling producers to document sustainable sourcing credentials. Stakeholders must weigh bio-based certification investments against fossil route cost structures before capacity commitments harden.
Market Dynamics
Specialty surfactant manufacturers in cosmetics and personal care are pulling C6 alcohol volumes away from commodity solvent applications, compressing margin pools for undifferentiated producers while rewarding bio-based certification investments.
Growth Catalysts
- EU Green Deal compliance:REACH registration mandates for C6 alcohol imports above one tonne annually favor bio-based feedstock routes, accelerating capital allocation toward renewable ethylene oligomerization pathways.
- Cosmetic formulation hubs:Clean-label emollient demand across European and Asian formulation labs is expanding cosmetic-grade offtake as brands reformulate away from petrochemical-derived emollients.
- Fischer-Tropsch synthesis:Gas-to-liquids technology is unlocking C6 alcohol streams from stranded natural gas assets, diversifying supply geography beyond traditional ethylene-cracker corridors.
Market Restraints
- Crude oil derivative pricing:Naphtha and ethylene cost volatility transmits directly to fossil-route hexanol production economics, eroding margin predictability for non-integrated producers.
- Supply concentration risk:Germany, China, and the United States concentrate formulation-grade output, creating single-point-of-failure exposure for pharmaceutical and cosmetic specification material.
- Substitution pressure:C8 and C10 fatty alcohols are displacing C6 variants in certain surfactant applications where longer carbon chains deliver equivalent emulsification performance.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO compliance requirements for excipient-grade alcohols are tightening, creating first-mover advantage for producers achieving pharmaceutical-grade certification ahead of domestic capacity expansion.
- Acetaldehyde condensation chemistry:Tight purity controls via this alternative synthesis route are enabling premium positioning in fragrance and flavor intermediate markets where impurity thresholds sit below 0.1 percent.
- Direct-to-formulator distribution:Specialty chemical houses are building in-house purification loops, fragmenting aftermarket solvent recovery services and opening channel access for certified bio-based suppliers.
Industry Challenges
- REACH toxicological dossier compilation:Full substance evaluation protocols require extensive mammalian toxicity data, stretching compliance timelines to 18-24 months for new market entrants.
- Legacy esterification asset retrofit:Existing solvent-grade production lines require capital-intensive purification upgrades to meet pharmaceutical and cosmetic specification thresholds.
- Cross-border certification reciprocity:Divergent EPA TSCA and ECHA substance evaluation criteria create redundant testing burdens for suppliers serving both United States and European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | N-Hexyl Alcohol Market |
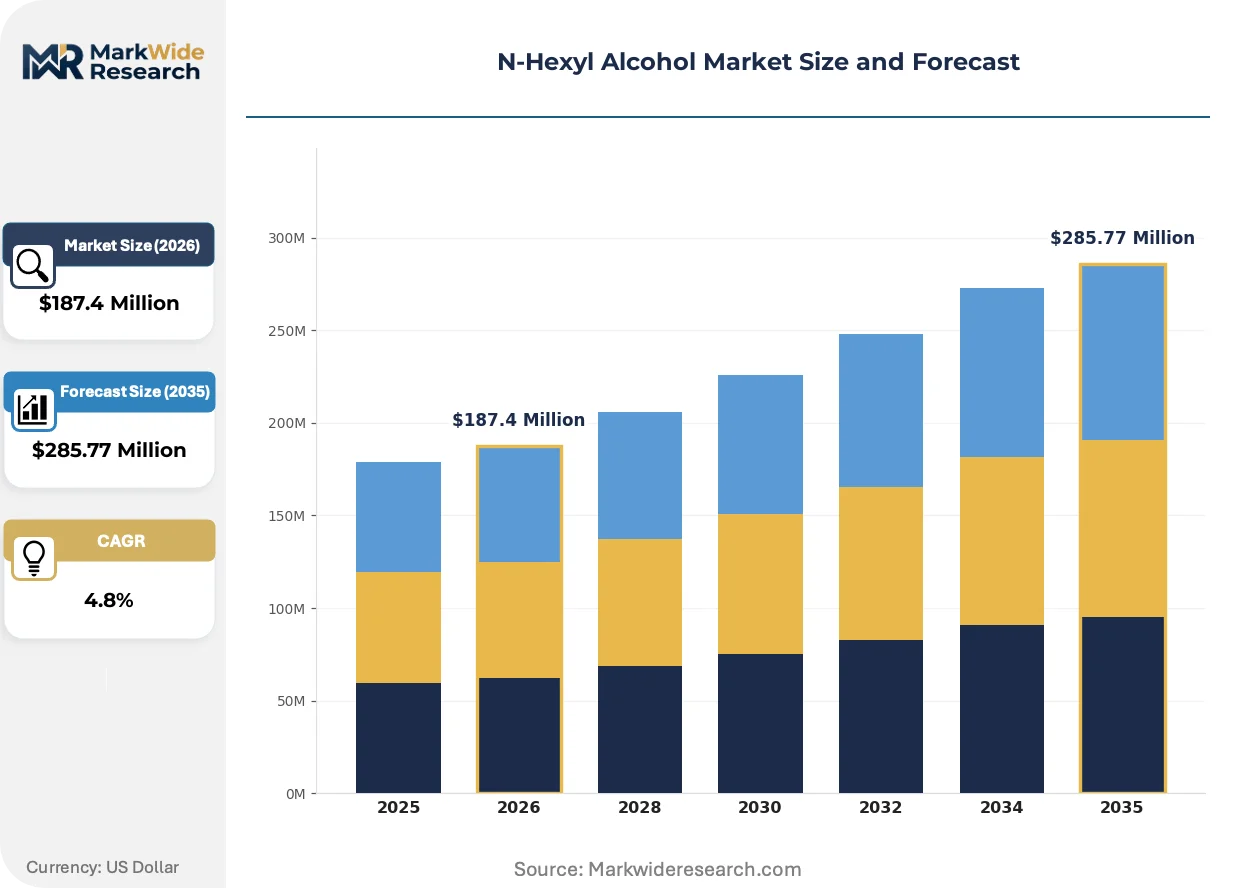
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Cosmetic Grade, Pharmaceutical Grade, Food Grade Application: Solvent, Surfactant, Additive, Intermediate End User: Cosmetics, Pharmaceuticals, Food & Beverage, Paints Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | BASF SE, Sasol, Eastman Chemical Company, Merck KGaA, Oxea GmbH, Huntsman Corporation, Mitsubishi Chemical Corporation, Kao Corporation, Godavari Biorefineries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
N-Hexyl Alcohol Market Emerging Trajectories
Process intensification and regulatory chemistry are compressing the traditional separation between commodity and specialty grades, forcing producers to choose between certification investments or volume-driven cost positions.
Enzymatic reduction of natural fatty acid feedstocks is hybridizing bio-based and petrochemical supply chains, allowing batch producers to toggle between routes based on feedstock arbitrage. Cosmetic formulators in France and Germany are qualifying these dual-source materials at accelerated timelines. The structural consequence is collapsing premium spreads between certified bio-based and mass-balance-attributed material.
REACH authorization sunset clauses for Substances of Very High Concern are tightening impurity specifications for C6 alcohol derivatives used in consumer-facing applications. Industrial consequence includes mandatory supply chain documentation extending back to cracker feedstock origin. Personal care and household cleaning segments are responding by consolidating supplier bases around vertically integrated producers with captive bio-based certification.
Specification-driven procurement is fragmenting traditional distributor relationships as end-users demand direct access to batch-level carbon intensity data and toxicological dossiers. Specialty surfactant houses are replacing spot-market purchasing with multi-year offtake agreements tied to certification maintenance. This behavioral shift is most visible in German and Dutch formulation clusters where ECHA compliance audits have become standard vendor qualification criteria.
N-Hexyl Alcohol Market Segmentation
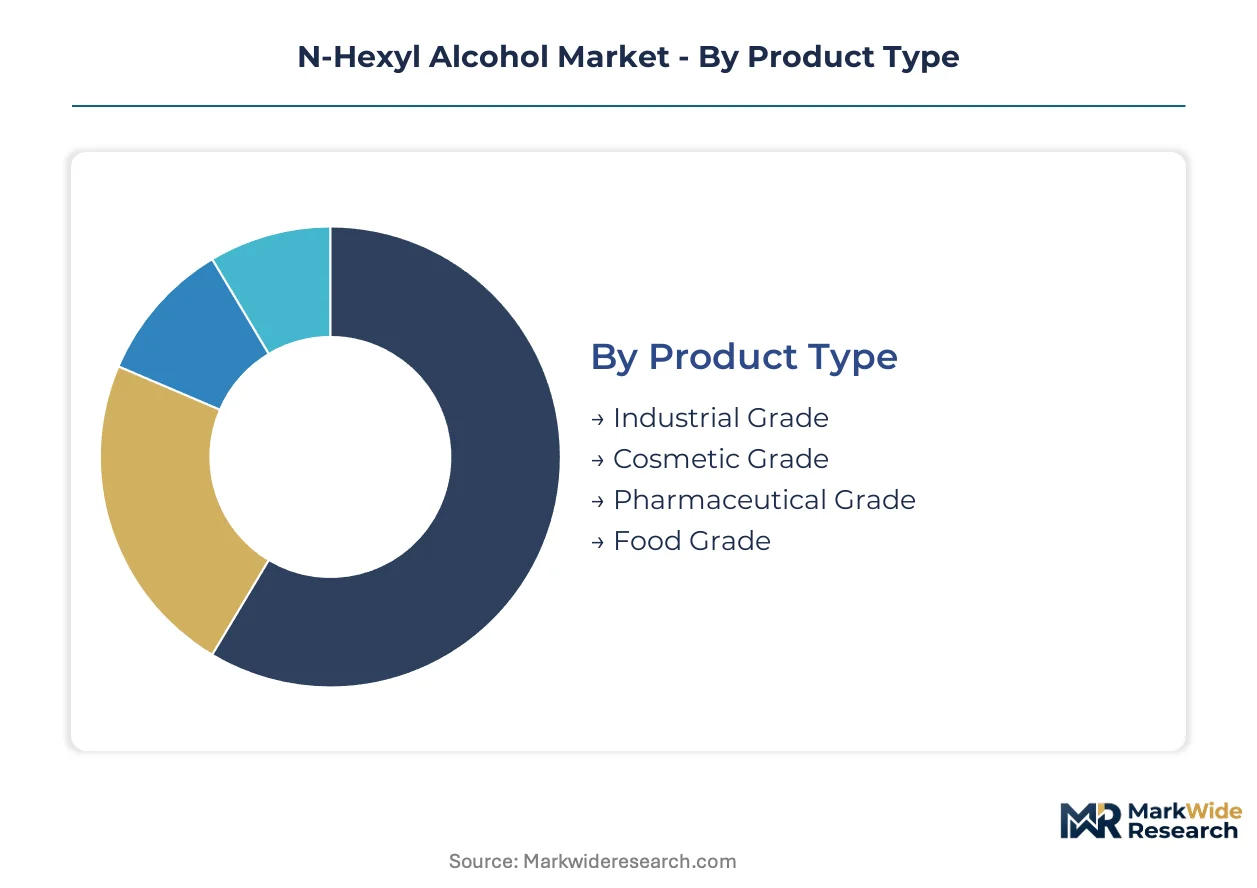
Grade differentiation determines purification investment intensity and regulatory compliance burden across n-hexyl alcohol supply chains. Specification thresholds below 0.1 percent impurity separate pharmaceutical and cosmetic grades from industrial material, fragmenting procurement relationships and margin structures.
Product Type:
After-sales technical support intensity escalates dramatically from industrial to pharmaceutical grades, with batch-level documentation and toxicological dossier maintenance becoming mandatory service components.
- Industrial Grade:Widest specification tolerance enables volume throughput in solvent and additive applications where cost minimization dominates procurement criteria. Demand concentrates in German and Chinese manufacturing corridors for paints and coatings, though margin compression from ethylene cost volatility erodes producer returns.
- Cosmetic Grade:Clean-label emollient specifications require impurity thresholds stricter than industrial material, typically below 0.5 percent. European formulation labs in France and Germany are accelerating qualification timelines for bio-certified cosmetic-grade streams as brands reformulate away from petrochemical-derived inputs.
- Pharmaceutical Grade:Sub-0.1 percent impurity mandates with full supply chain documentation back to cracker feedstock origin.
- Food Grade:Flavor and fragrance intermediate applications with FEMA GRAS and EU 1333/2008 compliance requirements.
Industrial grade holds the largest share; momentum sits with cosmetic grade.
Application:
Margin architecture varies sharply by application, with surfactant and intermediate uses commanding specification premiums that solvent applications cannot support.
- Surfactant:Specialty surfactant manufacturers are pulling C6 alcohol volumes away from commodity solvent applications, compressing margin pools for undifferentiated producers while rewarding bio-based certification investments. Clean-label emollient demand across Asian formulation labs is expanding cosmetic-grade offtake fastest.
- Intermediate:Ester synthesis for fragrance and flavor compounds requires tight purity controls, enabling premium positioning where impurity thresholds sit below 0.1 percent. Acetaldehyde condensation chemistry is gaining share in this specification-sensitive segment.
- Solvent:Aftermarket solvent recovery services fragmenting as specialty chemical houses build in-house purification loops.
- Additive:Plasticizer and lubricant formulations with widest specification tolerance.
Intermediate applications generate the steepest premium spreads; surfactant demand is climbing the fastest.
End User:
Regulatory chemistry intensity escalates from paints through food and beverage to pharmaceuticals, with compliance timelines stretching to 18-24 months for new market entrants in the most regulated segments.
- Pharmaceuticals:Excipient-grade requirements under FDA and EMA oversight mandate pharmaceutical-grade material with full toxicological dossiers. CDSCO compliance requirements in India are tightening, creating first-mover advantage for producers achieving certification ahead of domestic capacity expansion.
- Cosmetics:REACH authorization sunset clauses for Substances of Very High Concern are tightening impurity specifications, compelling consolidation around vertically integrated producers with captive bio-based certification.
- Food & Beverage:Flavor intermediate applications with FEMA GRAS and EU food additive compliance.
- Paints:Industrial-grade solvent consumption with widest specification tolerance and highest volume throughput.
Cosmetics holds the largest share; pharmaceuticals is gaining share fastest.
Distribution Channel:
Channel economics shift dramatically as end-users demand direct access to batch-level carbon intensity data and toxicological dossiers, fragmenting traditional distributor relationships.
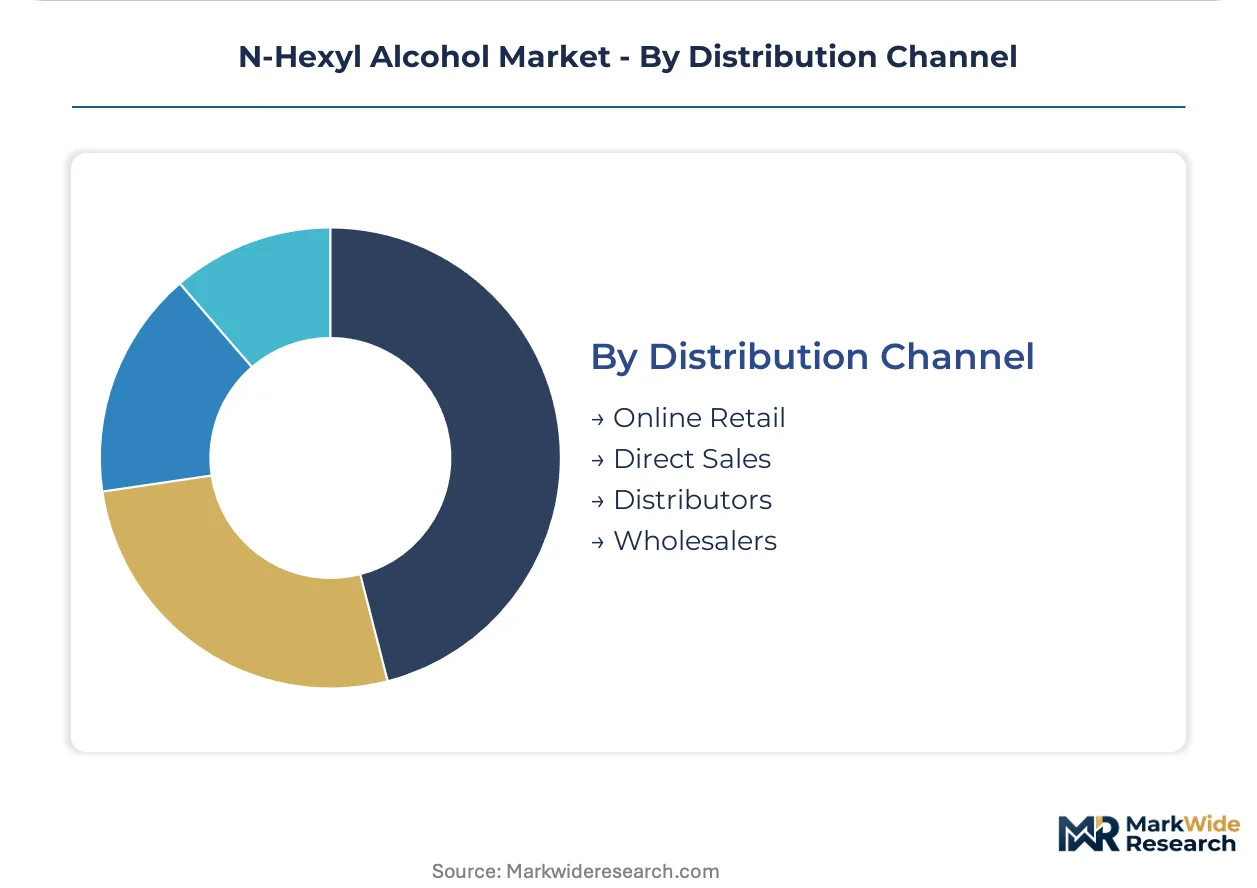
- Direct Sales:Specialty surfactant houses are replacing spot-market purchasing with multi-year offtake agreements tied to certification maintenance. This behavioral shift is most visible in German and Dutch formulation clusters where ECHA compliance audits have become standard vendor qualification criteria.
- Distributors:Traditional channel facing disintermediation pressure as specification-driven procurement demands supply chain transparency that layered distribution cannot provide.
- Online Retail:Industrial-grade material for small-batch purchasers with immediate delivery requirements.
- Wholesalers:Volume aggregation for commodity-grade applications with minimal specification requirements.
Direct sales holds the largest share; momentum sits with online retail for industrial-grade spot purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes n-hexyl alcohol predominantly for cosmetic-grade surfactant synthesis, whereas China and the United States allocate larger shares to industrial solvent and pharmaceutical intermediate applications. This consumption-mix differential shapes regulatory investment priorities and certification requirements across major demand centers.
United States
Pharmaceutical excipient demand from New Jersey and Massachusetts formulation clusters drives steady offtake for high-purity grades. EPA oversight under the Toxic Substances Control Act governs manufacturing emissions and new chemical notifications for derivatives. The Gulf Coast petrochemical corridor anchors fossil-route production capacity serving domestic solvent applications.
Germany
Cosmetic-grade consumption dominates as French and German formulation labs accelerate clean-label emollient qualification timelines. REACH registration requirements mandate full toxicological dossiers for C6 alcohol imports above one tonne annually. The North Rhine-Westphalia chemical cluster concentrates specialty surfactant manufacturing with integrated bio-based certification capabilities.
China
Industrial-grade solvent applications absorb the largest volume share for paints and coatings manufacturing. MIIT and SAMR oversight of chemical production standards tightens impurity specifications for export-oriented material. The Yangtze River Delta petrochemical corridor anchors ethylene-oligomerization capacity serving domestic and Asia-Pacific formulation demand.
India
Pharmaceutical manufacturing expansion in Maharashtra and Gujarat creates tightening demand for excipient-grade alcohols. CDSCO compliance requirements for excipient-grade materials are tightening ahead of domestic capacity expansion. Mumbai-Pune chemical belt formulation houses are consolidating supplier bases around certified producers with documented supply chain transparency.
Japan
Specialty surfactant and fragrance intermediate applications command premium positioning for high-purity material. METI oversight of chemical substance management aligns with international harmonization initiatives for toxicological data. The Kansai industrial corridor around Osaka maintains concentrated demand for specification-grade C6 alcohol derivatives.
N-Hexyl Alcohol Market Vendor Landscape
Capability concentration sits with integrated petrochemical majors possessing captive feedstock access; scale advantage sits with diversified chemical houses serving multiple alcohol chain lengths. The market structures around three tiers: backward-integrated oil-to-chemicals operators, Fischer-Tropsch synthesis specialists, and acetaldehyde condensation chemistry purists. Strategic moves center on bio-based certification investments and in-house purification loop construction to capture margins previously flowing to aftermarket solvent recovery services.
Among European integrated chemical majors, BASF SE and Sasol occupy positions representing the feedstock-control archetype, while Eastman Chemical Company anchors the alternative-synthesis tier emphasizing purity-driven positioning. BASF SE exemplifies backward integration into C6 alcohol feedstocks securing margin pools from third-party refiners. Sasol represents Fischer-Tropsch-derived hexanol production from stranded natural gas assets. Eastman Chemical Company sits within the acetaldehyde condensation chemistry segment competing on tight purity controls for specification-sensitive applications.
| Leading Market Players |
|---|
| BASF SE |
| Sasol |
| Eastman Chemical Company |
| Merck KGaA |
| Oxea GmbH |
| Huntsman Corporation |
| Mitsubishi Chemical Corporation |
| Kao Corporation |
| Godavari Biorefineries |
| Others |
Supply Flow & Price Mechanics
German ethylene-oligomerization capacity and Fischer-Tropsch streams from South African gas-to-liquids assets concentrate upstream control, directing margin capture toward cosmetic-grade purification and pharmaceutical-grade certification tiers rather than commodity solvent volumes.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical and cosmetic-grade procurement, with multi-year contracts tied to REACH dossier maintenance and batch-level carbon intensity documentation replacing spot-market purchasing in German and Dutch formulation clusters. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades tracks impurity thresholds and certification burden, with sub-0.1 percent material commanding steepest premiums. Cost compression in industrial-grade solvent tiers intensifies as ethylene cost volatility transmits directly from naphtha markets, eroding returns for non-integrated producers. Specialty surfactant houses show least price sensitivity due to clean-label reformulation mandates, while paints and coatings buyers prioritize cost minimization above specification.
Supply Chain Analysis
BASF SE, Sasol, and Eastman Chemical Company anchor global production capacity through distinct chemistries: ethylene oligomerization, Fischer-Tropsch synthesis, and acetaldehyde condensation respectively. Feedstock dependencies center on ethylene from naphtha crackers, stranded natural gas for gas-to-liquids conversion, and acetaldehyde from ethanol oxidation or ethylene oxide hydration. Single-source vulnerability concentrates in pharmaceutical-grade certification, where CDSCO compliance timelines and REACH toxicological dossier requirements create 18-24 month qualification barriers. Distribution runs through direct sales channels for specification-grade material, with traditional distributors retaining relevance only for industrial-grade spot volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory chemistry fragmentation across REACH, EPA TSCA, and CDSCO jurisdictions creates niche positioning opportunities for producers mastering jurisdiction-specific certification rather than competing on undifferentiated volume.
For Market Incumbents: Entrench certification moats by accelerating bio-based feedstock investments ahead of EU Green Deal sunset clauses for petrochemical-derived inputs. Construct in-house purification loops to capture margins previously flowing to aftermarket solvent recovery services. Prioritize backward integration into C6 alcohol feedstocks to defend against ethylene cost volatility eroding commodity-grade returns.
For New Entrants and Emerging Players: Build out pharmaceutical-grade capacity targeting Indian CDSCO compliance requirements ahead of domestic capacity expansion in Maharashtra and Gujarat. Exploit white space in enzymatic reduction of natural fatty acid feedstocks, where dual-source batch production enables feedstock arbitrage between bio-based and petrochemical routes. Lead with direct-to-formulator distribution emphasizing batch-level carbon intensity data and toxicological dossier transparency.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed Fischer-Tropsch specialists lacking cosmetic-grade certification capabilities and facing stranded natural gas feedstock cost pressures. Five-to-ten year viability hinges on successful bio-based transition rather than fossil-route cost position defense. Watch for REACH authorization sunset clause acceleration as the signal indicating certification-premium expansion versus commodity-grade margin collapse.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C6 Feedstocks | BASF SE's captive ethylene-oligomerization capacity secures margin pools from third-party refiners. |
| Bio-Based Certification Investment | EU Green Deal compliance mandates favor renewable ethylene pathways over fossil routes. |
| In-House Purification Loop Construction | Specialty chemical houses fragment aftermarket solvent recovery by internalizing purification. |
| Pharmaceutical-Grade Certification | CDSCO tightening in India creates first-mover advantage ahead of domestic capacity expansion. |
| Direct-to-Formulator Distribution | ECHA compliance audits in German clusters demand supply chain transparency that layered distribution cannot provide. |
Methodological Framework
A standing panel of specialty surfactant procurement directors, pharmaceutical excipient qualification managers, cosmetic formulation chemists, and Fischer-Tropsch plant engineers provided ongoing calibration across primary interview rounds. Secondary validation drew from ECHA substance evaluation protocols, EPA TSCA new chemical notifications, CDSCO excipient guidelines, customs trade data for C6 alcohol flows, and SEC filings from integrated chemical majors. Bottom-up grade-by-grade volume estimates triangulated against top-down ethylene-oligomerization capacity assessments.
Scenario-bracketing around regulatory acceleration versus compliance delay framed projections across the analysis window. Segmentation dimensions modeled include grade tier (pharmaceutical, cosmetic, industrial, food), application (surfactant, intermediate, solvent, additive), end-use industry, and regional production hub. CAGRs derived from elasticity-adjusted demand curves incorporating substitution pressure from C8 and C10 fatty alcohols and feedstock cost pass-through coefficients for ethylene and natural gas.
Sensitivities concentrate around REACH authorization timeline acceleration, CDSCO compliance requirement tightening, and Fischer-Tropsch feedstock cost volatility from stranded natural gas pricing. Quarterly review of ECHA substance evaluation protocol updates, CDSCO draft guideline releases, and ethylene-naphtha spread movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
High-End Chinese Spirits Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Alcoholic Beverages Market
Alcoholic Beverages
Beer Brewing Machine Market
Alcoholic Beverages
Kegs Market
Alcoholic Beverages
American Oak Barrels Market
Alcoholic Beverages
Industrial Alcohol Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Instant Wine Chillers and Refreshers Market
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
Still Wine Market