
 Wine Fermentation Equipment Market | 2026-2036
Wine Fermentation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Fermentation Equipment Market Analytics
Precision fermentation monitoring is rewriting how wineries manage cap management and yeast health during primary fermentation. Bucher Vaslin leverages decades of French viticulture engineering to dominate traditional press and tank configurations. Krones AG anchors its position through automated filling and fermentation lines that integrate with downstream packaging. Paul Mueller Company specializes in custom stainless steel vessels that sustain temperature control across variable batch sizes.
Wine fermentation equipment encompasses vessels, presses, pumps, and thermal management systems engineered to convert grape must into wine through controlled yeast metabolism, typically operating at temperatures between 12°C and 30°C depending on varietal and style objectives. Stainless steel fermentation tanks command the largest installed base due to their sanitization advantages and compatibility with glycol-jacketed cooling systems, while automated technology segments are gaining traction as labor costs climb in traditional winegrowing regions. Hybrid systems that blend manual punch-down capability with sensor-driven temperature logging represent a growing margin pool for mid-size winery capital budgets.
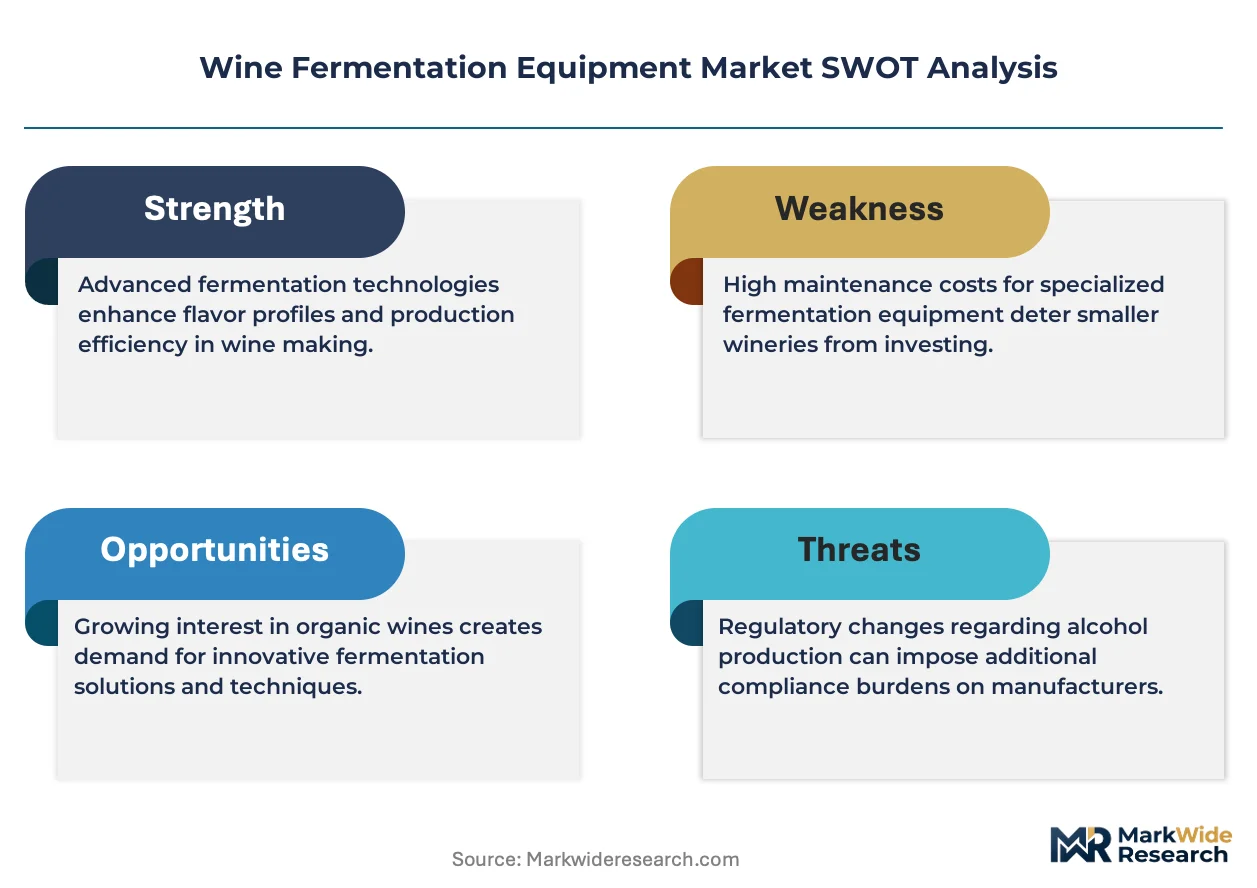
FDA food contact surface regulations and EU Machinery Directive safety standards shape material selection and equipment design for any system entering North American or European commercial wineries. California's CalRecycle water efficiency requirements and France's environmental compliance frameworks for agricultural processing further constrain equipment specifications in two of the world's largest premium wine production zones. Stakeholders must weigh total cost of ownership against retrofit compatibility when evaluating capital commitments across multi-decade winery infrastructure cycles.
Market Dynamics
Automated fermentation monitoring systems are compressing batch-to-batch variation windows while EPA water reuse mandates and EU industrial emissions frameworks force capital reinvestment cycles across legacy winery infrastructure.
Growth Catalysts
- CalRecycle Water Efficiency Mandates:California wineries face binding water reuse thresholds that accelerate stainless steel tank replacement schedules and drive demand for closed-loop cooling systems.
- Sensor-Driven Cap Management:Optical turbidity probes and dissolved oxygen meters enable real-time pomace submersion control, reducing labor intensity in premium red wine programs.
- Bordeaux Cluster Expansion:Right-bank satellite appellations are installing temperature-jacketed tanks to extend harvest processing capacity without expanding footprint.
Market Restraints
- Stainless Steel Price Volatility:Nickel and molybdenum input cost swings compress margin visibility for tank fabricators on fixed-price contracts.
- Specialized Welding Labor Scarcity:ASME-certified pressure vessel welders concentrate in Germany and northern Italy, creating installation bottlenecks for non-European projects.
- Glycol Refrigerant Phase-Downs:EU F-Gas Regulation restrictions on hydrofluorocarbon coolants force costly chiller system redesigns before end-of-life.
Strategic Opportunities
- English Sparkling Wine Corridor:Kent and Sussex plantings are scaling from experimental to commercial volumes, creating first-mover equipment installation contracts.
- Hybrid Fermentation Vessels:Concretes lined with epoxy-coated steel combine thermal mass stability with sanitization compliance, opening mid-tier price positioning.
- USDA BioPreferred Procurement:Federal winery grant programs prioritize equipment with recycled content thresholds, favoring domestic tank fabricators with circular material streams.
Industry Challenges
- Enology-Automation Skills Gap:Wineries struggle to hire staff who combine yeast microbiology expertise with PLC programming and data analytics.
- Legacy Oak Integration:Centuries-old barrel programs resist sensor retrofit compatibility, forcing parallel inventory systems and duplicate quality protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Fermentation Equipment Market |
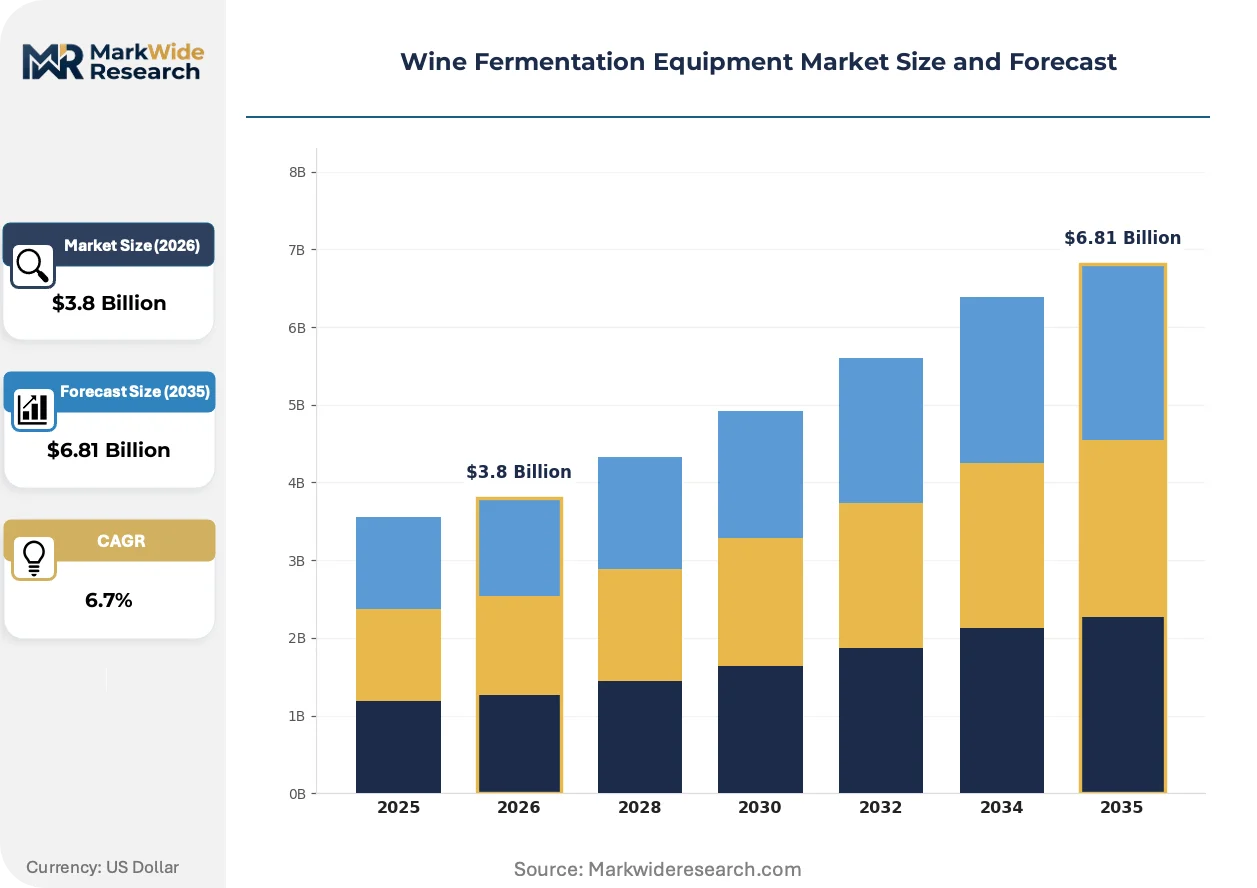
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermentation Tanks, Presses, Pumps, Temperature Control Units Material: Stainless Steel, Glass, Wood, Plastic End User: Wineries, Home Brewers, Research Institutions, Beverage Manufacturers Technology: Traditional, Automated, Hybrid, Mobile |
| Companies Covered | Criveller Group, G.W. Kent Inc., Agrovin, Bucher Vaslin, Pellenc Group, Krones AG, Paul Mueller Company, Albrigi Tecnologie S.r.l., Zambelli Enotech S.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Fermentation Equipment Market Evolving Landscape
Distributed fermentation telemetry is collapsing the information lag between cellar operations and executive decision-making, compressing response windows from days to hours across multi-site winery groups.
Wireless mesh sensor networks embedded in tank jackets now transmit temperature gradients at 30-second intervals to cloud-based fermentation dashboards. Large-scale Napa Valley and Mendoza operations are deploying these systems across 500+ tank installations within single harvest seasons. Manual thermocouple logging is rendering obsolete as labor arbitrage fails to offset batch consistency penalties.
EU Machinery Directive 2006/42/EC amendments now mandate functional safety ratings for automated pump-over systems with human-machine interface exposure. Tank manufacturers must certify emergency stop circuitry and interlocking guard designs through notified bodies before CE marking. Italian and Spanish equipment suppliers are absorbing six-month certification delays into project timelines, compressing their competitive position against pre-certified German competitors.
Winery procurement departments are consolidating vendor relationships from equipment-specific contracts to multi-year fermentation suite partnerships. Mid-size operations in Australia's Barossa Valley and Germany's Pfalz are shifting from transactional tank purchases to subscription-based monitoring and maintenance agreements. This bundling concentrates specification influence with integrators who control downstream service revenue streams.
Wine Fermentation Equipment Market Segmentation
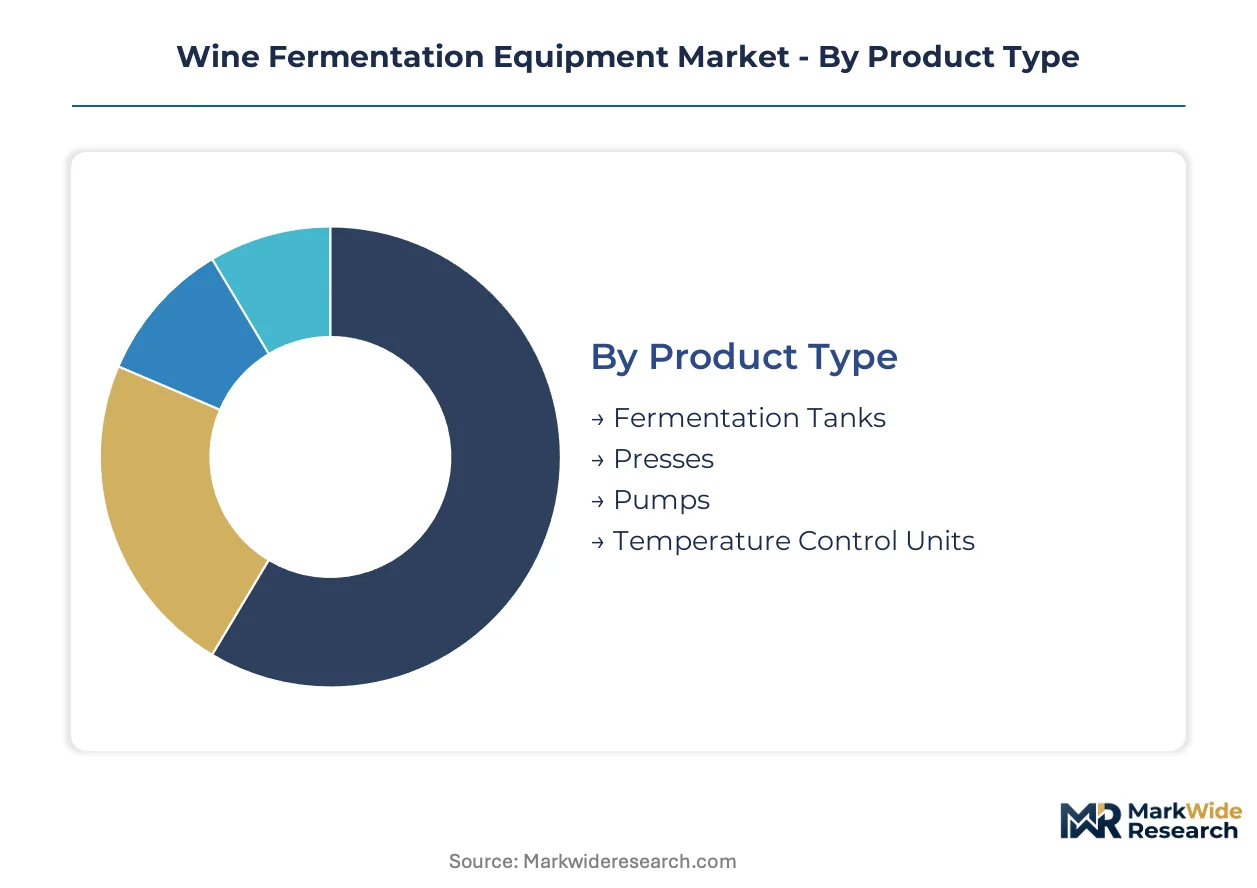
Wine fermentation equipment segmentation reveals how capital allocation priorities diverge across facility scale, regulatory exposure, and automation readiness. Equipment specification choices cascade through decades-long infrastructure cycles, locking wineries into particular operational paradigms.
Product Type:
Mature tank architectures dominate capital deployment, while emerging sensor-integrated systems reshape replacement schedules.
- Fermentation Tanks:Cylindrical vessels with glycol-jacketed cooling surfaces process must volumes from 1,000 to 50,000 liters. Napa Valley and Bordeaux operations prioritize ASME-certified pressure ratings for red wine cap management programs. Stainless steel variants command the largest installed base due to FDA food contact surface compliance and thermal conductivity specifications.
- Presses:Pneumatic membrane systems extract juice through controlled bladder inflation, replacing traditional basket screw mechanisms. Champagne houses and English sparkling wine producers concentrate demand here for gentle whole-cluster pressing protocols that preserve phenolic delicacy.
- Pumps:Peristaltic and centrifugal designs transfer must and wine between cellar stages. European suppliers face EU Machinery Directive certification delays that compress their competitive position against pre-certified German manufacturers.
- Temperature Control Units:Chiller systems and heat exchangers maintain fermentation kinetics within target ranges. EU F-Gas Regulation phase-downs on hydrofluorocarbon refrigerants force costly redesigns before end-of-life cycles.
Fermentation tanks retain volume leadership; temperature control units hold the steepest expansion curve as thermal precision becomes a competitive differentiator.
Material:
Cost tier stratification separates premium fabricators from commodity suppliers, with certification thresholds acting as pricing floor determinants.
- Stainless Steel:304 and 316L grades deliver sanitization compliance, weldability, and corrosion resistance for acidic must environments. Nickel and molybdenum price volatility compress margin visibility for tank fabricators on fixed-price contracts.
- Glass:Demijohns and carboys serve experimental and small-batch programs. Home brewer segments in Germany and Australia sustain demand for borosilicate vessels despite fragility constraints.
- Wood:Oak barrels and vats provide micro-oxygenation and tannin integration for premium programs. Centuries-old barrel programs resist sensor retrofit compatibility, forcing parallel inventory systems.
- Plastic:High-density polyethylene tanks serve entry-level and mobile fermentation applications. USDA BioPreferred procurement thresholds favor recycled content streams, opening positioning for domestic fabricators.
Stainless steel dominates revenue concentration; hybrid concrete-steel vessels are expanding most quickly as mid-tier wineries seek thermal mass stability with sanitization compliance.
End User:
Customer type determines automation sophistication, with commercial wineries separating from artisanal and research segments on capital intensity.
- Wineries:Commercial operations from boutique to industrial scale deploy capital across the full equipment spectrum. CalRecycle water efficiency mandates accelerate stainless steel replacement schedules in California.
- Home Brewers:Enthusiast and semi-professional segments purchase smaller-scale tanks and accessory systems. Online retail channels and subscription-based equipment services concentrate distribution here.
- Research Institutions:University enology programs and government experimental stations require precision instrumentation for yeast strain development. Funding cycles and grant dependencies create lumpy demand patterns.
- Beverage Manufacturers:Cider, sake, and alternative fermentation producers repurpose wine-specific equipment for parallel applications. Cross-category utilization expands addressable market for flexible tank configurations.
Commercial wineries anchor procurement volume; research institutions are gaining share fastest as precision fermentation monitoring migrates from academic to commercial adoption.
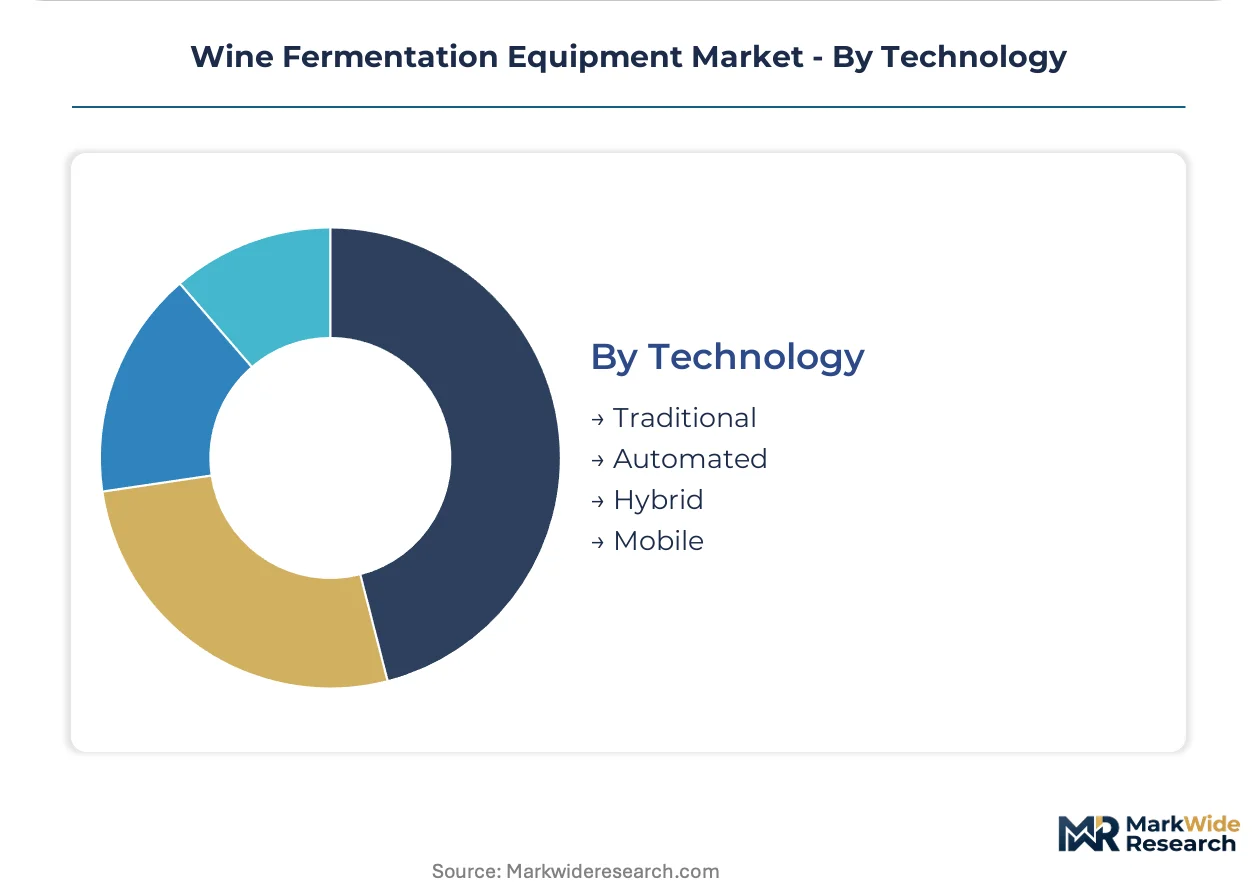
Technology:
Application intensity varies by harvest scale, with automated systems penetrating large operations while manual methods persist in heritage programs.
- Traditional:Manual punch-down, thermocouple logging, and gravity-fed transfers sustain artisanal methodologies. Labor arbitrage fails to offset batch consistency penalties as wage structures climb in traditional winegrowing regions.
- Automated:Sensor networks, programmable pump-overs, and cloud-based fermentation dashboards compress response windows. Napa Valley and Mendoza operations deploy these across 500+ tank installations within single harvest seasons.
- Hybrid:Manual capability preserved alongside sensor-driven temperature logging and automated alerts. Mid-size winery capital budgets concentrate here, balancing heritage protocols with consistency imperatives.
- Mobile:Trailer-mounted and modular tank systems serve custom crush facilities and harvest overflow scenarios. Right-bank Bordeaux satellite appellations deploy these to extend processing capacity without footprint expansion.
Traditional systems retain installed base dominance; automated technology is climbing the fastest as labor costs and consistency requirements reshape capital allocation priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment fabricators export precision-engineered fermentation systems to premium wine producers across France, Italy, and Spain, anchoring intra-European trade flows while California's Napa Valley operations source specialized tanks from domestic stainless steel specialists.
United States
California's boutique wineries in Napa and Sonoma are scaling automated tank installations to reduce labor dependency and improve batch consistency. The EPA's tightening water reuse mandates force equipment upgrades across major producing regions, accelerating stainless steel replacement schedules. Central Valley custom crush facilities deploy mobile fermentation systems to handle harvest overflow without permanent footprint expansion.
France
Bordeaux's right-bank satellite appellations install temperature-jacketed tanks to extend harvest processing capacity. The country's environmental compliance frameworks for agricultural processing constrain equipment specifications in premium production zones. Champagne houses concentrate demand for pneumatic membrane presses that preserve phenolic delicacy through gentle whole-cluster protocols.
Italy
Tuscan and Piedmont estates balance heritage barrel programs with sensor-integrated fermentation monitoring to compress batch-to-batch variation. EU Machinery Directive amendments mandate functional safety ratings for automated pump-over systems, creating six-month certification delays for domestic suppliers. ASME-certified pressure vessel welders concentrate in northern Italian fabrication clusters, creating installation bottlenecks for export projects.
Germany
Pfalz and Baden operations shift from transactional tank purchases to subscription-based monitoring and maintenance agreements, consolidating vendor relationships. EU F-Gas Regulation restrictions on hydrofluorocarbon coolants force costly chiller system redesigns before end-of-life cycles. German equipment suppliers leverage pre-certified status against Italian and Spanish competitors facing compliance delays.
Australia
Barossa Valley and Margaret River mid-size wineries concentrate capital budgets on hybrid fermentation vessels that blend manual punch-down capability with sensor-driven temperature logging. The country's national environmental regulator enforces agricultural processing water efficiency standards that accelerate equipment refresh cycles. Research institutions in Adelaide and Melbourne drive precision fermentation monitoring adoption from academic to commercial contexts.
Wine Fermentation Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where scale-driven integrators, precision engineering specialists, and regional fabrication houses occupy distinct competitive positions. Consolidation pressure concentrates influence with integrators who control downstream service revenue streams through multi-year fermentation suite partnerships. Three archetypes dominate: German precision-engineering houses, Italian specialist fabricators, and North American custom vessel producers. Geographic expansion and technology licensing represent the dominant competitive moves as suppliers seek to bypass certification bottlenecks and welding labor scarcity.
Among European precision-engineering specialists, Bucher Vaslin and Krones AG exemplify the channel-control archetype through integrated fermentation line offerings, while Paul Mueller Company anchors the North American custom fabrication tier. These three names represent distinct geographic and strategic positioning without implying specific market share or operational claims.
| Leading Market Players |
|---|
| Criveller Group |
| G.W. Kent Inc. |
| Agrovin |
| Bucher Vaslin |
| Pellenc Group |
| Krones AG |
| Paul Mueller Company |
| Albrigi Tecnologie S.r.l. |
| Zambelli Enotech S.r.l. |
| Others |
Value Network & Pricing Analysis
German and northern Italian ASME-certified welding clusters concentrate fabrication capacity for pressure-rated fermentation vessels, anchoring margin capture at the certified-fabricator tier while compressing returns for non-certified assembly operations. Nickel and molybdenum price volatility propagates downstream through fixed-price tank contracts, forcing fabricators to either absorb input swings or renegotiate terms mid-project.
Pricing Analysis
Current-generation sensor-integrated fermentation suites command substantial premiums over prior-generation manual tank configurations, while next-generation AI-driven predictive fermentation systems remain pre-commercial. Three-tier pricing structure across premium sensor-integrated, standard glycol-jacketed, and economy polyethylene vessels dominates procurement patterns. Price differentiation rests on ASME certification grade and after-sales service bundling. Cost compression in standard stainless steel tiers is intensifying because nickel price volatility compresses fabricator margins. Boutique Napa Valley and Bordeaux operations show least price sensitivity; entry-level home brewer segments drive volume at tight margin.
Supply Chain Analysis
Stainless steel feedstock draws from German, Italian, and Chinese mill complexes, with 304 and 316L grade specialization clustering in Düsseldorf-Ruhr and Milan-Turin corridors. Critical component dependencies include nickel alloying stock, molybdenum corrosion-resistant grades, and glycol-based thermal transfer fluids. Single-source vulnerability concentrates in ASME-certified pressure vessel welders, where German and northern Italian labor pools create installation bottlenecks for non-European projects. Distribution runs through equipment integrators who bundle tank supply with monitoring subscriptions and maintenance agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as mid-size winery groups consolidate vendor relationships from transactional equipment purchases to multi-year fermentation suite partnerships, compressing supplier pricing leverage across the installed base.
For Market Incumbents: Entrench position through backward integration into sensor hardware and cloud platform development, locking in switching costs before monitoring-as-a-service contracts proliferate. Defend against emerging Chinese fabrication entrants by accelerating ASME and EU Machinery Directive pre-certification investments. Prioritize certification investment as the primary defensive lever against price competition from uncertified Asian suppliers. For New Entrants and Emerging Players: English Sparkling Wine Corridor operations in Kent and Sussex represent the most penetrable entry point, as commercial vineyard expansion outpaces established supplier relationships. Mobile fermentation systems for custom crush overflow scenarios in California Central Valley and Bordeaux satellite appellations offer second white-space target. Go-to-market angle should emphasize rapid deployment capability against six-month certification delays facing European competitors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German precision-engineering houses and Italian specialist fabricators approaching holding period exits. Five-to-ten year viability framing favors suppliers with installed base conversion potential to subscription monitoring revenue. Signal to watch is consolidation velocity among mid-tier wineries, as group formation accelerates procurement centralization and vendor rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Hardware | Captures recurring monitoring revenue streams that incumbent tank fabricators currently forfeit to third-party IoT vendors. |
| EU Machinery Directive Pre-Certification | Compresses project timelines against Italian and Spanish competitors facing six-month notified body delays. |
| Subscription-Based Maintenance Agreements | Locks in multi-year revenue visibility with Pfalz and Barossa Valley mid-size operations shifting from transactional purchasing. |
| Mobile Fermentation System Development | Addresses harvest overflow capacity constraints without permanent footprint expansion in right-bank Bordeaux appellations. |
| Glycol Alternative Refrigerant Transition | Anticipates EU F-Gas Regulation phase-downs that force costly chiller redesigns before end-of-life cycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and equipment procurement databases. Primary interviews encompassed cellar operations directors at commercial wineries, ASME-certified fabrication plant managers, enology program research leads, and aftermarket service heads at equipment integrators. Secondary validation drew from EPA water efficiency mandate documentation, EU Machinery Directive amendment texts, CalRecycle compliance thresholds, and stainless steel commodity price indices. Bottom-up tank installation counts triangulate against top-down winery capital expenditure surveys.
Forecast inputs span fermentation tank capacity by material grade, technology adoption curves across manual-automated-hybrid segments, and regulatory-driven replacement schedules. Segmentation dimensions modeled include product type, material specification, end-user scale tier, and technology intensity across the projection horizon. CAGRs derive from installed base growth, replacement cycle compression, and premium tier mix shift assumptions. Industry-specific inputs incorporate harvest volume projections and water reuse mandate compliance deadlines.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity prices, enology-automation labor availability, or harvest volatility would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption elasticity. Cross-checking against winery association capital expenditure surveys and equipment manufacturer order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Sparkling Red Wine Market
Alcoholic Beverages
Europe Craft Spirits Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Grain Alcohol Market
Alcoholic Beverages
Isoamyl Alcohol Market
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
Middle East and Africa Alcoholic Beverage Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Microbrewery Supplies Market
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
Gin Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
United States Tequila Market
Alcoholic Beverages
Global Wine Market