
 Puncheon Barrel Market | 2026-2036
Puncheon Barrel Market Size, Share, and Industry Trends Forecast 2026-2036
Puncheon Barrel Market Outlook
The EU Timber Regulation and emerging buyer sustainability mandates from spirits conglomerates is pivoting cooperage procurement toward certified French and American oak traceability. Seguin Moreau Napa Cooperage leverages its vertical integration from stave mills to finished puncheons in California and France. Independent Stave Company anchors North American supply through its Missouri-based stave production and seasoning yards. Tonnellerie Sylvain differentiates through specialized toasting protocols for premium wine and spirits clients.
A puncheon barrel is a large-capacity wooden vessel, traditionally constructed from thick oak staves with capacities ranging from 50 to 250 liters, designed for extended liquid maturation through controlled oxygen exchange and wood extractive interaction. The oak material segment dominates commercial volume due to its tannin structure and flavor compound release profile, while acacia represents the fastest-growing alternative as distillers seek subtler wood influence. Traditional puncheon product types command the largest installed base, though customized puncheons with specific toast levels and stave thicknesses capture the highest margin pools as craft producers differentiate aging programs.
REACH compliance in Europe and FDA food-contact material standards in the United States govern cooperage resin treatments and finishing agents, directly shaping product specifications for export-bound barrels. The USDA and France's national forestry certification bodies further constrain raw material sourcing, tightening supply chains for heritage-grade oak. Stakeholders must monitor evolving chemical disclosure requirements across multiple jurisdictions to preserve market access and avoid reformulation costs.
Market Dynamics
Heritage bourbon distilleries in Kentucky and Tennessee are extending aging programs, concentrating demand for large-format oak vessels while EU F-Gas Regulation pressures cooperages to certify responsible sourcing.
Growth Catalysts
- Extended Aging Protocols:Kentucky and Tennessee distilleries are lengthening maturation cycles for premium whiskey expressions, driving replacement cycles and capacity expansion for 50-250 liter vessels.
- REACH Compliance:European chemical disclosure mandates for cooperage resin treatments are creating competitive moats for certified producers with documented supply chains.
- Acacia Adoption:Distillers seeking subtler wood influence are integrating acacia staves into blended barrel constructions, opening alternative material demand channels.
Market Restraints
- Oak Supply Concentration:Heritage-grade American and French oak sourcing tightens under USDA and French national forestry certification constraints, limiting qualified stave suppliers.
- Input Cost Volatility:Seasoned stave inventory carries 18-36 month lead times, exposing cooperages to raw material price swings without immediate pass-through mechanisms.
- Technical Limitation:Traditional puncheon construction requires specialized coopers with generational training, constraining production scaling regardless of capital investment.
Strategic Opportunities
- Wine-Spirits Convergence:Premium wineries in California and Oregon are adopting spirits-grade toasting protocols, blurring category boundaries and expanding addressable demand.
- EU Green Deal Tailwind:Carbon footprint disclosure requirements favor cooperages with vertically controlled stave mills and renewable energy seasoning yards.
- Direct Cooper Relationships:Craft distilleries are bypassing distributors to commission customized toast profiles and stave thicknesses, capturing margin from specification differentiation.
Industry Challenges
- Master Cooper Scarcity:Apprenticeship programs in Missouri and Kentucky cannot replenish retiring skilled labor fast enough to match distillery expansion timelines.
- Certification Timeline Compression:Multi-jurisdiction chemical disclosure requirements demand parallel documentation streams, straining quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Puncheon Barrel Market |
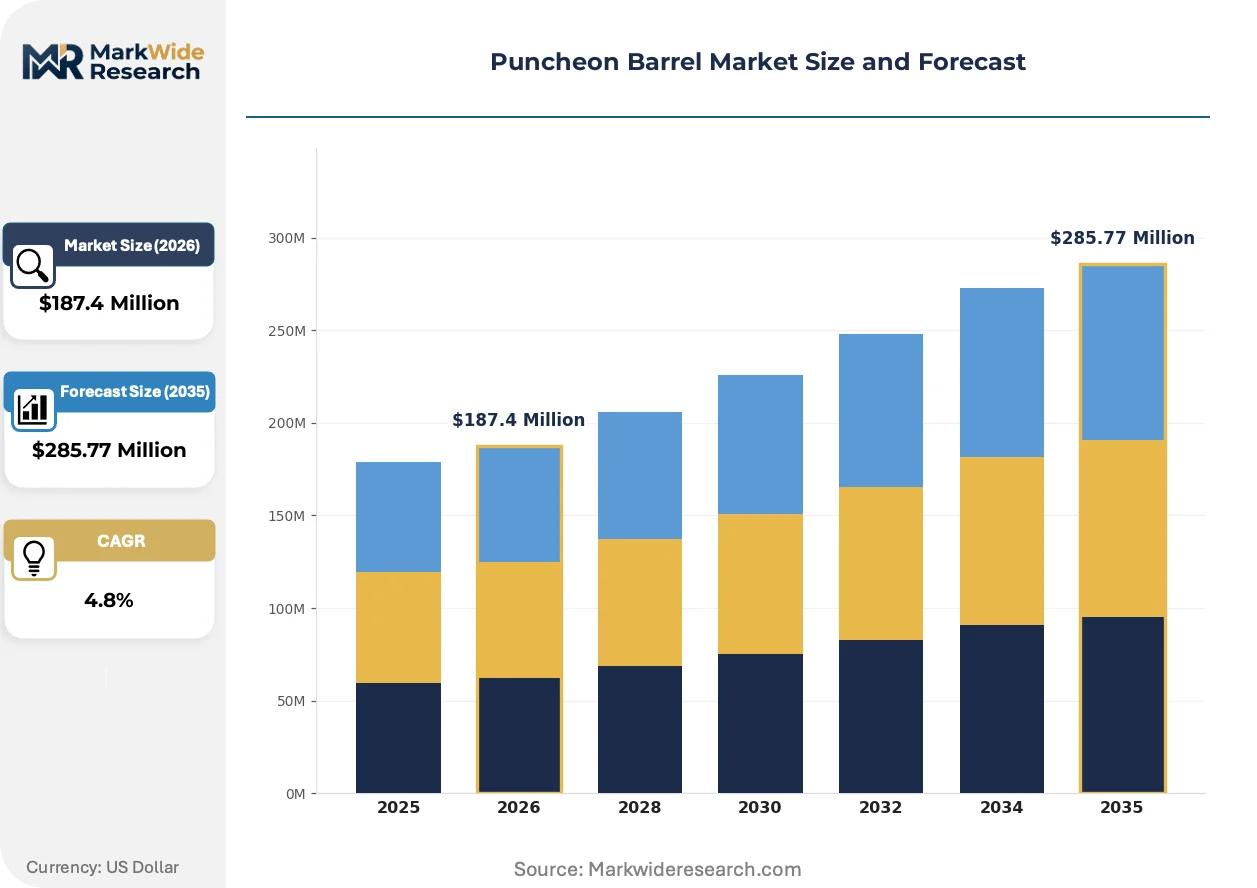
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Oak, Chestnut, Maple, Acacia Product Type: Traditional Puncheon, Customized Puncheon, Reconditioned Puncheon, Decorative Puncheon Application: Whiskey Aging, Wine Storage, Beer Fermentation, Spirits Production Size: 50 Liters, 100 Liters, 200 Liters, 250 Liters |
| Companies Covered | Seguin Moreau Napa Cooperage, Canton Cooperage, World Cooperage, The Barrel Mill, Nadalié USA, Tonnellerie Sylvain, Independent Stave Company, Tonnellerie de L’Adour, East Coast Wood Barrels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Puncheon Barrel Market Strategic Shifts
Precision toasting technology and alternative wood species are reshaping how maturation vessels deliver extractive compounds, while regulatory transparency mandates restructure procurement relationships across the value chain.
Laser-guided toasting systems are expanding into premium cooperage operations, enabling zone-specific heat application that modulates vanillin and lactone release profiles. Kentucky distilleries with experimental aging programs are commissioning these units for single-lot customization. The technology is expanding into mid-tier producers previously priced out of specification-grade barrel programs.
EU F-Gas Regulation enforcement is tightening traceability requirements for oak adhesives and finishing agents used in export-bound cooperage. French cooperages must now document stave mill origin and seasoning yard energy sources to maintain market access. American exporters to Europe are reformulating paraffin seals and resin treatments to preempt customs rejection.
Distillery procurement teams are consolidating supplier relationships around cooperages with captive stave production and certified forestry chains. Small-batch producers previously sourcing through distributors now negotiate directly with Missouri-based seasoning yards for allocation priority. This consolidation is most visible in Tennessee, where heritage brands anchor multi-year volume commitments with integrated suppliers.
Puncheon Barrel Market Segmentation
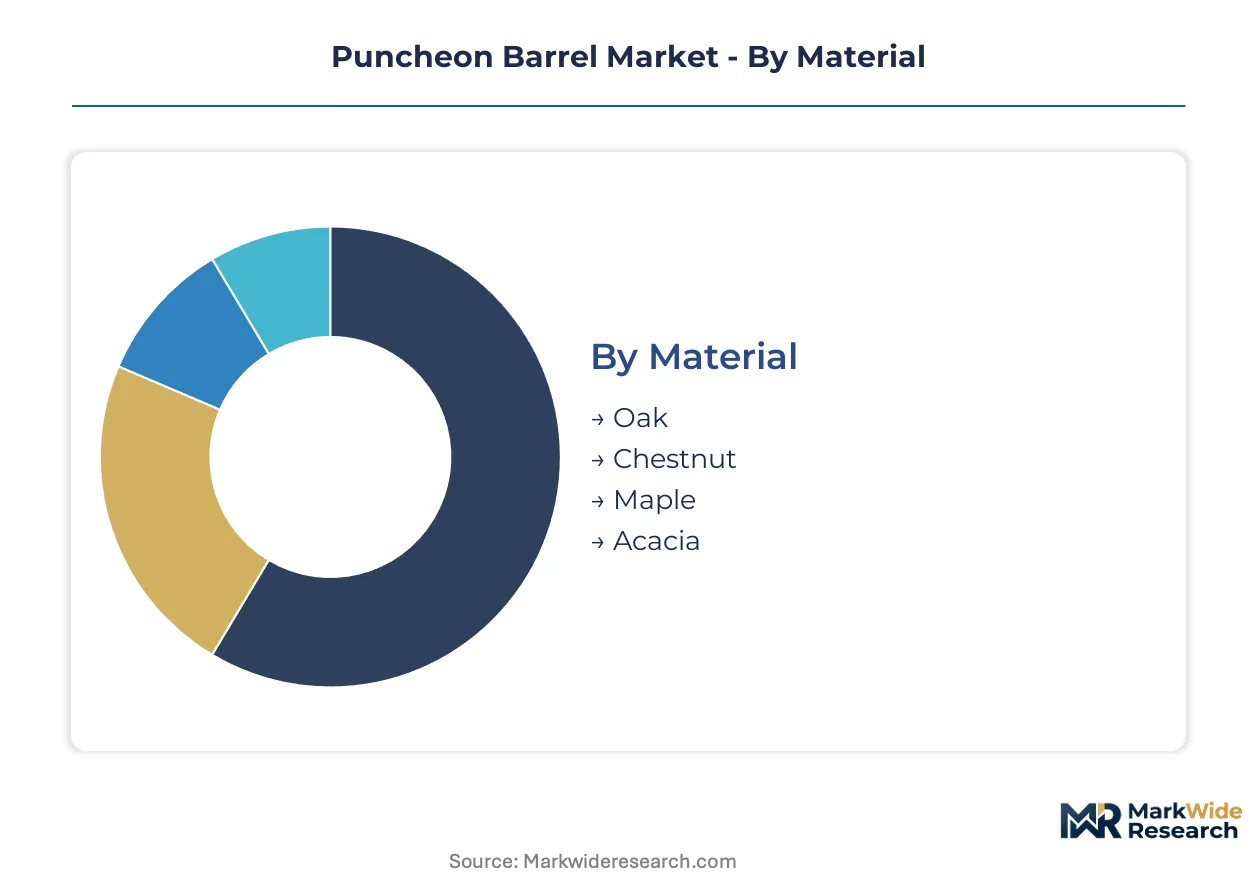
Puncheon barrel segmentation reflects divergent technical requirements across spirits maturation protocols. Material selection and vessel configuration directly determine extractive compound release rates, oxygen permeability, and compliance with jurisdiction-specific food-contact standards.
Material:
Material segments split between standalone oak dominance and emerging acacia integration for blended construction programs.
- Oak:American and French oak varieties provide the dense tannin lattice and lactone reservoirs that define premium whiskey maturation. Kentucky distilleries anchor volume commitments for heritage-grade white oak with 24-36 month air-seasoning protocols.
- Acacia:Distillers seeking reduced wood influence integrate acacia staves into hybrid barrel constructions. French cooperages report accelerating inquiries from experimental whiskey programs in Tennessee pursuing subtler extractive profiles.
- Chestnut:Italian grappa producers maintain niche demand for chestnut's porous structure and distinctive phenolic signature.
- Maple:Vermont craft distillers commission limited maple puncheon runs for specialty bourbon expressions requiring accelerated vanillin release.
Oak leads volumes today; acacia is gaining share fastest.
Product Type:
Product configuration stratifies by customer technical capability and margin capture potential.
- Traditional Puncheon:Standardized 50-250 liter vessels with established toast profiles serve high-volume bourbon houses. Missouri seasoning yards prioritize allocation to heritage brands with multi-year supply agreements.
- Customized Puncheon:Specification-grade units with zone-specific toasting and variable stave thickness command premium positioning. California wineries adopting spirits-grade protocols drive demand for laser-guided heat application systems.
- Reconditioned Puncheon:Refurbished vessels extend service life for mid-tier producers managing capital constraints.
- Decorative Puncheon:Aesthetic-finished barrels serve retail display and hospitality venue installations without maturation function.
Traditional puncheons dominate installed base; customized variants capture steepest expansion trajectory.
Application:
Application segmentation tracks divergent oxygen exchange requirements and regulatory compliance burdens across liquid categories.
- Whiskey Aging:Extended maturation cycles in Kentucky and Tennessee concentrate demand for 200-250 liter vessels with controlled permeability. REACH-compliant resin treatments are mandatory for export-bound cooperage.
- Wine Storage:Napa and Sonoma wineries are adopting spirits-grade toasting intensities for red wine programs, blurring traditional category specifications.
- Beer Fermentation:Sour beer producers in Oregon utilize puncheons for mixed-culture secondary fermentation.
- Spirits Production:Rum and brandy distillers in the Caribbean and Cognac maintain distinct stave thickness preferences.
Whiskey aging anchors volume; wine storage applications are climbing the fastest.
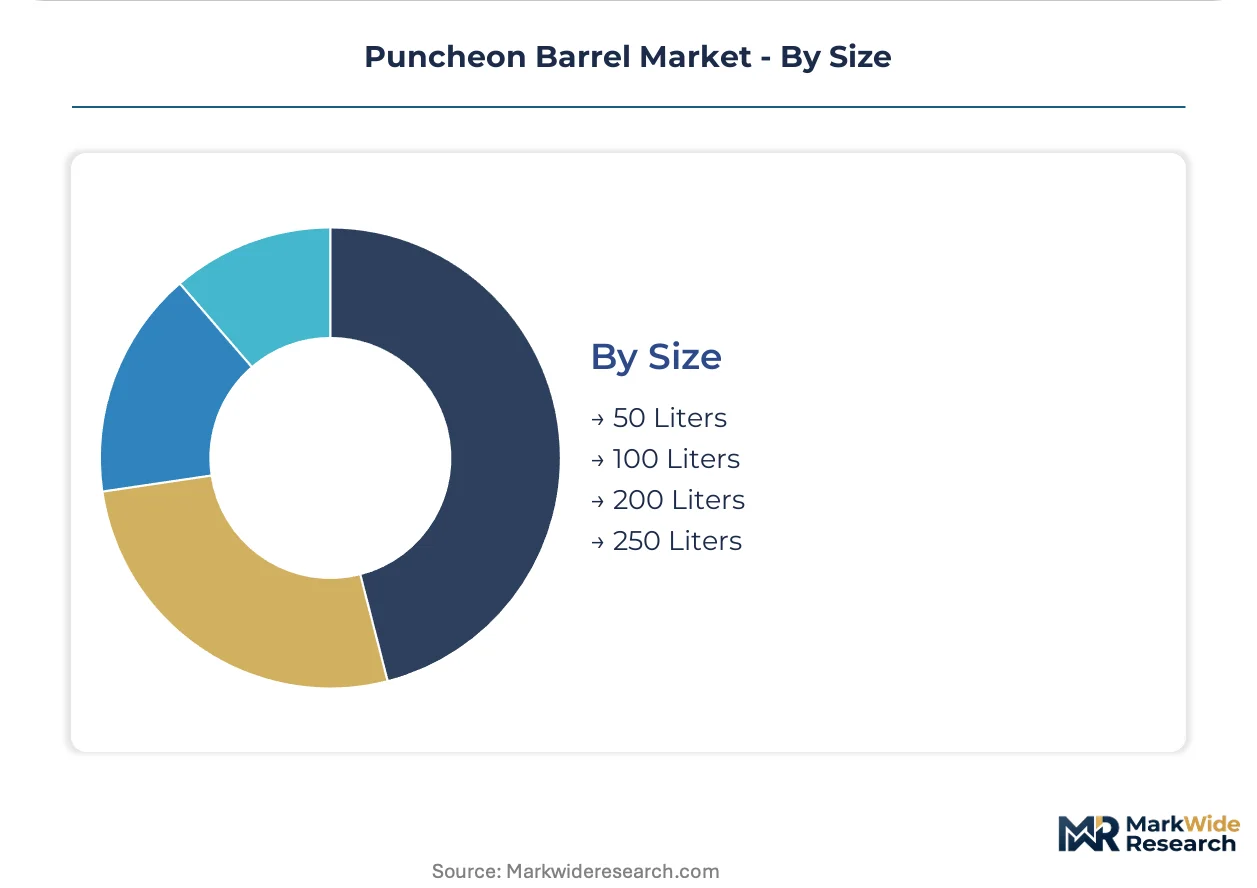
Size:
Capacity selection reflects surface-area-to-volume ratios that modulate maturation velocity and warehouse footprint efficiency.
- 200 Liters:The standard bourbon industry format balances extractive intensity with inventory turnover economics. Tennessee heritage brands anchor procurement at this capacity tier.
- 250 Liters:Extended-aging programs in Kentucky favor maximum volume for angel's share efficiency in multi-decade maturation.
- 100 Liters:Craft distilleries in Oregon and Washington utilize mid-capacity vessels for experimental single-lot releases.
- 50 Liters:Limited-run specialty expressions and pilot-scale production occupy this compact format.
200-liter vessels lead volumes today; 250-liter formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master coopers trained in Missouri and Kentucky anchor North American production capacity, while French apprenticeship pipelines in Limousin and Vosges sustain European heritage fabrication.
United States
Kentucky and Tennessee distilleries commission 200-250 liter puncheons for extended bourbon aging programs. FDA food-contact material standards govern resin treatments and paraffin seals on export-bound cooperage. The Missouri-Kentucky corridor concentrates seasoning yards and stave mills serving heritage brands with multi-year supply agreements.
France
Cognac houses and premium wine estates drive specification-grade demand for customized toast profiles. The EU F-Gas Regulation and REACH compliance mandates enforce chemical disclosure across stave mill origin documentation. Limousin and Vosges forests supply certified French oak to cooperages with vertically controlled seasoning operations.
Italy
Grappa producers maintain niche demand for chestnut puncheons with distinctive phenolic signatures. National forestry certification bodies constrain raw material sourcing for heritage-grade construction. Piedmont and Veneto cooperages serve regional distillers seeking traditional vessel formats for specialty spirit categories.
Spain
Sherry bodegas in Jerez sustain traditional puncheon formats for oxidative aging protocols. ECHA chemical disclosure requirements shape cooperage finishing agent specifications for export markets. Andalusian fabrication clusters preserve generational cooper techniques amid constrained skilled labor availability.
Japan
Whiskey distillers in Yamazaki and Yoichi integrate puncheon-scale vessels for experimental maturation programs. METI industrial standards and import regulations govern wood sourcing for domestic cooperage construction. The Chubu region hosts specialized fabricators serving premium spirits producers seeking controlled oxygen exchange profiles.
Puncheon Barrel Market Competitive Environment
Capital-heavy producers with captive stave mills and seasoning yards compete with asset-light designers commissioning specification-grade vessels from third-party cooperages. The market structure concentrates around vertically integrated specialists controlling upstream oak supply and independent fabricators serving regional craft distilleries. Two strategic archetypes dominate: heritage cooperages with generational workforce pipelines and technology-forward operations deploying laser-guided toasting systems. Competitive moves center on multi-year volume commitments with distillery anchor clients and backward integration into certified forestry concessions.
Among French heritage cooperages, Seguin Moreau Napa Cooperage and Tonnellerie Sylvain exemplify the premium-tier archetype with transatlantic production footprints. Independent Stave Company anchors the North American supply base from its Missouri operations. These three occupy positions spanning traditional apprenticeship-based fabrication and precision-toasting technology adoption.
| Leading Market Players |
|---|
| Seguin Moreau Napa Cooperage |
| Canton Cooperage |
| World Cooperage |
| The Barrel Mill |
| Nadalié USA |
| Tonnellerie Sylvain |
| Independent Stave Company |
| Tonnellerie de L'Adour |
| East Coast Wood Barrels |
| Others |
Value Chain & Pricing Dynamics
Certification-grade oak divergence between heritage-tier and commodity cooperage manifests in dual pricing tracks and geographically separated seasoning yard networks. Kentucky heritage brands command allocation priority through captive stave supply, while export-bound producers absorb REACH compliance premiums that reshape procurement geography toward vertically controlled French and American oak sources.
Pricing Analysis
Bundled specification services versus unbundled commodity vessel sales split the market into divergent margin structures. Three-tier pricing stratifies across premium laser-toasted custom puncheons, standard air-seasoned heritage oak vessels, and economy-grade reconditioned units. Price differentiation rests on certification tier and toast customization depth, with REACH-compliant resin treatments adding cost layers for EU-bound shipments. Pricing pressure intensifies in the standard tier as Missouri seasoning yards expand capacity to serve mid-volume craft distilleries. Craft producers exhibit highest price sensitivity, while heritage bourbon houses prioritize supply security over unit cost.
Supply Chain Analysis
Direct-to-distillery channels handle heritage brand volume commitments, while distributor networks serve fragmented craft demand across Oregon, Washington, and emerging state markets. Geographic supply concentration centers on the Missouri-Kentucky corridor for American oak and Limousin-Vosges forests for French heritage material. Raw material dependencies include 24-36 month air-seasoned stave inventory, specialized cooper labor pools, and FDA-compliant resin treatments. Supply chain risk runs through master cooper scarcity constraining production scaling regardless of capital investment. Distribution runs through integrated cooperages with captive seasoning yards for premium tiers, and independent fabricators for standardized vessel procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as distillery procurement shifts decisively toward specification-grade vessels with documented forestry chains and zone-specific toasting protocols.
For Market Incumbents: Lock in multi-year volume commitments with Tennessee and Kentucky heritage brands before craft distillery consolidation accelerates. Secure backward integration into certified forestry concessions to preempt oak supply tightening under USDA and French national certification constraints. Invest in laser-guided toasting capacity to capture margin from California winery adoption of spirits-grade protocols. For New Entrants and Emerging Players: Laser-guided toasting technology offers a defensible entry point into the customized puncheon segment previously monopolized by heritage cooperages. Target experimental whiskey programs in Oregon and Washington seeking single-lot toast customization unavailable from standardized suppliers. Pursue direct relationships with craft distilleries bypassing distributor markups through specification differentiation and allocation priority guarantees. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier cooperages possessing captive seasoning yards and pending REACH certification completion. Long-term viability favors operations with demonstrated apprentice pipeline replenishment and transatlantic production footprints serving both FDA and EU regulatory clusters. Monitor master cooper graduation rates from Missouri and Kentucky apprenticeship programs as inflection indicator for supply-constraint severity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Stave Mill Acquisition | Secures heritage-grade oak allocation priority under tightening USDA certification constraints. |
| Laser-Guided Toasting Deployment | Enables zone-specific heat application for California winery spirits-grade protocol adoption. |
| REACH Compliance Certification | Maintains EU market access as ECHA enforcement tightens on cooperage chemical disclosure. |
| Direct Distillery Partnership Program | Bypasses distributor networks to capture margin from craft producer specification differentiation. |
| Master Cooper Apprenticeship Expansion | Addresses skilled labor scarcity constraining production scaling across Missouri and Kentucky yards. |
Study Parameters
Coverage spans the American Southeast, Western Europe, and East Asian premium spirits markets, with primary inputs from each region informing demand calibration. The approach combines structured interviews with master coopers, distillery procurement directors, and seasoning yard operations managers with secondary validation from customs records, forestry certification databases, and FDA/ECHA regulatory filings. Bottom-up vessel shipment data triangulates against top-down distillery capacity expansion announcements.
Rate-of-change decomposition separates volume growth from value growth across the projection horizon. Segmentation dimensions modeled include material type, product configuration tier, application category, and capacity format. CAGRs derive from installed base replacement cycles, net capacity additions, and specification-grade adoption curves. Industry-specific forecast inputs incorporate REACH compliance timeline acceleration and laser-toasting technology penetration rates.
The model holds under sustained heritage bourbon aging program expansion and stable French-American oak supply; deviation in master cooper availability or EU chemical disclosure tightening would shift trajectory assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Barware Market
Alcoholic Beverages
High-End Baijiu Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
Mexico Alcohol E-Commerce Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Global Brewery Filtration Market
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market
Alcoholic Beverages
Sparkling Wine Market
Alcoholic Beverages
North America Soju Market
Alcoholic Beverages
Rhum Agricole Market
Alcoholic Beverages
United States Spirits Market
Alcoholic Beverages
Cider and Perry Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
Luxury Wines and Spirits Market