
 Bayberry Wine Market | 2026-2036
Bayberry Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Bayberry Wine Market Insights
Precision fermentation control is narrowing quality variance between artisanal and scaled bayberry wine production. Ningxia Hong leverages its northwest China terroir knowledge to sustain premium positioning in red-style bayberry expressions. Jiangzhong Pharmaceutical anchors its portfolio with health-positioned formulations that compete against conventional grape wines in pharmacy channels. Zhangzhou Tongyuan Wines specializes in traditional Fujian methods that differentiate its output from industrial alternatives.
Bayberry wine is an alcoholic beverage produced by fermenting bayberry (Myrica rubra) fruit, typically yielding 8–15% alcohol by volume with distinctive tart-phenolic profiles shaped by native yeast strains and controlled maceration periods. The product serves both gastronomic pairing and functional beverage markets where consumers seek alternatives to Vitis vinifera wines. Red Wine commands the dominant share of current output, though Sparkling Wine represents the fastest-growing product type as producers adopt Charmat-method adaptations for effervescent expressions. Online Sales channels are capturing disproportionate growth momentum, while Retail Stores retain the largest absolute volume throughput and margin stability.
China's SAMR enforces GB standards for fermented alcoholic beverages that dictate permissible additives and labeling claims for bayberry-derived products. The country's dual carbon goals pressure producers toward energy-efficient fermentation and localized sourcing to reduce transport emissions. Stakeholders must monitor how evolving national food safety protocols intersect with regional terroir marketing claims to determine compliance investment priorities.
Market Dynamics
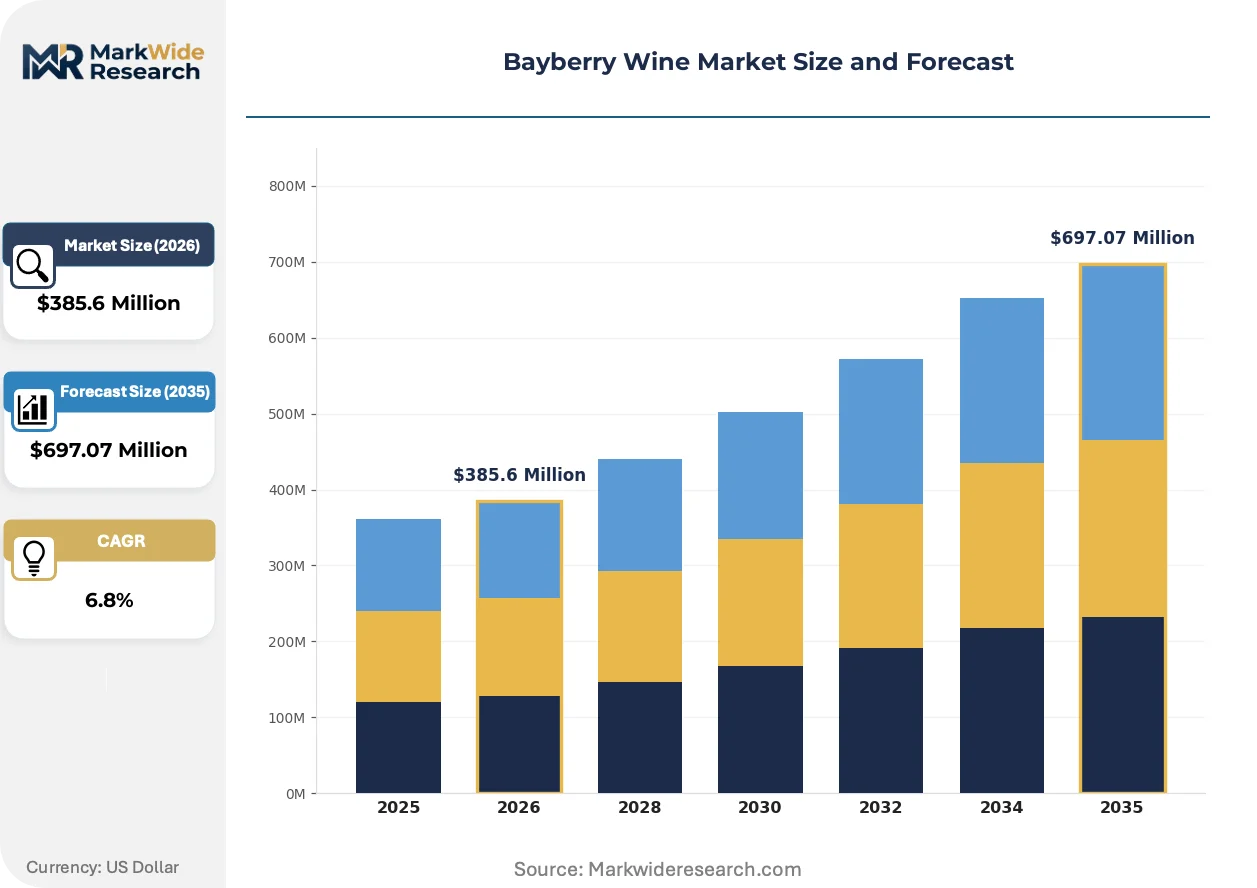
Precision fermentation control is compressing quality variance between artisanal and industrial bayberry wine production, while China's SAMR labeling enforcement and dual carbon goals reshape capital allocation priorities across the value chain.
Growth Catalysts
- Dual Carbon Goals:China's national emissions targets pressure producers toward energy-efficient fermentation systems and localized Zhejiang sourcing, reducing transport-related carbon intensity in supply chains.
- Charmat-Method Adaptation:Sparkling wine producers deploy modified tank fermentation for effervescent bayberry expressions, capturing consumer interest in celebratory indigenous alternatives.
- Pharmacy Channel Expansion:Health-positioned formulations compete against conventional grape wines in China's pharmacy retail networks, accessing wellness-oriented consumer segments.
Market Restraints
- Input Volatility:Bayberry harvest concentration in Zhejiang Province creates seasonal supply risk and price instability for processors dependent on single-origin fruit procurement.
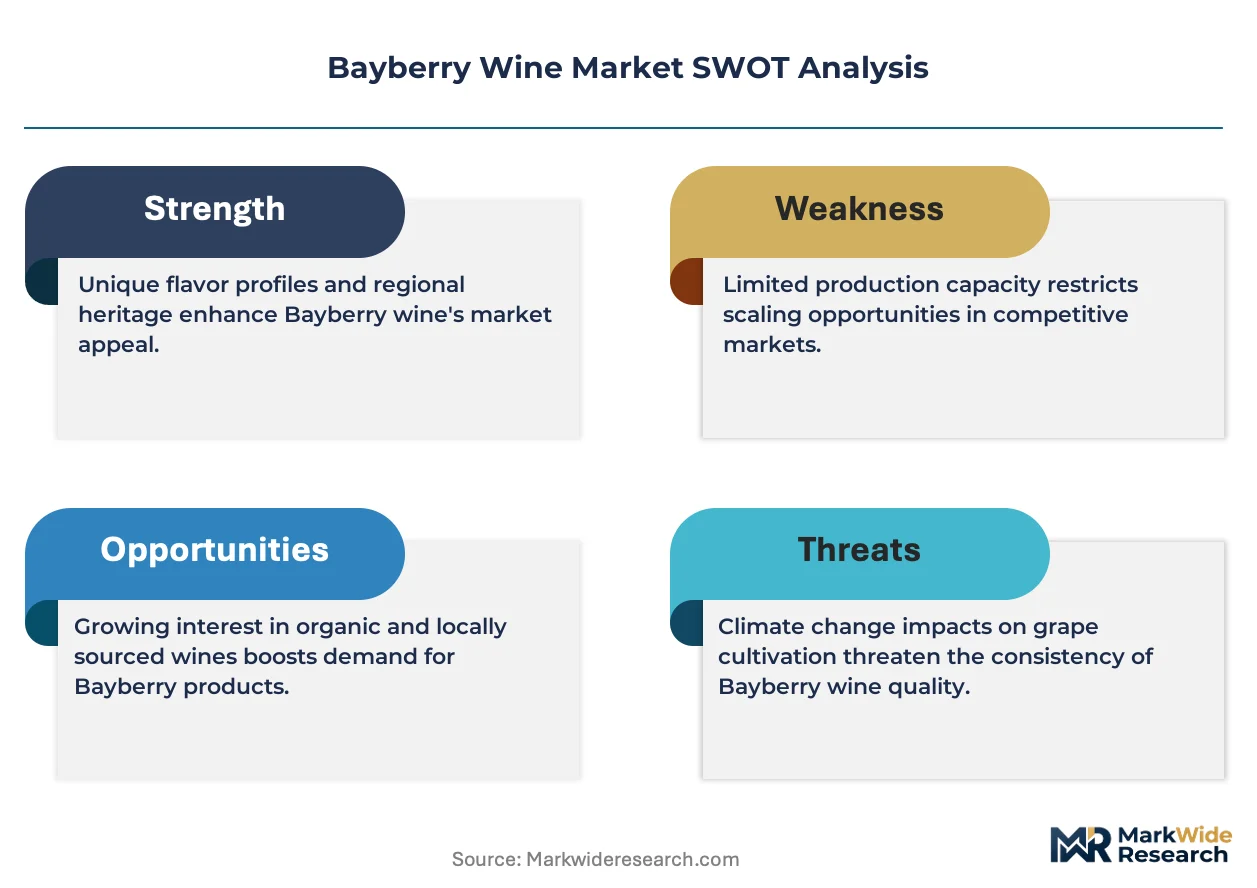
- GB Standard Friction:SAMR's evolving GB standards for fermented alcoholic beverages impose compliance costs on small-scale producers lacking in-house regulatory expertise.
- Grape Wine Substitution:Established Vitis vinifera wines dominate consumer familiarity and retail shelf space, limiting trial conversion for unfamiliar fruit wine categories.
Strategic Opportunities
- E-Commerce Penetration:Online sales channels capture disproportionate growth momentum in China's beverage market, enabling direct-to-consumer reach beyond traditional retail gatekeepers.
- Terroir Marketing:Northwest China producers leverage distinct soil and climate conditions to differentiate premium red-style expressions from mass-market alternatives.
- Functional Positioning:Polyphenol-rich tart profiles align with preventive health consumption trends, opening formulation partnerships with wellness-focused retail channels.
Industry Challenges
- Yeast Strain Consistency:Native fermentation microbiota variability complicates batch standardization, requiring investment in controlled inoculation protocols and laboratory infrastructure.
- Labeling Compliance Timeline:SAMR's stricter additive disclosure mandates force reformulation cycles and packaging redesigns that compress product launch windows.
- Cross-Channel Integration:Producers managing simultaneous pharmacy, specialty retail, and direct-to-online distribution face inventory fragmentation and margin accounting complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bayberry Wine Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Wine, White Wine, Sparkling Wine, Dessert Wine Distribution Channel: Retail Stores, Online Sales, Wholesale, Direct-to-Consumer End User: Restaurants, Retailers, Distributors, Individual Consumers Packaging Type: Bottles, Cans, Tetra Packs, Kegs |
| Companies Covered | Ningxia Hong, Jiangzhong Pharmaceutical, 12Ling, Zhongbo Green Technology, Beijing Shunxing Halewood Alcoholic Beverages, Shaanxi Lanhai Fruit Industry, Zhangzhou Tongyuan Wines Co., Ltd, Sanmen Xiaoxiang Bayberry Wine Co., Ltd, Zhejiang Goodday Food Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bayberry Wine Market Trends and Innovations
Active fermentation monitoring, regulatory disclosure expansion, and channel diversification are restructuring how bayberry wine reaches consumers and complies with evolving safety frameworks.
Native yeast cultivation is migrating from spontaneous fermentation reliance toward controlled strain banking and laboratory propagation. Premium producers in Zhejiang and Fujian are adopting cryopreserved inoculum to reduce vintage variation. This biotechnology compression enables consistent phenolic extraction and alcohol stability across scaled output volumes.
China's SAMR is tightening additive disclosure requirements under revised GB standards for fermented fruit products. Industrial consequence includes mandatory reformulation of products containing non-standard processing aids. Small-batch artisanal producers face disproportionate analytical testing burdens compared to integrated operations with captive laboratories.
Specialty beverage retailers are unbundling traditional distributor relationships to source directly from provincial producers. This disintermediation concentrates in East Asian urban markets where consumers prioritize provenance transparency. Pharmacy channels in Chinese tier-one cities now stock health-positioned bayberry formulations alongside conventional supplement categories.
Bayberry Wine Market Segmentation
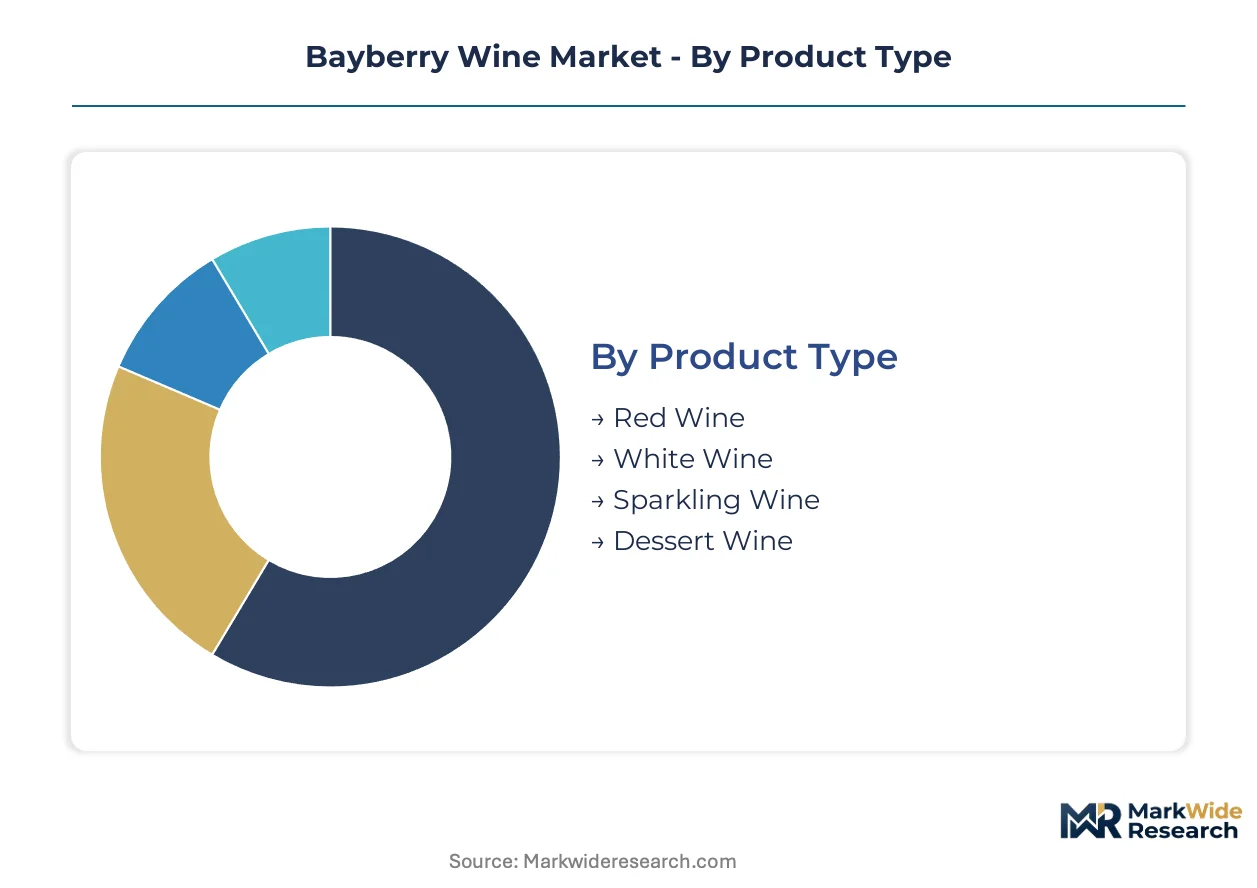
Segmentation in the bayberry wine market reveals how production cycles, channel velocity, and consumption occasions fragment commercial opportunity. Understanding these divides exposes where capital deploys most efficiently and which formats resist commoditization.
Product Type:
Production cycle times vary dramatically across fermentation styles, with Charmat-method sparklings demanding extended tank residence while red wines compress from crush to bottle.
- Red Wine:Extended maceration extracts anthocyanins and tannins from bayberry skins, yielding 8–15% ABV expressions with structured phenolic profiles. Zhejiang Province's cultivation clusters anchor supply for this dominant format, though vintage compression from dual carbon goals pressures energy-intensive cellar operations.
- Sparkling Wine:Modified tank fermentation creates effervescent indigenous alternatives to imported champagne, with secondary fermentation extending production cycles 40–60 days longer than still formats. China's tier-one cities drive disproportionate trial as celebratory positioning displaces conventional grape sparklings at price-advantaged entry points.
- White Wine:Pressed-juice fermentation without skin contact produces lighter, lower-tannin expressions suited to summer consumption occasions.
- Dessert Wine:Arrested fermentation or late-harvest concentration elevates residual sugar for after-dinner positioning in specialty retail.
Red Wine dominates installed base. Sparkling Wine is where expansion concentrates.
Distribution Channel:
Channel economics stratify by margin retention and working capital intensity, with direct models capturing value that wholesale relinquishes for volume scale.
- Online Sales:Direct-to-consumer platforms bypass traditional retail gatekeepers, enabling provincial producers to reach urban consumers without distributor margin stacking. SAMR's evolving e-commerce disclosure mandates impose compliance costs that favor integrated operations with captive regulatory expertise over fragmented artisanal sellers.
- Retail Stores:Specialty beverage retailers in East Asia expand shelf space for indigenous fruit wines, offering margin stability through established foot traffic and provenance storytelling. Inventory carrying costs and slotting fees compress returns for smaller producers lacking negotiating leverage.
- Wholesale:Volume aggregation through regional distributors enables national reach but relinquishes pricing control and consumer data access.
- Direct-to-Consumer:Winery tasting rooms and subscription models capture highest per-unit margins while limiting geographic scalability.
Retail Stores anchor volume throughput. Online Sales is climbing the fastest.
End User:
Demand concentration shifts by occasion type, with on-premise consumption commanding premium pricing against at-home volume plays.
- Individual Consumers:Wellness-oriented households in Chinese tier-one cities drive pharmacy channel expansion for health-positioned formulations, accessing preventive consumption trends that compete with conventional supplements. E-commerce penetration enables discovery beyond traditional retail gatekeepers, though brand building requires sustained digital marketing investment.
- Restaurants:Gastronomic pairing programs in East Asian metropolitan markets elevate bayberry wine as indigenous alternatives to imported grape varieties, with sommelier education determining trial conversion rates.
- Retailers:Specialty beverage merchants curate provenance-transparent assortments that differentiate from mass-market alternatives.
- Distributors:Regional aggregators manage logistics complexity for producers lacking national cold-chain infrastructure.
Individual Consumers represent the deepest volume pool. Restaurants is gaining share fastest.
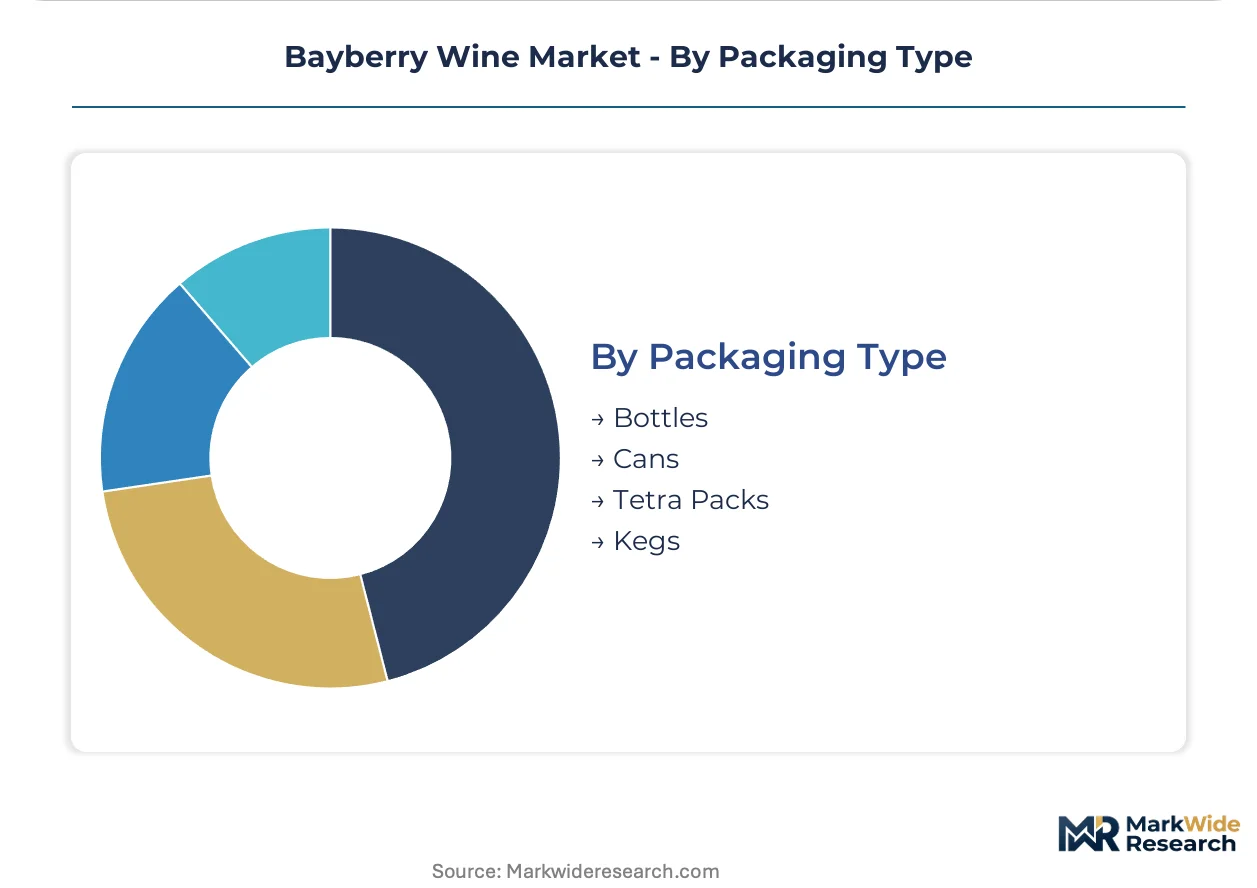
Packaging Type:
Format selection trades preservation integrity against logistics economics, with single-serve innovations disrupting traditional bottle hegemony.
- Bottles:Standard 750ml glass remains the prestige format for red and dessert wine expressions, with label real estate enabling terroir storytelling and regulatory compliance display. Zhejiang and Fujian producers leverage premium bottle aesthetics to differentiate from industrial alternatives in specialty retail.
- Cans:Single-serve aluminum formats target outdoor consumption and younger demographics with portability advantages, though oxygen transmission rates limit shelf life versus glass.
- Tetra Packs:Aseptic cartons reduce shipping weight and breakage for value-tier expressions in mass retail.
- Kegs:On-premise draft systems minimize packaging waste for high-volume restaurant accounts with rapid turnover.
Bottles command premium positioning. Cans is where format experimentation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang Province exports bayberry wine through Shanghai's port infrastructure to reach urban consumers across East Asia, while domestic distribution networks concentrate within China's eastern seaboard corridor.
China
Pharmacy channel expansion and dual carbon compliance reshape production economics for health-positioned formulations. SAMR enforces GB standards for fermented alcoholic beverages that dictate additive disclosure and labeling claims. Zhejiang Province's bayberry cultivation clusters anchor supply for red-style expressions, with Ningxia producers leveraging northwest terroir for premium positioning.
Japan
Specialty beverage retailers in Tokyo and Osaka curate indigenous fruit wine assortments as alternatives to conventional grape varieties. METI guidelines on alcoholic beverage imports shape compliance requirements for Chinese exporters entering Japanese distribution. Kyushu's emerging fruit wine producers experiment with bayberry fermentation techniques adapted from local shochu expertise.
South Korea
Seoul's gastronomic dining scene drives sommelier-led trial of East Asian fruit wines in pairing programs. MFDS regulates fermented fruit product labeling and health claims for beverages distributed through retail and hospitality channels. Busan-Ulsan port logistics enable re-export handling of Chinese bayberry wine shipments bound for broader Northeast Asian markets.
Taiwan
Direct-to-consumer e-commerce platforms connect Taiwanese consumers with Fujian and Zhejiang producers bypassing traditional importer margins. The island's food safety authority enforces additive disclosure standards for fermented alcoholic beverages crossing the strait. Taichung's specialty beverage retailers expand shelf space for provenance-transparent indigenous fruit wine categories.
Vietnam
Ho Chi Minh City's emerging middle class generates trial demand for celebratory sparkling alternatives to imported champagne. Vietnam's Ministry of Health regulates alcohol content labeling and marketing restrictions for fermented beverages. Da Nang's hospitality sector experiments with bayberry wine pairings in coastal resort dining programs targeting regional tourists.
Bayberry Wine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiering that separates mass-market formulators from terroir-positioned artisans. The vendor base organizes around three strategic archetypes: pharmaceutical-channel specialists leveraging health claims, traditional-method preservationists emphasizing regional heritage, and scale-oriented producers optimizing for e-commerce velocity. Competitive moves concentrate on pharmacy network penetration and Charmat-method capacity installation for sparkling expressions.
Among Zhejiang-based producers, Ningxia Hong and Zhangzhou Tongyuan Wines Co., Ltd occupy positions within the terroir-specialist tier, while Jiangzhong Pharmaceutical exemplifies the pharmaceutical-channel archetype with health-positioned formulations. These entities represent contrasting strategic paths: geographic origin differentiation versus wellness-market access through non-traditional retail networks.
| Leading Market Players |
|---|
| Ningxia Hong |
| Jiangzhong Pharmaceutical |
| 12Ling |
| Zhongbo Green Technology |
| Beijing Shunxing Halewood Alcoholic Beverages |
| Shaanxi Lanhai Fruit Industry |
| Zhangzhou Tongyuan Wines Co., Ltd |
| Sanmen Xiaoxiang Bayberry Wine Co., Ltd |
| Zhejiang Goodday Food Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Zhejiang Province's bayberry cultivation clusters concentrate upstream supply for red-style expressions, channeling margin pools toward producers with captive fermentation capacity and controlled yeast strain banking. SAMR's evolving GB standards impose differential compliance costs that stratify pricing power between integrated operations and fragmented artisanal processors.
Pricing Analysis
Charmat-method sparkling production commands 40–60 day extended tank cycles versus still formats, creating vintage-to-vintage pricing gaps between effervescent and red wine tiers. Three-tier pricing structure across premium, standard, and economy levels separates Ningxia terroir-positioned expressions from mass-market Zhejiang output and value-tier tetra-pack alternatives. Price differentiation rests on certification grade for additive disclosure compliance and volume scale for per-unit cost absorption. Cost compression in economy tiers is intensifying because small-batch producers face disproportionate SAMR analytical testing burdens. Individual consumers in pharmacy channels exhibit lowest price sensitivity for health-positioned formulations, while mass retail buyers drive hardest bargain for standard-tier red wines.
Supply Chain Analysis
Single-origin procurement dependency on Zhejiang's seasonal harvest concentrates supply risk for processors lacking geographic diversification. Raw material flows draw from bayberry fruit clusters, native yeast strain repositories, and aseptic packaging materials sourced through East Asian manufacturing networks. Tariff exposure between China and Japan shapes compliance cost structures for exporters entering METI-regulated distribution. Distribution runs through specialty beverage retailers in tier-one cities, online direct-to-consumer platforms, and pharmacy networks with diverging margin retention profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across product types, distribution channels, and end-user occasions creates multiple white-space entry points. Wellness-oriented consumption in Chinese pharmacy retail and celebratory sparkling adoption in Vietnam's emerging middle class are reshaping demand concentration.
For Market Incumbents: Insulate premium positioning by deepening captive yeast strain banking and laboratory propagation infrastructure against native microbiota variability. Defend pharmacy channel access through accelerated GB standard compliance investment before SAMR disclosure mandates compress launch windows. Vertical integration into Zhejiang cultivation clusters reduces seasonal input volatility exposure. For New Entrants and Emerging Players: Pursue Charmat-method sparkling capacity installation targeting Vietnam's Ho Chi Minh City celebratory market and South Korea's Seoul gastronomic dining scene. Online sales channels offer most penetrable entry vector for provincial producers lacking retail slotting fee capital. Direct-to-consumer provenance storytelling bypasses distributor margin stacking. For Investors and Strategic Acquirers: Secondary-cycle assets sit with pharmaceutical-channel specialists holding health-claim regulatory expertise but lacking terroir marketing capability. Five-to-ten year viability hinges on dual carbon compliance infrastructure and e-commerce operational scale. Watch SAMR enforcement intensity against small-scale producers as consolidation catalyst signal.| Strategic Initiative | Industry Significance |
|---|---|
| Charmat-Method Capacity Installation | Modified tank fermentation captures Vietnamese and South Korean celebratory demand displacement from imported champagne. |
| Pharmacy Channel Expansion | Jiangzhong Pharmaceutical's health-positioned formulations demonstrate wellness-retail access competing against conventional supplements. |
| Native Yeast Strain Banking | Cryopreserved inoculum reduces vintage variation for Zhejiang and Fujian producers scaling beyond artisanal batch inconsistency. |
| Direct-to-Consumer E-Commerce Launch | Taiwanese platforms connecting Fujian producers bypass traditional importer margins and enable provenance transparency. |
| Dual Carbon Compliance Investment | Energy-efficient fermentation systems align with China's national emissions targets and reduce transport-related carbon intensity. |
Research Methodology
Operator-level perspectives from fermentation technologists, SAMR regulatory consultants, pharmacy category buyers, and specialty beverage retail merchants anchored the qualitative base. Secondary validation drew from GB standards documentation, SAMR disclosure mandate filings, East Asian customs trade data, and Nielsen retail audit coverage of indigenous fruit wine shelf space. Bottom-up volume modeling from provincial production clusters triangulated against top-down demand estimation across channel archetypes.
Scenario-bracketing around SAMR enforcement intensity and dual carbon compliance timelines shaped projections across the analysis window. Segmentation dimensions modeled include product type fermentation style, distribution channel margin structure, end-user occasion type, and packaging format logistics economics. CAGRs derived from vintage production cycle analysis and channel velocity differential between retail and online throughput. Forecast inputs incorporated Zhejiang harvest concentration risk and Charmat-method capacity installation pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pharmaceutical-channel specialists into terroir positioning or sparkling producers into pharmacy networks would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Moonshine Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Beer Filter System Market
Alcoholic Beverages
Cocktail Market
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
Wine Destemmer Market
Alcoholic Beverages
Pinot Meunier Market
Alcoholic Beverages
Beer Cans Market
Alcoholic Beverages
Pisco Market
Alcoholic Beverages
Cannabis Beverages Market
Alcoholic Beverages
Brewing Enzymes Market
Alcoholic Beverages
F-Style Jugs Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market