
 Mezcal Market | 2026-2036
Mezcal Market Size, Share, and Industry Trends Forecast 2026-2036
Mezcal Market Analysis
Multi-source agave procurement is expanding across the mezcal value chain as producers diversify beyond single-estate supply. Campari Group leverages long-term grower contracts to secure Espadin volumes. William Grant & Sons anchors its position through direct investment in Oaxaca palenques. Diageo PLC differentiates via certified-sustainable sourcing programs that trace agave from field to bottle.
Mezcal denotes a distilled agave spirit produced under Denominación de Origen protection, requiring cooking in earthen pits, crushing with stone tahona or mechanical mills, and double distillation in copper or clay stills to achieve 36-55% alcohol by volume. Joven expressions dominate export volumes due to shorter production cycles and lower price points, while Reposado and Añejo segments command disproportionate margin pools through oak-aging premiums and limited releases. Espadin agave supplies the bulk of commercial output, though Tobalá and Madrecuixe variants attract connoisseur segments willing to pay scarcity premiums.
Mexico's Secretaría de Economía enforces NOM-070-SCFI standards that govern agave species eligibility, geographic boundaries, and labeling integrity for export-bound mezcal. The United States Alcohol and Tobacco Tax and Trade Bureau (TTB) classifies mezcal under distinct federal standards of identity, creating compliance complexity for cross-border shipments. Stakeholders must monitor how evolving sustainability certifications and carbon-footprint disclosure requirements reshape premium positioning and retail access.
Market Dynamics
Wild agave maturation cycles stretching 7-35 years are compressing available biomass just as NOM-070-SCFI certification requirements tighten production eligibility. This supply-demand asymmetry is forcing producers toward multi-species cultivation contracts and certified-sustainable sourcing programs to secure volume.
Growth Catalysts
- NOM-070-SCFI Certification Expansion:Mexico's updated Denominación de Origen standards are elevating export legitimacy by mandating geographic traceability and traditional production methods. US craft cocktail bars now specify certified mezcal on premium menus.
- Espadin Cultivation Scaling:Commercial nurseries in Oaxaca's central valleys are expanding clonal propagation to shorten replacement cycles. This domesticates supply for Joven expressions dominating North American export volumes.
- Palenque Modernization:Stone tahona crushing and copper still distillation are being preserved through equipment subsidies tied to heritage certification. Traditional producers gain access to premium pricing tiers.
Market Restraints
- Wild Tobalá Scarcity:Mature specimens require 15-25 years to reach harvestable sugar concentration. Foraging pressure in Oaxaca's Sierra Madre highlands is depleting wild populations faster than natural regeneration permits.
- Agave Price Volatility:Espadin piña costs fluctuate with rainfall patterns across southern Mexico. Drought cycles in Puebla and Guerrero transmit directly to palenque input costs.
- TTB Classification Friction:The United States Alcohol and Tobacco Tax and Trade Bureau maintains distinct standards of identity from Mexican NOM requirements. Cross-border compliance adds documentation burden and shipment delays.
Strategic Opportunities
- Durango and Guanajuato Expansion:New Denominación de Origen territories opened under NOM-070-SCFI amendments are attracting distillery investment. These regions offer untapped wild agave populations and lower land costs than saturated Oaxaca valleys.
- Direct-to-Consumer E-Commerce:US state-level shipping law liberalization is enabling producer-owned channels. Palenques bypass three-tier distribution to capture margin and build brand equity.
- Carbon Footprint Certification:Emerging sustainability disclosure requirements in California and EU markets favor producers with verified low-emission production. Earthen pit cooking with renewable biomass qualifies for preferential retail placement.
Industry Challenges
- Maestro Mezcalero Succession:Traditional knowledge of fire management in underground ovens and cut-point judgment for agave harvest is concentrated among aging practitioners. Formal apprenticeship programs remain underdeveloped.
- Batch-to-Batch Variability:Wild fermentation with native yeasts produces inconsistent flavor profiles. Scale-oriented buyers demand standardization that conflicts with artisanal production norms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mezcal Market |
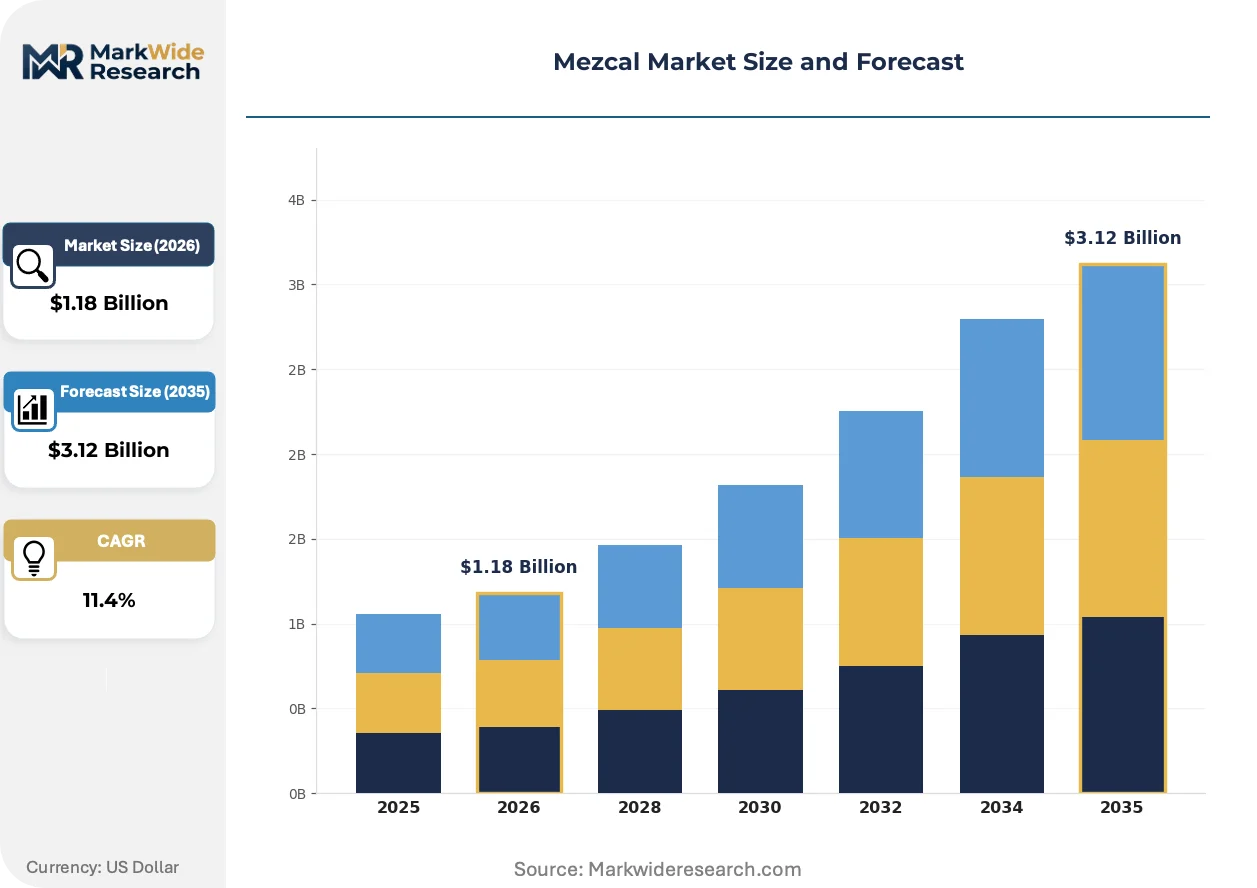
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $3.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Joven, Reposado, Añejo, Extra Añejo Agave Type: Espadin, Tobalá, Madrecuixe, Tepeztate Alcohol Content: Oro, Plata, 40%, 50% Packaging Type: Glass Bottle, PET Bottle, Can, Tetra Pack |
| Companies Covered | Campari Group, William Grant & Sons, Pernod Ricard, Compania Tequilera de Arandas, Constellation Brands, Diageo PLC, Bacardi Limited, Mezcal Vago, Proximo Spirits, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mezcal Market Emerging Trajectories
Production technology is bifurcating between heritage-method preservation and efficiency-driven modernization. This tension is reshaping capital allocation across the value chain while regulatory authorities on both sides of the border tighten compliance frameworks.
Mechanical shredders paired with traditional earthen pit roasting is modularizing the crushing stage for mid-volume producers. Palenques serving export markets adopt hybrid configurations to maintain NOM-070-SCFI eligibility while expanding throughput. Equipment suppliers now offer retrofit kits that preserve tahona optionality for premium batches.
Mexico's Secretaría de Economía is enforcing stricter agave species eligibility lists under revised NOM-070-SCFI annexes. Industrial consequence limits wild-harvested Tobalá and Madrecuixe volumes eligible for certified export. Connoisseur segment producers are responding with estate-cultivated rare species programs to maintain product availability.
Certification-driven preference shifts are restructuring on-premise procurement. US craft cocktail bars now require NOM-070-SCFI documentation and sustainability attestations for back-bar placement. This behavior concentrates volume with compliant producers while squeezing informal supply out of premium channels.
Mezcal Market Segmentation
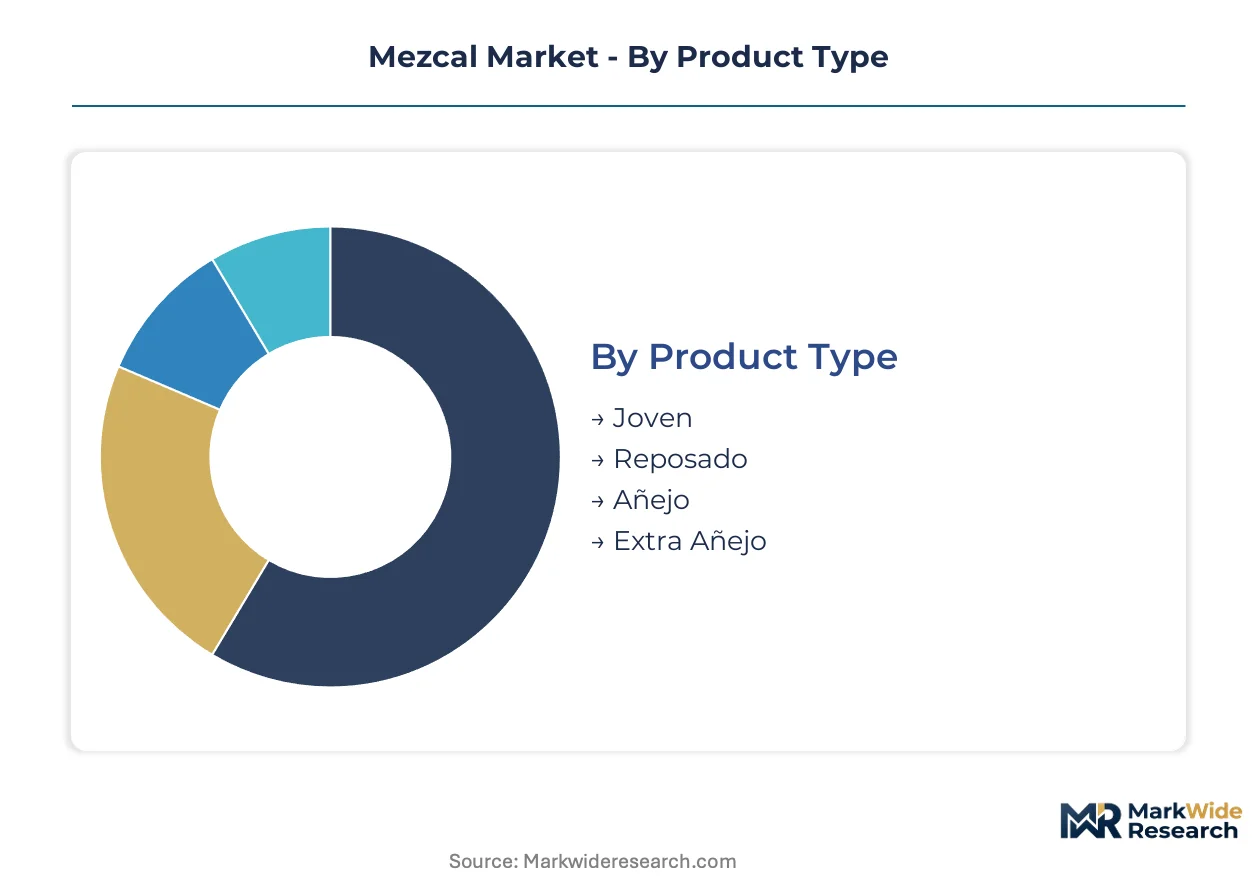
Mezcal segmentation reflects the tension between heritage production economics and export market scalability. Each dimension—product aging, agave species, alcohol grade, and packaging format—carries distinct capital requirements and margin profiles that determine producer strategy.
Product Type:
Capital intensity peaks with oak-aged expressions requiring multi-year inventory carrying costs and climate-controlled warehouse investment.
- Joven:Unaged spirit bottled immediately after distillation preserves the raw smoke and agave character of earthen pit cooking. Demand concentrates in US craft cocktail bars where mixologists prize its mixability and lower price point for high-volume serves. Shorter production cycles free working capital for palenque expansion.
- Reposado:Two-to-twelve month oak rest develops vanilla and caramel notes that bridge traditional mezcal profile with bourbon-drinking converts. Premium on-premise accounts in Texas and California specify Reposado for sipping menus. Barrel programs require sustained investment in American and French oak inventory.
- Añejo:Minimum one-year oak aging demands extended capital lockup and evaporative loss management.
- Extra Añejo:Three-plus year maturation represents the highest fixed-asset commitment in the category.
Most installed capacity flows through Joven. Expansion is steepest in Reposado.
Agave Type:
Field-to-bottle timelines vary dramatically by species, determining which segments attract plantation investment versus wild-foraging dependence.
- Espadin:Cultivated variety maturing in seven to ten years dominates commercial volume through predictable harvest scheduling. Clonal propagation programs in Oaxaca's central valleys supply consistent piña throughput for certified export production. Irrigation infrastructure and nursery operations concentrate grower investment here.
- Tobalá:Wild-harvested mountain agave requiring fifteen to twenty-five years develops concentrated sugars that command scarcity premiums in connoisseur channels. Estate cultivation experiments in San Luis Potosí seek to domestic supply as Sierra Madre foraging restrictions tighten under NOM-070-SCFI enforcement.
- Madrecuixe:Tall wild species with extended maturation cycles limits commercial scalability.
- Tepeztate:Decades-long wild growth period restricts output to ultra-premium limited releases.
Espadin carries the bulk of fermentation tank throughput. Tobalá gains share fastest in direct-to-consumer channels.
Alcohol Content:
Proof determination at distillation cutoff shapes excise tax liability and regional market access.
- Oro:Gold-hued expression incorporating minimal additives occupies entry-price positioning in Mexican domestic trade.
- Plata:Clear unaltered spirit represents the purity standard for export certification.
- 40%:Standardized bottling strength aligns with US TTB import requirements and mainstream retail distribution.
- 50%:Higher-proof traditional bottling appeals to enthusiast segments seeking unmasked agave intensity.
40% strength commands the largest bottling line allocation. 50% proof expressions climb fastest in specialty retail.
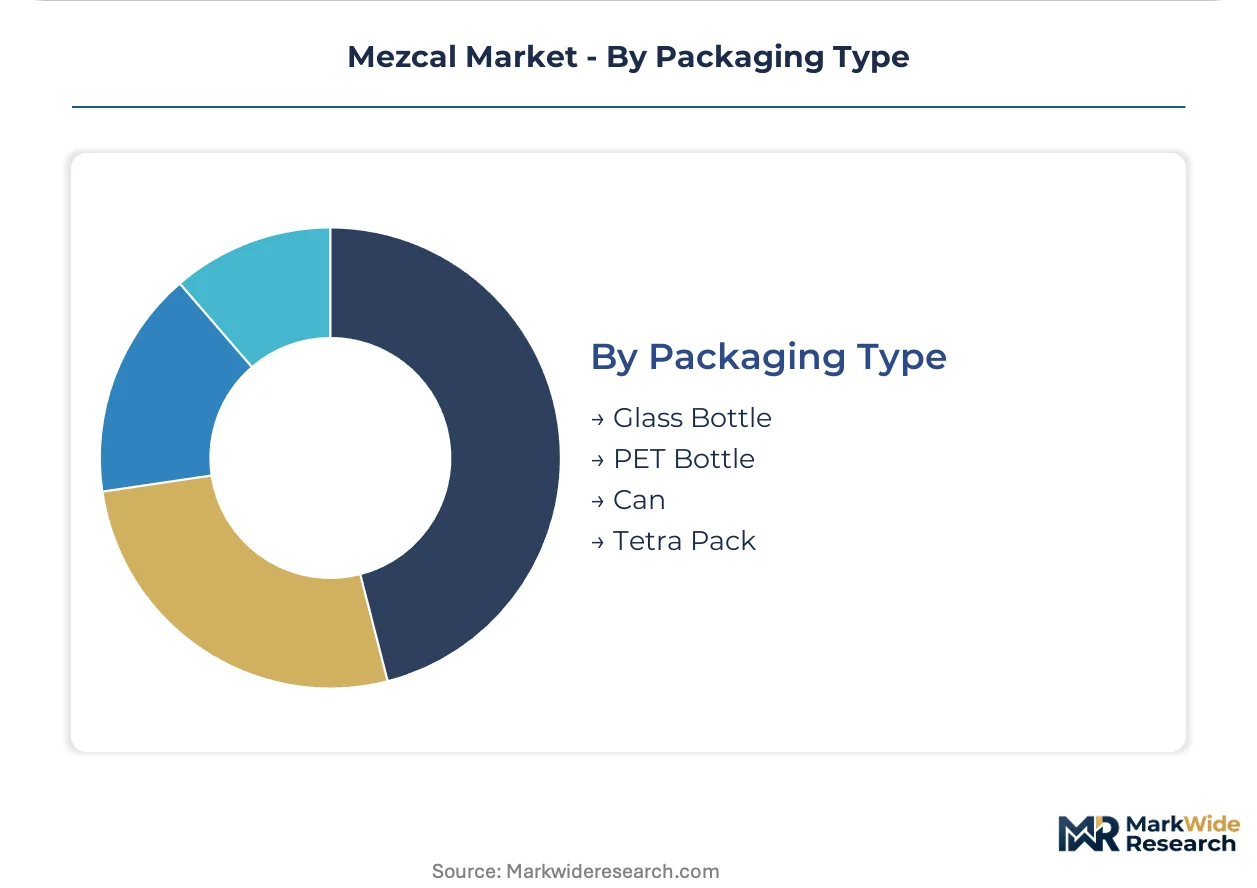
Packaging Type:
Material selection balances premium perception, shipping economics, and sustainability credentialing for target channels.
- Glass Bottle:Heavyweight and artisan-etched formats signal authenticity for back-bar placement and gift occasions. Mexican glassworks in Monterrey supply heritage producers with recycled-content options that satisfy California and EU sustainability disclosure requirements. Decoration complexity drives per-unit cost variation.
- PET Bottle:Lightweight unbreakable format enables outdoor event and travel retail penetration where glass prohibitions apply.
- Can:Single-serve aluminum format targets ready-to-drink cocktail premix expansion.
- Tetra Pack:Aseptic carton technology offers minimal environmental footprint for bulk hospitality formats.
Glass dominates filling line investment. Can format expands most quickly in convenience retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting mezcal investment toward jurisdictions with lower certification compliance costs and untapped agave biomass. Producers are migrating from saturated Oaxaca valleys to emerging Denominación de Origen territories where land and labor inputs carry less premium.
United States
TTB import classification standards create documentation friction that favors large distributors with compliance infrastructure. California's carbon-footprint disclosure requirements are reshaping retail procurement toward certified-sustainable producers. New York City's craft cocktail density concentrates back-bar specification power in Manhattan and Brooklyn accounts.
Mexico
Secretaría de Economía enforcement of NOM-070-SCFI standards is elevating export legitimacy through mandatory geographic traceability. Oaxaca's central valleys remain the production core, though Durango and Guanajuato are attracting palenque investment under expanded Denominación de Origen boundaries. Mexico City Metro anchors domestic premium consumption and distribution logistics.
Canada
Provincial liquor board monopolies structure import access through centralized procurement tenders that favor established suppliers with volume guarantees. British Columbia's sustainability credentialing requirements align with emerging carbon-footprint certification trends. Toronto's on-premise mixology scene drives specialty retail demand in Ontario.
United Kingdom
HMRC excise classification for agave spirits creates tariff positioning distinct from tequila, enabling premium pricing strategies. London's bar sector specification power concentrates in Shoreditch and Soho accounts with agave-focused programs. Manchester and Glasgow are developing secondary market density through independent retail expansion.
Germany
Bundesministerium der Finanzen import regulations govern spirits labeling integrity for agave products entering EU distribution. Berlin's craft cocktail development lags southern European markets but shows acceleration in Kreuzberg and Neukölln precincts. Hamburg's port infrastructure anchors bulk logistics for northern European re-export.
Mezcal Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue heritage-method differentiation and direct-to-consumer channel control. The vendor base stratifies across multinational spirits conglomerates with portfolio diversification strategies and independent palenques with single-origin positioning. Three archetypes dominate: scale-driven distributors with compliance infrastructure, heritage-certified artisans with scarcity-premium access, and hybrid operators blending traditional production with modern throughput. Competitive moves concentrate on Denominación de Origen territory expansion and certified-sustainable sourcing program development.
Among multinational spirits conglomerates, Campari Group, Diageo PLC, and William Grant & Sons occupy positions defined by long-term grower contracting and direct production investment. These entities exemplify the scale-tier archetype through compliance infrastructure and cross-border distribution reach. Independent specialists including Mezcal Vago represent heritage-method positioning with maestro mezcalero relationships and limited-batch scarcity premiums. Constellation Brands and Pernod Ricard sit within portfolio diversification strategies that treat mezcal as geographic expansion within broader agave spirits allocation.
| Leading Market Players |
|---|
| Campari Group |
| William Grant & Sons |
| Pernod Ricard |
| Compania Tequilera de Arandas |
| Constellation Brands |
| Diageo PLC |
| Bacardi Limited |
| Mezcal Vago |
| Proximo Spirits |
| Others |
Supply Flow & Price Mechanics
Backward integration into agave cultivation anchors both supply security and margin capture for palenque operators navigating NOM-070-SCFI compliance costs. Campari Group's long-term grower contracts and William Grant & Sons' direct Oaxaca palenque investments exemplify how upstream control converts volatile piña costs into predictable input pricing.
Pricing Analysis
Distributor margin layers absorb the steepest markup between palenque gate and US back-bar placement. Three-tier pricing structure across heritage-certified, standard-export, and informal domestic levels separates NOM-070-SCFI documentation premiums from commodity Espadin volumes. Pricing pressure stems from drought-driven agave cost spikes in Puebla and Guerrero. US craft cocktail bars show lowest price sensitivity for certified Tobalá expressions; Mexican domestic trade exhibits highest elasticity.
Supply Chain Analysis
Maestro mezcalero availability constraints in Oaxaca's central valleys limit production scaling regardless of equipment investment. Geographic supply concentrates in Mexico, with emerging capacity in Durango and Guanajuato under expanded Denominación de Origen boundaries. Raw material dependencies center on Espadin piña, American and French oak barrels, and copper still fabrication. Single-source vulnerability runs through wild Tobalá foraging restrictions. Distribution runs through three-tier US systems, though direct-to-consumer e-commerce channels bypass traditional markup layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mezcal market compounds steadily as premium spirits adoption in North American craft cocktail bars creates durable demand expansion. NOM-070-SCFI certification requirements erect regulatory moats that favor compliant incumbents.
For Market Incumbents: Deploy heritage certification investment as the primary defensive lever. Lock in multi-year Espadin supply contracts before drought cycles intensify price volatility. Acquire distressed palenques in Durango and Guanajuato to secure expanded Denominación de Origen capacity ahead of competitor migration.
For New Entrants and Emerging Players: US state-level direct-to-consumer shipping liberalization offers underserved enthusiast buyers bypassing three-tier markups. Carbon-footprint certification gaps in California retail procurement present the most penetrable positioning angle. Lead with estate-cultivated rare agave programs to differentiate from depleted wild-foraging supply.
For Investors and Strategic Acquirers: Consolidation pressure builds where maestro mezcalero knowledge concentrates among aging practitioners without formal succession pipelines. Five-to-ten year viability favors hybrid operators blending traditional production credibility with modern throughput scalability. Watch NOM-070-SCFI enforcement intensity in wild agave harvesting restrictions as the key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Certification Investment | NOM-070-SCFI compliance unlocks US craft cocktail bar back-bar placement and premium pricing tiers. |
| Multi-Species Cultivation Contracts | Espadin cloning programs in Oaxaca's central valleys domestic supply for Joven export volume security. |
| Direct-to-Consumer Channel Buildout | Producer-owned e-commerce captures distributor margin and builds brand equity in enthusiast segments. |
| Carbon Footprint Certification | California and EU sustainability disclosure requirements favor earthen pit cooking with renewable biomass. |
| Maestro Mezcalero Apprenticeship Programs | Formal knowledge transfer addresses succession risk in fire management and agave cut-point judgment. |
Methodological Framework
Direct dialogue with palenque operators, agave nursery managers, US craft cocktail bar buyers, Mexican Secretaría de Economía officials, and TTB compliance specialists grounded qualitative findings in operational reality. Secondary validation drew from NOM-070-SCFI regulatory filings, US TTB import classification databases, Oaxaca agricultural census data, and California carbon-footprint disclosure requirements. Bottom-up volume estimates from individual palenque capacity triangulated against top-down category spending flows.
Segment-level projections across product aging tiers, agave species, and packaging formats informed value calculations over the projection horizon. CAGRs emerged from regression analysis against historical volume trajectories and premium spirits adoption elasticities. Modeled inputs included Espadin cultivation cycle timelines, oak barrel inventory carrying costs, and state-level US shipping law liberalization schedules.
Underlying measurement precision varies by segment; Joven volume estimates carry tighter precision than ultra-premium Extra Añejo limited releases. Forecasts reflect assumptions about NOM-070-SCFI enforcement continuity, TTB classification stability, and wild agave population regeneration rates. Material deviation in drought frequency or Denominación de Origen boundary expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
France Alcohol E-Commerce Market
Alcoholic Beverages
East Africa Alcoholic Beverages Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Global Premium Alcoholic Beverage Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Kegs Market
Alcoholic Beverages
Global Spiced/Flavored Rum Market
Alcoholic Beverages
Commercial Wine Dispenser Market