
 Sake Market | 2026-2036
Sake Market Size, Share, and Industry Trends Forecast 2026-2036
Sake Market Intelligence
Japanese brewer capacity is decoupling from domestic consumption trends as export-oriented production lines expand. Takara Holdings leverages its biotechnology heritage to sustain consistent flavor profiles across international batches. Gekkeikan Sake anchors volume through established distribution in North American retail channels. Hakkaisan Brewery differentiates via mountain-spring water sourcing and cold-climate brewing conditions.
Sake denotes a fermented alcoholic beverage brewed from polished rice, water, koji mold, and yeast, with rice polishing ratio directly determining classification grade and flavor intensity. The beverage serves ceremonial, culinary-pairing, and premium spirits functions across on-trade and off-trade channels. Junmai and Ginjo categories command margin concentration due to ingredient purity requirements and aging protocols. Daiginjo occupies the ultra-premium tier where 50% or lower polishing ratios justify price multiples over standard grades. Nigori, with its coagulated rice sediment, competes in accessible entry-level positioning for new consumer conversion.
Japan's National Tax Agency governs geographic indication and labeling standards, while the FDA and TTB regulate import safety and alcohol taxation in the United States. These frameworks shape product formulation, certification costs, and channel access for export-focused brewers. Stakeholders must monitor evolving tariff structures and bilateral trade agreements that could reconfigure competitive access across priority export corridors.
Market Dynamics
Export-oriented production lines are decoupling from Japan's shrinking domestic consumption, creating a bifurcated supply structure where overseas capacity expansion runs parallel to domestic brewery consolidation. This geographic rebalancing is redirecting capital toward North American and European distribution infrastructure.
Growth Catalysts
- Geographic Indication Tightening:Japan's National Tax Agency revised labeling standards to strengthen provenance verification, elevating consumer trust in authentic Japanese sake and compressing counterfeit supply.
- Craft Brewery Infrastructure:United States importer-distributors are building dedicated education platforms, converting wine and spirits buyers through sommelier certification programs and tasting events.
- Premium Dining Integration:North American fine-dining establishments are expanding sake programs beyond Japanese cuisine, creating new pairing occasions with French and New American menus.
Market Restraints
- Rice Input Concentration:Yamada Nishiki and other brewing-grade rice varieties concentrate cultivation in Hyogo Prefecture, exposing supply to climate volatility and single-origin risk.
- TTB Certification Friction:United States Alcohol and Tobacco Tax and Trade Bureau labeling requirements create six-to-twelve-month approval timelines for new product introductions.
- Wine and Spirits Substitution:Premium white wines and low-ABV cocktails compete directly for culinary-pairing occasions in North American on-trade channels.
Strategic Opportunities
- United States Regional Expansion:Underpenetrated Midwest and Southeast markets lack dedicated sake distribution, creating first-mover advantage for localized cold-chain logistics investment.
- Ready-to-Drink Formats:Canned sake and single-serve packaging align with convenience retail and outdoor recreation channels, diverging from traditional 720ml bottle conventions.
- Carbon-Neutral Brewing:Japan's METI green transition incentives reward renewable energy adoption and water recycling, qualifying export products for EU CSRD-aligned procurement preferences.
Industry Challenges
- Toji Skill Succession:Master brewer apprenticeship programs face enrollment declines, compressing the pipeline for traditional multiple parallel fermentation expertise.
- Cold-Chain Capex Burden:Temperature-controlled shipping from Japan to North American ports requires dedicated reefer investment, elevating working capital requirements for mid-scale exporters.
- Organic Certification Complexity:JAS organic standards diverge from USDA National Organic Program requirements, forcing dual-track compliance for premium positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sake Market |
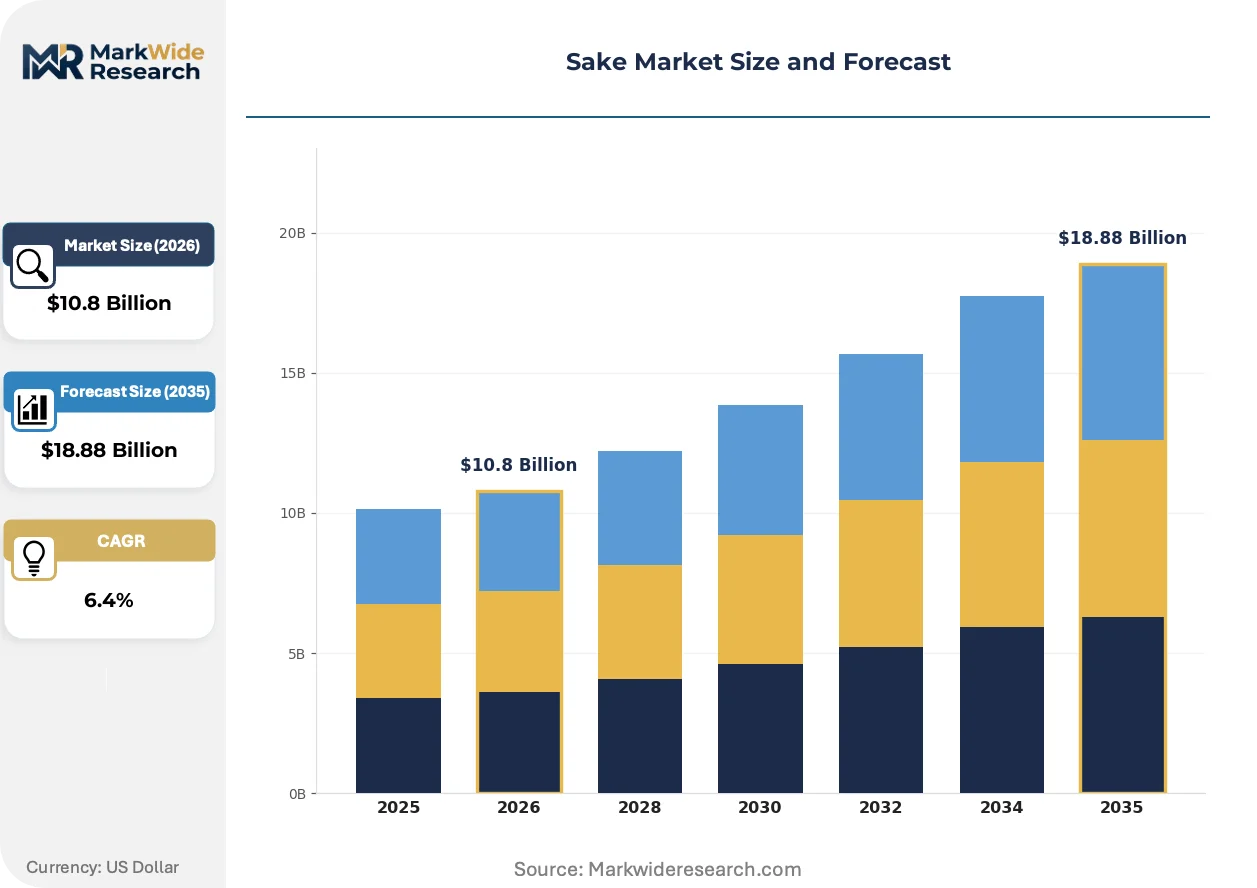
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Junmai, Honjozo, Ginjo, Daiginjo, Nigori Rice Polishing Ratio: 70%, 60%, 50%, 40%, 30% Flavor Profile: Sweet, Dry, Fruity, Umami, Earthy Packaging Format: Bottle, Can, Box, Pouch, Keg |
| Companies Covered | Takara Holdings, Nihon Sakari, Hakutsuru Sake Brewing, SakeOne, Tatsuuma-Honke Brewing, Gekkeikan Sake, Ozeki Sake, Hakkaisan Brewery, Asahi Shuzo (Dassai), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sake Market Strategic Shifts & Innovations
Precision fermentation controls and alternative rice polishing methods are compressing traditional brewing timelines while preserving quality markers. These technical advances intersect with regulatory modernization and shifting channel preferences to reshape competitive access.
Automated koji propagation systems are expanding into mid-scale breweries, enabling consistent enzymatic conversion without toji-level manual intervention. North American craft sake producers adopt these systems fastest, compressing skill barriers and accelerating batch consistency. This technology is expanding into volume-tier production previously reserved for heritage houses.
Japan's National Tax Agency implemented revised geographic indication enforcement protocols in 2023, mandating blockchain-verified supply chain documentation for export certification. Brewers must now submit rice provenance records and water source testing to qualify for "Japanese Sake" protected designation. Small-to-mid-scale exporters face disproportionate compliance burden, consolidating advantage toward integrated producers with in-house laboratory capabilities.
Sommelier-driven certification programs are displacing informal consumer education in United States on-trade channels. Restaurant buyers now prioritize staff-trained establishments, shifting volume toward distributors with embedded training infrastructure. This preference concentration is most visible in California and New York metropolitan markets, where sake-by-the-glass penetration in non-Japanese restaurants has doubled.
Sake Market Segmentation
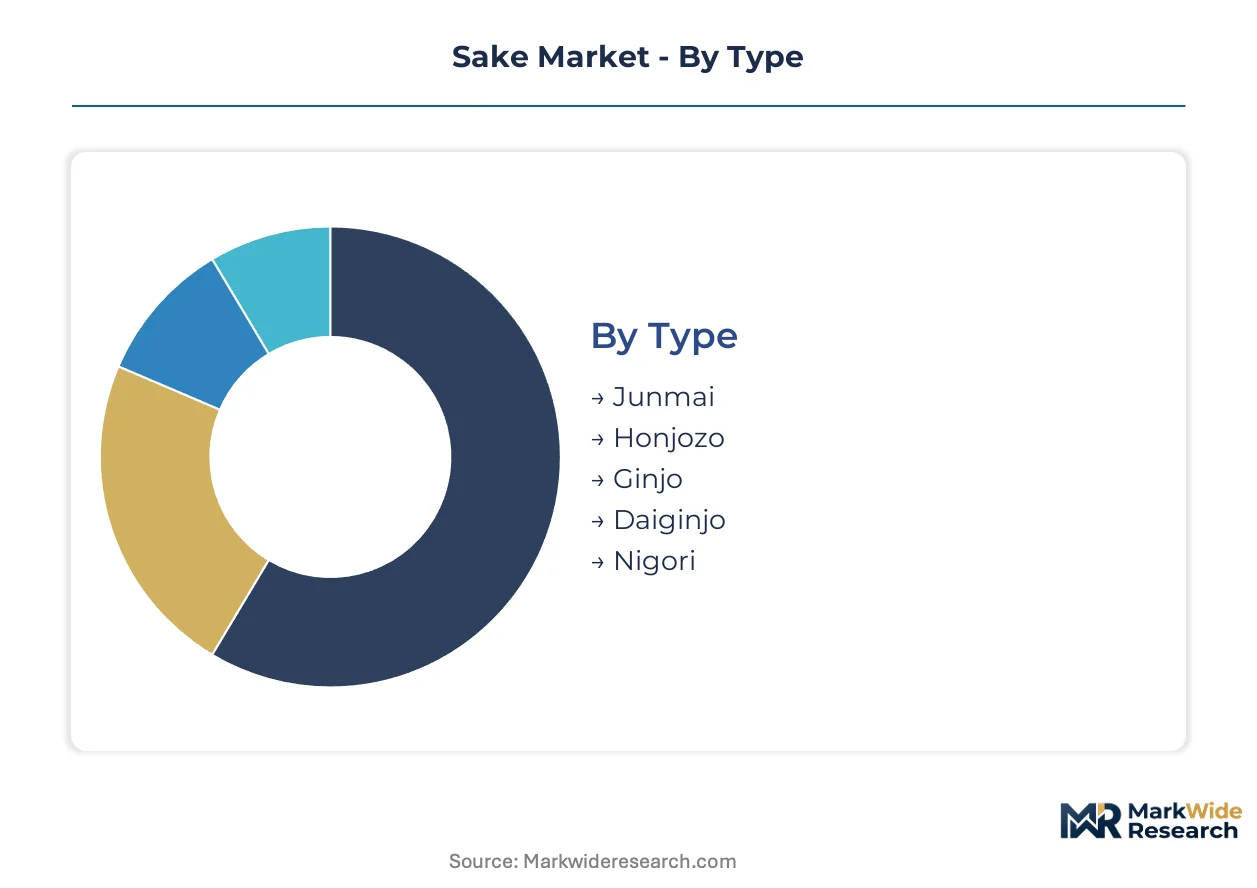
Sake classification systems directly govern pricing architecture and channel access. Rice polishing ratios and brewing methods create tiered quality signals that distributors leverage for margin management across on-trade and off-trade environments.
Type:
Volume concentrates in mid-tier classifications while premium positioning accelerates in export corridors.
- Junmai:Pure rice sake brewed without added distilled alcohol, delivering fuller body and pronounced rice character. United States retail channels favor Junmai for entry-level consumer conversion, constrained by limited cold-chain infrastructure in secondary markets.
- Daiginjo:Ultra-premium classification requiring 50% or lower rice polishing ratio, yielding highly aromatic, delicate profiles. Fine-dining establishments in California and New York metropolitan areas anchor demand, driven by sommelier certification programs that validate premium positioning.
- Honjozo:Small amount of distilled alcohol added to lighten texture and enhance aroma. Standard-tier positioning serves casual dining and retail shelf-stable segments.
- Ginjo:Polished to 60% or less, fermented at colder temperatures for refined fruit-forward notes. Mid-premium tier bridges accessibility and quality signaling.
- Nigori:Coarsely filtered with visible rice sediment, offering creamy sweetness and lower clarity. Outdoor recreation and convenience retail channels in the United States favor canned Nigori formats for casual consumption occasions.
Today's leader: Junmai. Tomorrow's challenger: Daiginjo.
Rice Polishing Ratio:
Polishing intensity correlates directly with ingredient input costs and aging protocol complexity.
- 50%:Threshold for Daiginjo classification, removing half the outer rice grain to isolate starchy core. Premium on-trade accounts in the United States concentrate procurement here, balancing exclusivity with manageable price points for by-the-glass programs.
- 70%:Baseline for standard sake, retaining more protein and fat content for robust flavor. Volume production for domestic Japanese consumption and export commodity tiers.
- 60%:Ginjo-grade specification enabling cleaner fermentation with reduced off-flavors. Mid-scale export breweries optimize here for margin efficiency.
- 40%:Advanced Daiginjo tier demanding extended brewing timelines and precise temperature control. Ultra-premium collector markets in select United States coastal cities.
- 30%:Extreme polishing reserved for competition-grade and ceremonial releases. Limited commercial scale due to rice waste ratios exceeding 70%.
50% polishing anchors current export value. 40% specifications are climbing the fastest among new product introductions.
Flavor Profile:
Consumer palate evolution in Western markets is displacing traditional dryness preferences.
- Fruity:Estery profiles with pronounced apple, melon, or tropical notes. Ginjo and Daiginjo brewing methods emphasize these characteristics. United States millennial and Gen-Z demographics drive expansion here, particularly in canned RTD formats.
- Dry:Low residual sugar with crisp finish, historically dominant in Japanese domestic consumption. Aging demographic preference constrains growth velocity in export markets.
- Sweet:Higher residual sugar content, often associated with Nigori or lower-alcohol styles. Dessert pairing applications in North American fine dining.
- Umami:Savory depth from amino acids developed during koji propagation. Culinary integration with non-Japanese cuisines creates niche demand.
- Earthy:Mineral and fungal notes from traditional yeast strains and water chemistry. Limited commercial penetration outside specialist retail.
Fruity profiles command current innovation investment. Umami positioning represents the emerging challenger for culinary crossover applications.
Packaging Format:
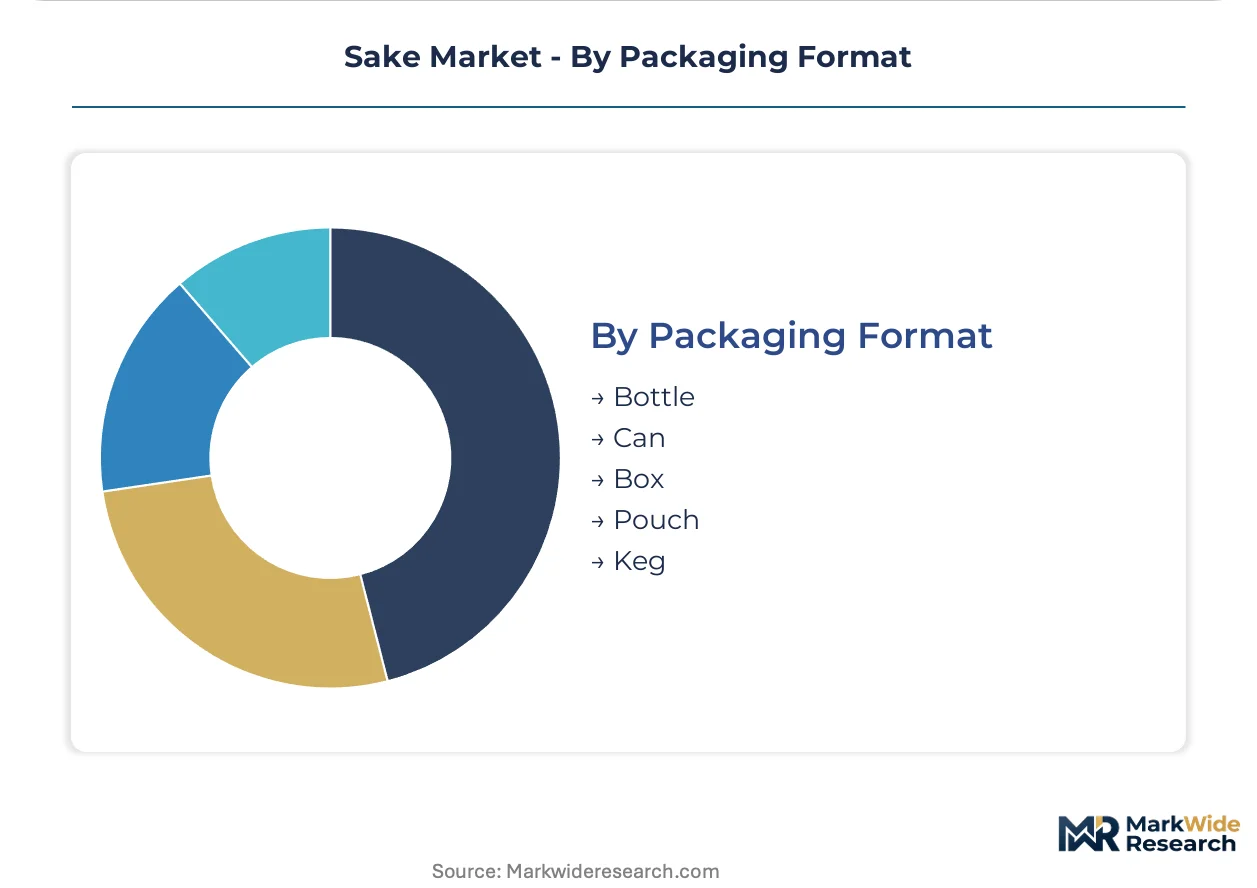
Format selection determines channel eligibility and margin capture mechanics.
- Bottle:Dominant format at 720ml and 1.8L volumes, preserving optimal light protection and temperature stability. Heritage breweries and premium importers rely on glass for provenance signaling, though shipping weight elevates landed costs for trans-Pacific distribution.
- Can:Single-serve aluminum formats gaining traction in United States convenience retail and outdoor recreation channels. Domestic craft sake producers in California and Oregon adopt canning lines fastest, bypassing traditional import cold-chain constraints.
- Box:Bag-in-box configurations for volume on-trade accounts, reducing per-serving cost and extending post-open shelf life.
- Pouch:Flexible packaging for travel retail and airline catering, minimizing weight and breakage risk.
- Keg:Stainless steel draft systems for high-volume restaurant and bar accounts, enabling sake-on-tap programs with reduced packaging waste.
Bottle formats defend incumbent position. Cans are expanding most quickly among format innovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting sake production capacity toward export corridors where compliance costs align with premium positioning. Japan's National Tax Agency labeling reforms have elevated authentication burdens that favor integrated producers with in-house laboratory capabilities, compressing marginal operations and consolidating geographic advantage.
United States
California and New York metropolitan markets anchor North American demand through sommelier certification programs and fine-dining integration. The Alcohol and Tobacco Tax and Trade Bureau maintains six-to-twelve-month approval timelines for new product introductions, creating friction for Japanese exporters. Pacific Northwest craft sake producers in Oregon and Washington are expanding canning capacity for outdoor recreation channels.
Japan
Domestic consumption contraction is accelerating brewery consolidation in Hyogo Prefecture and Niigata Prefecture, the historic heartland of Yamada Nishiki cultivation. The National Tax Agency's 2023 blockchain-verified supply chain documentation mandate for geographic indication is compressing counterfeit supply. Kobe and Kyoto clusters concentrate heritage production capacity while Tokyo-based exporters build dedicated North American distribution infrastructure.
China
Coastal metropolitan demand in Shanghai and Shenzhen is expanding for ceremonial and gift-market applications, though wine and baijiu substitution constrains velocity. The country's national quality regulator enforces divergent labeling standards that complicate Japanese import authentication. Yangtze River Delta logistics hubs are developing temperature-controlled warehousing for premium beverage distribution.
Germany
Berlin and Munich on-trade channels are integrating sake programs into European fine-dining frameworks, driven by sommelier education expansion. EU CSRD-aligned procurement preferences under the EU Green Deal are rewarding carbon-neutral brewing certifications. Hamburg port infrastructure is upgrading reefer capacity for Japanese cold-chain imports.
United Kingdom
London's restaurant sector is displacing informal consumer education with staff-trained sake service, doubling by-the-glass penetration in non-Japanese establishments. The Food Standards Agency coordinates with Japanese regulators on mutual recognition agreements for brewing-grade rice imports. Southeast England distribution clusters are investing in localized cold-chain logistics for premium positioning.
Sake Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue craft positioning and alternative format innovation. The market structures around heritage Japanese houses with integrated distribution, mid-scale regional specialists, and North American craft challengers. Strategic archetypes include biotechnology-leveraged consistency players, mountain-spring water differentiated specialists, and domestic canning-focused format innovators. Competitive moves concentrate on capacity expansion in export-oriented production lines and strategic partnerships with importer-distributors embedding education infrastructure.
Within the heritage house tier, Takara Holdings and Gekkeikan Sake occupy positions representing biotechnology-anchored consistency and volume retail distribution respectively. Hakkaisan Brewery exemplifies the terroir-differentiated specialist archetype through its mountain-spring water sourcing. Among North American craft entrants, SakeOne represents the domestic production model bypassing trans-Pacific cold-chain constraints.
| Leading Market Players |
|---|
| Takara Holdings |
| Nihon Sakari |
| Hakutsuru Sake Brewing |
| SakeOne |
| Tatsuuma-Honke Brewing |
| Gekkeikan Sake |
| Ozeki Sake |
| Hakkaisan Brewery |
| Asahi Shuzo (Dassai) |
| Others |
Cost & Logistics Intelligence
Japan's METI green transition incentives gate qualified supply and premium-tier pricing access, rewarding carbon-neutral brewing certifications that qualify export products for EU CSRD-aligned procurement preferences while compressing margin structures for non-compliant producers.
Pricing Analysis
Distributor margin layers in North American channels absorb elevated cold-chain logistics costs, compressing net returns for Japanese exporters. Three-tier pricing structure across Daiginjo, Ginjo, and Junmai levels separates ultra-premium positioning from volume tiers, with rice polishing ratio and geographic indication certification as primary differentiation drivers. Pricing pressure stems from TTB certification friction extending approval timelines and elevating working capital requirements. Entry-level retail buyers exhibit highest price sensitivity, while fine-dining sommelier programs sustain inelastic demand for authenticated Daiginjo.
Supply Chain Analysis
Toji skill succession constraints in Hyogo Prefecture and Niigata Prefecture compress the pipeline for traditional multiple parallel fermentation expertise, elevating labor costs for heritage production methods. Supply concentrates in Japan, with emerging craft capacity in Oregon and Washington drawing from domestic rice cultivation. Yamada Nishiki rice, mountain-spring water, and specialized koji strains constitute critical input dependencies. Single-origin rice cultivation in Hyogo Prefecture exposes supply to climate volatility. Distribution runs through importer-distributors with embedded cold-chain infrastructure and sommelier education platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage dynamics favor export-oriented production expansion, as Japan's shrinking domestic consumption and METI green incentives create cost and regulatory differentials against North American craft entrants facing localized labor and real estate premiums.
For Market Incumbents: To counter craft brewery disruption in Pacific Northwest markets, heritage Japanese houses should deepen backward integration into Yamada Nishiki cultivation through long-term grower contracts, while expanding in-house laboratory capabilities to absorb National Tax Agency blockchain-verified documentation burdens that marginalize smaller exporters. For New Entrants and Emerging Players: Launch via canned single-serve formats targeting outdoor recreation channels in underpenetrated Midwest and Southeast United States markets, bypassing established cold-chain infrastructure requirements while leveraging sommelier certification program gaps in these regions for rapid consumer conversion. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale regional specialists with integrated distribution infrastructure because National Tax Agency compliance burdens consolidate advantage toward producers with in-house laboratory and documentation capabilities. Long-term viability hinges on export corridor positioning rather than domestic Japanese consumption. Watch for inflection in TTB approval timeline compression or bilateral trade agreement developments affecting tariff structures.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Neutral Brewing Certification | Qualifies export products for EU CSRD-aligned procurement preferences under Japan's METI green transition incentives. |
| Backward Integration into Rice Cultivation | Secures Yamada Nishiki supply against Hyogo Prefecture climate volatility and single-origin concentration risk. |
| Automated Koji Propagation Deployment | Compresses skill barriers and accelerates batch consistency for mid-scale breweries without toji-level manual intervention. |
| Regional Cold-Chain Logistics Investment | Captures first-mover advantage in underpenetrated Midwest and Southeast United States distribution corridors. |
| Sommelier Certification Program Partnership | Displaces informal consumer education and shifts volume toward distributors with embedded training infrastructure. |
Research Approach
Multiple input streams — primary interviews with toji master brewers, importer-distributor category managers, and fine-dining beverage directors; secondary validation through National Tax Agency regulatory filings, FDA and TTB import documentation, and Japan Sake and Shochu Makers Association production statistics; and customs trade data — were reconciled through bottom-up brewery capacity modeling and top-down export value triangulation.
Historical volume trajectories were cross-referenced against panel input from distributor procurement leads and sommelier program administrators. Segmentation dimensions modeled include rice polishing ratio tiers, flavor profile categories, packaging formats, and regional regulatory clusters. CAGRs were derived from production capacity expansion schedules, export shipment manifests, and channel penetration assumptions. Industry-specific forecast inputs encompass toji apprenticeship enrollment trends and reefer shipping capacity utilization rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under climate disruption affecting Hyogo Prefecture rice cultivation or abrupt TTB regulatory revision. Material deviation in bilateral trade agreement developments or National Tax Agency documentation mandate enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Beer Line Cooling System Market
Alcoholic Beverages
Asia Pacific Wine Coolers Market
Alcoholic Beverages
UK Tequila Market
Alcoholic Beverages
Beer Stabilizers Market
Alcoholic Beverages
Europe Tequila Market
Alcoholic Beverages
Europe Alcohol E-Commerce Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Beer Fermenter Market
Alcoholic Beverages
Japanese Whisky Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Malt Beverages Market
Alcoholic Beverages
Cabernet Sauvignon Market
Alcoholic Beverages
Chardonnay Market
Alcoholic Beverages
Wine Bags Market
Alcoholic Beverages
Frozen Cocktails Market