
 Orange Terpenes Market | 2026-2036
Orange Terpenes Market Size, Share, and Industry Trends Forecast 2026-2036
Orange Terpenes Market Outlook
Modular blending kits for custom fragrance formulations are repositioning how cosmetic brands and food manufacturers procure orange terpenes. Firmenich leverages captive citrus sourcing networks across multiple continents. Givaudan sustains R&D intensity in biotech-derived terpene analogs. Citrosuco anchors its position through backward integration into Brazilian orange groves and on-site distillation capacity.
Orange terpenes are volatile hydrocarbon compounds extracted from citrus peel oil, primarily comprising d-limonene in concentrations of 90-95%, with applications as natural solvents, flavor carriers, and fragrance precursors across industrial and consumer sectors. The natural product type segment dominates volume due to clean-label preferences in food and cosmetics, while high-purity grades command premium positioning in pharmaceutical applications where residual pesticide limits fall below 0.01 ppm. Pharmaceutical end users represent the fastest-expanding demand pool as inhalation therapies and transdermal delivery systems adopt terpene-based permeation enhancers.
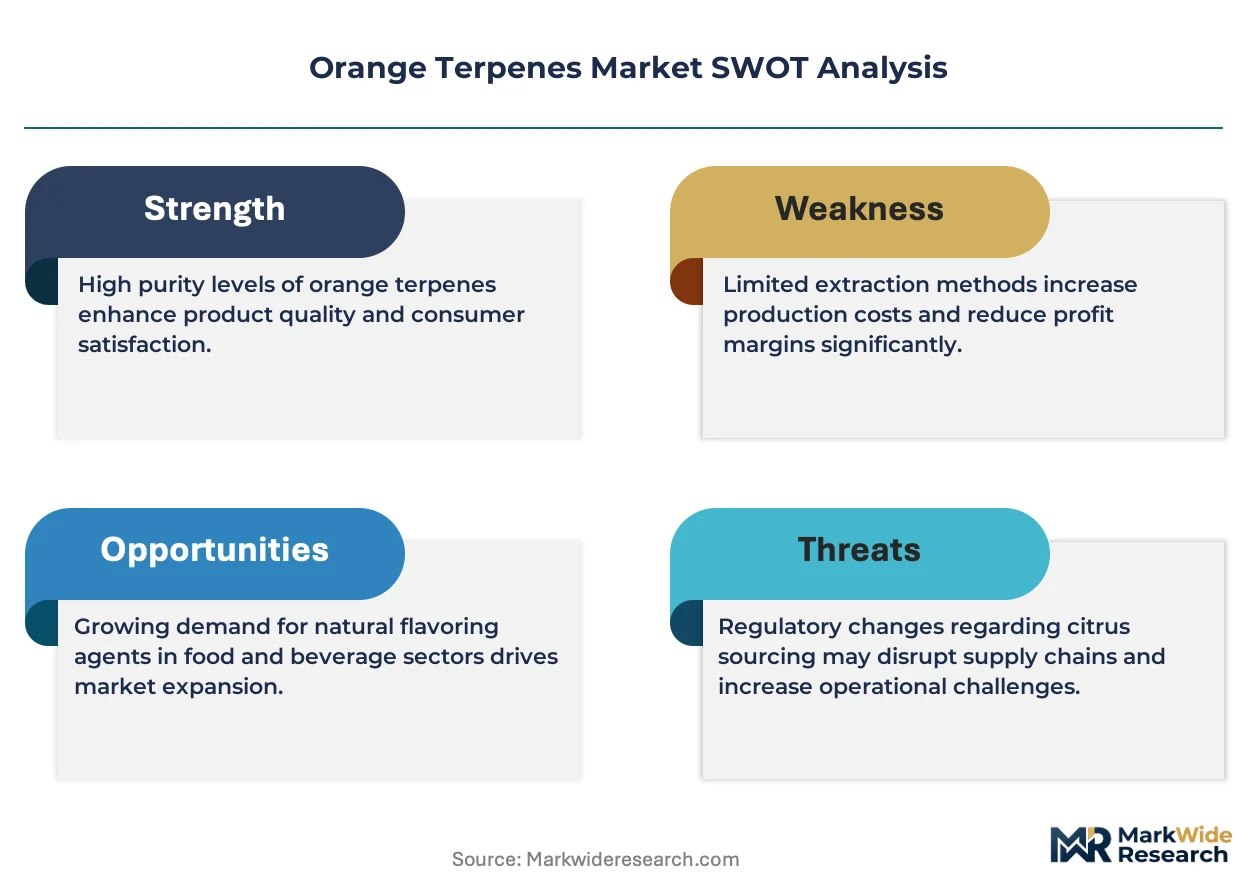
EPA regulates orange terpenes under the Federal Insecticide, Fungicide, and Rodenticide Act when marketed as antimicrobial solvents, while ECHA classifies d-limonene as a skin sensitizer under REACH, forcing reformulation in leave-on cosmetic products. FDA's Food Additive Status List governs food-grade specifications for direct addition to beverages and confections. Stakeholders must monitor evolving classification thresholds for volatile organic compounds under state-level air quality mandates and decide whether to invest in molecular distillation upgrades or pivot toward synthetic bio-identical alternatives.
Market Dynamics
REACH and F-Gas Regulation in Europe are tightening volatile organic compound limits for fragrance applications, forcing reformulation investments and molecular distillation upgrades across the supply base.
Growth Catalysts
- Clean-label food mandates:FSSAI in India and FDA in the US are driving natural solvent substitution in beverage and confectionery processing.
- Inhalation therapy expansion:Pharmaceutical formulators are adopting d-limonene as a permeation enhancer in transdermal and respiratory drug delivery systems.
- Brazilian citrus concentration:Integrated groves-to-distillation operations in São Paulo state secure feedstock access for high-purity grades.
Market Restraints
- Input cost volatility:Brazilian orange harvest fluctuations and climate stress on citrus yields create raw material price instability.
- Supply concentration risk:Over-reliance on São Paulo processors exposes buyers to regional weather events and logistics disruptions.
- Regulatory friction:ECHA's skin sensitizer classification under REACH forces costly reformulation in leave-on cosmetic applications.
Strategic Opportunities
- Underpenetrated pharmaceutical markets:India and Southeast Asia show nascent adoption of terpene-based drug delivery technologies.
- Biotech-derived analogs:Microbial fermentation platforms are converging with synthetic biology to produce bio-identical terpenes independent of citrus agriculture.
- Modular fragrance procurement:Cosmetic brands are bypassing traditional bulk contracts through on-demand blending kits and custom formulation services.
Industry Challenges
- Analytical chemistry talent scarcity:Residual pesticide testing below 0.01 ppm for pharmaceutical grades requires specialized chromatography expertise that outpaces training pipelines.
- Multi-jurisdiction compliance timelines:Simultaneous FDA food additive, EPA FIFRA antimicrobial, and REACH skin sensitization assessments extend product launch cycles.
- Legacy equipment retrofit costs:Molecular distillation upgrades for VOC compliance demand capital deployment that mid-scale processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orange Terpenes Market |
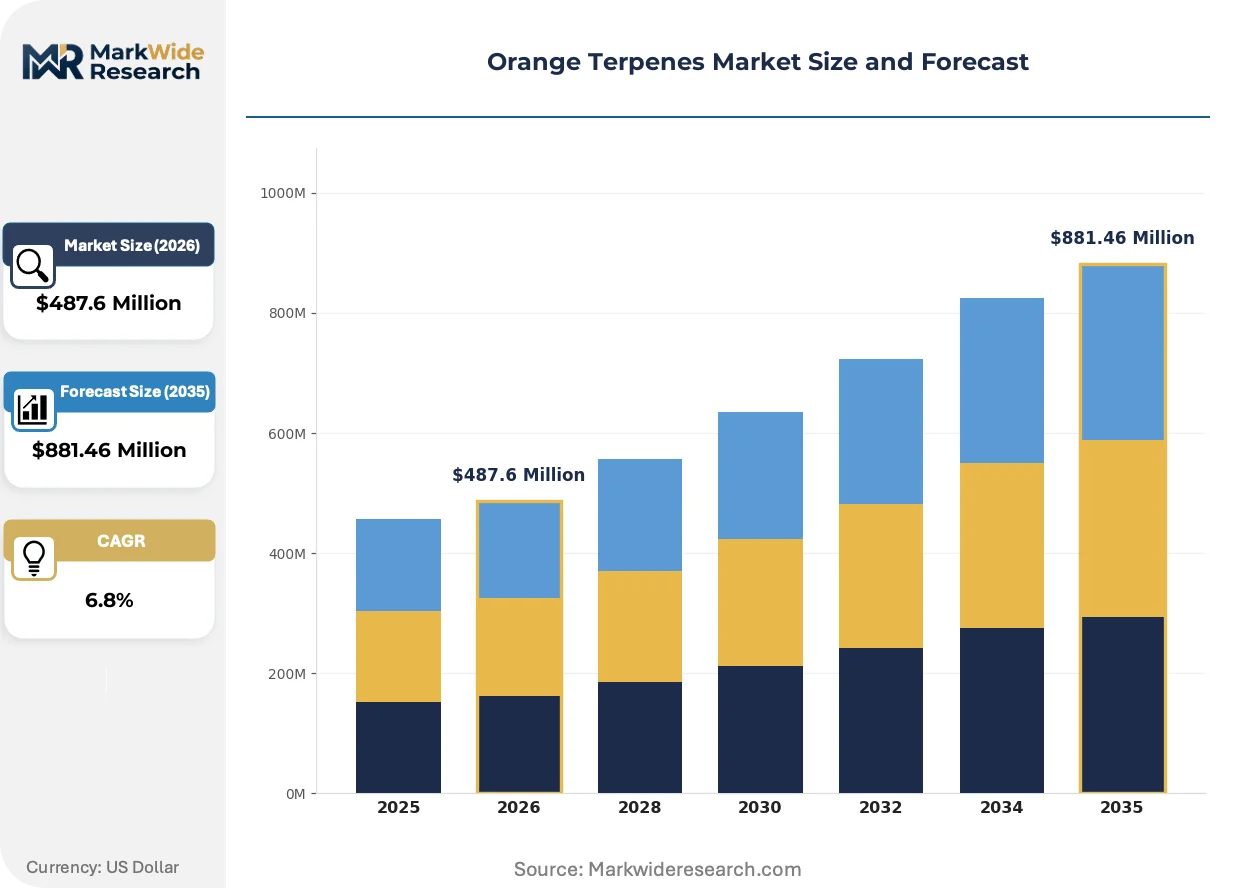
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, High Purity, Food Grade Application: Fragrance, Food & Beverage, Cosmetics, Pharmaceuticals Distribution Channel: Online, Retail, Direct Sales, Distributors End User: Food Manufacturers, Cosmetic Brands, Pharmaceutical Companies, Beverage Producers |
| Companies Covered | Firmenich, Givaudan, Citrosuco, Cutrale, Florida Chemical Company, Vigon International, Archer-Daniels-Midland Company, Symrise AG, Florachem Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orange Terpenes Market Strategic Shifts
Automation, regulatory reclassification, and procurement model fragmentation are compressing traditional supply arrangements while opening specialized service niches.
Supercritical CO2 extraction technology is automating the separation of high-purity d-limonene from cold-pressed orange oil with reduced thermal degradation. Pharmaceutical and food-grade producers in Germany and Switzerland are adopting these systems to meet residual solvent specifications that conventional steam distillation cannot achieve. This automation is compressing batch-to-batch variability and enabling continuous processing economics previously unavailable to mid-scale operators.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon use in industrial solvents, creating explicit preference for terpene-based alternatives in cleaning and degreasing applications. Aerosol and precision electronics manufacturers are reformulating product lines to qualify for green procurement tenders in France and Germany. The regulatory pressure is most acute in automotive component cleaning, where OEMs are mandating VOC-free process chemicals ahead of 2030 compliance deadlines.
Long-term supply contracts are fragmenting as fragrance houses and food manufacturers adopt spot-market purchasing through digital commodity platforms. Small-batch cosmetic brands in California and South Korea are sourcing directly from Brazilian distillers, bypassing traditional distributor markups. This disintermediation is most visible in premium natural fragrance segments, where provenance verification and carbon footprint transparency command price premiums over standardized bulk grades.
Orange Terpenes Market Segmentation
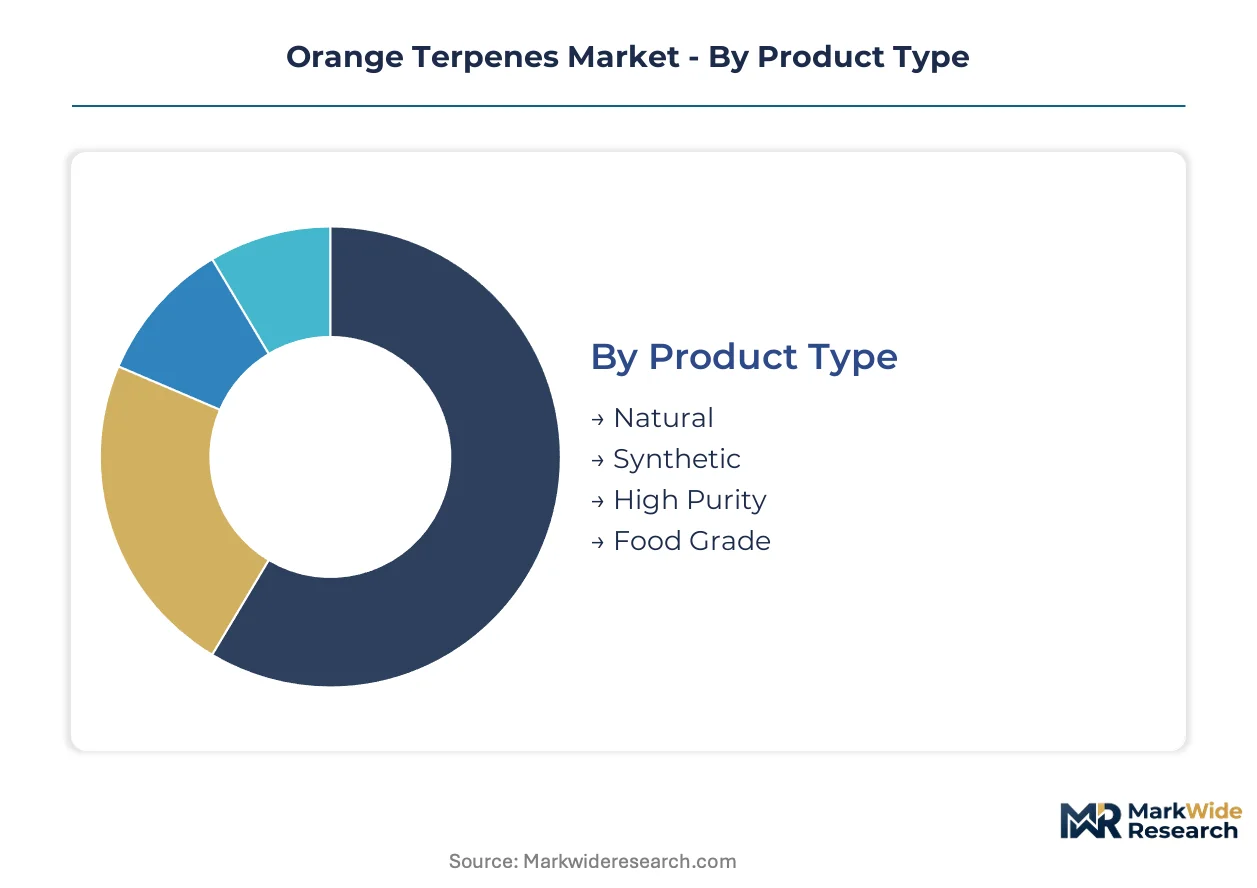
Orange terpenes command divergent price premiums based on purity thresholds and regulatory certification tiers. Pharmaceutical and food-grade specifications impose analytical chemistry barriers that standard fragrance grades bypass entirely. Segmentation strategy determines whether processors invest in molecular distillation infrastructure or compete on volume in commodity solvent markets.
Product Type:
Customization intensity spans from bulk commodity grades to certificate-of-analysis-driven pharmaceutical specifications, with each tier demanding distinct capital equipment and quality systems.
- Natural:Cold-pressed and steam-distilled extracts containing 90-95% d-limonene dominate clean-label fragrance and food applications. Demand concentrates in São Paulo state processors serving Givaudan and Firmenich formulation centers, constrained by Brazilian orange harvest volatility and residual pesticide testing requirements.
- High Purity:Molecular distillation achieves residual solvent specifications below 0.01 ppm for inhalation therapy and transdermal drug delivery. Pharmaceutical formulators in Germany and Switzerland adopt these grades for permeation enhancer applications, driving the steepest margin expansion across the product spectrum.
- Synthetic:Bio-identical terpenes from microbial fermentation platforms bypass agricultural feedstock dependence. Synthetic biology ventures in California and South Korea are scaling production independent of citrus climate risk.
- Food Grade:FDA Food Additive Status List compliance governs direct addition to beverages and confections. Beverage producers in India source these grades under FSSAI natural solvent mandates.
Most installed capacity flows through Natural grades. Expansion is steepest in High Purity.
Application:
End-use diversification runs from discretionary cosmetic spending to regulated pharmaceutical procurement, with compliance burden and pricing power inversely correlated.
- Pharmaceuticals:d-Limonene permeation enhancers enable transdermal and respiratory drug delivery systems. Formulators in Germany and Switzerland are expanding adoption fastest, constrained by ECHA skin sensitizer classification forcing reformulation in leave-on topical applications.
- Food & Beverage:Natural solvent substitution in beverage processing and confectionery flavor carriers responds to FDA and FSSAI clean-label mandates. India's FSSAI is driving substitution fastest among emerging markets.
- Fragrance:Precursor for citrus accords in fine fragrance and functional perfumery. REACH and F-Gas Regulation tightening VOC limits is forcing molecular distillation upgrades across European supply bases.
- Cosmetics:Fragrance ingredient and natural solvent in personal care formulations. ECHA's skin sensitizer classification under REACH is compelling reformulation investment in leave-on products.
Volume concentration sits with Fragrance applications. Regulatory tailwinds are strongest in Pharmaceuticals.
Distribution Channel:
Channel economics shift with batch size requirements, documentation burden, and the buyer's technical sophistication in specifying certificate-of-analysis parameters.
- Distributors:Traditional bulk procurement through specialized chemical distributors serving mid-scale fragrance houses and regional food processors. São Paulo-based processors maintain long-standing relationships with European and North American distribution networks.
- Direct Sales:Large-volume pharmaceutical and multinational fragrance houses negotiate directly with Brazilian integrated processors. Citrosuco and Cutrale anchor supply security through captive grove-to-distillation operations.
- Online:Digital commodity platforms are fragmenting long-term contracts as small-batch cosmetic brands in California and South Korea source directly. Provenance verification and carbon footprint transparency command price premiums over standardized bulk grades.
- Retail:Limited to specialty chemical reagents and small-scale laboratory supply. Academic and R&D procurement in Germany and Switzerland accesses analytical-grade terpenes through this channel.
Transaction value concentrates through Direct Sales. Channel expansion is fastest in Online.
End User:
Buyer sophistication ranges from commodity solvent procurement to validated pharmaceutical supply chains requiring audit trails and stability documentation.
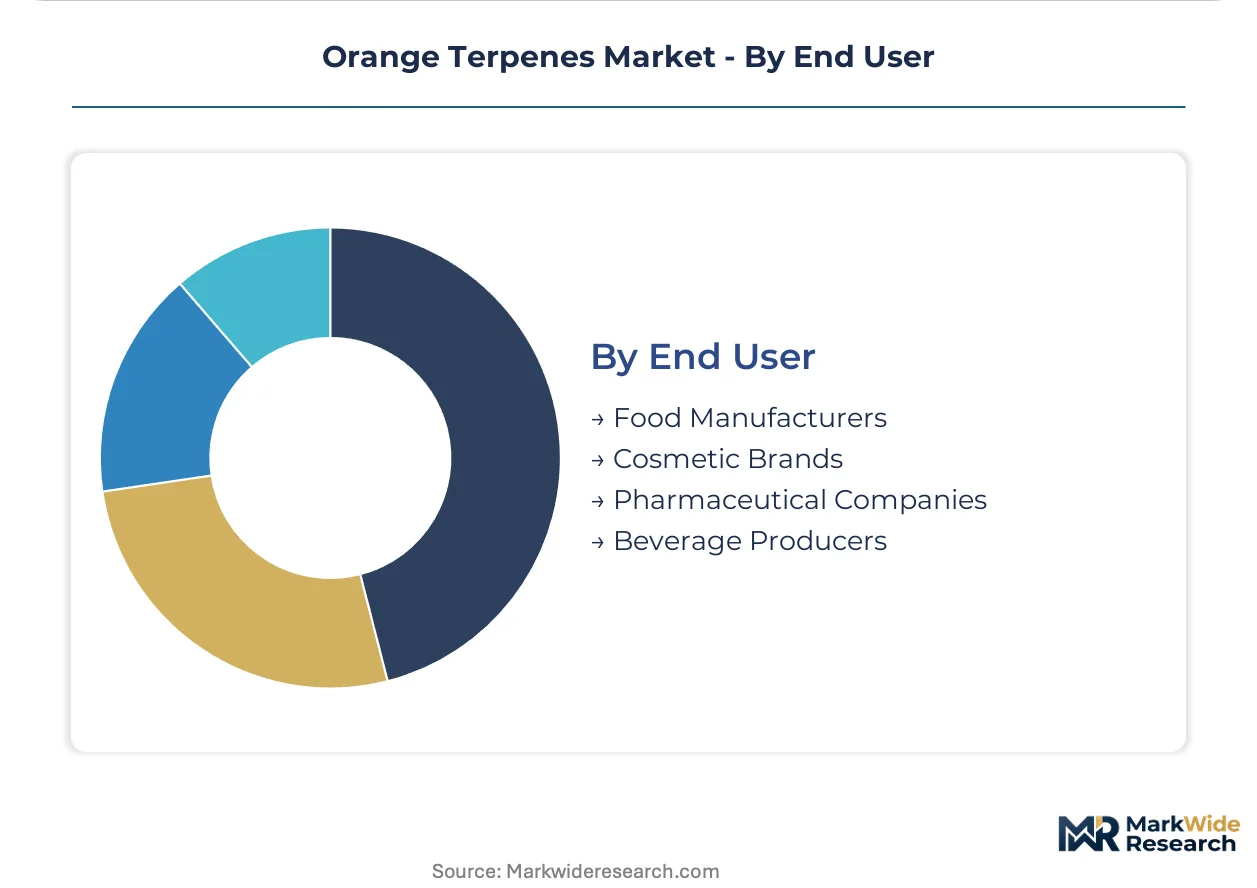
- Pharmaceutical Companies:Inhalation therapy and transdermal delivery system formulators demand residual pesticide testing below 0.01 ppm. German and Swiss pharmaceutical manufacturers are expanding terpene-based permeation enhancer adoption fastest.
- Cosmetic Brands:Fine fragrance houses and clean-label personal care marketers specify natural-origin grades with provenance verification. Modular blending kits are repositioning procurement toward on-demand custom formulation services.
- Food Manufacturers:Confectionery and processed food producers substitute synthetic solvents under FDA and FSSAI natural ingredient mandates. India's FSSAI is accelerating substitution timelines.
- Beverage Producers:Natural flavor carriers and solvent systems for extraction processes. Brazilian citrus processors supply high-volume contracts to multinational beverage conglomerates.
Contract value concentrates with Pharmaceutical Companies. Procurement reform is advancing fastest among Cosmetic Brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orange terpene extraction originated in Mediterranean citrus groves before industrial scaling shifted to São Paulo state in the mid-twentieth century. Brazilian processors now supply the majority of global feedstock. Regulatory fragmentation across consuming markets is reshaping regional demand patterns and certification requirements.
Brazil
São Paulo state's integrated grove-to-distillation operations anchor global supply security for high-purity grades. ANVISA pharmaceutical regulations and export certification protocols govern residual pesticide thresholds for international shipments. Citrosuco and Cutrale maintain captive citrus processing capacity in the Araraquara and Bebedouro corridor, securing feedstock access independent of spot-market volatility.
United States
Florida's citrus belt sustains domestic terpene production through cold-pressed peel oil extraction serving flavor and fragrance formulators. EPA FIFRA registration requirements govern antimicrobial solvent marketing, while FDA food additive status governs beverage and confectionery applications. Florida Chemical Company operates distillation capacity in the Lake Wales Ridge region, supplying regional fragrance houses and industrial solvent distributors.
Germany
Pharmaceutical formulators in the Rhine-Main and Upper Bavaria clusters drive premium-grade terpene demand for inhalation therapy and transdermal drug delivery systems. ECHA's REACH skin sensitizer classification and F-Gas Regulation VOC limits force molecular distillation upgrades across European supply chains. BASF and Merck KGaA procurement specifications are tightening residual solvent thresholds below conventional steam distillation capabilities.
India
FSSAI clean-label mandates are accelerating natural solvent substitution in beverage processing and confectionery manufacturing. Maharashtra and Gujarat-based flavor houses are expanding terpene procurement for domestic food manufacturers seeking synthetic additive replacement. Mumbai and Ahmedabad distribution networks are fragmenting long-term contracts toward spot-market purchasing through digital commodity platforms.
Switzerland
Givaudan and Firmenich formulation centers in Geneva and Zurich drive pharmaceutical-grade terpene specification setting for global fragrance and flavor applications. Swissmedic inhalation product regulations and carbon footprint disclosure requirements are shifting procurement toward provenance-verified Brazilian supply. Basel-area biotech ventures are piloting microbial fermentation platforms for bio-identical terpene production independent of agricultural feedstock.
Orange Terpenes Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-tier stratification, with pharmaceutical-grade specifications commanding threefold price multiples over standard fragrance grades. The vendor base concentrates around Brazilian integrated processors and European formulation houses, with mid-scale distributors occupying thinning intermediate positions. Three archetypes dominate: captive grove-to-distillation operators, R&D-intensive fragrance houses, and digital-native commodity platforms. Competitive moves center on backward integration into citrus agriculture and molecular distillation capacity expansion for regulatory compliance.
Within the integrated-processor tier, Citrosuco and Cutrale exemplify upstream control strategies through São Paulo state grove ownership and on-site distillation infrastructure. Among fragrance-house formulators, Givaudan and Firmenich occupy positions defining pharmaceutical-grade specification standards for permeation enhancer applications. These four entities collectively anchor supply security and price discovery mechanisms across natural, high-purity, and food-grade product tiers.
| Leading Market Players |
|---|
| Firmenich |
| Givaudan |
| Citrosuco |
| Cutrale |
| Florida Chemical Company |
| Vigon International |
| Archer-Daniels-Midland Company |
| Symrise AG |
| Florachem Corporation |
| Others |
Value Chain & Pricing Dynamics
REACH-mandated molecular distillation upgrades across European fragrance formulators are forcing São Paulo processors to absorb capital costs or cede share to synthetic alternatives, compressing margins on standard grades while widening premiums for pharmaceutical-certified output.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, food-grade, and fragrance tiers dominates transaction structures, with certification grade and residual solvent thresholds driving price differentiation. Pharmaceutical specifications command substantial premiums over fragrance grades due to sub-0.01 ppm pesticide testing requirements. Pricing pressure stems from Brazilian harvest volatility and climate stress on citrus yields. Fragrance houses exhibit highest price sensitivity, while pharmaceutical formulators prioritize supply security over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore consolidate Brazilian exports for European and Asian fragrance manufacturers. Supply concentrates in Brazil, with secondary sourcing from Florida and Mediterranean processors. Raw material flows draw from orange peel oil, cold-pressed citrus extracts, and microbial fermentation feedstocks. Single-source vulnerability runs through São Paulo's integrated grove-to-distillation corridor. Distribution runs through direct sales contracts for pharmaceutical volumes and specialized chemical distributors for mid-scale fragrance procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in high-purity pharmaceutical grades where certification barriers protect pricing power, while synthetic biology platforms offer cost-down pathways independent of agricultural volatility.
For Market Incumbents: Lock in captive citrus supply through long-term grove leases or equity stakes in São Paulo processing corridors before synthetic alternatives achieve cost parity. Expand molecular distillation capacity in Germany and Switzerland to capture REACH-driven reformulation demand from fragrance houses facing ECHA skin sensitizer reclassification. For New Entrants and Emerging Players: Begin with microbial fermentation platforms targeting pharmaceutical-grade d-limonene specifications, bypassing Brazilian climate risk entirely. India's FSSAI clean-label mandates present the most penetrable demand pool for natural solvent substitution, with digital commodity platforms enabling direct access to small-batch food manufacturers. For Investors and Strategic Acquirers: Asymmetric upside sits with synthetic biology ventures possessing scalable fermentation pathways and existing pharmaceutical certification relationships. Long-term viability favors platforms demonstrating production economics independent of citrus agriculture. Watch for inflection when bio-identical terpenes achieve cost parity with cold-pressed extracts in high-purity applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Groves | Citrosuco and Cutrale secure feedstock access independent of São Paulo spot-market volatility. |
| Molecular Distillation Capacity Expansion | German processors meet BASF and Merck KGaA residual solvent specifications below conventional steam distillation thresholds. |
| Microbial Fermentation Scale-Up | California and South Korean ventures bypass Brazilian climate risk for bio-identical pharmaceutical-grade output. |
| Digital Commodity Platform Partnership | Small-batch cosmetic brands in California source directly from Brazilian distillers, disintermediating traditional distributors. |
| Pharmaceutical Certification Investment | Swissmedic-compliant producers capture premium positioning in inhalation therapy and transdermal delivery applications. |
Study Parameters
Direct dialogue with citrus processing plant managers, fragrance house procurement directors, pharmaceutical formulators, and distribution channel partners grounded qualitative findings, cross-referenced with ANVISA export certification records, FDA Food Additive Status List filings, ECHA REACH registration databases, and Brazilian agricultural ministry harvest statistics. Bottom-up volume estimates from processor capacity and utilization rates triangulated against top-down demand segmentation from end-use industry consumption patterns.
Top-down macroeconomic drivers and bottom-up capacity-expansion pipelines converged across the projection horizon. Segmentation modeling spanned product type tiers, application end-uses, distribution channel structures, and regional regulatory clusters. CAGRs derived from historical volume trajectories and announced capacity investments, with pharmaceutical adoption curves and synthetic biology production timelines informing scenario-weighted outcomes.
Caveats apply where Brazilian climate events, ECHA reclassification thresholds, or synthetic biology cost breakthroughs could materially shift the outlook. Forecasts reflect stated assumptions around regulatory implementation timelines and technology scale-up trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
American Spikenard Extract Market
Flavorings and Food Additives
Brazil Food Flavor and Enhancer Market
Flavorings and Food Additives
Bergamot Extract Market
Flavorings and Food Additives
Pumpkin Spice Products Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Culinary Essence Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Synthetic Food Colors Market
Flavorings and Food Additives
Savory Extract Market
Flavorings and Food Additives
Apple Essence Market
Flavorings and Food Additives
Egypt Food Flavor and Enhancer Market
Flavorings and Food Additives
Annatto Extract Market
Flavorings and Food Additives
Russia Food Flavor and Enhancer Market
Flavorings and Food Additives
South America Food Flavor and Enhancer Market
Flavorings and Food Additives
Flavor Drops Market
Flavorings and Food Additives
Flavoring Agents Market