
 Transgenic Seeds Market | 2026-2036
Transgenic Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Transgenic Seeds Market Analytics
Consolidation among North American row-crop cooperatives is restructuring procurement leverage across the transgenic seed value chain. Bayer anchors its position through captive biotechnology pipelines spanning herbicide and insect-resistance trait stacks. Corteva differentiates via CRISPR-edited native trait integration alongside conventional transgenic platforms. Syngenta competes through integrated crop protection bundles that lock in multi-year seed-chemistry contracts with grain elevator networks.
Transgenic seeds contain exogenous genetic material introduced through Agrobacterium-mediated transformation or biolistic particle delivery, producing proteins that confer herbicide tolerance, insecticidal activity, or enhanced nutritional profiles for commercial agricultural production. Herbicide-resistant seed types dominate planted area in soybean and corn systems where glyphosate, glufosinate, and dicamba chemistries rotate against weed resistance pressure. Insect-resistant traits, led by Cry and Vip protein expression in cotton and corn, command premium positioning where bollworm and corn rootworm infestations justify technology fees.
The US EPA regulates plant-incorporated protectants under FIFRA, while the USDA APHIS oversees interstate movement and environmental release of transgenic organisms through permit and notification pathways. Brazil's CTNBio and Argentina's CONABIA operate parallel approval systems that shape South American market access timelines and trait stacking complexity. Stakeholders must monitor evolving gene-editing regulatory classifications that could resegment competitive boundaries between transgenic and precision-bred varieties.
Market Dynamics
Gene-editing regulatory reclassification is fragmenting competitive boundaries between transgenic and precision-bred varieties, forcing seed developers to maintain dual R&D pipelines while awaiting jurisdictional clarity on edited-trait approval pathways.
Growth Catalysts
- Brazil CTNBio streamlined stacking approvals:Accelerated regulatory timelines for pyramided insect-resistance traits enable faster commercialization of multi-protein corn varieties in the Cerrado expansion zone.
- Herbicide-tolerant weed pressure:Glyphosate-resistant Palmer amaranth and waterhemp infestations across the US Midwest drive replacement demand for seeds carrying glufosinate and dicamba tolerance traits.
- Double-cropping systems:Insect-resistant soybean varieties permit sequential planting of corn-soy rotations without pesticide application windows, compressing growing seasons in tropical latitude zones.
Market Restraints
- EU Green Deal Farm to Fork restrictions:Tightened transgenic crop approval pathways and national cultivation bans in member states divert R&D investment toward gene-editing alternatives with uncertain regulatory standing.
- Trait licensing cost concentration:Patent thickets around Cry and Vip protein families concentrate technology fee structures among three integrated agribusiness conglomerates, raising input costs for independent seed distributors.
- Agrobacterium transformation bottlenecks:Low transformation efficiency in elite maize inbred lines extends product development cycles and constrains trait introgression throughput.
Strategic Opportunities
- Argentina CONABIA gene-editing clarity:Explicit regulatory distinction between transgenic and site-directed nuclease products creates first-mover advantage for CRISPR-edited drought-tolerance traits in soybean export zones.
- India BIS stacked-trait cotton:Regulatory harmonization of insect-resistant and herbicide-tolerant gene combinations opens premium positioning in Gujarat and Maharashtra cotton belts.
- Carbon intensity accounting:EU CSRD Scope 3 agricultural emissions disclosure requirements favor transgenic seeds reducing diesel-powered cultivation passes through no-till herbicide tolerance systems.
Industry Challenges
- Regulatory science talent scarcity:Shortage of molecular biologists with dual expertise in plant transformation and jurisdiction-specific dossier preparation extends submission-to-approval timelines.
- Seed-chemistry contract integration:Multi-year bundled agreements with grain elevator networks lock procurement managers into inflexible trait-chemistry combinations as resistance patterns shift.
- Refuge compliance monitoring:EPA-mandated non-transgenic buffer zones for insect-resistance management impose logistical complexity on farm-scale planting operations and invite compliance penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transgenic Seeds Market |
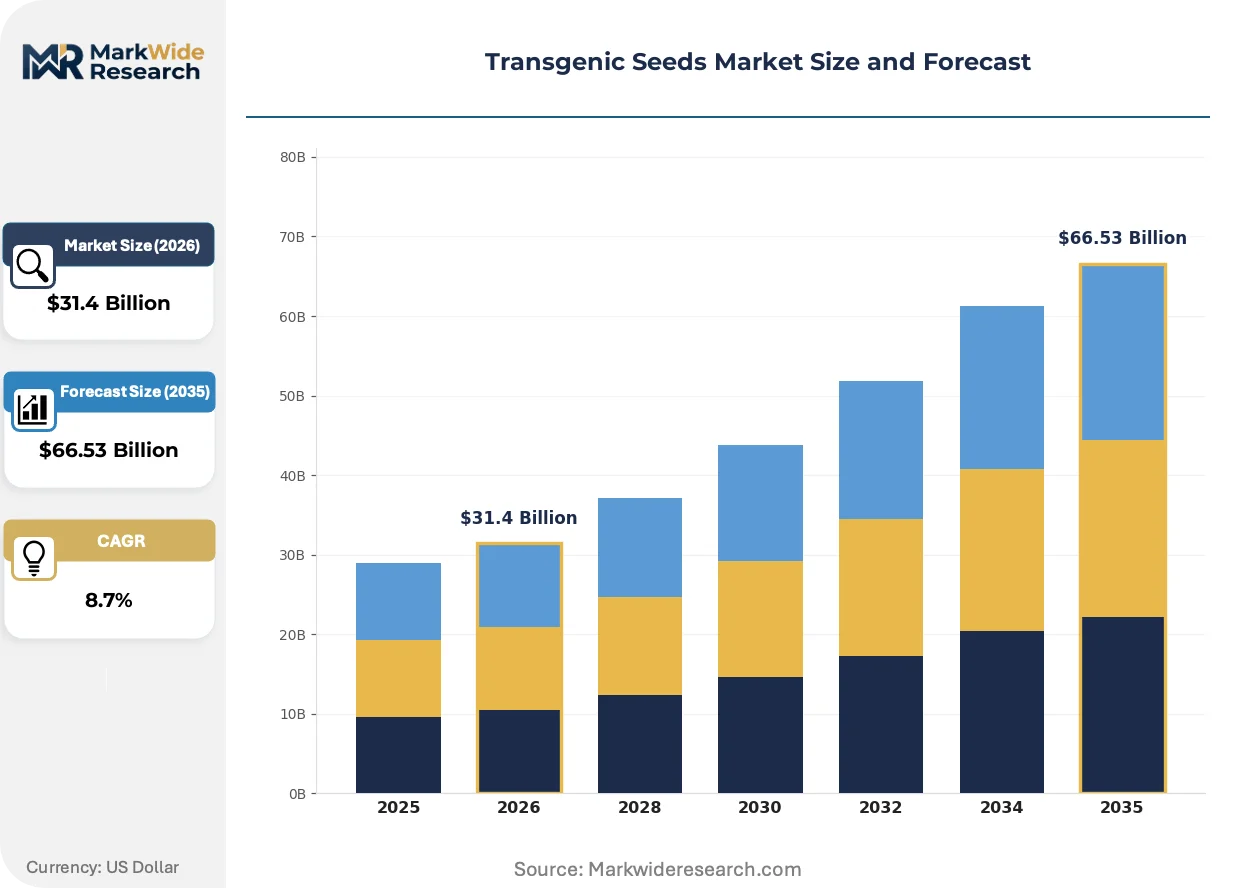
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $66.53 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Herbicide-Resistant, Insect-Resistant, Disease-Resistant, Nutritionally Enhanced Crop Type: Corn, Soybean, Cotton, Canola Application: Agricultural Production, Research & Development, Commercialization, Food Security Distribution Channel: Direct Sales, Online Retail, Distributors, Agricultural Stores |
| Companies Covered | Bayer, Syngenta, Corteva, BASF, Groupe Limagrain, Land O'Lakes, KWS SAAT, Sakata Seed Corporation, Vilmorin & Cie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transgenic Seeds Market Evolving Landscape
Stacked-trait architecture is compressing product development economics while regulatory divergence between gene-editing classifications resegments competitive boundaries. Three developments are restructuring commercial priorities.
RNA interference trait delivery is modularizing insect-resistance deployment. The technology suppresses essential gene expression in target pests through dsRNA molecules rather than Bt protein production. Large-scale corn growers in the US Corn Belt are piloting RNAi rootworm traits as rotation partners for Cry-expressing varieties. This approach is modularizing refuge requirements and extending trait durability timelines against resistance evolution.
EU EFSA revised guidance on stacked event risk assessment is lengthening authorization timelines for multi-trait varieties. The framework now demands separate interaction studies for each novel protein combination rather than extrapolation from single-event data. Corn and soybean seed developers targeting European import markets are sequencing trait launches to prioritize single-event approvals, delaying stacked-product introductions by regulatory sequencing constraints.
Grain elevator procurement consolidation is compressing seed purchasing autonomy. Cooperative mergers across the US Midwest concentrate volume contracting power among fewer buyers, shifting negotiation leverage from individual farm operators to centralized agronomy committees. This concentration is most visible in Iowa and Illinois, where regional cooperatives now specify trait packages in supply agreements rather than accommodating grower variety preferences.
Transgenic Seeds Market Segmentation
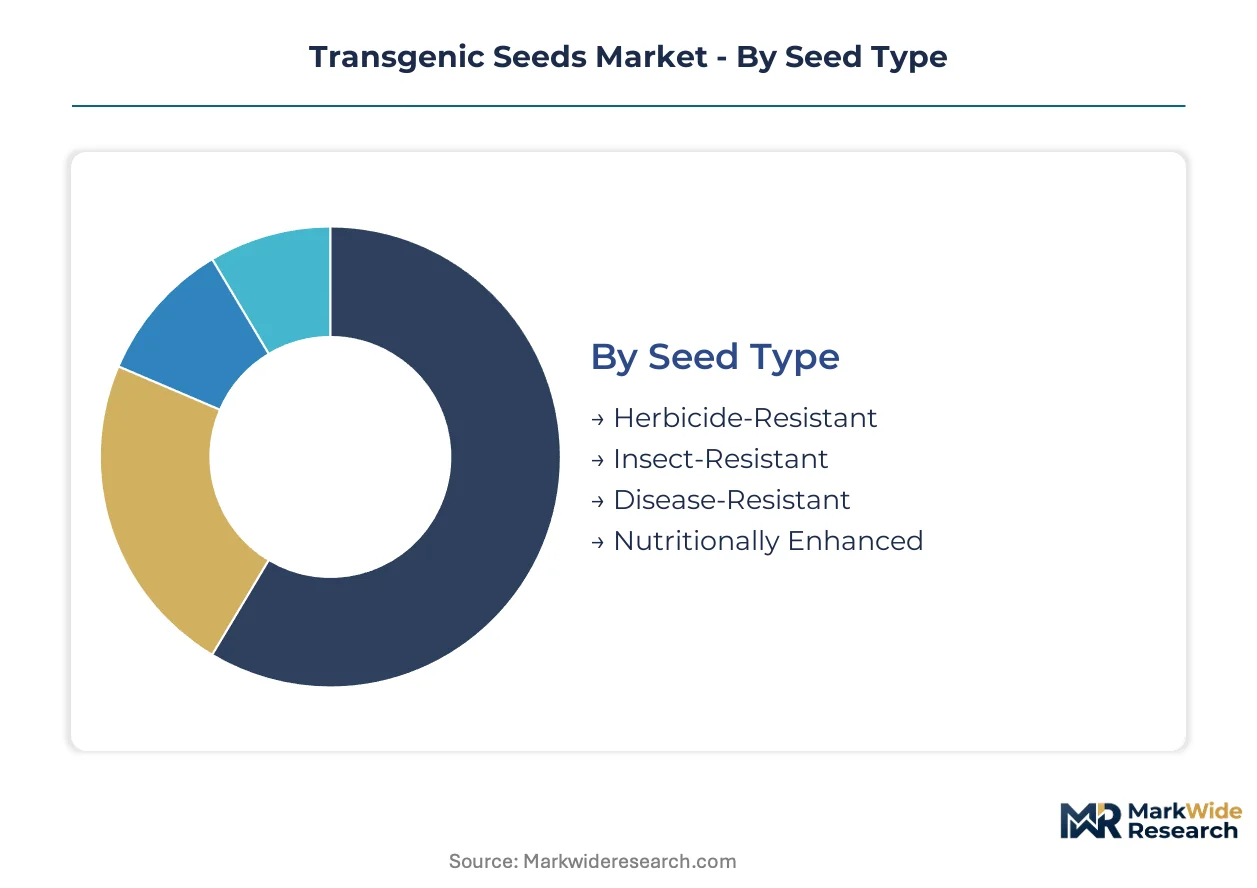
Trait stacking economics and regulatory approval pathways drive procurement decisions across seed categories. Farmers select combinations based on local pest pressure profiles, chemistry rotation requirements, and elevator contract specifications.
Seed Type:
Farmers prioritize trait combinations based on weed resistance maps and insect pressure monitoring in their counties.
- Herbicide-Resistant:Seeds express modified EPSPS, ALS, or PPO enzymes that detoxify glyphosate, glufosinate, or dicamba chemistries. Demand clusters in Iowa and Illinois corn-soy rotations where Palmer amaranth populations have rendered conventional chemistry ineffective.
- Insect-Resistant:Cry and Vip protein expression targets lepidopteran and coleopteran pests through Bt endotoxin production. Cotton growers in Gujarat and Maharashtra pay technology premiums for bollworm protection that eliminates spray windows during flowering stages.
- Disease-Resistant:Stacked antifungal protein traits address Fusarium and rust pathogens in humid soybean zones.
- Nutritionally Enhanced:High-oleic and omega-3 modified oil profiles command identity-preserved premiums from food processors.
Herbicide-Resistant leads on scale; Insect-Resistant leads on momentum.
Crop Type:
Double-cropping intensity and export market access shape acreage allocation decisions.
- Corn:Stacked rootworm and earworm traits dominate the US Corn Belt where continuous corn systems amplify pest pressure. EPA refuge mandates require structured non-transgenic plantings that complicate farm management.
- Soybean:Herbicide-tolerant varieties enable no-till establishment in Brazil's Cerrado where soybean-corn double-cropping compresses fieldwork windows. Intacta traits combining insect resistance with glyphosate tolerance capture premium share in Mato Grosso.
- Cotton:Bollgard and Widestrike trait platforms anchor production in India and Pakistan where manual spraying costs exceed technology fees.
- Canola:Glufosinate-tolerant varieties facilitate direct harvest systems in Canadian prairie provinces.
Corn dominates planted area; soybean expands most quickly through tropical double-cropping adoption.
Application:
End-use determines trait validation requirements and regulatory dossier complexity.
- Agricultural Production:Commercial field deployment of approved events in commodity crop systems. Farmers in Argentina's Pampas region select trait packages through grain elevator procurement committees that specify chemistry-seed bundles.
- Research & Development:Confined field trials and regulatory data generation for novel protein submissions. CTNBio and CONABIA parallel review pathways accelerate South American market entry relative to EFSA timelines.
- Commercialization:Seed production scaling and distributor network establishment for approved events.
- Food Security:Biofortified trait deployment in subsistence systems with humanitarian funding support.
Agricultural Production commands volume concentration; Research & Development shows steepest investment trajectory as gene-editing platforms multiply pipeline candidates.
Distribution Channel:
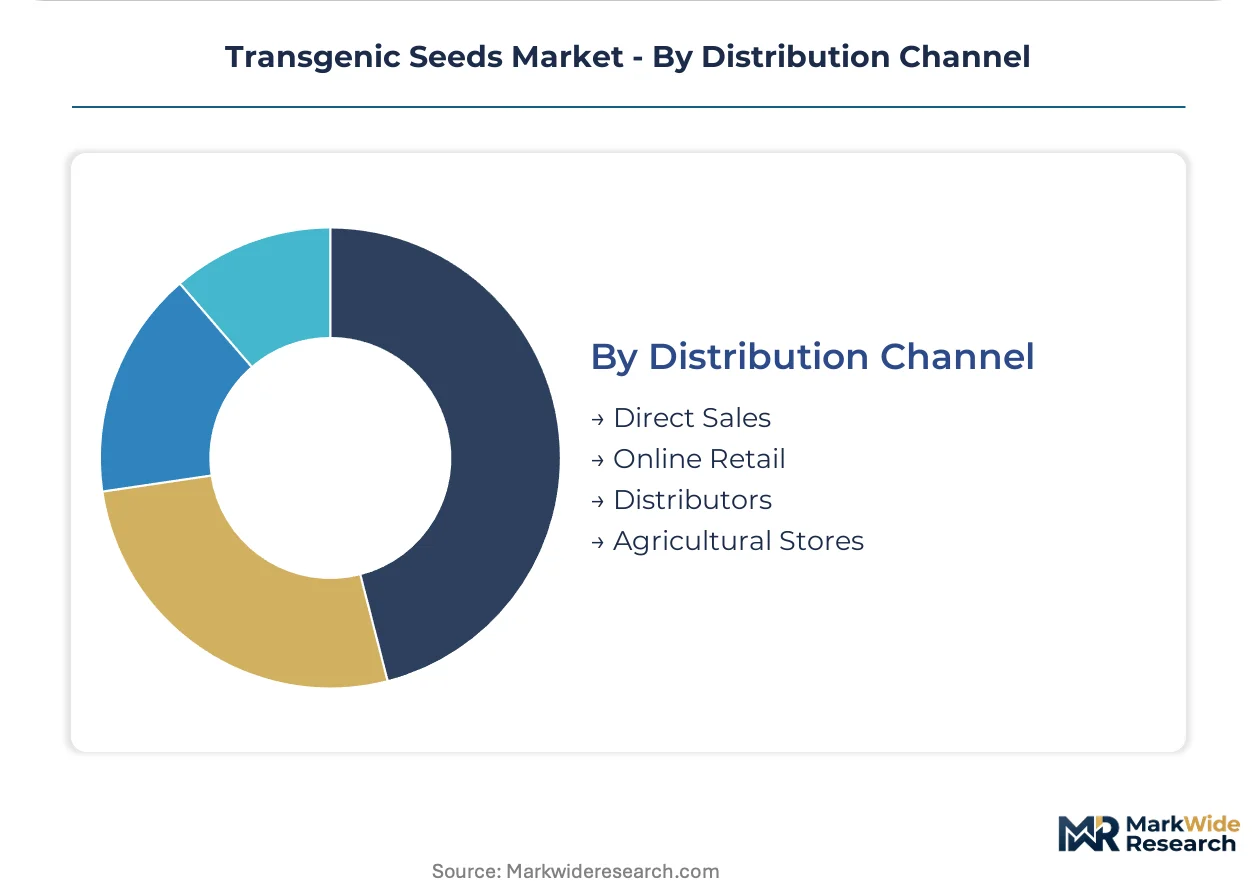
Procurement autonomy is compressing as cooperative consolidation concentrates contracting power.
- Direct Sales:Manufacturer-to-grower contracts for large-scale operations with volume commitments. Bayer and Corteva field representatives negotiate multi-year trait-chemistry agreements directly with Iowa and Illinois farms exceeding 2,000 acres.
- Distributors:Independent seed dealers with localized agronomy support and credit extension. Regional networks in Brazil's Midwest maintain inventory positions across multiple trait platforms to hedge against approval delays.
- Online Retail:E-commerce platforms with variety comparison tools and financing integration.
- Agricultural Stores:Cooperative retail locations with bundled input procurement.
Direct Sales captures premium contract value; Distributors retain widest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plant molecular biologists and regulatory affairs specialists cluster in agricultural biotechnology hubs across the United States, Brazil, Germany, China, and India. These talent concentrations anchor regional R&D pipelines and shape approval pathway strategies for novel trait submissions.
United States
EPA FIFRA jurisdiction over plant-incorporated protectants and USDA APHIS interstate movement permits structure the regulatory landscape for herbicide-tolerant corn and soybean varieties. The Iowa-Illinois corn belt drives replacement demand as glyphosate-resistant Palmer amaranth populations render conventional chemistry ineffective. Bayer and Corteva field representatives negotiate multi-year trait-chemistry agreements directly with operations exceeding 2,000 acres.
Brazil
CTNBio streamlined stacking approvals accelerate commercialization timelines for pyramided insect-resistance traits in multi-protein corn varieties. The Cerrado expansion zone concentrates double-cropping soybean-corn rotations where Intacta traits combining insect resistance with glyphosate tolerance capture premium positioning. Regional distributor networks maintain inventory across multiple trait platforms to hedge against approval delays.
Germany
EU EFSA revised guidance on stacked event risk assessment lengthens authorization timelines for multi-trait varieties targeting European import markets. The EU Green Deal Farm to Fork strategy diverts R&D investment toward gene-editing alternatives with uncertain regulatory standing. KWS SAAT anchors trait development pipelines from its Einbeck headquarters while navigating member-state cultivation bans.
China
NMPA and Ministry of Agriculture and Rural Affairs oversight of genetically modified organism safety certificates shapes domestic corn and soybean trait adoption. The Yangtze River Delta and Northeast China corn belt concentrate pilot programs for insect-resistant varieties. State-owned seed enterprises coordinate with international technology licensors under technology transfer frameworks.
India
BIS regulatory harmonization of stacked-trait cotton combinations opens premium positioning in Gujarat and Maharashtra cotton belts. The Central Institute for Cotton Research anchors bollworm resistance monitoring networks that inform refuge compliance mandates. Maharashtra's Vidarbha region and Gujarat's Saurashtra peninsula concentrate Bollgard and Widestrike trait deployment where manual spraying costs exceed technology fees.
Transgenic Seeds Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across trait development, regulatory dossier preparation, and distributor network access. Three integrated agribusiness conglomerates anchor the consolidated tier through captive biotechnology pipelines spanning herbicide and insect-resistance trait stacks. Patent thickets around Cry and Vip protein families concentrate technology fee structures and raise input costs for independent seed distributors. Dominant competitive moves include M&A-driven trait portfolio expansion and multi-year bundled agreements with grain elevator networks.
Within the integrated agribusiness tier, Bayer and Syngenta exemplify conglomerate-scale operations spanning seeds, crop protection, and digital agriculture platforms. Corteva occupies a position as the agriculture-focused pure-play spinoff with CRISPR-edited native trait integration alongside conventional transgenic platforms. Among European specialists, KWS SAAT and Vilmorin & Cie represent family-controlled seed enterprises with century-scale breeding programs and regional regulatory expertise.
| Leading Market Players |
|---|
| Bayer |
| Syngenta |
| Corteva |
| BASF |
| Groupe Limagrain |
| Land O'Lakes |
| KWS SAAT |
| Sakata Seed Corporation |
| Vilmorin & Cie |
| Others |
Value Network & Pricing Analysis
EU CSRD Scope 3 agricultural emissions disclosure requirements gate qualified supply access for seed developers while compressing premium-tier pricing power among sustainability-certified distributors. Compliance documentation costs filter smaller distributors from high-margin contract segments.
Pricing Analysis
Bundled trait-chemistry contracts dominate large-scale procurement while unbundled seed-only transactions persist among independent dealers. Three-tier pricing structure across premium, standard, and economy levels separates Intacta-type stacked trait packages from single-event herbicide tolerance and conventional germplasm. Cost compression in economy-tier conventional seed is intensifying because elevator procurement committees now specify minimum trait thresholds. Independent distributors exhibit highest price sensitivity; integrated agribusiness conglomerates with captive chemistry pipelines demonstrate lowest.
Supply Chain Analysis
Direct-to-farm channels handle hyperscale buyer demand across Iowa and Illinois while regional distributor networks manage inventory risk in Brazil's Cerrado. Supply concentrates in the United States, Brazil, and Argentina as transformation facility locations and regulatory approval hubs. Elite maize inbred lines, Cry protein licensing rights, and glufosinate active ingredient feed from concentrated upstream sources. Single-source vulnerability around Agrobacterium transformation capacity constrains trait introgression throughput. Distribution runs through cooperative grain elevator networks that specify chemistry-seed bundles in multi-year agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transgenic seeds market functions as a regulatory compounder where Brazil CTNBio streamlined stacking approvals accelerate replacement demand and reshape competitive timelines.
For Market Incumbents: Extend trait portfolio depth through CRISPR-edited native trait integration alongside conventional transgenic platforms to hedge against gene-editing regulatory reclassification. Deepen backward integration into elite maize inbred line transformation capacity to reduce Agrobacterium bottlenecks. Lock grain elevator procurement committees into multi-year bundled agreements before resistance pattern shifts invalidate current chemistry rotations. For New Entrants and Emerging Players: Begin with Argentina CONABIA's explicit gene-editing regulatory distinction to establish first-mover positioning in CRISPR-edited drought-tolerance soybean traits. Target Gujarat and Maharashtra cotton belts where BIS stacked-trait regulatory harmonization opens premium positioning against incumbent Bollgard platforms. Pursue identity-preserved contracting with food processors seeking high-oleic oil profiles as a channel entry wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributor networks with localized agronomy support and credit extension capabilities in Brazil's Midwest. Long-term viability rests on regulatory science talent scarcity resolving through automated dossier preparation tools. Watch CTNBio approval velocity as the inflection signal distinguishing South American market access timelines from EFSA stagnation.| Strategic Initiative | Industry Significance |
|---|---|
| Trait Stacking Architecture | Compresses product development economics while extending trait durability against resistance evolution. |
| Gene-Editing Platform Investment | Positions developers for regulatory reclassification advantages in Argentina and potential EU pathway shifts. |
| Grain Elevator Network Integration | Locks multi-year chemistry-seed contracts that shift negotiation leverage from farm operators to cooperatives. |
| RNA Interference Trait Pipeline | Modularizes insect-resistance deployment and simplifies EPA refuge compliance monitoring requirements. |
| Regulatory Science Talent Acquisition | Accelerates submission-to-approval timelines amid molecular biologist scarcity in plant transformation. |
Research Methodology
Multiple input streams — regulatory dossier analysis, seed industry procurement data, and trait approval timeline records — were reconciled across primary interviews with plant molecular biologists, regulatory affairs specialists, grain elevator procurement managers, and independent seed distributors. Secondary validation drew from EPA FIFRA registrations, USDA APHIS permits, CTNBio and CONABIA approval databases, and SEC filings of integrated agribusiness conglomerates. Bottom-up acreage estimates and top-down market value reconstructions were triangulated to anchor segmentation outputs.
Historical trait adoption curves were cross-referenced against expert panel assessments of resistance pressure evolution and regulatory pathway clarity. Segmentation modeling spanned trait type, crop category, distribution channel, and regional regulatory cluster across the analysis window. CAGRs were derived from acreage trajectory projections and technology fee structures. Forecast inputs included CTNBio stacking approval velocity, Palmer amaranth resistance spread maps, and cooperative merger activity in the US Midwest.
Several conditions sit outside the modeled scope, including abrupt EU gene-editing reclassification, unanticipated Cry protein resistance outbreaks, and major cooperative insolvencies. Forecasts reflect assumptions about regulatory timeline continuity and trait durability that stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
Asia Pacific Feed Phytogenics Market
Agricultural Biotechnology
Global Plant Hormones Market
Agricultural Biotechnology
Agricultural Biotechnology Market
Agricultural Biotechnology
Plant-Based Vaccines Market
Agricultural Biotechnology
Europe Agriculture Biotech Market
Agricultural Biotechnology
Asia-Pacific Agriculture Biotech Market
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
Duckweed Protein Market
Agricultural Biotechnology
Biorationals Market
Agricultural Biotechnology
Global Poultry Vaccines Market
Agricultural Biotechnology
Ruminant Vaccines Market
Agricultural Biotechnology
Europe Plant Growth Regulators Market
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Agroscience Market
Agricultural Biotechnology
Brazil Veterinary Vaccines Market
Agricultural Biotechnology
Microarray in Agriculture Market