
 At-Home Vaginal Ph Test Kit Market | 2026-2036
At-Home Vaginal Ph Test Kit Market Size, Share, and Industry Trends Forecast 2026-2036
At-Home Vaginal Ph Test Kit Market Outlook
Subscription-based telehealth bundling is reshaping margin distribution between one-time kit sales and recurring physician consultations. Abbott Laboratories leverages its diagnostic manufacturing scale to anchor supply reliability across retail and digital channels. Everlywell competes through integrated lab-to-app workflows that extend customer lifetime value beyond the initial purchase.
An at-home vaginal pH test kit comprises pH-sensitive indicator strips or digital biosensors calibrated to detect acidity ranges between 3.8 and 4.5, with colorimetric or electrochemical readouts designed for self-administered vaginal health monitoring without clinical supervision. Test strips occupy the highest volume tier due to minimal unit economics and broad retail placement, while digital testers command premium positioning through Bluetooth-linked data tracking. Telehealth consultations represent the fastest-expanding delivery mode as virtual care platforms integrate diagnostic results into remote gynecological workflows.
The FDA oversees 510(k) clearance pathways for over-the-counter diagnostic devices in the United States, while the EU MDR governs CE marking requirements for self-testing products sold in European markets. These frameworks elevate compliance costs for new entrants but simultaneously validate product accuracy claims that drive consumer trust and pharmacy channel access. Stakeholders must monitor evolving digital health reimbursement policies that could either subsidize or fragment telehealth-integrated kit adoption.
Market Dynamics
Telehealth bundling is compressing the traditional kit-only revenue model into subscription ecosystems where diagnostic hardware serves as a loss-leader for recurring consultation fees.
Growth Catalysts
- HIPAA-aligned data portability:The US framework for protected health information exchange enables seamless app-to-physician data handoffs that reduce friction in remote diagnostic workflows.
- Metropolitan direct-to-consumer density:Urban clusters in the United States with established pharmacy delivery networks concentrate early adoption of self-testing protocols.
- Electrochemical biosensor miniaturization:Solid-state pH electrodes calibrated for vaginal acidity ranges now integrate with smartphone peripherals at consumer price points.
Market Restraints
- 510(k) clearance timeline volatility:FDA review cycles for over-the-counter diagnostic devices create launch-date uncertainty that freezes capital allocation.
- Indicator chemistry supply concentration:Nitrazine yellow and bromocresol green dye synthesis concentrates among Asian specialty chemical manufacturers.
- Urinary pH strip substitution:Lower-cost general-purpose pH test strips marketed for multi-use applications erode perceived differentiation of vaginal-specific kits.
Strategic Opportunities
- Perimenopausal monitoring white space:Hormonal transition tracking represents an underdeveloped application segment with limited dedicated product offerings.
- Medicaid telehealth reimbursement expansion:State-level policy variations in the United States create arbitrage opportunities for platforms targeting underserved populations.
- Bluetooth-LTE convergence:Continuous connectivity architectures enable real-time clinician alerts without smartphone dependency, opening rural deployment channels.
Industry Challenges
- Clinical validation talent scarcity:Biostatisticians with gynecological endpoint expertise command premium compensation that strains mid-cap R&D budgets.
- Multi-jurisdiction labeling complexity:Divergent symbol requirements between FDA, Health Canada, and EU MDR regimes fragment packaging standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | At-Home Vaginal Ph Test Kit Market |
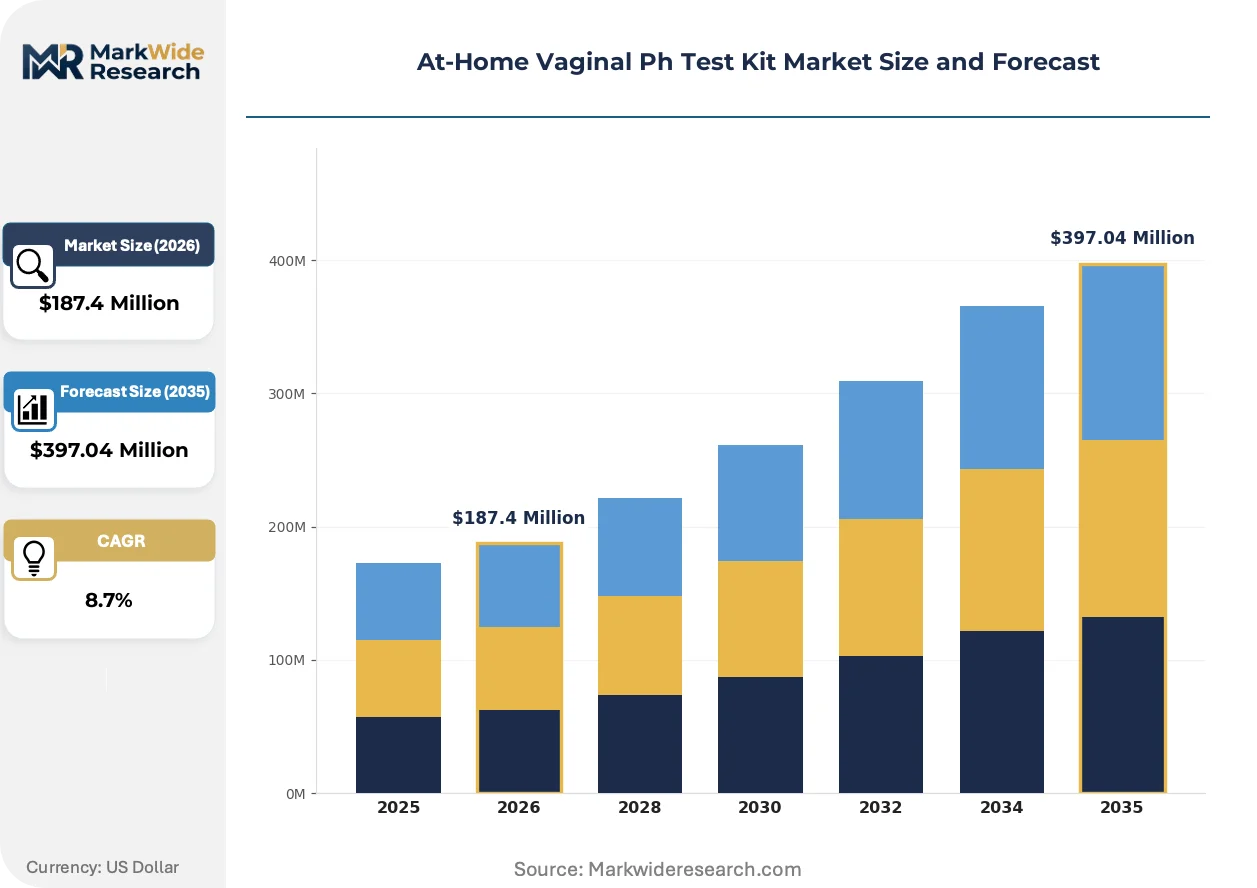
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Strips, Digital Testers, Kits, Swabs Delivery Mode: Home Use, Telehealth Consultations, In-Store Pickup, Mail Order Target Audience: Women, Healthcare Providers, Gynecologists, Fertility Clinics Packaging Type: Boxed Kits, Individually Wrapped, Eco-Friendly, Standard Packaging |
| Companies Covered | Abbott Laboratories, OraSure Technologies, Inc., Everlywell, LetsGetChecked, Bayer AG, Prestige Consumer Healthcare, Inc., Vagisil, Stix, Clearblue, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
At-Home Vaginal Ph Test Kit Market Strategic Shifts
Digital biomarker integration is dissolving the boundary between consumer wellness tracking and clinical-grade diagnostic evidence, forcing kit manufacturers to choose between hardware margins and data platform economics.
Electrochemical biosensor arrays with solid-state reference electrodes are virtualizing the colorimetric interpretation step that previously required user judgment. Fertility-tracking app subscribers in the United States and Germany are adopting these peripherals at three times the rate of standalone strip purchasers. The shift is virtualizing diagnostic expertise into algorithmic readouts that compress the need for synchronous physician consultation.
The EU MDR's post-market surveillance requirements for self-testing devices are elevating clinical follow-up obligations beyond pre-market validation. Manufacturers now face mandatory periodic safety reporting that extends compliance costs across product lifecycles. Class IIa self-test designations for vaginal pH devices sold in France and Italy are triggering notified body backlogs that delay CE marking by eight to fourteen months.
Subscription bundling of kits with asynchronous physician review is displacing one-time retail purchases in urban United States markets. Direct-to-consumer platforms capture recurring revenue that pharmacy chains cannot match without telehealth infrastructure. The model concentrates in California and New York metropolitan statistical areas where same-day delivery logistics intersect with high telehealth literacy.
At-Home Vaginal Ph Test Kit Market Segmentation
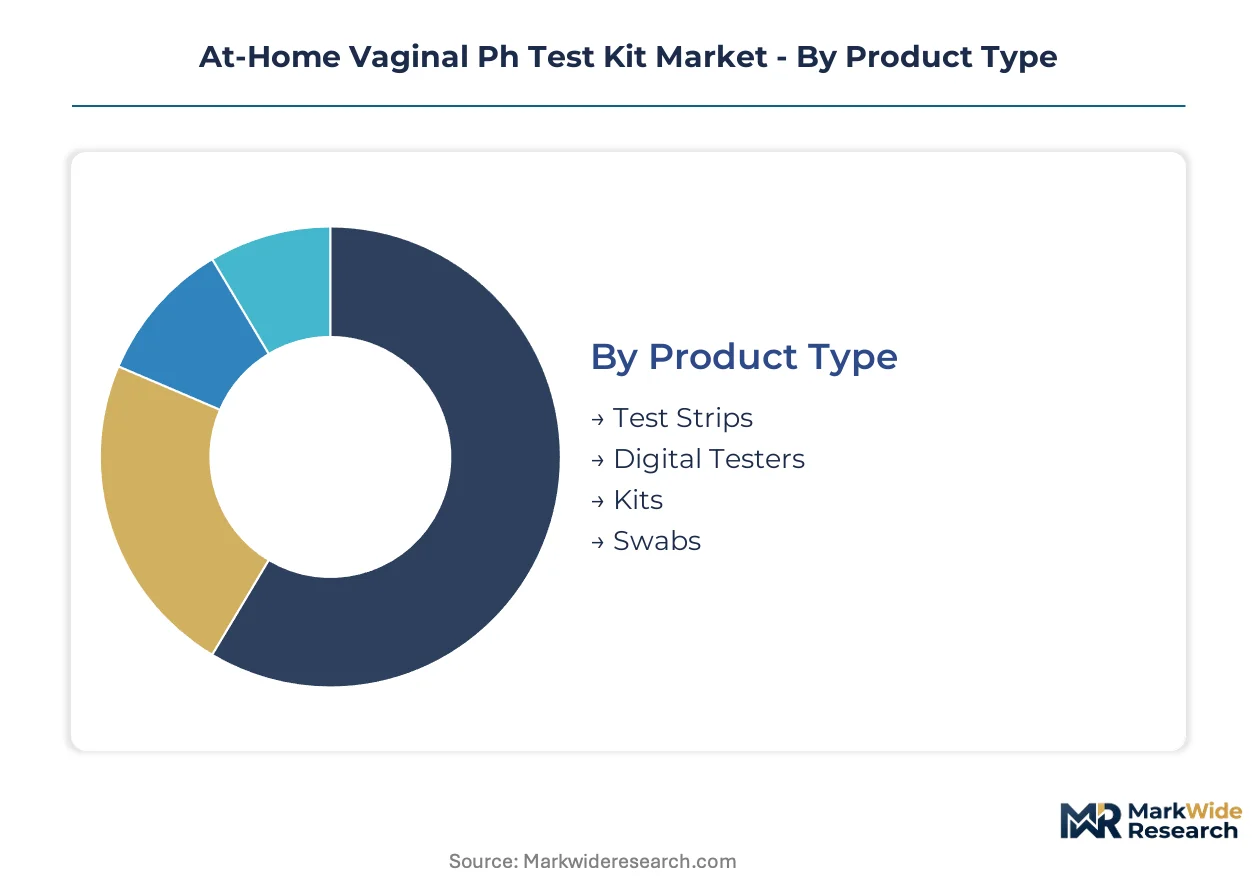
Segmentation in at-home vaginal pH testing reveals divergent margin architectures across hardware formats and service bundling models. Manufacturers must align production scale with the economics of each tier, from disposable strips to connected biosensor ecosystems.
Product Type:
Mature colorimetric formats dominate unit shipments while electrochemical platforms emerge as the premium tier with recurring data revenue potential.
- Test Strips:Nitrazine yellow-impregnated cellulose strips deliver pH readings through color-matching charts, with manufacturing concentrated among Asian specialty chemical suppliers. Demand clusters in United States pharmacy retail chains where impulse purchase pricing drives volume. Indicator chemistry supply bottlenecks periodically constrain output flexibility.
- Digital Testers:Solid-state pH electrodes paired with Bluetooth peripherals eliminate subjective color interpretation, capturing fertility-tracking app subscribers in Germany and the United States at premium price points. Electrochemical biosensor miniaturization has collapsed component costs to consumer-accessible levels.
- Kits:Bundled combinations of strips, digital readers, and collection implements serve first-time purchasers seeking complete protocols.
- Swabs:Pre-moistened applicator formats target users prioritizing hygiene and reduced handling steps.
Test strips retain volume leadership; digital testers hold the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates one-time hardware transactions from subscription-dependent service models with divergent customer acquisition economics.
- Home Use:Direct-to-consumer shipments through e-commerce platforms capture price-sensitive users seeking privacy, with same-day delivery infrastructure in California and New York metropolitan areas compressing purchase-to-test intervals.
- Telehealth Consultations:Virtual care platforms integrate diagnostic results into asynchronous physician review workflows, generating recurring consultation fees that subsidize hardware margins. HIPAA-aligned data portability enables seamless app-to-clinician handoffs in United States markets.
- In-Store Pickup:Pharmacy chain fulfillment preserves immediacy for users avoiding shipping delays.
- Mail Order:Subscription replenishment programs lock in recurring strip purchases with automated reorder triggers.
Home use maintains shipment dominance; telehealth consultations are climbing the fastest as virtual care platforms scale.
Target Audience:
Application focus distinguishes self-monitoring consumers from clinical intermediaries with divergent accuracy requirements and purchasing authority.
- Women:Individual end-users conducting unsupervised vaginal health monitoring represent the addressable mass market, with perimenopausal tracking emerging as an underserved subsegment.
- Healthcare Providers:Physician practices purchasing kits for patient distribution demand FDA 510(k) clearance documentation and batch traceability.
- Gynecologists:Specialist clinics prioritize digital testers with electronic health record integration for remote patient monitoring programs.
- Fertility Clinics:Assisted reproduction centers require precise pH tracking as part of broader hormonal monitoring protocols.
Women constitute the volume anchor; fertility clinics show the steepest adoption acceleration.
Packaging Type:
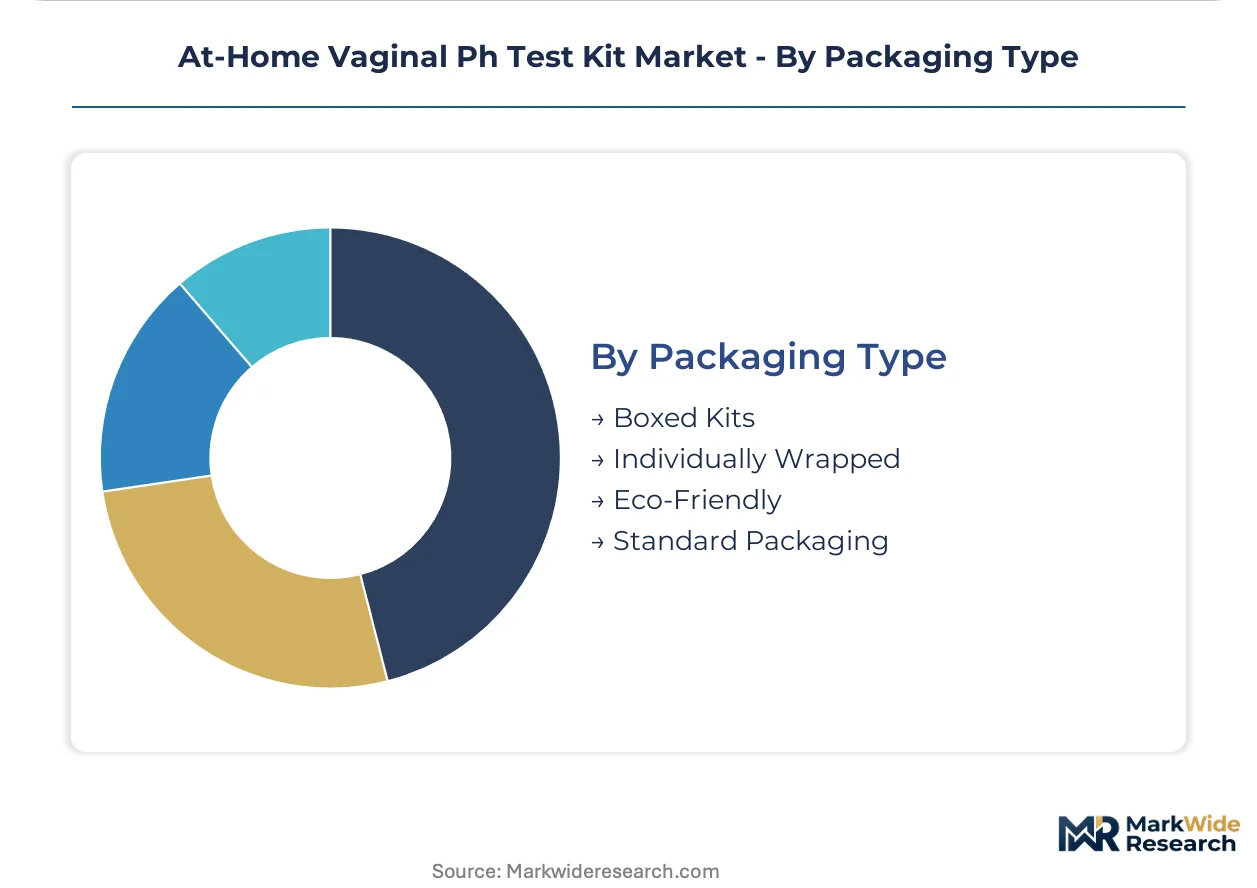
Customer type preferences split between convenience-oriented disposables and sustainability-motivated purchasing decisions with margin implications.
- Boxed Kits:Multi-test containers with instructional inserts serve retail pharmacy placement where shelf presence influences selection.
- Individually Wrapped:Single-unit sterile pouches address travel use cases and clinical settings requiring contamination control.
- Eco-Friendly:Compostable or recyclable materials capture environmentally conscious purchasers in European markets governed by EU Green Deal packaging directives.
- Standard Packaging:Conventional plastic and paper formats minimize unit cost for price-competitive channels.
Standard packaging retains cost leadership; eco-friendly formats gain share fastest in regulated European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between markets where telehealth bundling dominates recurring revenue and those where retail pharmacy impulse purchases anchor volume. Metropolitan density of direct-to-consumer infrastructure determines which model prevails.
United States
Telehealth-integrated kit subscriptions concentrate in California and New York metropolitan statistical areas where same-day delivery logistics intersect with high virtual care literacy. FDA 510(k) clearance pathways for over-the-counter diagnostic devices create regulatory validation that drives pharmacy channel access. HIPAA-aligned data portability frameworks enable seamless app-to-clinician handoffs in these urban clusters.
Germany
Fertility-tracking app subscribers adopt digital pH testers at triple the rate of standalone strip purchasers, compressing demand into connected biosensor formats. EU MDR Class IIa self-test designations trigger notified body backlogs that delay CE marking by eight to fourteen months. Berlin and Munich anchor demand concentration for electrochemical peripherals with smartphone integration.
France
ANSM oversight of self-testing devices elevates clinical follow-up obligations beyond pre-market validation, extending compliance costs across product lifecycles. Eco-friendly packaging formats gain share fastest here under EU Green Deal packaging directives. Paris and Lyon metropolitan areas concentrate early adoption of subscription-based telehealth bundling.
United Kingdom
Asynchronous physician review platforms displace one-time retail purchases in Greater London and Southeast England where digital health literacy runs highest. MHRA regulations align with EU MDR requirements post-Brexit, preserving CE marking relevance for market access. Manchester and Birmingham emerge as secondary demand nodes for pharmacy-chain fulfillment models.
Canada
Health Canada regulations govern medical device licensing for self-testing products, with provincial telehealth reimbursement variations creating arbitrage opportunities. Toronto and Vancouver anchor demand for privacy-oriented direct-to-consumer shipments through e-commerce platforms. Mail-order subscription replenishment programs lock in recurring strip purchases with automated reorder triggers in these metros.
At-Home Vaginal Ph Test Kit Market Competitive Environment
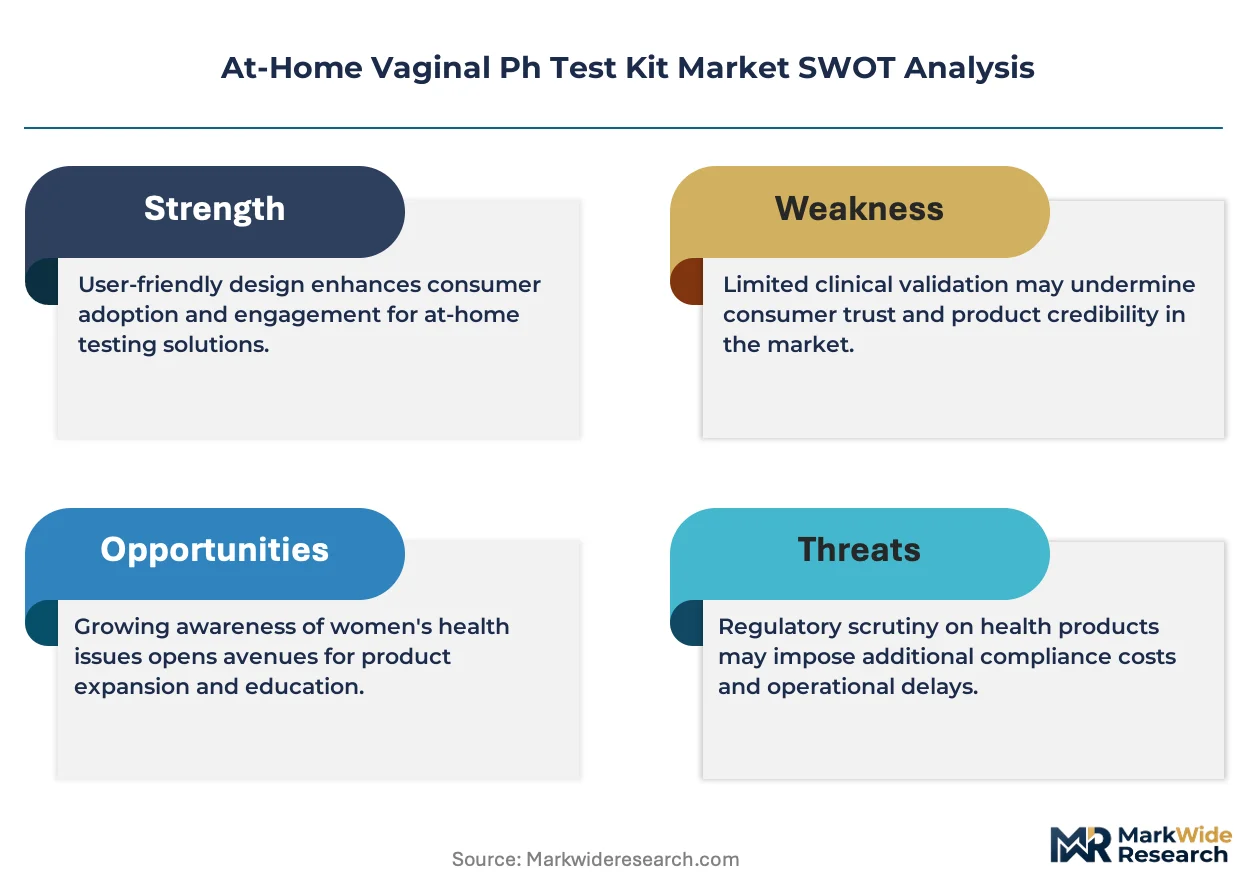
Capability concentration sits with diagnostic specialists possessing gynecological endpoint expertise; scale advantage sits with diversified healthcare conglomerates with retail distribution infrastructure. The vendor base stratifies across three tiers: multinational diagnostic manufacturers with FDA-cleared device portfolios, direct-to-consumer platforms with integrated telehealth workflows, and private-label suppliers serving pharmacy chains. Dominant competitive moves include strategic partnerships between hardware manufacturers and virtual care platforms, plus portfolio diversification into perimenopausal monitoring applications.
Within the multinational diagnostic tier, Abbott Laboratories and Bayer AG exemplify scale-driven supply reliability across retail and digital channels. Among direct-to-consumer platforms, Everlywell occupies a position representing integrated lab-to-app workflows that extend customer lifetime value beyond initial hardware purchases. These three anchors illustrate the bifurcation between manufacturing scale economics and data platform monetization models reshaping margin distribution in the sector.
| Leading Market Players |
|---|
| Abbott Laboratories |
| OraSure Technologies, Inc. |
| Everlywell |
| LetsGetChecked |
| Bayer AG |
| Prestige Consumer Healthcare, Inc. |
| Vagisil |
| Stix |
| Clearblue |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific container freight corridors linking Shanghai to Long Beach transmit cost volatility directly into landed costs for nitrazine yellow indicator chemistry, compressing margins for test strip assemblers while amplifying price spreads between Asian-manufactured generics and FDA-cleared premium tiers.
Pricing Analysis
Long-term offtake contracts for indicator dye supply anchor pricing stability for established manufacturers, while spot-market procurement exposes smaller assemblers to bromocresol green price swings. Three-tier pricing structure across premium, standard, and economy levels separates Bluetooth-integrated digital testers from pharmacy retail strips from unbranded multi-use pH substitutes. Pricing pressure stems from urinary pH strip substitution eroding perceived vaginal-specific value. Fertility-tracking app subscribers show lowest price sensitivity; uninsured cash-pay pharmacy customers exhibit highest.
Supply Chain Analysis
Export-control restrictions on solid-state electrochemical sensor technology limit component flows from certain jurisdictions into domestic manufacturing. Indicator chemistry synthesis concentrates in China, India, and South Korea; cellulose substrate production draws from Indonesian pulp mills. Supply chain risk centers on single-source vulnerability for nitrazine yellow precursors. Distribution runs through direct-to-consumer platforms, pharmacy chain fulfillment centers, and telehealth-integrated subscription logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
At-home vaginal pH testing sits in early-cycle expansion as telehealth bundling normalizes diagnostic self-monitoring among perimenopausal and fertility-focused demographics previously underserved by clinical access.
For Market Incumbents: Build regulatory data moats through expanded FDA 510(k) clearance portfolios that block private-label entrants from pharmacy chain placement. Deepen backward integration into indicator chemistry synthesis to escape Asian specialty chemical supply bottlenecks. Counter electrochemical biosensor commoditization by embedding proprietary algorithmic interpretation layers that lock users into platform ecosystems. For New Entrants and Emerging Players: Establish a beachhead in perimenopausal monitoring white space where dedicated product offerings remain scarce and customer acquisition costs run below fertility-tracking saturation. Medicaid telehealth reimbursement expansion in underserved US states offers the most penetrable geography. Deploy asynchronous physician review workflows as the primary go-to-market angle rather than hardware-first positioning. For Investors and Strategic Acquirers: Telehealth-integrated diagnostic platforms with recurring consultation revenue represent the highest-conviction acquisition archetype for portfolio exposure to virtual care monetization. Long-term viability hinges on sustained policy support for remote diagnostic reimbursement rather than one-time kit margin capture. Watch state-level Medicaid telehealth parity legislation as the critical inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Partnership | Integrates diagnostic hardware into recurring consultation revenue streams beyond one-time kit sales. |
| FDA 510(k) Clearance Expansion | Unlocks pharmacy chain placement and validates accuracy claims that drive consumer trust. |
| Perimenopausal Product Line Extension | Captures underserved hormonal transition tracking demand with limited incumbent competition. |
| Bluetooth-LTE Connectivity Development | Enables real-time clinician alerts without smartphone dependency for rural deployment channels. |
| Eco-Friendly Packaging Transition | Aligns with EU Green Deal directives for European market access and sustainability-motivated purchasers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with gynecologists, fertility clinic administrators, direct-to-consumer platform executives, biomedical engineers, and pharmacy chain category buyers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body databases, hospital procurement records, and telehealth reimbursement policy trackers. Bottom-up shipment modeling and top-down macroeconomic calibration were triangulated to anchor volume estimates.
Calibration against historical adoption curves for comparable self-testing categories refined the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, delivery mode integration depth, target audience clinical sophistication, and metropolitan infrastructure density. CAGRs were derived from fitted growth curves rather than linear extrapolation. Fertility app subscriber penetration rates and Medicaid telehealth parity expansion timelines served as industry-specific forecast inputs.
Stress conditions across FDA review cycle duration, indicator chemistry supply disruption, and telehealth reimbursement policy reversal were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about virtual care platform scaling and consumer diagnostic literacy evolution. Cross-checking against CMS Medicare telehealth utilization benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Mexico Electrocardiograph (ECG) Market
Medical Devices
Surgical Smart Glasses Market
Medical Devices
Electroencephalogram (EEG) Caps Market
Medical Devices
Laryngeal Masks Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Digital BTE Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Dialysis Catheters Market
Medical Devices
Global Artificial Organ Market
Medical Devices
Passive Prosthetics Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
US Medical Bionic Implants & Artificial Organs Market
Medical Devices
Single-Lead ECG Monitors Market
Medical Devices
Americas Medical Suction Device Market
Medical Devices
Infant Radiant Warmer Market