
 Global Hemorrhoid Treatment Devices Market | 2026-2036
Global Hemorrhoid Treatment Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hemorrhoid Treatment Devices Market Foresight
A shortage of trained proctology specialists is collapsing access timelines in outpatient settings across multiple countries. Boston Scientific Corporation leverages its endoscopy portfolio to sustain presence in office-based ligation systems. Medtronic Plc anchors its position through integrated energy platforms that span gastrointestinal interventions. Johnson & Johnson competes on brand strength in surgical stapling and advanced energy devices for hemorrhoidectomy procedures.
Hemorrhoid treatment devices are medical instruments designed to apply mechanical, thermal, or energy-based intervention to vascular tissue in the anal canal, typically operating at controlled temperatures between 60°C and 100°C for coagulation or at cryogenic ranges below −20°C for tissue destruction. These devices serve the primary commercial purpose of enabling same-session treatment in ambulatory settings, reducing operative room dependency and recovery duration. Rubber band ligators and infrared coagulators occupy mature margin pools where reimbursement codes are well-established, while laser therapy machines represent the fastest-growing segment as diode and CO2 platforms gain traction in private proctology clinics. Bipolar diathermy devices dominate hospital procurement for thrombosed hemorrhoid cases where precise thermal control reduces mucosal injury risk.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for energy-based hemorrhoid devices. ISO 13485 quality management standards govern manufacturing consistency across Boston Scientific, Medtronic, and Cook Medical production facilities. Stakeholders must monitor evolving NICE interventional procedures guidance and CMS reimbursement decisions for office-based treatments as these directly determine adoption velocity in ambulatory surgical centers.
Market Dynamics
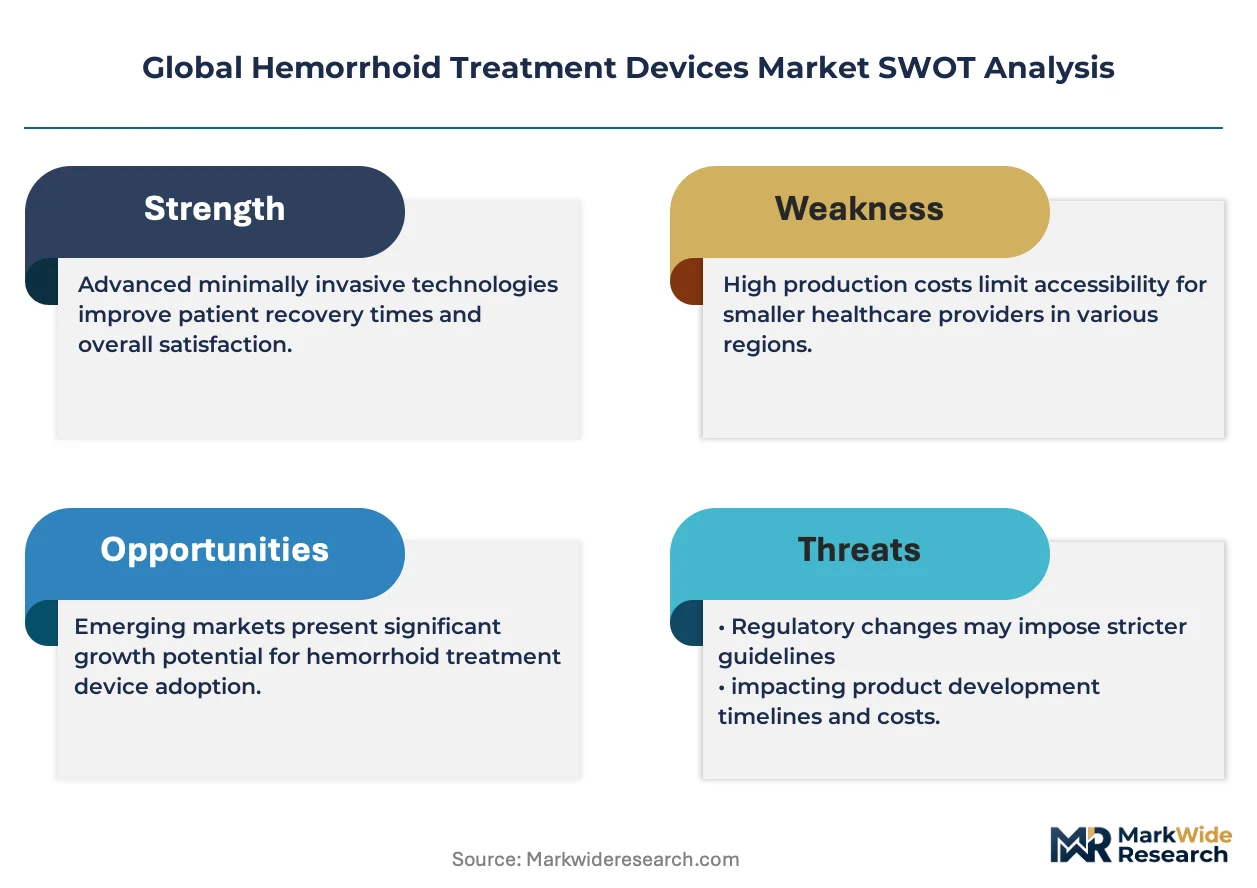
Minimally invasive thermal and mechanical ligation technologies are collapsing traditional hemorrhoidectomy volumes by shifting procedures from operating rooms to ambulatory suites, compressing hospital revenue per case while expanding total treatable population.
Growth Catalysts
- FDA 510(k) clearance streamlining:Accelerated pathways for predicate-based energy devices reduce time-to-market for bipolar diathermy platforms targeting thrombosed hemorrhoid cases.
- Ambulatory surgical center expansion:United States facility growth in dedicated proctology service lines creates captive demand for same-session ligation and coagulation systems.
- Diode laser platforms:Wavelength-tunable systems enable precise tissue ablation with reduced mucosal injury risk, driving replacement cycles in private German and Japanese clinics.
Market Restraints
- Specialist training pipeline collapse:Proctology fellowship vacancies in United States academic medical centers limit procedure volume expansion regardless of device availability.
- Reimbursement code lag:CMS and German statutory insurers maintain differential payment gaps between office-based ligation and surgical hemorrhoidectomy, distorting site-of-care decisions.
- Capital equipment intensity:CO2 laser platforms require dedicated maintenance contracts and controlled-environment installation, raising total cost of ownership for independent practices.
Strategic Opportunities
- India outpatient penetration:Underserved urban middle-class populations in Mumbai and Delhi present first-mover potential for infrared coagulator placement in multi-specialty clinics.
- EU MDR Article 117 convergence:Drug-device combination requirements for hemostatic adjuncts create regulatory moats for integrated platform suppliers with established quality management systems.
- Telehealth-integrated follow-up:Remote post-procedure monitoring protocols reduce in-person visit burden, enabling volume scaling in United Kingdom NHS community settings.
Industry Challenges
- ISO 13485 audit compression:Notified body backlogs for energy-based surgical device recertification under EU MDR delay product launches by 12-18 months.
- Legacy EMR integration:Proprietary data formats from ligation system consoles fail to map cleanly to Epic and Cerner anesthesia modules, forcing manual documentation workflows.
- Sterilization validation complexity:Reusable bipolar probe reprocessing protocols require cycle-specific bioburden studies that strain quality assurance bandwidth at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hemorrhoid Treatment Devices Market |
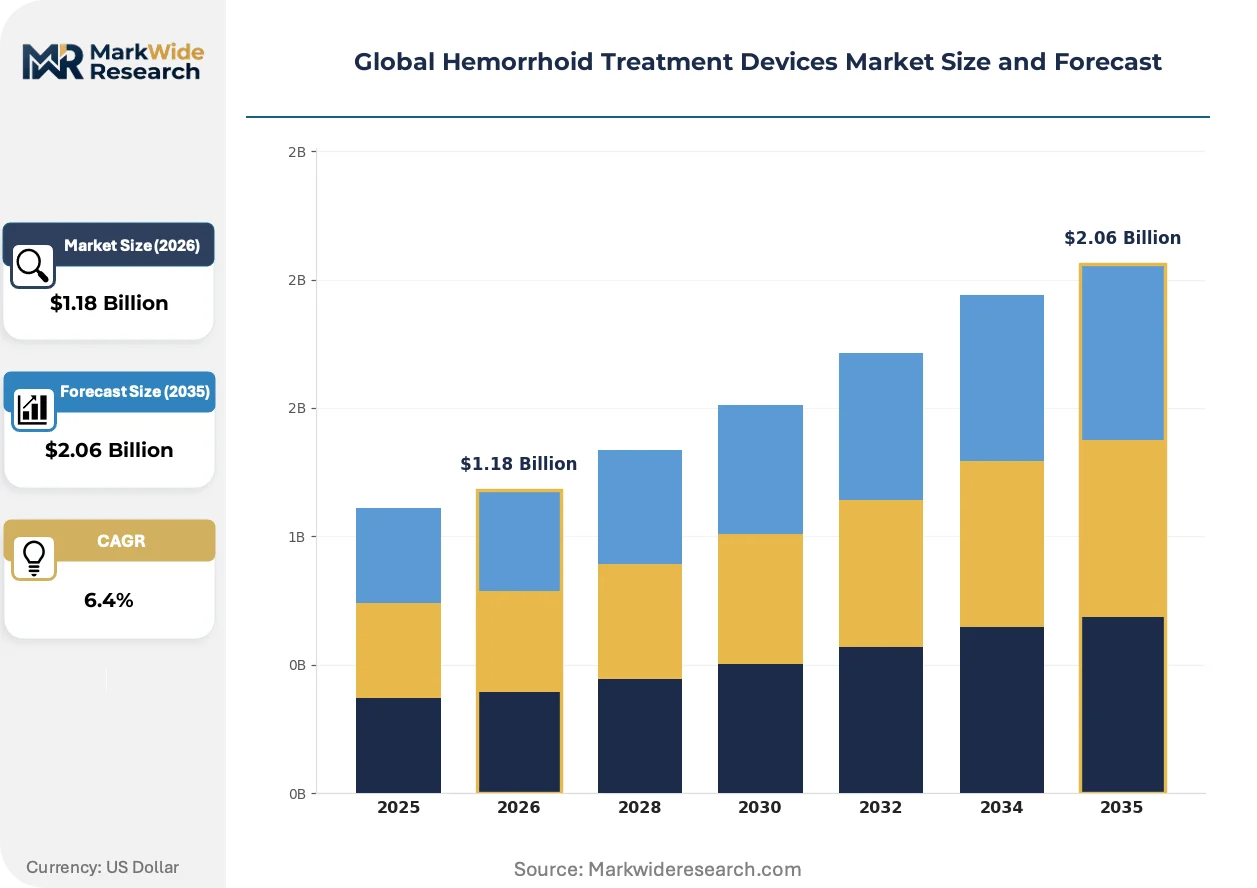
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Band Ligators, Infrared Coagulators, Laser Therapy Machines, Bipolar Diathermy Devices, Cryotherapy Equipment Therapy Area: External Hemorrhoids, Internal Hemorrhoids, Thrombosed Hemorrhoids, Prolapsed Hemorrhoids End User: Ambulatory Surgical Centers, Gastroenterology Clinics, Proctology Specialists, Outpatient Care Facilities Delivery Mode: Minimally Invasive Procedures, Non-Surgical Techniques, Surgical Interventions, Office-Based Treatments |
| Companies Covered | Boston Scientific Corporation, Medtronic Plc, Cook Medical, Integra LifeSciences Corporation, Johnson & Johnson, CONMED Corporation, OBP Medical Corporation, Teleflex Incorporated, Privi Medical Pte. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hemorrhoid Treatment Devices Market Shifts & Advancements
Device miniaturization and energy delivery precision are converging to enable procedure migration from hospital-based operating suites to office-based settings, fundamentally restructuring site-of-care economics and capital deployment patterns across developed markets.
Radiofrequency ablation catheters with impedance-feedback control are decomposing the traditional surgical hemorrhoidectomy by enabling targeted mucosal fixation without excision. Gastroenterology clinics in Japan and Germany are adopting these platforms at replacement-cycle velocity. The technology is decomposing hospital outpatient department revenue streams while expanding total addressable procedure volume through reduced anesthesia requirements.
EU Medical Device Regulation Annex XVI expansion is reclassifying certain energy-based tissue modification devices, forcing retrospective clinical evidence generation for legacy infrared coagulators. Manufacturers with predicate device portfolios face disproportionate compliance burdens. United Kingdom proctology service lines are deferring procurement decisions pending NICE interventional procedures guidance updates anticipated under post-Brexit regulatory divergence.
Direct-to-facility purchasing by ambulatory surgical centers is bypassing traditional distributor networks for high-value laser platforms, compressing channel margins and forcing manufacturers to build captive clinical specialist teams. United States multi-site ASC chains are consolidating vendor panels to three preferred suppliers, privileging integrated energy platform vendors with dedicated proctology application training infrastructure.
Global Hemorrhoid Treatment Devices Market Segmentation
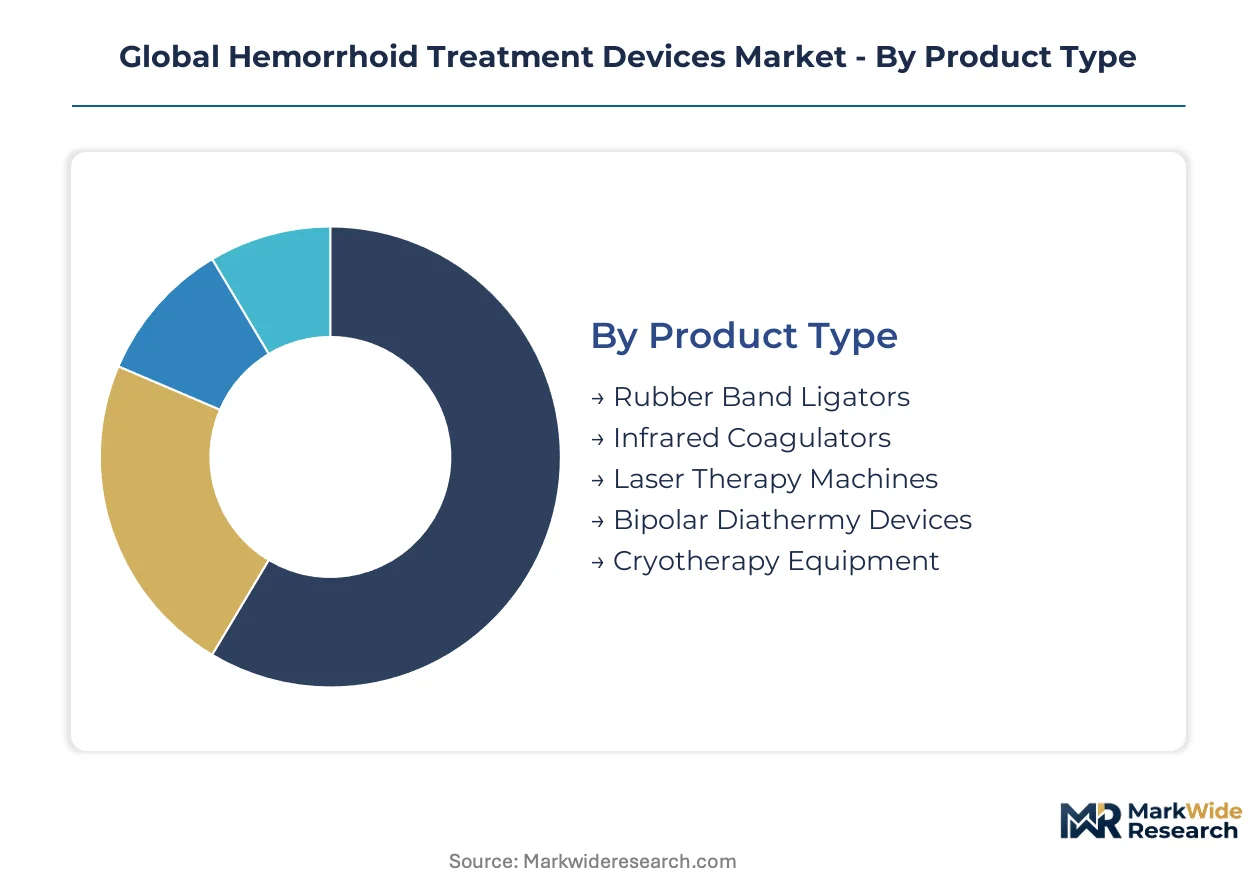
Channel economics in hemorrhoid treatment diverge sharply between capital-intensive laser platforms sold direct to ambulatory surgical centers and disposable ligation kits moving through medical distributors. Understanding segment-channel alignment reveals where procurement consolidation and margin compression concentrate.
Product Type:
Rubber band ligators and infrared coagulators flow through established distributor networks to outpatient clinics, while laser therapy machines bypass intermediaries via manufacturer-direct sales teams.
- Rubber Band Ligators:Mechanical devices apply elastic constriction to hemorrhoidal tissue at the dentate line, utilizing single-use bands loaded onto reusable applicators. Demand clusters in United States gastroenterology clinics where CMS reimbursement codes for office-based ligation remain well-established. Procurement runs through Cardinal Health and McKesson distribution channels with high volume, low margin economics.
- Laser Therapy Machines:Diode and CO2 platforms deliver precise thermal ablation at 980nm or 10600nm wavelengths with adjustable power settings from 5W to 30W. German and Japanese private proctology clinics drive replacement cycles as wavelength-tunable systems displace older infrared units. Direct-to-facility purchasing compresses traditional distributor margins and forces manufacturers to maintain captive clinical specialist teams.
- Infrared Coagulators:Solid-state generators produce controlled thermal injury at 150W peak output through handheld probes, dominating mature margin pools where predicate device pathways simplify regulatory entry.
- Bipolar Diathermy Devices:Precise thermal control between 60°C and 100°C reduces mucosal injury risk in thrombosed hemorrhoid cases, anchoring hospital procurement decisions.
- Cryotherapy Equipment:Nitrous oxide or liquid nitrogen systems achieve tissue destruction below −20°C, occupying niche positions in select European markets with limited United States adoption.
Rubber band ligators dominate installed base. Laser therapy machines are where expansion concentrates.
Therapy Area:
Procedure complexity and anesthesia requirements segment therapy areas into distinct reimbursement tiers, with external and thrombosed presentations commanding higher facility fees.
- Internal Hemorrhoids:Graded I through III presentations respond to office-based mechanical and thermal interventions without sedation. Volume concentrates in ambulatory settings across United States, Germany, and Japan where same-session treatment protocols minimize operative room dependency.
- Thrombosed Hemorrhoids:Acute vascular compromise requires precise thermal control to prevent mucosal injury, driving demand for bipolar diathermy platforms in hospital outpatient departments.
- External Hemorrhoids:Cutaneous presentations below the dentate line often necessitate surgical excision rather than energy-based approaches.
- Prolapsed Hemorrhoids:Grade IV presentations with manual reduction failure typically require hemorrhoidectomy rather than device-based intervention.
Internal hemorrhoids anchor procedure volume. Thrombosed presentations concentrate premium device placement.
End User:
Site-of-care migration reshapes end user economics, with gastroenterology clinics capturing cases previously routed to hospital outpatient departments.
- Ambulatory Surgical Centers:Multi-site chains in the United States consolidate vendor panels to three preferred suppliers, privileging integrated energy platform vendors with dedicated proctology training infrastructure. Captive demand for same-session ligation and coagulation systems expands with dedicated proctology service line development.
- Gastroenterology Clinics:Office-based settings in Japan and Germany adopt radiofrequency ablation platforms at replacement-cycle velocity, decomposing traditional surgical hemorrhoidectomy volumes.
- Proctology Specialists:Fellowship-trained practitioners in academic medical centers limit procedure expansion regardless of device availability due to training pipeline constraints.
- Outpatient Care Facilities:United Kingdom NHS community settings defer procurement pending NICE interventional procedures guidance updates anticipated under post-Brexit regulatory divergence.
Ambulatory surgical centers dominate capital equipment procurement. Gastroenterology clinics concentrate volume expansion.
Delivery Mode:
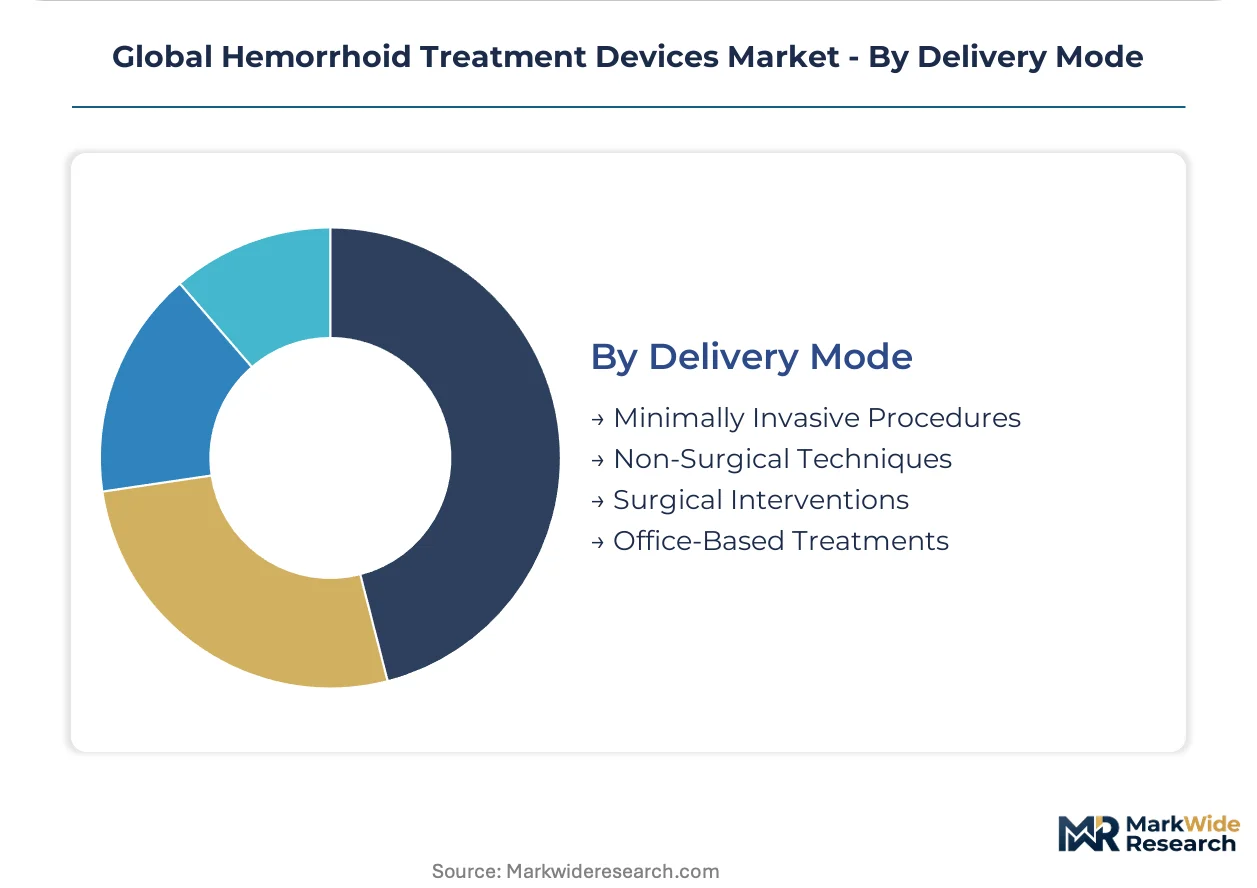
Reimbursement differentials between office-based and surgical settings distort site-of-care decisions regardless of clinical appropriateness.
- Minimally Invasive Procedures:Radiofrequency ablation and laser coagulation enable targeted mucosal fixation without excision, collapsing traditional hemorrhoidectomy volumes in developed markets.
- Office-Based Treatments:Rubber band ligation and infrared coagulation reduce anesthesia requirements and recovery duration, expanding total treatable population.
- Non-Surgical Techniques:Sclerotherapy and cryotherapy occupy declining share as thermal methods demonstrate superior efficacy profiles.
- Surgical Interventions:Hemorrhoidectomy and stapled procedures retain position for Grade IV and complicated presentations despite device-based displacement trends.
Minimally invasive procedures dominate new investment. Office-based treatments concentrate margin defense.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways and CMS reimbursement decisions anchor commercial strategy in the United States, while EU MDR compliance timelines and NICE guidance updates shape European procurement patterns. Device manufacturers navigate divergent regulatory velocities across three major markets.
United States
Ambulatory surgical center expansion drives captive demand for same-session ligation systems. CMS maintains differential payment gaps between office-based treatments and surgical hemorrhoidectomy. Multi-site ASC chains in Texas and Florida consolidate vendor panels to three preferred suppliers.
Germany
Private proctology clinics in Munich and Hamburg adopt wavelength-tunable diode laser platforms at replacement-cycle velocity. CE marking under EU MDR tightens quality benchmarks for energy-based surgical devices. Statutory insurance reimbursement codes lag behind technology adoption.
Japan
Gastroenterology clinics in Tokyo and Osaka deploy radiofrequency ablation catheters with impedance-feedback control. METI standards govern medical device manufacturing consistency. Aging demographics expand the addressable patient population for minimally invasive interventions.
United Kingdom
NHS community settings defer procurement decisions pending NICE interventional procedures guidance updates. Post-Brexit regulatory divergence from EU MDR creates compliance uncertainty. London proctology service lines pilot telehealth-integrated follow-up protocols.
India
Underserved urban middle-class populations in Mumbai and Delhi present first-mover potential for infrared coagulator placement. CDSCO regulates medical device imports and quality standards. Multi-specialty clinics in metropolitan corridors expand outpatient procedural capacity.
Global Hemorrhoid Treatment Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in hemorrhoid treatment devices. Boston Scientific Corporation, Medtronic Plc, and Johnson & Johnson command premium positions through endoscopy portfolios, integrated energy platforms, and surgical stapling franchises respectively. Mid-tier manufacturers compete on predicate device pathways and distributor relationships. Consolidation pressures concentrate around direct-to-facility purchasing models and captive clinical specialist team requirements. Strategic partnerships and portfolio diversification represent dominant competitive moves as reimbursement complexity escalates.
Within the integrated platform tier, Boston Scientific Corporation and Medtronic Plc exemplify archetypes built on endoscopy and energy system breadth. Johnson & Johnson occupies a position representing surgical device brand strength. These three entities anchor the competitive structure through established quality management systems and dedicated proctology application training infrastructure. Smaller specialists including Cook Medical and CONMED Corporation sit within the predicate-device tier, competing on regulatory pathway efficiency and distributor channel access.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic Plc |
| Cook Medical |
| Integra LifeSciences Corporation |
| Johnson & Johnson |
| CONMED Corporation |
| OBP Medical Corporation |
| Teleflex Incorporated |
| Privi Medical Pte. Ltd. |
| Others |
Supply & Pricing Matrix
Diode laser platforms displacing infrared coagulators in German and Japanese private clinics simultaneously redraw procurement geography toward direct-to-facility channels and compress distributor margins by eliminating intermediary markups on capital equipment.
Pricing Analysis
Price spreads between United States ambulatory surgical centers and Indian multi-specialty clinics exceed threefold for identical infrared coagulator platforms. Three-tier pricing structure across premium, standard, and economy levels segments by FDA 510(k) clearance tier and bundled clinical training. Pricing pressure stems from ASC vendor panel consolidation privileging integrated platform suppliers. Independent gastroenterology practices exhibit highest price sensitivity; hospital outpatient departments demonstrate lowest.
Supply Chain Analysis
United States, Germany, and Japan anchor finished device manufacturing for energy-based surgical platforms. Supply chains draw from Chinese diode laser component suppliers, Japanese precision optics manufacturers, and German solid-state generator producers. Single-source vulnerability concentrates in 980nm wavelength diode modules. Distribution runs through Cardinal Health and McKesson for disposable ligation kits; laser platforms ship direct via manufacturer captive sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Office-based procedure migration represents an early-cycle expansion story justified by ambulatory surgical center service line development outpacing hospital outpatient department growth across developed markets.
For Market Incumbents: Compound endoscopy portfolio breadth into dedicated proctology training infrastructure to defend against direct-to-facility purchasing compression. Deepen backward integration into diode laser component supply to offset Chinese supplier concentration risk. Prioritize ISO 13485 recertification velocity under EU MDR to exploit notified body backlogs delaying rival launches. For New Entrants and Emerging Players: Anchor in India's underserved urban middle-class corridor where infrared coagulator placement lags procedural demand in Mumbai and Delhi multi-specialty clinics. Target telehealth-integrated follow-up protocols as differentiated service bundling for NHS community settings awaiting NICE guidance. Pursue predicate device pathway efficiency for accelerated FDA 510(k) clearance against established infrared platforms. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors integrated energy platform vendors with captive clinical specialist teams. Five-to-ten year viability hinges on reimbursement code expansion for office-based thermal interventions. Acquisition target archetype: mid-tier manufacturers with established predicate device portfolios and distributor relationships in lagging geographies. Monitor CMS reimbursement parity decisions between ligation and hemorrhoidectomy as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 117 compliance creates regulatory moats for integrated platform suppliers with established quality systems. |
| Hospital System Partnership | Multi-site ASC chains in Texas and Florida consolidate vendor panels to three preferred suppliers with dedicated training infrastructure. |
| Reimbursement Strategy | CMS office-based treatment code parity drives adoption velocity in ambulatory surgical centers over hospital outpatient departments. |
| Software Companion Development | Epic and Cerner EMR integration resolves manual documentation workflows from proprietary ligation console data formats. |
| FDA Submission | Accelerated 510(k) pathways for predicate-based bipolar diathermy platforms reduce time-to-market for thrombosed hemorrhoid indications. |
Research Methodology
A standing panel of proctology specialists, ASC purchasing directors, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, EU MDR notified body registries, and hospital procurement contract disclosures. Bottom-up device shipment analysis triangulated against top-down procedure volume estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, therapy area complexity grading, end-user site-of-care tier, and delivery mode reimbursement classification. CAGRs derived from procedure volume elasticity to specialist workforce expansion and technology replacement cycle timing. Forecast inputs incorporated ambulatory surgical center facility growth trajectories and NICE interventional procedures guidance revision probability.
Material uncertainties — specialist training pipeline collapse, reimbursement code lag, and EU MDR recertification delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding procedural migration velocity and regulatory pathway efficiency. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Operating Microscopes Market
Medical Devices
Global Gynecological Dilators Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Veterinary Procedure Lights Market
Medical Devices
Sensor Based Smart Catheters Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Digital Magnifiers Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Global Surgical Navigation System Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
Ostomy Drainage Systems Market
Medical Devices
Global Mucosal Atomization Devices Market
Medical Devices
North America Non-Surgical Procedures Market