
 Global Disposable Medical Sensors Market | 2026-2036
Global Disposable Medical Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disposable Medical Sensors Market Foresight
Hospital-grade sterility certification is collapsing into a baseline expectation for even mid-tier disposable sensors. Medtronic plc leverages its vertically integrated sterilization network to sustain cost advantages across glucose and pressure sensor lines. Abbott Laboratories dominates electrochemical sensor R&D through captive materials science capabilities, while Philips Healthcare anchors European hospital procurement with bundled patient monitoring systems.
Disposable medical sensors are single-use transducers manufactured from biocompatible polymers, conductive inks, and thin-film substrates that convert physiological signals into measurable electrical or optical outputs for clinical decision-making. These devices eliminate cross-contamination risks in acute and ambulatory settings through guaranteed sterility and predetermined functional lifespans. Glucose sensors and pulse oximeters capture disproportionate margin pools due to chronic disease management volumes, whereas electrochemical technology leads in miniaturization trajectories for wearable formats. Pressure sensors retain structural importance in surgical and critical care applications where real-time hemodynamic feedback governs outcomes.
FDA 510(k) pathways and EU MDR conformity assessments shape market access timelines and clinical evidence burdens for disposable sensor manufacturers seeking multi-regional distribution. ISO 13485 quality management systems and IEC 60601 electrical safety standards further constrain design flexibility while raising barriers for entrants lacking established regulatory affairs infrastructure. Stakeholders must monitor how FDA's evolving cybersecurity guidance for connected devices intersects with disposable sensor wireless data transmission architectures.
Market Dynamics
FDA sterility validation mandates for Class II devices are compressing manufacturer margins while simultaneously elevating entry barriers for non-integrated producers. This regulatory pressure is forcing consolidation around captive sterilization infrastructure.
Growth Catalysts
- Home Healthcare Expansion:Decentralized care infrastructure in Germany, the United States, and Japan is pulling single-use monitoring devices into ambulatory settings. Chronic disease management volumes sustain glucose sensor deployment.
- EU MDR Conformity Pathways:Streamlined multi-regional distribution access is accelerating hospital procurement standardization across European markets. Bundled patient monitoring systems anchor volume commitments.
- Thin-Film Substrate Miniaturization:Electrochemical technology advances are enabling wearable format penetration. Biocompatible polymer integration supports predetermined functional lifespans.
Market Restraints
- Sterilization Input Cost Volatility:Ethylene oxide and gamma irradiation capacity constraints in North America are squeezing contract sterilization pricing. Captive facility construction demands 18-24 month lead times.
- Technical Limitation in Wireless Architectures:Battery integration in single-use formats restricts continuous monitoring duration. Energy harvesting from physiological signals remains pre-commercial.
- Regulatory Friction from FDA Cybersecurity Guidance:Connected disposable sensors face evolving data transmission security requirements. 510(k) pathway documentation burdens extend review timelines.
Strategic Opportunities
- Underpenetrated Surgical Robotics Integration:Pressure sensor demand from robotic-assisted procedures in South Korea and Switzerland outpaces current supply alignment. Real-time hemodynamic feedback modules represent white space.
- Technology Convergence:Optical glucose sensing combined with NFC data transmission is creating smartphone-integrated chronic care formats. Consumer electronics supply chains offer cost structure advantages.
- PLI Scheme Tailwinds:India's production-linked incentive framework for medical devices is attracting electrochemical sensor manufacturing investments. Export-oriented units target Middle East and Southeast Asian hospital procurement.
Industry Challenges
- ISO 13485 Talent Scarcity:Quality management system auditors with disposable sensor-specific experience command premium compensation. Regulatory affairs infrastructure gaps constrain mid-tier expansion.
- Legacy Hospital IT Integration Complexity:Wireless disposable sensors must interface with proprietary patient data architectures. HL7 FHIR standard adoption remains uneven across German hospital networks.
- Capex Intensity for Cleanroom Expansion:Class 7 and Class 8 manufacturing environments require specialized HVAC and environmental monitoring systems. Depreciation schedules compress return-on-investment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disposable Medical Sensors Market |
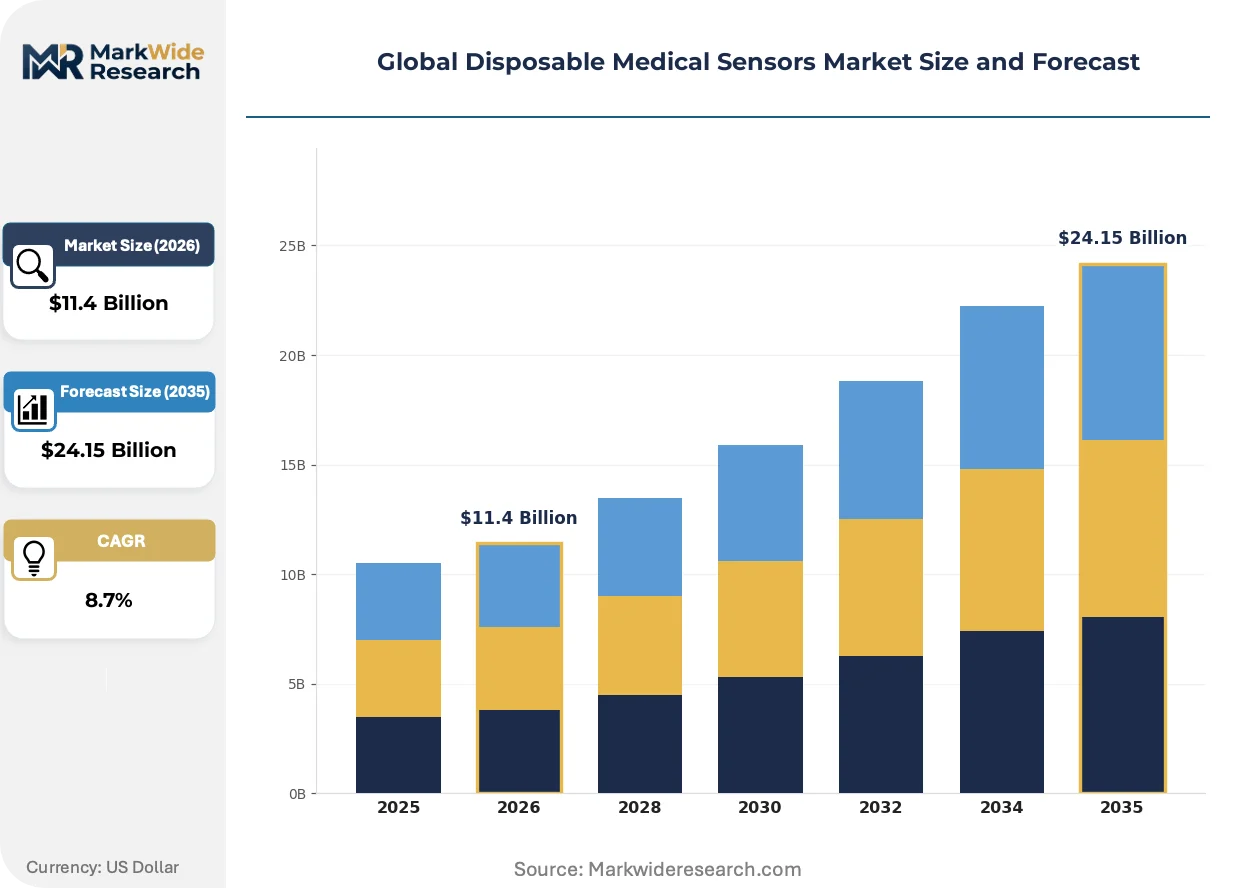
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Glucose Sensors, Pulse Oximeters, Electrochemical Sensors Technology: Optical, Electrochemical, Piezoelectric, Capacitive, Resistive Application: Patient Monitoring, Chronic Disease Management, Surgical Procedures, Diagnostics, Rehabilitation End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Home Healthcare Providers |
| Companies Covered | Medtronic plc, Abbott Laboratories, Philips Healthcare, GE Healthcare, Honeywell International Inc., TE Connectivity, Sensirion AG, Smiths Medical, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disposable Medical Sensors Market Shifts & Advancements
Printed electronics and biodegradable substrate integration are compressing cost structures while introducing new end-of-life management obligations. These material shifts are reshaping competitive positioning around sustainability credentials.
Printed electronics using silver nanowire conductive inks is fragmenting traditional PCB-based sensor manufacturing. German diabetes management clinics are adopting these formats at twice the rate of Southern European markets. The technology is fragmenting procurement patterns as hospitals unbundle single-use components from legacy monitoring system vendors.
EU MDR Article 10 technical documentation requirements are extending conformity assessment timelines for wireless-enabled disposables. Manufacturers must demonstrate clinical evidence for software-controlled measurement algorithms. Pulse oximetry modules with Bluetooth transmission face the steepest evidence burdens, compressing product refresh cycles.
Hospital procurement departments are consolidating vendor panels around integrated sterilization-to-distribution capabilities. Group purchasing organizations in the United States are displacing individual hospital negotiations with multi-year sensor supply agreements. This concentration is most visible in cardiovascular catheterization lab purchasing across Texas and California health systems.
Global Disposable Medical Sensors Market Segmentation
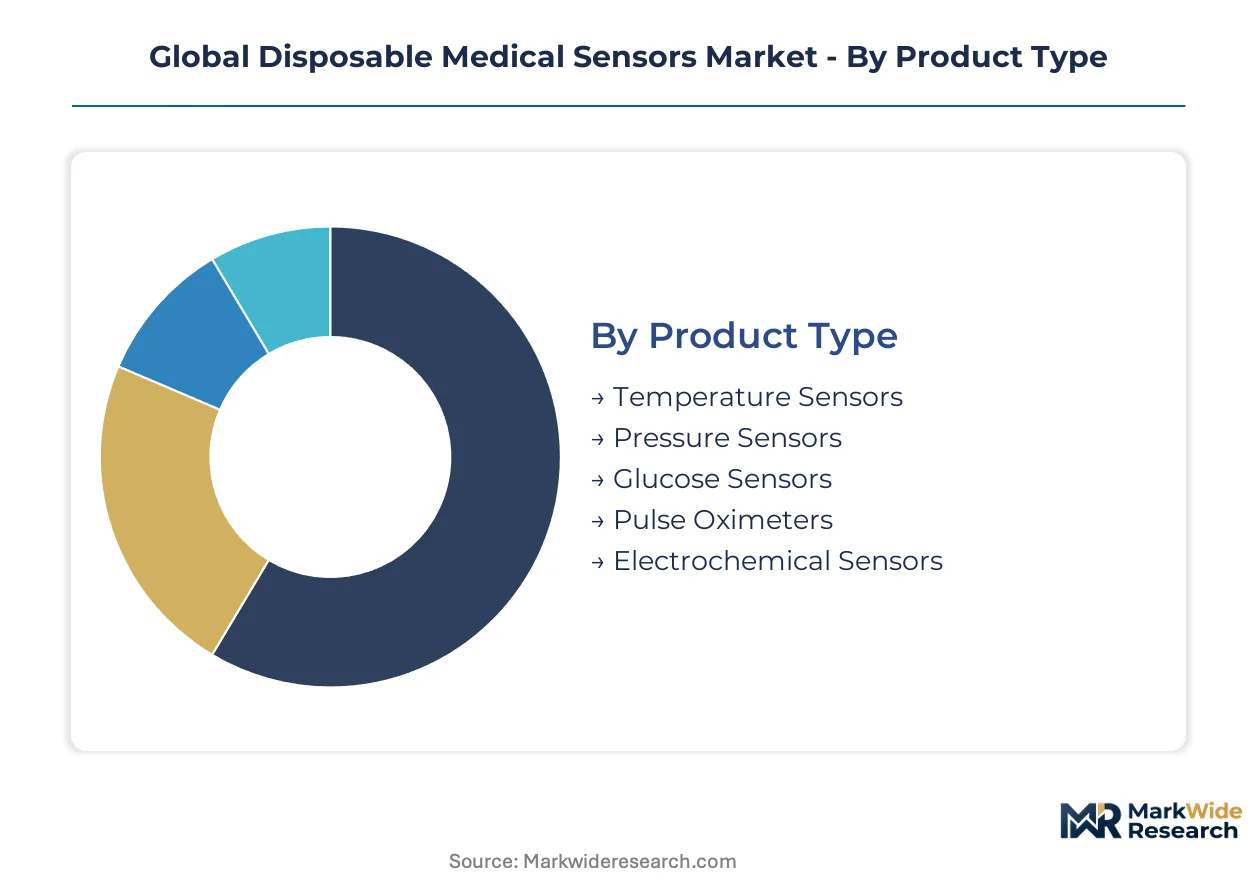
Disposable medical sensor segmentation reveals how regulatory pathways, reimbursement structures, and clinical workflows fragment procurement patterns across acute and ambulatory settings. Each dimension carries distinct sterility validation burdens and supply chain configuration requirements.
Product Type:
FDA Class II sterility mandates compress margins most severely for implant-adjacent formats, while EU MDR technical documentation extends timelines for wireless-enabled variants.
- Glucose Sensors:Electrochemical transducers with enzymatic glucose oxidase layers dominate chronic disease management volumes. German diabetes clinics and United States home healthcare providers sustain deployment through bundled reimbursement codes.
- Pressure Sensors:MEMS-based piezoresistive elements manufactured from biocompatible polymers deliver real-time hemodynamic feedback. Surgical robotics integration in South Korea and Switzerland outpaces current supply alignment.
- Pulse Oximeters:Dual-wavelength LED-photodiode assemblies face steepest EU MDR evidence burdens for Bluetooth-enabled variants.
- Temperature Sensors:Thermistor-based single-use strips concentrate in perioperative monitoring bundles across Japanese hospital networks.
- Electrochemical Sensors:Thin-film substrate formats enable miniaturization trajectories for wearable applications in ambulatory settings.
Glucose sensors handle the majority of throughput; pressure sensors are expanding most quickly on share through surgical robotics adoption.
Technology:
Cost tier differentiation separates premium optical formats from standard electrochemical production, with piezoelectric variants occupying mid-tier positioning in surgical applications.
- Electrochemical:Enzyme-coated electrodes with conductive ink interconnects achieve lowest per-unit manufacturing costs at scale. Abbott Laboratories' captive materials science capabilities anchor R&D leadership in this layer.
- Optical:Near-infrared spectroscopy and photoplethysmography modules command premium pricing through non-invasive glucose monitoring potential. Japanese METI-funded consortia accelerate photonics integration.
- Piezoelectric:Polyvinylidene fluoride films convert mechanical strain into electrical signals for cardiovascular pressure monitoring.
- Capacitive:Parallel-plate geometries with biocompatible dielectrics serve touch-sensitive surgical instrument interfaces.
- Resistive:Strain-gauge configurations in polymer substrates deliver cost-optimized force sensing for rehabilitation devices.
Electrochemical technology captures the largest production volume; optical formats show the steepest expansion trajectory through smartphone-integrated chronic care development.
Application:
Volume concentration follows chronic disease management workflows, with surgical procedure applications demanding highest sterility assurance tiers.
- Chronic Disease Management:Continuous glucose monitoring and pulse oximetry deployment sustains recurring revenue models through disposable consumables. United States Medicare reimbursement codes and German statutory health insurance contracts stabilize procurement volumes.
- Patient Monitoring:Multi-parameter disposable patches aggregate ECG, temperature, and respiratory rate for telemetry wards. Philips Healthcare bundles anchor European hospital procurement standardization.
- Surgical Procedures:Pressure and temperature sensors require Class 7 cleanroom manufacturing with validated ethylene oxide sterilization.
- Diagnostics:Single-use electrochemical strips for point-of-care testing concentrate in Indian diagnostic laboratory networks under PLI scheme incentives.
- Rehabilitation:Force-sensitive resistors and motion-tracking disposables support physical therapy protocols in Japanese long-term care facilities.
Chronic disease management handles the majority of throughput; surgical procedures are gaining share fastest through robotic-assisted procedure expansion.
End User:
Customer type determines sterilization infrastructure requirements, with hospitals demanding captive validation and home healthcare accepting contract-sterilized formats.
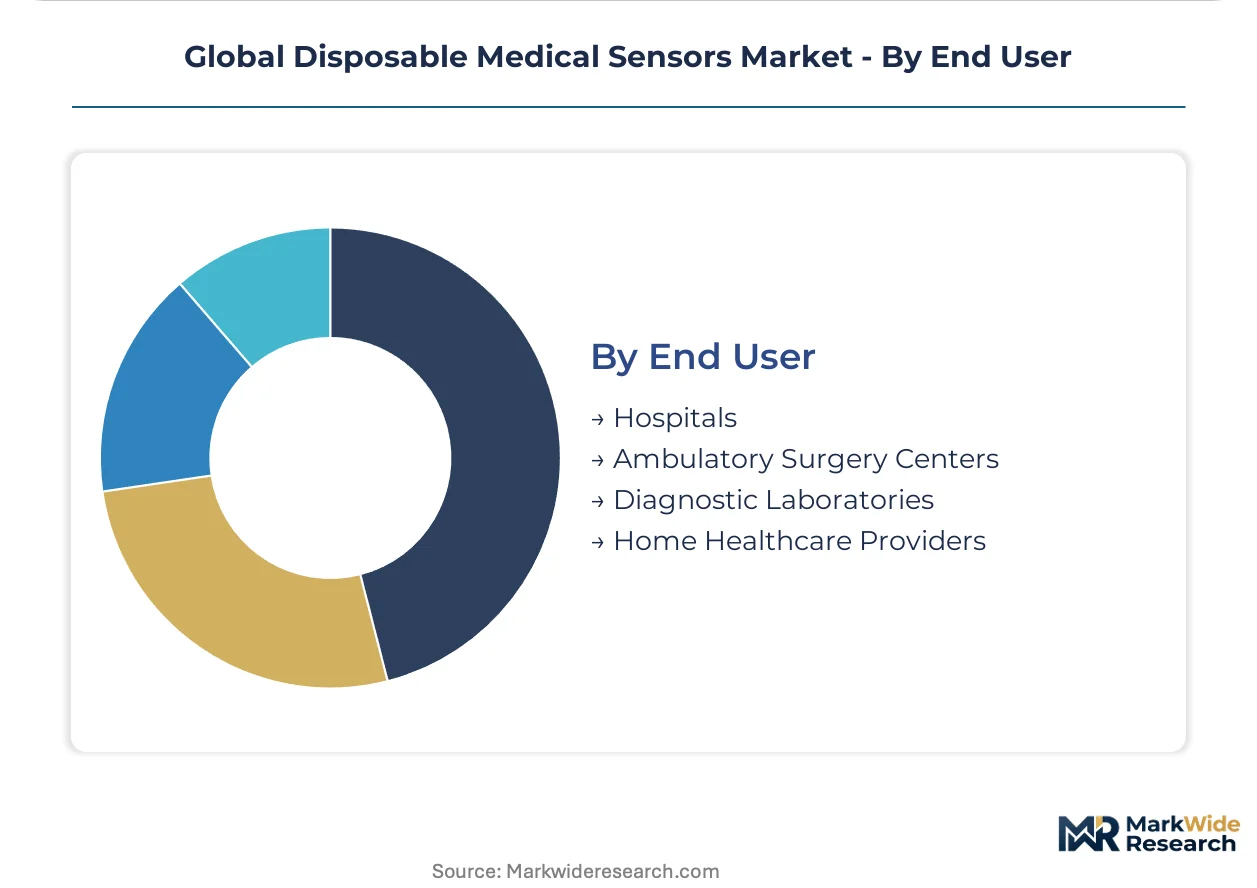
- Hospitals:Integrated delivery networks in Texas and California health systems consolidate vendor panels around sterilization-to-distribution capabilities. Group purchasing organizations displace individual hospital negotiations with multi-year supply agreements.
- Home Healthcare Providers:Decentralized care infrastructure in Germany, the United States, and Japan pulls single-use monitoring devices into ambulatory settings with simplified FDA 510(k) pathways.
- Ambulatory Surgery Centers:Lower-volume procurement concentrates on pre-sterilized bundles from distributors with same-day replenishment logistics.
- Diagnostic Laboratories:High-throughput electrochemical strip consumption drives price sensitivity and regional manufacturing sourcing.
Hospitals handle the majority of throughput; home healthcare providers are climbing the fastest on share through chronic disease management decentralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal Germany and the United States as net exporters of sterilized sensor components, while India and China balance domestic assembly with raw polymer imports. Japan maintains near-autarky in optical substrate fabrication.
United States
Decentralized care infrastructure in Texas and California health systems drives home healthcare sensor procurement. FDA sterility validation mandates for Class II devices compress margins while elevating compliance burdens. Minneapolis and Boston anchor electrochemical sensor R&D clusters where vertically integrated manufacturers sustain cost advantages.
Germany
Statutory health insurance contracts stabilize glucose sensor volumes through bundled reimbursement codes. EU MDR conformity assessments extend wireless-enabled product timelines while streamlining multi-regional distribution. Bavarian medical technology clusters concentrate cleanroom manufacturing capacity for pressure sensor exports.
Japan
METI-funded photonics consortia accelerate optical glucose sensing development for smartphone-integrated formats. PMDA regulatory pathways favor domestic manufacturers with established quality management systems. Tokyo-Osaka industrial corridors host thin-film substrate miniaturization facilities serving wearable device OEMs.
India
Production-linked incentive schemes attract electrochemical sensor manufacturing investments targeting Middle East exports. CDSCO medical device regulations tighten while remaining more permissive than FDA pathways. Gujarat and Maharashtra host export-oriented cleanroom units supplying diagnostic laboratory networks.
South Korea
Robotic-assisted surgical procedure expansion outpaces pressure sensor supply alignment. MFDS sterility validation requirements mirror FDA stringency for implant-adjacent formats. Seoul-Suwon manufacturing belts concentrate MEMS-based piezoresistive element fabrication for cardiovascular applications.
Global Disposable Medical Sensors Market Competitive Landscape
Concentration sits with diversified health technology conglomerates and specialized sensor fabricators. Three to five integrated players capture disproportionate margin pools through captive sterilization networks and bundled procurement relationships. Two strategic archetypes dominate: vertically integrated device manufacturers with in-house materials science capabilities, and contract sensor specialists serving branded OEMs. Competitive moves center on cleanroom capacity expansion and regulatory affairs infrastructure acquisition.
Among diversified health technology conglomerates, Medtronic plc and Abbott Laboratories exemplify the integrated archetype through captive supply chains and direct hospital procurement relationships. Philips Healthcare occupies a position bridging European hospital system bundling with ambulatory monitoring formats. Specialized sensor fabricators including Sensirion AG and TE Connectivity represent the component-supply tier, serving OEMs lacking in-house MEMS or electrochemical fabrication. STMicroelectronics sits within the semiconductor crossover segment, leveraging wafer-scale manufacturing for disposable transducer cost structures. These five entities collectively span the value chain from substrate fabrication through sterilized finished device distribution.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Philips Healthcare |
| GE Healthcare |
| Honeywell International Inc. |
| TE Connectivity |
| Sensirion AG |
| Smiths Medical |
| STMicroelectronics |
| Others |
Supply & Pricing Matrix
FDA Class II sterility validation requirements gate both supplier qualification and price differentiation simultaneously, compressing margins for non-integrated manufacturers while rewarding captive sterilization networks with pricing power over hospital procurement committees.
Pricing Analysis
Hospital procurement committees anchor contract-based long-term offtake structures, with three-tier pricing separating FDA-cleared premium formats from CE-marked standard variants and economy-grade unconnected strips. Price differentiation rests on certification grade and volume scale, with German statutory health insurance contracts stabilizing glucose sensor procurement at scale. Cost compression in mid-tier electrochemical strips is intensifying because ethylene oxide sterilization capacity constraints squeeze contract manufacturers. Diagnostic laboratories exhibit highest price sensitivity; integrated delivery networks in Texas and California health systems demonstrate lowest sensitivity due to bundled reimbursement codes.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for biocompatible polymer raw materials sourced from German and Japanese chemical suppliers. Manufacturing concentrates in Germany, the United States, and Japan, with thin-film substrate fabrication drawing from captive photonics capabilities in Tokyo-Osaka industrial corridors. Raw material dependencies center on silver nanowire conductive inks, polyvinylidene fluoride films, and enzymatic glucose oxidase layers. Single-source vulnerability in gamma irradiation capacity creates supply chain risk. Distribution runs through group purchasing organizations consolidating multi-year sensor supply agreements across cardiovascular catheterization labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable medical sensors are approaching a platform-economics inflection as smartphone-integrated chronic care formats and NFC data transmission architectures create interoperability dependencies with consumer electronics ecosystems.
For Market Incumbents: Secure captive sterilization infrastructure through backward integration into ethylene oxide and gamma irradiation facilities, defending against margin erosion from FDA sterility validation mandates. Acquire regulatory affairs talent with ISO 13485 quality management system expertise to accelerate EU MDR conformity assessment timelines for wireless-enabled variants. Hospital procurement consolidation around sterilization-to-distribution capabilities represents the priority defensive lever.
For New Entrants and Emerging Players: CDSCO medical device registration in India offers a certification fast-track for electrochemical sensor manufacturing targeting Middle East export markets. White-space targets include pressure sensor supply alignment for robotic-assisted surgical procedures in South Korea and Switzerland, plus smartphone-integrated optical glucose sensing formats leveraging consumer electronics supply chains. A go-to-market angle through diagnostic laboratory networks under India's PLI scheme minimizes upfront hospital procurement barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cleanroom manufacturing expansion for Class 7 and Class 8 environments with specialized HVAC systems. Long-term viability favors vertically integrated device manufacturers with in-house materials science capabilities and established hospital procurement relationships over contract sensor specialists. Acquisition target archetypes include electrochemical sensor fabricators with captive thin-film substrate miniaturization facilities. The signal to watch is FDA cybersecurity guidance finalization for connected disposable sensors, which would extend 510(k) review timelines and elevate compliance infrastructure requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Acceleration | Streamlined multi-regional distribution access compresses product refresh cycles for Bluetooth-enabled pulse oximetry modules. |
| Hospital System Partnership Consolidation | Integrated delivery networks in Texas and California displace individual negotiations with sterilization-to-distribution vendor panels. |
| Software Companion Development | HL7 FHIR standard adoption enables wireless disposable sensor integration with proprietary patient data architectures. |
| Reimbursement Strategy Alignment | United States Medicare codes and German statutory health insurance contracts stabilize chronic disease management sensor volumes. |
| CE Marking Pathway Investment | EU MDR Article 10 technical documentation requirements extend timelines for wireless-enabled disposables requiring clinical evidence. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contracts, and GPO supply agreements preceded structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at sterilization service providers. Primary fieldwork combined with secondary validation from ISO 13485 audit records and customs trade data for biocompatible polymer imports. Bottom-up sensor shipment estimates triangulated against top-down healthcare expenditure allocations for disposable monitoring devices.
Variance decomposition across product type, technology layer, application workflow, and end-user procurement channel shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by reimbursement code stability and regulatory pathway timelines. Forecast inputs incorporated EU MDR conformity assessment duration estimates and FDA cybersecurity guidance evolution for connected devices.
Decision-makers should treat outputs as directional under assumptions of sustained chronic disease management decentralization and stable ethylene oxide sterilization capacity; material deviation would warrant model refresh. Specific risk factors include abrupt FDA sterility validation requirement changes, gamma irradiation facility closures, and tariff disruptions on silver nanowire conductive ink imports. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South Africa Aesthetic Devices Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
New Zealand Diabetes Devices Market
Medical Devices
Transradial Closure Devices Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Wearable Artificial Kidney Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
Global Photobiostimulation Market
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
Orthodontic Headgear Market
Medical Devices
Europe Manual Resuscitators Market
Medical Devices
Powered Wheelchair Market
Medical Devices
Eye Massage Device Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Atrial Fibrillation Devices Market