
 Snoring Control Devices Market | 2026-2036
Snoring Control Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Snoring Control Devices Market Outlook
Buyer concentration across sleep clinics is broadening as independent dental practices and specialized sleep centers expand their share of oral appliance dispensing. ResMed leverages its respiratory care infrastructure to sustain channel access for integrated sleep solutions. SomnoMed anchors its position through geographic dominance in dental sleep medicine across North America and Europe. Fisher & Paykel Healthcare competes with hospital-grade ventilation expertise that extends into adjacent sleep-disordered breathing portfolios.
Snoring control devices encompass mechanical and electronic apparatus designed to maintain upper airway patency during sleep, including mandibular repositioning mouthpieces fabricated from medical-grade thermoplastic polymers that advance the lower jaw by 5–10 millimeters to reduce pharyngeal collapse. Their primary commercial purpose centers on non-invasive management of primary snoring and mild-to-moderate obstructive sleep apnea outside surgical or continuous positive airway pressure interventions. Mouthpieces occupy the deepest margin pools due to prescription requirements and dental professional involvement in fitting and titration. Electronic devices incorporating positional therapy sensors represent the fastest-growing technology segment as smartphone-integrated feedback mechanisms improve patient adherence monitoring. Nasal strips constitute a mature, price-commoditized category with limited clinical differentiation.
FDA 510(k) premarket notification requirements govern mandibular advancement devices in the United States, while the EU Medical Device Regulation imposes clinical evidence standards for custom-fabricated oral appliances sold in European markets. ISO 13485 quality management certification shapes supplier qualification for contract manufacturers serving branded device companies. Stakeholders must monitor evolving reimbursement codes for home sleep testing and oral appliance therapy across Medicare and private payer frameworks to anticipate demand inflection points.
Market Dynamics
Home sleep testing expansion is compressing diagnostic bottlenecks and accelerating oral appliance prescription velocity. Dental-sleep medicine integration creates new channel control points between diagnostic confirmation and device dispensing.
Growth Catalysts
- Diagnostic pathway liberalization:Medicare reimbursement for home sleep apnea testing reduces polysomnography wait times and expands candidate pools for mandibular advancement therapy.
- FDA 510(k) pathway efficiency:Streamlined premarket notification for Class II oral appliances accelerates commercialization timelines for thermoplastic mandibular repositioning devices.
- CPAP intolerance migration:Patient non-adherence to continuous positive airway pressure ventilation drives referrals toward non-invasive mechanical alternatives managed through dental sleep specialists.
Market Restraints
- Dental professional scarcity:Limited availability of dentists with sleep medicine credentials constrains fitting and titration capacity for prescription mouthpieces.
- Reimbursement code fragmentation:Inconsistent private payer coverage for oral appliance therapy across US state markets creates geographic access inequities.
- Medical-grade polymer cost volatility:EVA and copolyester raw material price swings compress margins for custom-fabricated thermoplastic devices.
Strategic Opportunities
- Remote monitoring integration:Smartphone-connected adherence tracking for mandibular devices opens subscription revenue streams beyond hardware sales.
- Direct-to-consumer channel development:Over-the-counter nasal dilators and boil-and-bite mouthpieces bypass prescription requirements in deregulated US retail environments.
- EU MDR clinical evidence pathways:Custom oral appliance manufacturers can leverage existing FDA 510(k) data packages to satisfy European Medical Device Regulation conformity assessment.
Industry Challenges
- Titration protocol standardization:Absence of universal mandibular advancement measurement protocols complicates multi-site clinical studies and regulatory submissions.
- Supply chain reconfiguration:Reliance on US-based dental laboratories for device fabrication creates geographic concentration risk and capacity constraints during demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snoring Control Devices Market |
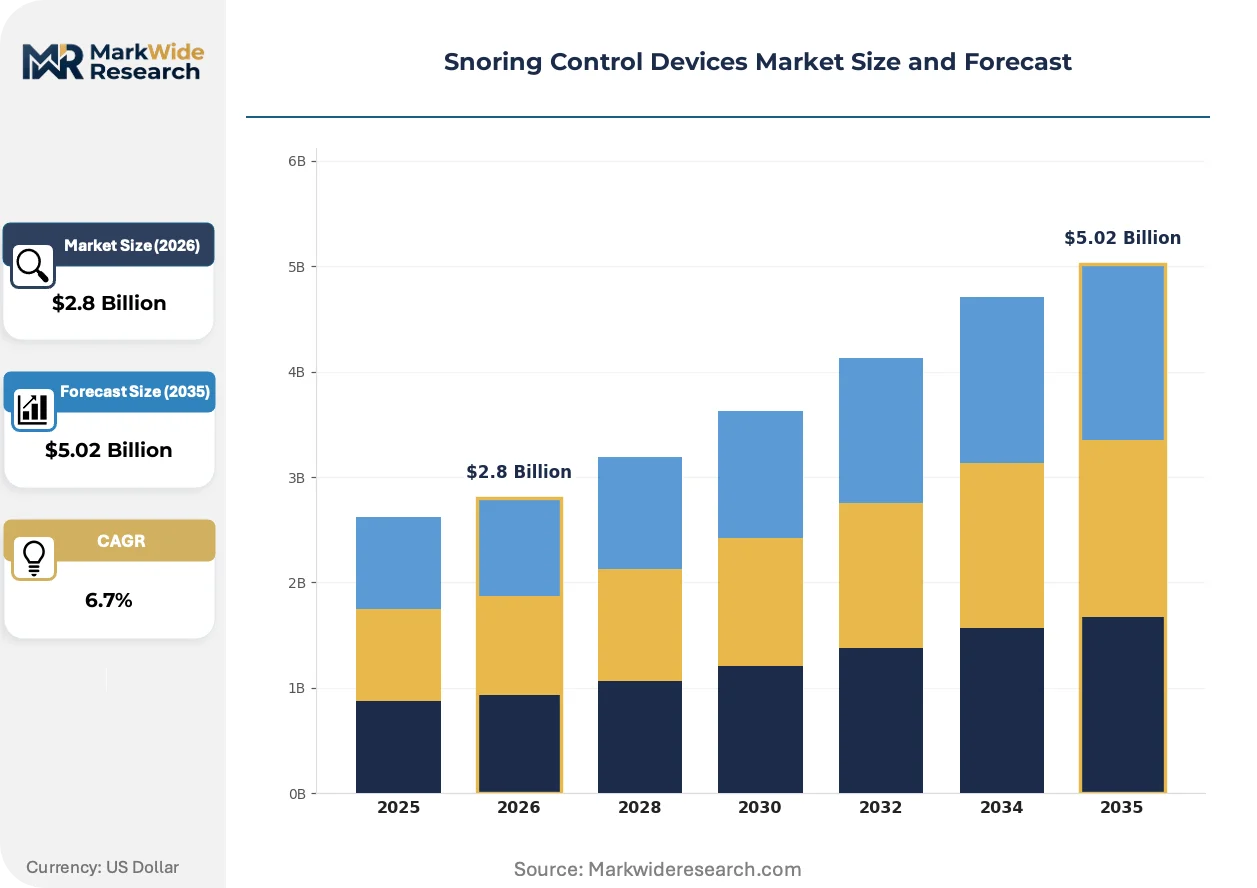
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Snore Pillows, Nasal Strips, Mouthpieces, Chin Straps End User: Individuals, Hospitals, Sleep Clinics, Healthcare Professionals Distribution Channel: Online Retail, Pharmacies, Specialty Stores, Direct Sales Technology: Electronic Devices, Mechanical Devices, Adjustable Straps, Neck Pillows |
| Companies Covered | ResMed, SomnoMed, Fisher & Paykel Healthcare, ProSomnus Sleep Technologies, Apnea Sciences Corporation, Tomed GmbH, Airway Management, Sleeping Well, Glidewell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snoring Control Devices Market Strategic Shifts
Sensor miniaturization and biometric feedback loops are transforming passive mechanical devices into active therapeutic systems with real-time adherence verification.
Positional therapy sensors embedded in wearable neckbands and chest straps is automating sleep position correction through gentle vibration alerts. Sleep clinics in Germany and the Netherlands are piloting these systems for supine-predominant obstructive sleep apnea patients. The technology is automating the previously manual process of positional training and generating objective adherence data that supports reimbursement justification.
EU Medical Device Regulation clinical evidence requirements are elevating barriers for custom oral appliance market entry. Manufacturers must now demonstrate biocompatibility and mechanical safety through notified body review rather than self-certification. Small European dental laboratories without quality management system infrastructure face consolidation pressure or contract manufacturing outsourcing to ISO 13485-certified production partners.
Patient acquisition patterns are fragmenting across telehealth platforms that connect home sleep test results directly to dental sleep medicine providers. Traditional referral pathways through pulmonology and otolaryngology are losing channel control as direct dental access models proliferate in urban US markets. This disintermediation compresses the diagnostic-to-treatment interval but fragments care coordination between medical and dental specialties.
Snoring Control Devices Market Segmentation
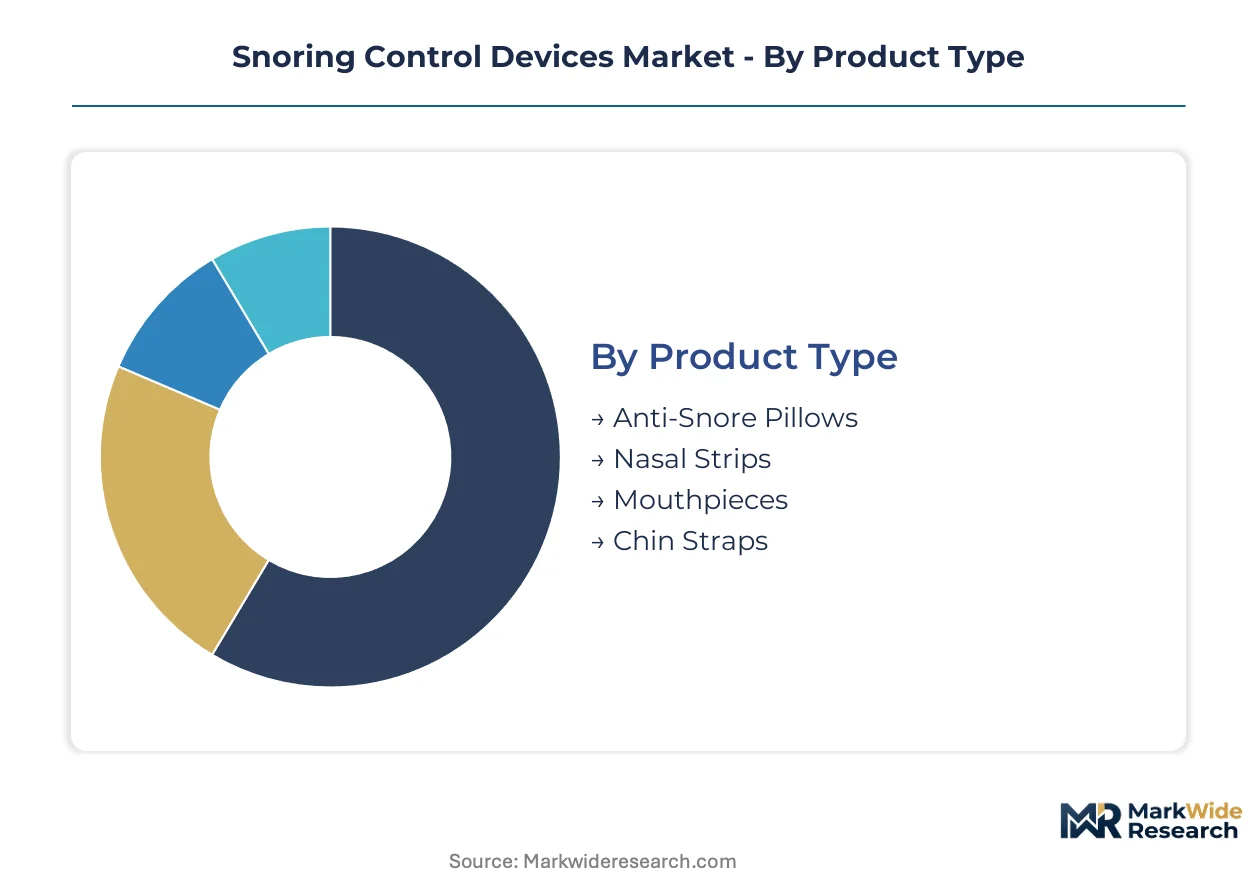
Segmentation in snoring control devices reveals distinct margin profiles and regulatory pathways across mechanical, electronic, and hybrid therapeutic categories. Each axis—product form, prescribing setting, channel structure, and underlying technology—carries different reimbursement codes, clinical validation requirements, and patient adherence patterns that shape commercial strategy.
Product Type:
Technology and material specification differentiate therapeutic efficacy and prescription requirements across form factors.
- Mouthpieces:Mandibular repositioning devices fabricated from medical-grade EVA or copolyester thermoplastics require dental professional fitting and FDA 510(k) clearance. Demand concentrates in US sleep clinics where home sleep testing expansion accelerates prescription velocity for mild-to-moderate obstructive sleep apnea candidates.
- Nasal Strips:Elastic adhesive bands with spring-like plastic filaments mechanically dilate nasal valves. Volume leadership sits with US mass retail and pharmacy channels where over-the-counter positioning eliminates prescription friction, though clinical differentiation remains minimal and pricing faces commoditization pressure.
- Anti-Snore Pillows:Foam or latex constructions with cervical positioning contours aim to maintain lateral sleep posture.
- Chin Straps:Neoprene or fabric bands securing the mandible against the cranium to enforce nasal breathing.
Mature deployment sits with Nasal Strips. Newer deployment is concentrated in Mouthpieces.
End User:
Prescription authority and reimbursement eligibility fragment demand across clinical and consumer settings.
- Sleep Clinics:Accredited diagnostic centers with polysomnography or home sleep testing capabilities generate prescription flows for mandibular advancement devices and positional therapy systems. Patient volume is climbing fastest in Germany and the Netherlands where integrated dental-sleep medicine protocols compress diagnostic-to-treatment intervals.
- Healthcare Professionals:Dentists with sleep medicine credentials control fitting and titration workflows for custom oral appliances. Capacity constraints in credentialed dental practices create geographic access inequities across US state markets with fragmented private payer coverage.
- Individuals:Self-directed purchasers accessing over-the-counter nasal dilators, chin straps, and boil-and-bite mouthpieces.
- Hospitals:Inpatient and outpatient departments managing complex sleep-disordered breathing cases.
Volume leadership rests with Individuals. Margin concentration sits with Sleep Clinics.
Distribution Channel:
Channel selection determines regulatory burden, patient education requirements, and recurring revenue potential.
- Online Retail:E-commerce platforms and direct-to-consumer brands bypass prescription requirements for Class I devices while leveraging smartphone-connected adherence tracking to open subscription revenue streams. Growth is steepest in deregulated US retail environments where telehealth platforms connect home sleep test results directly to dental sleep providers.
- Direct Sales:Manufacturer-controlled channels serving sleep clinics and dental practices with custom-fabricated oral appliances. Relationships anchor on ISO 13485-certified production partnerships and titration protocol support that justifies premium positioning.
- Pharmacies:Brick-and-mortar and mail-order drugstore chains stocking nasal strips and entry-level mouthpieces.
- Specialty Stores:Sleep-focused retailers and medical equipment suppliers catering to diagnosed patients.
Traditional volume anchors at Pharmacies. Expansion is sharpest in Online Retail.
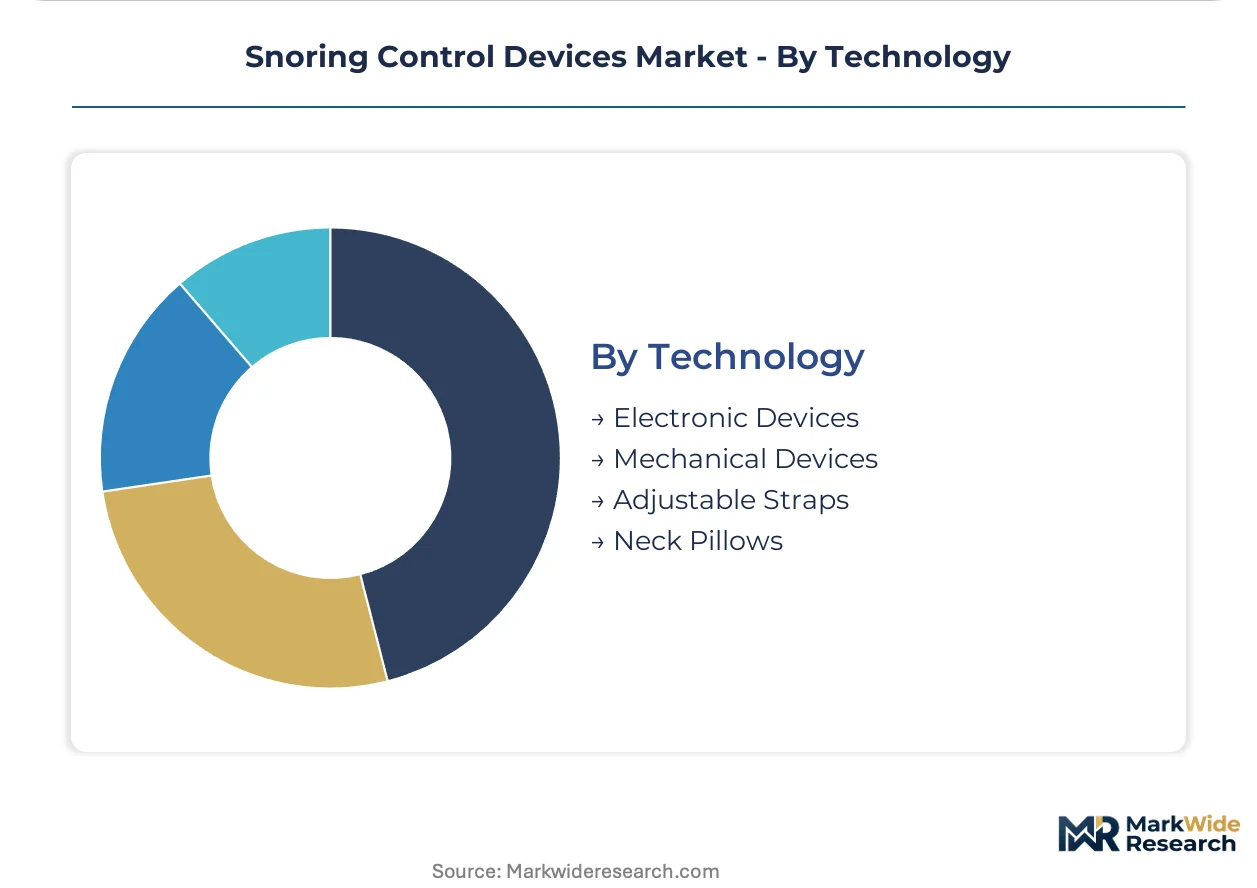
Technology:
Underlying mechanism of action separates passive mechanical systems from sensor-integrated active therapies.
- Electronic Devices:Positional therapy sensors embedded in wearable neckbands and chest straps automate sleep position correction through vibration alerts while generating objective adherence data. Pilot deployment is scaling across German and Dutch sleep clinics for supine-predominant obstructive sleep apnea patients.
- Mechanical Devices:Passive mandibular advancement and nasal dilation systems without powered components or data connectivity. Cost structure and reimbursement stability favor these systems in Medicare-dominated US markets where remote monitoring integration remains nascent.
- Adjustable Straps:Tension-modified chin and headgear systems with user-customizable fit.
- Neck Pillows:Anatomically contoured foam or latex cervical supports for positional maintenance.
Established presence sits with Mechanical Devices. Steepest expansion trajectory belongs to Electronic Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where home sleep testing expansion and dental-sleep medicine integration compress diagnostic-to-treatment intervals for mandibular advancement devices.
United States
Sleep clinics across Texas and Florida are expanding oral appliance dispensing capacity as Medicare reimbursement for home sleep apnea testing accelerates prescription velocity. FDA 510(k) clearance pathways govern mandibular advancement device commercialization, with Class II premarket notification requirements shaping product launch timelines. The Greater Boston corridor anchors dental-sleep medicine training programs that feed credentialed practitioners into suburban markets.
Germany
Positional therapy sensors embedded in wearable neckbands are scaling through sleep clinics in Munich and Hamburg for supine-predominant obstructive sleep apnea patients. EU Medical Device Regulation clinical evidence requirements elevate barriers for custom oral appliance market entry, forcing consolidation among small dental laboratories. The Baden-Württemberg region hosts ISO 13485-certified contract manufacturers serving branded device companies.
Netherlands
Integrated dental-sleep medicine protocols in Amsterdam and Rotterdam compress diagnostic-to-treatment intervals faster than neighboring markets. The country's national pharmaceutical regulator enforces biocompatibility and mechanical safety standards through notified body review rather than self-certification. Eindhoven-area sensor manufacturers supply positional therapy hardware to German and Belgian sleep clinics.
United Kingdom
Telehealth platforms connecting home sleep test results directly to dental sleep providers are fragmenting traditional referral pathways through pulmonology and otolaryngology in London and Manchester. NHS reimbursement frameworks for oral appliance therapy vary across integrated care boards, creating geographic access inequities. The Oxford-Cambridge corridor hosts smartphone-connected adherence tracking startups targeting subscription revenue models.
Japan
CPAP intolerance migration drives referrals toward non-invasive mechanical alternatives managed through dental sleep specialists in Tokyo and Osaka. PMDA regulatory pathways for mandibular repositioning devices require clinical evidence packages that parallel FDA 510(k) structures. The Nagoya industrial cluster supplies medical-grade thermoplastic polymers to domestic mouthpiece fabricators.
Snoring Control Devices Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue sensor-integrated and direct-to-consumer channels outside prescription workflows. Market structure tilts toward consolidation among respiratory care incumbents with sleep-disordered breathing portfolios, while dental-sleep medicine specialists defend niche positions through geographic density. Three archetypes dominate: integrated respiratory giants with channel infrastructure, dental-focused device fabricators with titration expertise, and sensor-technology entrants with smartphone connectivity. Competitive moves center on M&A to capture dental-sleep medicine practices and strategic partnerships to embed remote monitoring capabilities.
Within the respiratory-integrated tier, ResMed leverages its infrastructure to sustain channel access for sleep solutions. SomnoMed anchors geographic dominance in dental sleep medicine across North America and Europe. Fisher & Paykel Healthcare occupies a position extending hospital-grade ventilation expertise into adjacent sleep-disordered breathing portfolios.
| Leading Market Players |
|---|
| ResMed |
| SomnoMed |
| Fisher & Paykel Healthcare |
| ProSomnus Sleep Technologies |
| Apnea Sciences Corporation |
| Tomed GmbH |
| Airway Management |
| Sleeping Well |
| Glidewell |
| Others |
Value Chain & Pricing Dynamics
Medical-grade thermoplastic polymer costs propagate downstream through three distinct pricing tiers for mandibular advancement devices, with EVA and copolyester volatility compressing margins most acutely at the custom-fabricated prescription end where dental laboratory concentration in the United States creates geographic supply bottlenecks.
Pricing Analysis
Volume leadership sits with over-the-counter nasal strips and boil-and-bite mouthpieces in mass retail channels, while margin concentration rests with prescription mandibular devices requiring dental professional fitting and FDA 510(k) clearance. Three-tier pricing structure across premium custom-fitted, standard adjustable, and economy disposable levels reflects certification grade and customization depth. Cost compression in the premium tier is intensifying because medical-grade polymer price swings and dental laboratory capacity constraints. Individual self-directed purchasers show highest price sensitivity, whereas sleep clinics demonstrate lowest sensitivity due to reimbursement pass-through mechanisms.
Supply Chain Analysis
Returns and refurbishment flows for mandibular devices remain minimal given the personal-fit nature of oral appliances, though sensor-integrated electronic devices in Germany and the Netherlands are piloting subscription models with hardware refresh cycles. Manufacturing concentrates in the United States, Germany, and China, with the Baden-Württemberg region hosting ISO 13485-certified contract manufacturers and the Nagoya industrial cluster supplying medical-grade thermoplastics. Production rests on EVA copolymer, dental-grade acrylic resins, and miniaturized positional sensors. Single-source vulnerability in US-based dental laboratory networks creates capacity risk during demand surges. Distribution runs through direct sales to sleep clinics, online retail platforms, and pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
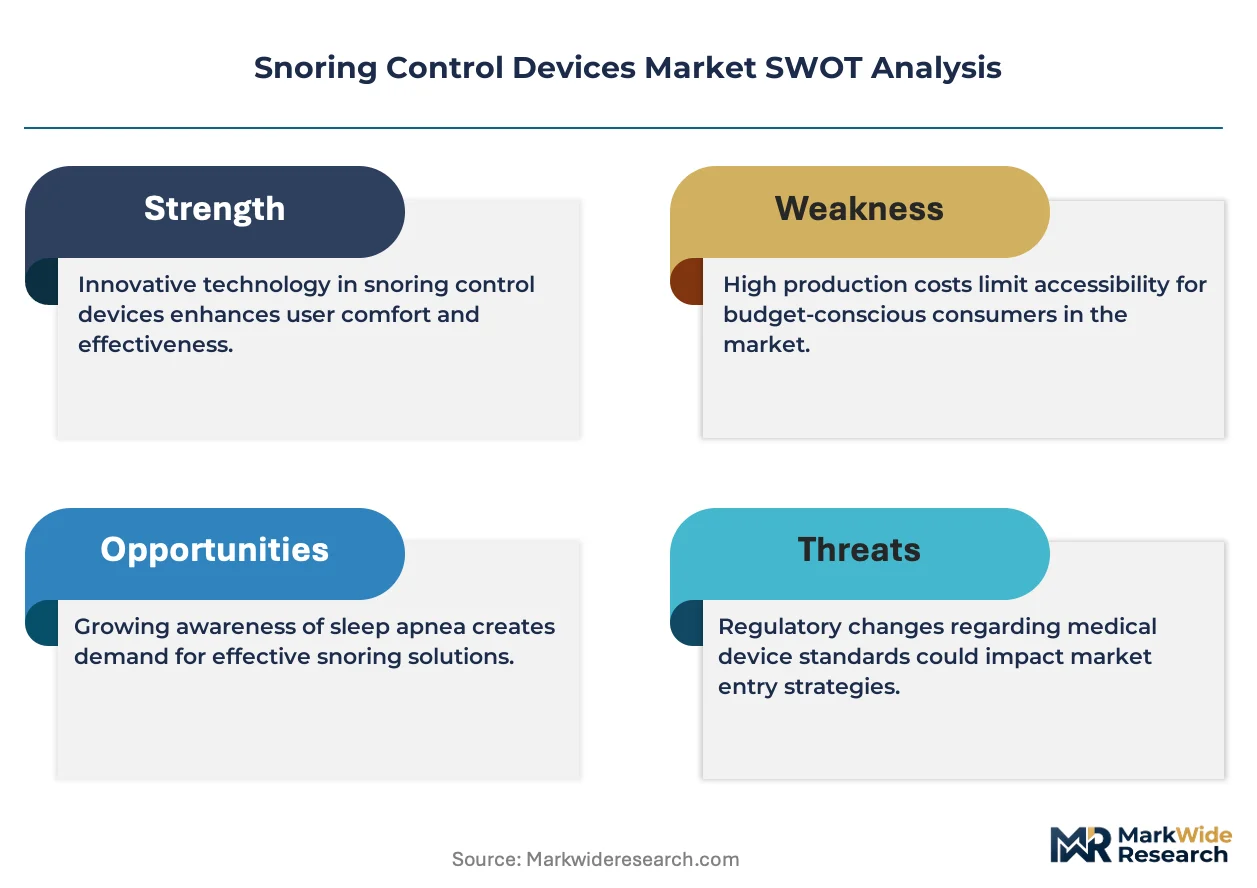
The snoring control devices market operates under supply-constrained conditions where credentialed dental sleep medicine practitioners represent the binding capacity bottleneck, propping pricing power for incumbent device fabricators with established professional training relationships.
For Market Incumbents: Hedge against direct-to-consumer channel erosion by acquiring dental-sleep medicine practices in Texas and Florida where home sleep testing expansion concentrates prescription flow. Build backward integration into medical-grade thermoplastic compounding to insulate margins from EVA price volatility. Sensor-technology entrants with smartphone connectivity threaten premium positioning unless incumbents embed remote monitoring capabilities through subscription revenue models. For New Entrants and Emerging Players: Telehealth platforms connecting home sleep test results to dental providers offer the most penetrable route for bypassing traditional pulmonology referral gatekeepers. Target the United Kingdom and Netherlands where integrated dental-sleep medicine protocols fragment established channel control. Pursue over-the-counter nasal dilator and positional therapy sensor segments in deregulated US retail environments where prescription friction is eliminated. For Investors and Strategic Acquirers: FDA 510(k) clearance pathway efficiency is the leading indicator that custom oral appliance manufacturers can accelerate commercialization timelines and capture Medicare reimbursement expansion. Long-term viability over the projection horizon favors targets with ISO 13485-certified production infrastructure and existing European Medical Device Regulation conformity packages. Monitor home sleep testing reimbursement code expansion across US state markets as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Monitoring Integration | Smartphone-connected adherence tracking opens subscription revenue beyond hardware sales for mandibular devices. |
| Dental-Sleep Medicine Practice Acquisition | Channel control points between diagnostic confirmation and device dispensing compress competitor access to prescribers. |
| EU MDR Conformity Assessment | Leveraging existing FDA 510(k) data packages accelerates European market entry for custom oral appliances. |
| Direct-to-Consumer Channel Development | Over-the-counter positioning in deregulated US retail bypasses prescription requirements and dental professional scarcity constraints. |
| Medical-Grade Polymer Backward Integration | In-house compounding of EVA and copolyester insulates margins from raw material price volatility. |
Study Parameters
FDA 510(k) premarket notification databases, CMS Medicare reimbursement filings, and EU Medical Device Regulation conformity assessment records formed the secondary backbone, cross-referenced against primary interviews with dental sleep medicine practitioners, sleep clinic medical directors, biomedical engineers at contract manufacturers, and GPO contracts managers. Bottom-up and top-down triangulation validated prescription volume estimates and pricing tier distributions across mechanical and electronic device categories.
Historical trendline analysis of mandibular advancement device approvals and home sleep testing reimbursement expansion informed the projection framework across product type, prescribing setting, distribution channel, and underlying technology dimensions. CAGRs were derived from segmented demand modeling incorporating dental professional capacity constraints, polymer cost trajectories, and regulatory pathway efficiency variations. Forecast inputs included Medicare coverage determination timelines and EU notified body review capacity.
The model holds under stable FDA 510(k) clearance timelines and consistent Medicare reimbursement for oral appliance therapy; deviation in dental professional training program expansion rates or medical-grade polymer supply disruptions would shift prescription velocity assumptions. Practitioners should monitor home sleep testing coverage determination updates and EU MDR notified body backlog indicators for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
Sterile Filtration Module Market
Medical Devices
South Africa Aesthetic Devices Market
Medical Devices
Veterinary Ventilators Market
Medical Devices
Artificial Eye Lenses Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Neonatal Hearing Screening Devices Market
Medical Devices
Germany Spinal Surgery Devices Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Contact Thermometer Market
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
Medical Hydrophilic Coatings Market
Medical Devices
Spain Aesthetic Devices Market
Medical Devices
Autosamplers Market
Medical Devices
Medical Bionic Implant Market