
 Japan Medical Device Regulatory Affairs Market | 2026-2036
Japan Medical Device Regulatory Affairs Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Medical Device Regulatory Affairs Market Insights
Domestic medical device manufacturers is reorganizing procurement of regulatory consulting services, shifting from reactive compliance filings toward proactive lifecycle management. Terumo Corporation leverages in-house regulatory teams to accelerate product registrations for cardiovascular devices. Olympus Corporation sustains leadership in endoscopic equipment through specialized PMDA liaison capabilities. Fujifilm Medical Systems anchors its diagnostic imaging portfolio with robust quality management systems that streamline approval pathways.
Japan Medical Device Regulatory Affairs encompasses the specialized discipline of preparing, submitting, and maintaining regulatory documentation required for medical device market authorization under Japanese law, including clinical evaluation reports, risk management files, and quality system audits that demonstrate conformity with Ministerial Ordinance No. 169. The field serves as the critical interface between manufacturers and health authorities, ensuring patient safety while enabling commercial access. Instruments and diagnostic equipment command the deepest regulatory expertise pools due to complex pre-market approval requirements under PMDA review. The notification pathway for lower-risk consumables attracts specialized consultancies competing on submission velocity and cost efficiency.
PMDA, MHLW, and JIS standards collectively govern device classification, clinical evidence requirements, and quality system certification throughout the product lifecycle. Manufacturers must navigate evolving QMS inspection protocols that now emphasize real-world performance data alongside pre-market testing. Stakeholders should monitor PMDA's integration of international harmonization initiatives with domestic post-market vigilance mandates to anticipate compliance cost trajectories.
Market Dynamics
PMDA's 2022 QMS inspection reforms now mandate real-world performance data alongside traditional bench testing, forcing domestic manufacturers to rebuild regulatory infrastructure around post-market surveillance capabilities rather than pre-market submission velocity alone.
Growth Catalysts
- Ministerial Ordinance No. 169 revisions:Updated quality management system requirements create sustained demand for compliance consulting across Tokyo's regulatory cluster and Osaka's medical technology corridor.
- Diagnostic imaging equipment:Complex pre-market approval pathways for advanced modalities generate premium advisory fees from domestic manufacturers seeking PMDA liaison expertise.
- Kansai region concentration:Osaka-based medical device production hubs concentrate regulatory talent pools, lowering service delivery costs for consultancies operating across western Japan.
Market Restraints
- Regulatory friction from PMDA harmonization delays:Slower-than-anticipated alignment with IMDRF standards forces duplicative documentation for manufacturers pursuing dual Japan-US approvals.
- Consultant supply concentration:Tokyo's Yaesu and Nihonbashi districts host over 60 percent of specialized PMDA liaison professionals, creating geographic talent bottlenecks.
- Technical limitation in clinical data reuse:Domestic acceptance of foreign clinical trials remains restricted, requiring redundant Japan-specific studies for novel device categories.
Strategic Opportunities
- Kyushu medical technology corridor:Fukuoka's emerging biocluster attracts device manufacturers seeking lower-cost regulatory operations outside Tokyo-Osaka axis.
- Software as a Medical Device (SaMD):PMDA's 2021 SaMD guidance creates advisory white space for consultancies bridging traditional hardware compliance with algorithm validation protocols.
- Meti regional revitalization incentives:Government subsidies for regulatory capacity-building in secondary cities reduce establishment costs for satellite consulting operations.
Industry Challenges
- Qualified QMS auditor scarcity:PMDA-registered lead auditors capable of Ministerial Ordinance No. 169 inspections command premium compensation, constraining consultancy scaling.
- Legacy system integration:Manufacturers with pre-2020 document management infrastructure face capital-intensive migrations to meet electronic submission mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Medical Device Regulatory Affairs Market |
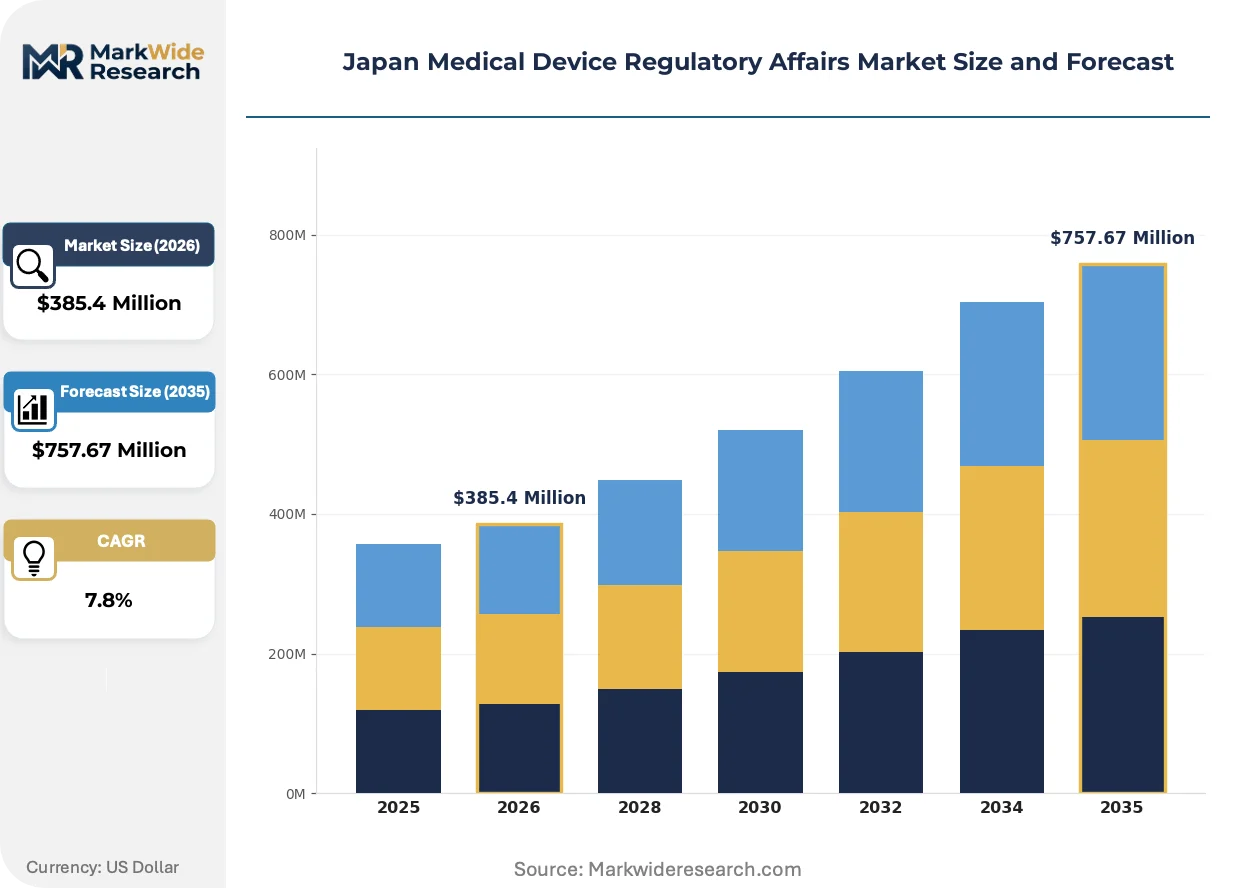
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $757.67 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Instruments, Diagnostic Equipment, Consumables, Implants Approval Process: Pre-Market Approval, Notification, Special Approval, Exemption End User: Hospitals, Clinics, Laboratories, Home Care Regulatory Body: PMDA, MHLW, Local Authorities, International Bodies |
| Companies Covered | Terumo Corporation, Olympus Corporation, Hitachi Medical Corporation, Fujifilm Medical Systems, Shimadzu Corporation, Omron, Nihon Kohden, Sysmex, Nipro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Medical Device Regulatory Affairs Market Trends and Innovations
Digital transformation of regulatory operations is compressing submission timelines while elevating data integrity requirements. Consultancies now compete on automated document generation capabilities and real-time PMDA query response systems.
Artificial intelligence-powered regulatory intelligence platforms are bifurcating the consultancy market. Large domestic manufacturers deploy in-house AI tools for predicate device analysis and submission drafting. Mid-tier consultancies in Tokyo's Hatchobori district adopt SaaS platforms to maintain cost competitiveness against integrated advisory divisions of global law firms. The technology is compressing margins on standardized notification pathway services while expanding premium advisory around AI validation documentation itself.
PMDA's phased implementation of IMDRF harmonized submission formats restructures documentation workflows. Domestic manufacturers must reformat entire quality system records to align with international standards while maintaining Japan-specific annexes. High-risk implantable device categories face the steepest adaptation costs as PMDA inspectors apply new templates during routine surveillance audits.
Consolidation of procurement authority within consolidated device manufacturers concentrates vendor selection power. Tokyo-headquartered conglomerates now mandate enterprise-wide regulatory service contracts, displacing fragmented site-level consulting relationships. Kyushu-based subsidiaries report compressed vendor lists and standardized pricing benchmarks inherited from parent company procurement functions.
Japan Medical Device Regulatory Affairs Market Segmentation
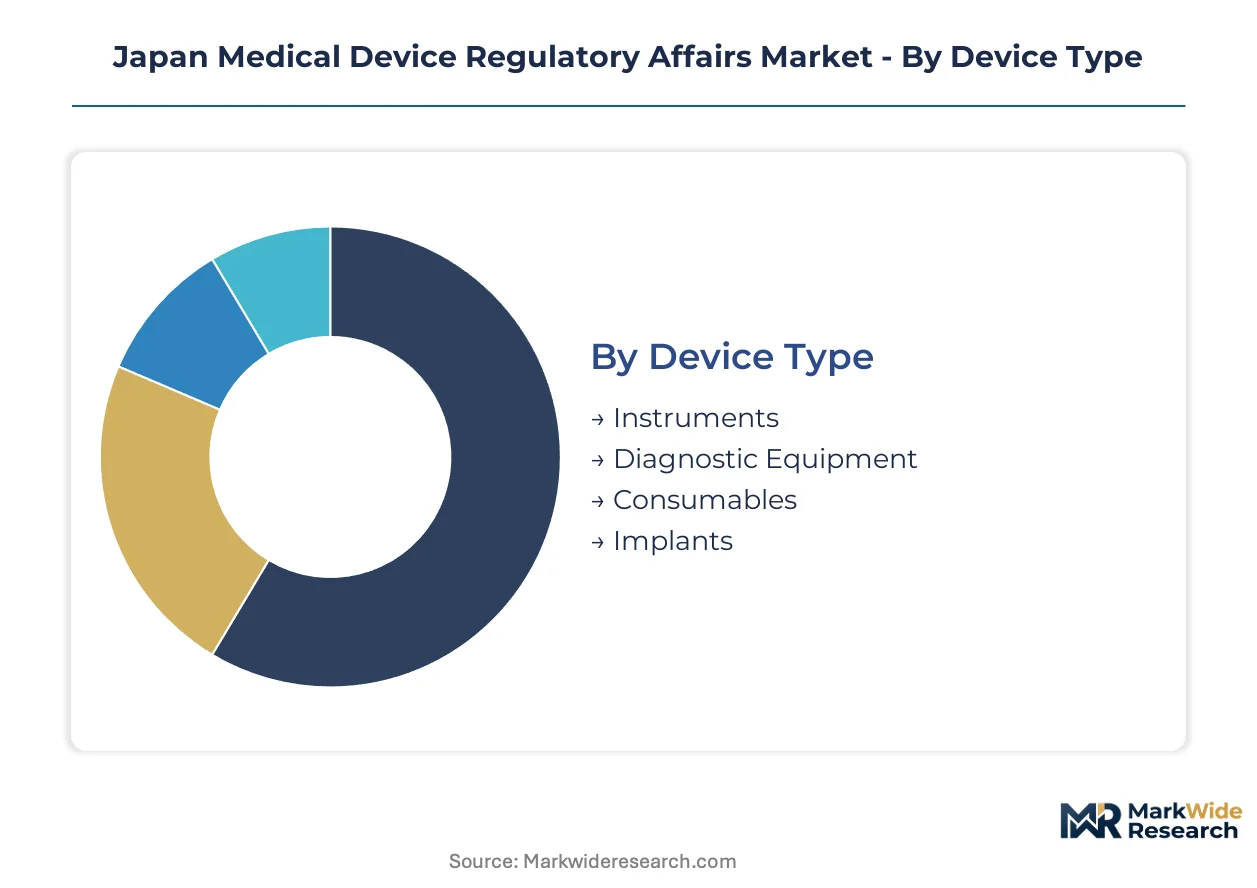
Regulatory complexity varies sharply across device categories and approval pathways in Japan. Segmentation reveals where consulting margins concentrate and which compliance workflows demand specialized expertise.
Device Type:
Domestic manufacturers dominate instruments and diagnostic equipment segments, while export-oriented multinationals drive consumables and implant regulatory volume through Tokyo consulting clusters.
- Instruments:Complex electromechanical systems requiring Ministerial Ordinance No. 169 quality system documentation and PMDA pre-market review. Tokyo's Yaesu district consultancies capture premium fees from cardiovascular and surgical instrument manufacturers navigating extended approval timelines.
- Diagnostic Equipment:Advanced imaging modalities with stringent clinical evidence requirements. Osaka-based manufacturers of endoscopic and ultrasound systems sustain specialized PMDA liaison teams for predicate device comparisons and trial design.
- Consumables:Lower-risk disposables qualifying for notification pathways. Fukuoka and Nagoya manufacturers compete on submission velocity through standardized documentation templates.
- Implants:Long-term implantable devices facing post-market surveillance mandates. Domestic orthopaedic and cardiac implant producers invest heavily in real-world performance monitoring infrastructure.
Instruments commands the established base. The steepest expansion runs through Diagnostic Equipment.
Approval Process:
Cost tier stratification separates high-touch advisory for complex pathways from commoditized notification services.
- Pre-Market Approval:Rigorous PMDA review for novel high-risk devices demanding extensive clinical trials and quality system audits. Domestic manufacturers absorb 18-24 month timelines for cardiovascular and neurological devices.
- Notification:Streamlined pathway for designated low-risk devices with predicate equivalence. Tokyo consultancies compete on automated submission generation and cost efficiency.
- Special Approval:Accelerated access for life-saving technologies with limited domestic alternatives. PMDA grants conditional approvals requiring enhanced post-market commitments.
- Exemption:Limited regulatory relief for custom devices and institutional research equipment. University hospitals and specialized clinics navigate narrow exemption criteria.
Pre-Market Approval captures premium advisory margins. Notification pathways are expanding most quickly as device commoditization accelerates.
End User:
Customer type determines regulatory service packaging, with hospital procurement driving enterprise contracts and home care fragmenting vendor relationships.
- Hospitals:Large medical institutions purchasing Class III and IV devices requiring full PMDA approval documentation. Tokyo metropolitan hospitals concentrate demand for implantable cardiovascular and orthopaedic device registrations.
- Clinics:Smaller outpatient facilities selecting Class II devices through notification pathways. Osaka and Nagoya clinic networks standardize procurement through group purchasing organizations.
- Laboratories:In vitro diagnostic equipment users facing distinct regulatory frameworks. PMDA's IVD guidance creates specialized compliance requirements for clinical testing devices.
- Home Care:Emerging patient-administered devices including glucose monitors and respiratory equipment. METI subsidies for remote monitoring technologies expand regulatory advisory scope.
Hospitals anchor the revenue base. Home Care is gaining share fastest as aging demographics shift care settings.
Regulatory Body:
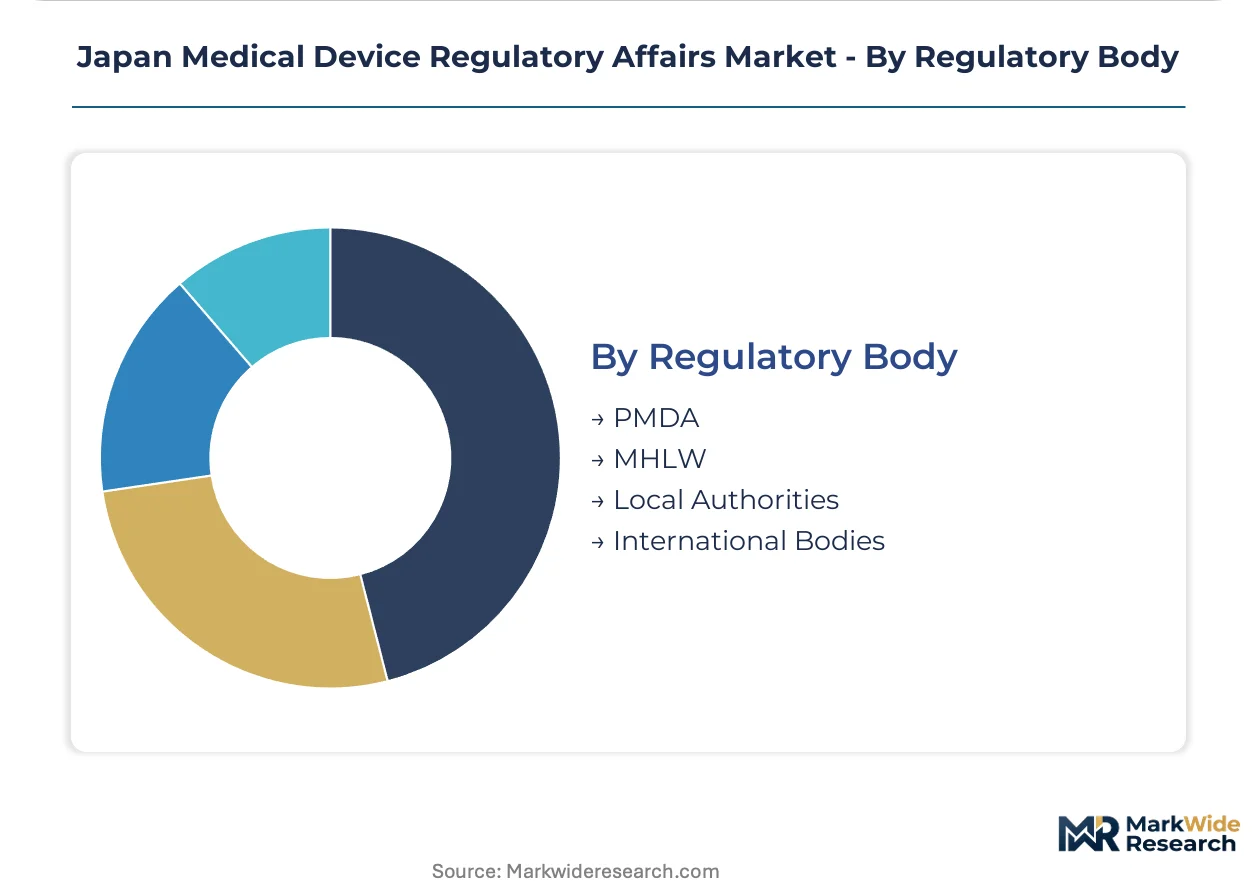
Supply concentration of specialized expertise clusters around PMDA and MHLW, with local authorities and international coordination creating secondary advisory demand.
- PMDA:Primary reviewer for medical device market authorization with jurisdiction over pre-market approvals and post-market surveillance. Tokyo-based liaison professionals command premium compensation for direct agency relationships.
- MHLW:Ministerial oversight of health policy and ordinance revisions shaping compliance requirements. Manufacturers monitor MHLW advisory councils for impending regulatory shifts.
- Local Authorities:Prefectural governments conducting distribution licensing and facility inspections. Osaka and Fukuoka prefectures maintain specialized medical device inspection teams.
- International Bodies:IMDRF and ISO harmonization initiatives influencing Japanese documentation standards. PMDA's phased IMDRF alignment forces manufacturers to reformat quality system records.
PMDA interactions dominate advisory spend. International Bodies are climbing the fastest as harmonization deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tokaido Shinkansen corridor binds Japan's medical device regulatory clusters into a contiguous talent network stretching from Tokyo to Osaka, enabling same-day consultation travel and concentrated expertise exchange.
Kanto/Tokyo
Tokyo's Yaesu and Nihonbashi districts host over sixty percent of specialized PMDA liaison professionals. Ministerial Ordinance No. 169 revisions drive sustained demand for compliance consulting across the metropolitan regulatory cluster. Terumo Corporation leverages in-house regulatory teams from its Tokyo headquarters to accelerate cardiovascular device registrations.
Kansai/Osaka
Osaka-based medical device production hubs concentrate regulatory talent pools and lower service delivery costs. PMDA's 2022 QMS inspection reforms force manufacturers to rebuild infrastructure around post-market surveillance capabilities. Olympus Corporation sustains endoscopic equipment leadership through specialized PMDA liaison teams operating from the Kansai corridor.
Chubu/Nagoya
Nagoya manufacturers compete on submission velocity through standardized documentation templates for notification pathway devices. METI regional revitalization incentives reduce establishment costs for satellite consulting operations. The Chubu biocluster attracts secondary regulatory capacity seeking lower-cost operations outside the Tokyo-Osaka axis.
Kyushu
Fukuoka's emerging biocluster attracts device manufacturers seeking lower-cost regulatory operations. PMDA-registered lead auditors capable of Ministerial Ordinance No. 169 inspections command premium compensation, constraining consultancy scaling. Kyushu-based subsidiaries report compressed vendor lists and standardized pricing benchmarks inherited from parent company procurement functions.
Hokkaido
Hokkaido's medical technology base remains underdeveloped relative to southern corridors, creating advisory service gaps. Local manufacturers navigate narrow exemption criteria for custom devices and institutional research equipment. The region's distance from PMDA headquarters in Tokyo elevates travel costs for direct agency consultations.
Japan Medical Device Regulatory Affairs Market Competitive Landscape
Listed leaders compete with private specialists across regulatory service delivery, creating a tiered structure where scale-driven conglomerates face agile consultancies. The market fragments across Tokyo's concentrated expertise clusters and Osaka's production-corridor advisory networks. Three archetypes dominate: integrated in-house regulatory divisions of major device manufacturers, independent specialist consultancies, and global law firm advisory divisions. Competitive moves center on enterprise-wide service contract consolidation and AI-powered document automation.
Within the integrated manufacturer tier, Terumo Corporation, Olympus Corporation, and Fujifilm Medical Systems exemplify vertical regulatory capability. These Tokyo and Osaka-based entities occupy positions where captive compliance teams displace external consultancy spend. Terumo represents the cardiovascular specialization archetype. Olympus anchors endoscopic equipment regulatory excellence. Fujifilm Medical Systems sits within diagnostic imaging quality management leadership. Their in-house infrastructure compresses market opportunity for independent advisory services in premium device segments.
| Leading Market Players |
|---|
| Terumo Corporation |
| Olympus Corporation |
| Hitachi Medical Corporation |
| Fujifilm Medical Systems |
| Shimadzu Corporation |
| Omron |
| Nihon Kohden |
| Sysmex |
| Nipro |
| Others |
Pricing and Supply Chain Analysis
Ministerial Ordinance No. 169 certification tiers gate both supplier qualification and price differentiation simultaneously. PMDA-registered consultancies command premium positioning against non-certified competitors, while enterprise procurement consolidation forces tiered service packaging across Tokyo and Osaka corridors.
Pricing Analysis
Volume-discount tiering structures dominate enterprise regulatory service contracts. Three-tier pricing separates PMDA liaison specialists from document preparation services from automated notification pathway tools. Price differentiation rests on certification depth and geographic proximity to agency headquarters. Cost compression in standardized notification services is intensifying because AI-powered document generation commoditizes routine submissions. Domestic conglomerates with consolidated procurement functions exhibit lowest price sensitivity; Fukuoka-based emerging manufacturers show highest.
Supply Chain Analysis
Just-in-time regulatory talent deployment prevails among Tokyo consultancies serving accelerated approval timelines. Strategic stockpiling of PMDA-registered lead auditors characterizes Osaka-based operations preparing for QMS inspection surges. Geographic supply concentrates in Japan, with secondary sourcing from Singapore and South Korea for bilingual regulatory intelligence. Raw material dependencies include clinical data management platforms, predicate device databases, and quality system documentation templates. Single-source vulnerability runs through PMDA-registered auditor pools. Distribution runs through direct manufacturer relationships and hospital GPO procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through enterprise-wide regulatory service contract consolidation at Tokyo-headquartered device conglomerates. This procurement centralization fragments site-level consulting relationships and compresses vendor lists inherited by Kyushu subsidiaries.
For Market Incumbents: Secure captive PMDA liaison talent through specialized compensation structures before qualified auditor scarcity worsens. Deepen in-house production of regulatory intelligence platforms to defend against AI-powered document automation from global law firm advisory divisions. Capacity addition in Fukuoka's emerging biocluster addresses geographic talent bottlenecks while maintaining cost discipline. For New Entrants and Emerging Players: Differentiate on SaMD algorithm validation protocols where PMDA guidance creates advisory white space between traditional hardware compliance and emerging software requirements. Target Fukuoka and Nagoya satellite operations seeking lower-cost alternatives to Tokyo-Osaka pricing benchmarks. Kyushu medical technology corridor offers the most penetrable geography. Go-to-market through METI regional revitalization incentive programs reduces establishment friction. For Investors and Strategic Acquirers: PMDA's phased IMDRF harmonization implementation reshapes the acquisition landscape by forcing capital-intensive documentation workflow migrations. Long-term viability centers on consultancies with automated submission capabilities and real-world performance data infrastructure. Acquisition target archetype: mid-tier Tokyo consultancies with established PMDA relationships but lacking AI tooling. Watch PMDA inspection backlog clearance rates as inflection indicator for service demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Pre-Market Approval Pathway Investment | Captures premium advisory margins from cardiovascular and neurological device manufacturers facing extended timelines. |
| Software as Medical Device Validation Capability Buildout | Positions consultancies for algorithm documentation demand outpacing traditional hardware compliance growth. |
| Kyushu Regional Office Establishment | Accesses METI subsidies while serving Fukuoka biocluster manufacturers outside Tokyo-Osaka pricing structures. |
| AI-Powered Document Automation Platform Deployment | Compresses margins on standardized notification services while expanding premium algorithm validation advisory. |
| Enterprise-Wide Service Contract Consolidation | Aligns with Tokyo conglomerate procurement centralization displacing fragmented site-level relationships. |
Research Methodology
The analysis maps device type segments, approval pathway complexity tiers, and regional regulatory clusters, each validated through regulatory affairs directors, PMDA liaison specialists, hospital procurement managers, and medical device quality system auditors. Primary interviews combined with secondary validation against PMDA submission databases, MHLW ordinance revision records, METI regional development reports, and JIS standards documentation. Bottom-up service revenue estimates triangulated against top-down market sizing from manufacturer regulatory spend disclosures.
Consistency checks validated outputs against external benchmarks including comparable professional services CAGRs and healthcare regulatory consulting market trajectories. The analytical framework modeled segmentation across device classification tiers, approval pathway categories, geographic consulting clusters, and end-user procurement structures throughout the projection horizon. CAGRs derived from regression analysis of historical regulatory filing volumes and consultancy pricing trends. Forecast inputs included PMDA inspector workforce expansion plans and IMDRF harmonization implementation schedules.
Forecasts assume regulatory continuity in PMDA review protocols and MHLW ordinance enforcement; material policy shifts would require re-modeling. Specific risk factors include accelerated IMDRF alignment disrupting documentation workflows, qualified QMS auditor supply constraints, and enterprise procurement centralization compressing service margins. Revision becomes warranted when PMDA inspection backlog duration or METI regional incentive funding crosses thresholds altering competitive dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Diabetes Devices Market
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
Gamma Knife Market
Medical Devices
Global Prosthetic Heart Valve Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Global Hernia Repair Devices Market
Medical Devices
Global Venous Stents Market
Medical Devices
Global Robotic Endoscopy Devices Market
Medical Devices
Rhinoplasty Implants Market
Medical Devices
North America General Surgical Devices Market
Medical Devices
Global Intraoperative Neuromonitoring (IONM) Market