
 Contraceptive Devices Market | 2026-2036
Contraceptive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Contraceptive Devices Market Analysis
Asian polymer processors is expanding output of medical-grade silicone sheeting for condom and diaphragm production. Bayer AG leverages its polymer science heritage to sustain leadership in hormonal intrauterine systems. CooperSurgical anchors its position through specialized manufacturing of in-clinic insertion devices. Pfizer Inc. competes in the hormonal implant segment with extended-release delivery platforms.
Contraceptive devices comprise engineered products designed to prevent pregnancy through barrier, hormonal, or intrauterine mechanisms, typically manufactured from medical-grade silicone, polyethylene, or copper alloys with specifications for biocompatibility and controlled release rates. Their primary commercial purpose centers on enabling voluntary fertility management across diverse healthcare settings. Intrauterine devices command the largest installed base due to multi-year efficacy and declining insertion complication rates. Hormonal technology captures premium margins through patent-protected formulations, while non-hormonal options occupy growing share among consumers seeking steroid-free alternatives.
FDA premarket notification requirements and EPA chemical safety assessments shape product approval timelines and material selection for US manufacturers. The EU Medical Device Regulation and REACH substance restrictions impose additional compliance layers on devices distributed across European markets. Stakeholders must monitor evolving reimbursement classifications and state-level coverage mandates to anticipate demand shifts and channel investment toward compliant product portfolios.
Market Dynamics
Medicaid expansion across multiple US states is restructuring demand for long-acting reversible contraceptives by broadening subsidized access channels and shifting procurement volumes toward hospital networks rather than retail pharmacies.
Growth Catalysts
- Medicaid Expansion:State-level coverage mandates in the United States are pulling uninsured populations into prescription contraceptive programs, expanding the addressable patient base for clinic-administered devices.
- FDA Safety Labeling Updates:Revised guidance on intrauterine device complications has reduced liability concerns among healthcare providers, accelerating in-clinic insertion rates.
- Copper Alloy Refinement:Medical-grade copper processing improvements are extending non-hormonal intrauterine device efficacy windows while reducing manufacturing defect rates.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Asian polymer processors dominate specialty silicone sheeting production, creating single-source vulnerability for condom and diaphragm manufacturers.
- EPA Chemical Safety Assessments:Evolving environmental toxicity thresholds for polymer additives are extending reformulation timelines and raising compliance costs for US-based device makers.
- Hormonal Implant Patent Cliffs:Extended-release delivery platform protections are nearing expiration in key markets, threatening margin compression for incumbent suppliers.
Strategic Opportunities
- EU Medical Device Regulation Harmonization:Streamlined CE marking pathways for Class IIb contraceptive devices are opening consolidated European distribution opportunities for compliant manufacturers.
- Steroid-Free Preference Surge:Endocrine-conscious consumer segments are driving demand for copper-based and barrier alternatives, creating premium positioning for non-hormonal product lines.
- Telehealth Integration:Remote prescription and mail-order delivery channels are bypassing traditional clinic gatekeepers, enabling direct-to-patient access in underserved rural geographies.
Industry Challenges
- Biocompatibility Certification Bottlenecks:ISO 10993 testing backlogs at accredited laboratories are delaying product launches by six to twelve months for novel materials.
- Insertion Device Sterilization Validation:In-clinic applicator systems require redundant sterilization assurance protocols, complicating manufacturing scale-up for combination product submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contraceptive Devices Market |
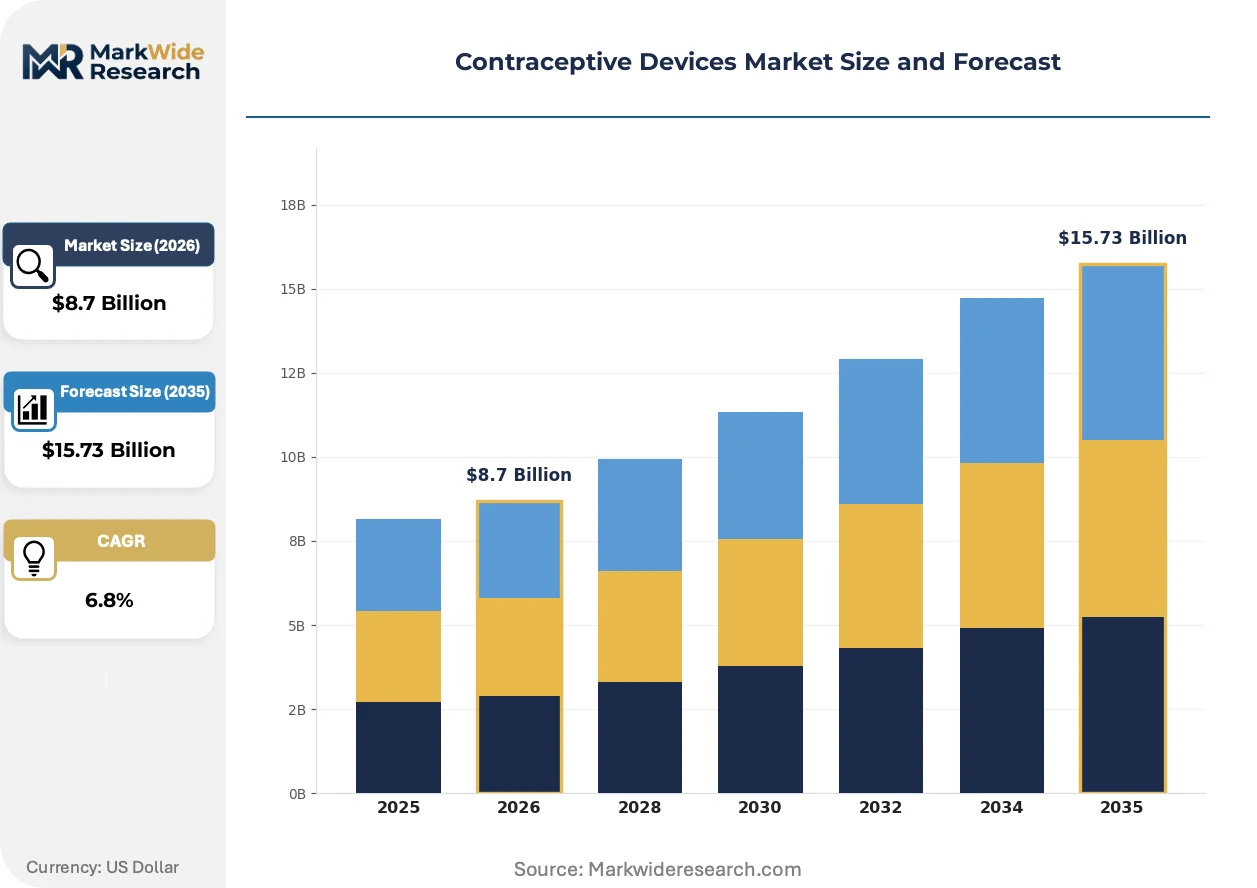
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrauterine Devices, Condoms, Implants, Diaphragms Technology: Hormonal, Non-Hormonal, Barrier, Intrauterine Application: Family Planning, Emergency Contraception, Menstrual Regulation, Health Education End User: Women, Healthcare Providers, Pharmacies, Clinics |
| Companies Covered | Bayer AG, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Merck & Co., Inc., Reckitt Benckiser Group plc, CooperSurgical Inc., Janssen Global Services, LLC, Church & Dwight Co., Inc., Mylan N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contraceptive Devices Market Emerging Trajectories
Digital health integration and materials science advances are converging to reshape how contraceptive devices are prescribed, delivered, and monitored across healthcare systems.
Bioresorbable polymer formulations for hormonal implants are electrifying long-acting contraceptive design by eliminating removal procedures. Women's health clinics in Scandinavia are piloting these platforms for adolescent populations seeking discrete, provider-independent options. The technology is compressing the total cost of care while expanding addressable markets beyond traditional clinic-dependent segments.
REACH substance restrictions on persistent organic pollutants are forcing reformulation of silicone curing agents used in condom manufacturing. European manufacturers are accelerating migration to platinum-catalyzed vulcanization processes ahead of 2026 enforcement deadlines. The regulatory pressure is concentrating supply relationships with REACH-compliant chemical suppliers and raising barriers for non-EU exporters.
Subscription-based contraceptive delivery is displacing pharmacy-dependent fulfillment among urban millennials in the United States and United Kingdom. Direct-to-consumer platforms are bundling telehealth consultations with automated resupply, capturing patients who avoid traditional provider interactions. This channel shift is most pronounced among users of combined hormonal patches and vaginal rings seeking discretion and convenience.
Contraceptive Devices Market Segmentation
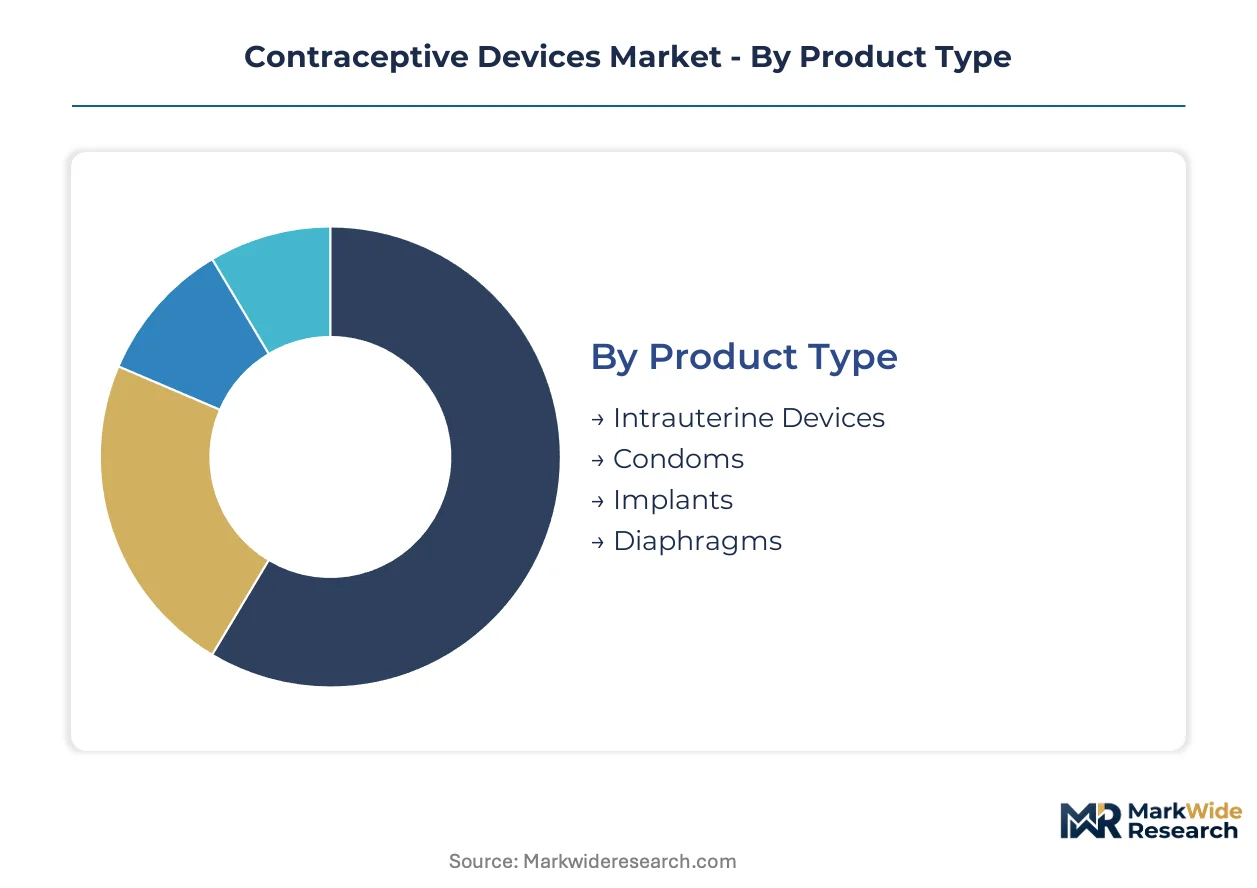
Segmentation in the contraceptive devices market reveals divergent capital requirements across manufacturing modalities, from polymer extrusion lines for barrier products to precision metalworking for intrauterine systems. Understanding these structural differences illuminates where economies of scale concentrate and where niche positioning remains viable.
Product Type:
Capital intensity varies sharply across product categories, with hormonal intrauterine systems demanding the heaviest upfront investment in controlled-release polymer synthesis and sterile filling infrastructure.
- Intrauterine Devices:T-shaped frames manufactured from medical-grade polyethylene or copper alloys with controlled-release hormone reservoirs. Hospital networks in the United States are expanding procurement following FDA safety labeling updates that reduced provider liability concerns.
- Condoms:Latex or synthetic polyisoprene sheeting formed through dipping processes with electronic integrity testing. Asian polymer processors dominate medical-grade silicone supply for specialty variants, creating single-source vulnerability for Western manufacturers.
- Implants:Subdermal rods utilizing progestin-eluting polymer matrices.
- Diaphragms:Reusable silicone barrier devices requiring custom fitting protocols.
Intrauterine devices absorb the bulk of installed capacity; implants are expanding most quickly among long-acting reversible categories.
Technology:
Technology segmentation tracks the underlying biological mechanism, with hormonal platforms commanding premium pricing through formulation complexity while non-hormonal alternatives gain traction among endocrine-conscious patient populations.
- Hormonal:Progestin-releasing systems that thicken cervical mucus and suppress ovulation through steady-state drug delivery. Patent-protected extended-release platforms in this category face impending expiration pressures in key markets.
- Non-Hormonal:Copper-based intrauterine devices and barrier methods that avoid steroid exposure. Scandinavian women's health clinics are piloting bioresorbable polymer formulations for adolescent populations seeking discrete, provider-independent options.
- Barrier:Physical obstruction methods including condoms and diaphragms.
- Intrauterine:Device-based uterine placement systems encompassing both hormonal and copper variants.
Hormonal technology retains the steepest margin profile; non-hormonal alternatives are climbing the fastest as consumer preferences shift toward steroid-free fertility management.
Application:
Application segmentation reflects divergent reimbursement pathways, with family planning services receiving comprehensive coverage under Medicaid expansion while emergency contraception occupies a more fragmented payment landscape.
- Family Planning:Scheduled contraceptive counseling and device provision through clinical channels. State-level Medicaid expansion across multiple US jurisdictions is restructuring demand by pulling uninsured populations into subsidized prescription programs.
- Emergency Contraception:Post-coital intervention methods including copper intrauterine device insertion and oral levonorgestrel regimens.
- Menstrual Regulation:Hormonal devices prescribed for cycle control beyond pregnancy prevention.
- Health Education:Counseling and access programs delivered through public health infrastructure.
Family planning absorbs the bulk of clinical throughput; emergency contraception is gaining share fastest through telehealth-integrated direct-to-patient channels.
End User:
End user segmentation maps to distribution channel economics, with healthcare providers and clinics capturing the highest-value insertion procedures while pharmacies and direct-to-consumer platforms compete on convenience and discretion.
- Women:The ultimate decision-makers and device recipients, increasingly accessing subscription-based delivery platforms that bundle telehealth consultations with automated resupply in urban United States and United Kingdom markets.
- Healthcare Providers:Physicians and advanced practice clinicians performing in-clinic insertions and removals. REACH substance restrictions on persistent organic pollutants are forcing reformulation of silicone curing agents ahead of enforcement deadlines, complicating sterilization validation for their applicator systems.
- Pharmacies:Retail and mail-order fulfillment points for over-the-counter and prescription barrier methods.
- Clinics:Specialized women's health and family planning centers.
Healthcare providers control the bulk of long-acting reversible device placements; direct-to-patient platforms are expanding most quickly among millennial urban demographics seeking discretion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone feedstock from Southeast Asian polymer processors anchors contraceptive device manufacturing across key demand centers, with distribution networks radiating from Singapore, Bangkok, and Ho Chi Minh City to assembly plants in North America and Europe.
United States
Medicaid expansion across twelve states since 2023 has pulled uninsured populations into subsidized long-acting reversible contraceptive programs, restructuring procurement toward hospital networks. FDA safety labeling updates for intrauterine devices reduced provider liability exposure, accelerating clinic insertion rates. Minneapolis and Boston medical device clusters house specialized sterilization validation facilities for in-clinic applicator systems.
Germany
EU Medical Device Regulation harmonization streamlined CE marking pathways for Class IIb contraceptive devices, consolidating European distribution opportunities. ECHA REACH substance restrictions on persistent organic pollutants forced platinum-catalyzed vulcanization migration ahead of enforcement deadlines. Rhine-Ruhr industrial corridor manufacturers now dominate REACH-compliant silicone curing agent supply for condom production.
India
Domestic demand for affordable intrauterine devices surged through government family planning programs and public health infrastructure expansion. CDSCO medical device rules classify copper IUDs as notified devices, requiring manufacturing license compliance for domestic producers. Gujarat pharmaceutical special economic zones host polymer extrusion facilities serving South Asian barrier method markets.
China
NMPA medical device registration reforms compressed approval timelines for hormonal implant submissions, attracting multinational licensing activity. Dual carbon goals drove medical-grade copper processors toward energy-efficient refining technologies for non-hormonal IUD production. Yangtze River Delta medical device clusters integrate precision metalworking with controlled-release polymer synthesis capabilities.
Brazil
ANVISA medical device regulations align with Mercosur technical standards, enabling cross-border distribution throughout South America. Federal family planning program expansions broadened subsidized access to clinic-administered devices in underserved northern states. São Paulo metropolitan health networks pilot telehealth-integrated prescription channels for hormonal patch delivery.
Contraceptive Devices Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue bioresorbable polymer platforms and direct-to-consumer subscription models. The vendor base concentrates around pharmaceutical conglomerates with polymer science heritage, specialized women's health device manufacturers, and over-the-counter consumer health divisions. Three archetypes dominate: hormonal formulation patent holders, precision metalworking specialists for intrauterine systems, and barrier method mass producers. Capacity expansion and strategic portfolio diversification represent the dominant competitive moves, with players acquiring sterilization validation capabilities and telehealth platform integrations.
Within the pharmaceutical-origin tier, Bayer AG and Pfizer Inc. exemplify multinational conglomerates leveraging extended-release drug delivery expertise into contraceptive device portfolios. CooperSurgical Inc. occupies a specialized manufacturing position, anchoring the precision device fabrication segment through in-clinic insertion system production. Among diversified consumer health groups, Reckitt Benckiser Group plc and Church & Dwight Co., Inc. represent over-the-counter barrier method distribution archetypes with pharmacy and retail channel dominance.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Merck & Co., Inc. |
| Reckitt Benckiser Group plc |
| CooperSurgical Inc. |
| Janssen Global Services, LLC |
| Church & Dwight Co., Inc. |
| Mylan N.V. |
| Others |
Supply Flow & Price Mechanics
REACH substance restrictions on persistent organic pollutants gate qualified silicone supply for European condom manufacturers, concentrating premium-tier pricing access among REACH-compliant chemical suppliers while forcing non-EU exporters toward reformulation investments or market exit. This regulatory filter compresses margins for uncertified producers and elevates pricing power for compliant polymer processors serving Western healthcare procurement channels.
Pricing Analysis
Extended-release hormonal implant warranties bundle removal coverage and replacement guarantees into multi-year service contracts, while copper IUD pricing remains unbundled and transactional. Three-tier pricing structure across premium, standard, and economy levels separates patent-protected hormonal systems from generic copper variants and bulk-procured barrier methods. Cost compression in the standard tier is intensifying because Asian silicone supply concentration limits Western manufacturers' negotiating leverage. Medicaid expansion populations exhibit highest price sensitivity, while private clinic networks demonstrate lowest sensitivity for premium hormonal offerings.
Supply Chain Analysis
Regional distribution centers in Singapore, Bangkok, and Ho Chi Minh City anchor hub-and-spoke patterns radiating to North American and European assembly plants. Medical-grade silicone sheeting production concentrates in Thailand, Malaysia, and Vietnam, while copper alloy refining for non-hormonal IUDs centers on Chinese Yangtze River Delta facilities. Supply chain risk manifests as single-source vulnerability for specialty polymer curing agents subject to REACH enforcement deadlines. Distribution runs through hospital network procurement consortia and direct-to-consumer subscription platforms competing on fulfillment speed.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contraceptive device manufacturing is consolidating around polymer science capabilities and sterilization validation infrastructure, with EPA chemical safety assessments and REACH substance restrictions forcing capital-constrained competitors toward exit or acquisition.
For Market Incumbents: Deploy backward integration into medical-grade silicone compounding to secure supply continuity against Asian processor concentration. Anchor market position through acquisition of telehealth-integrated prescription platforms capturing millennial direct-to-patient demand. Patent cliff pressures on extended-release hormonal platforms threaten margin compression; diversify into bioresorbable polymer R&D to extend product lifecycle differentiation. For New Entrants and Emerging Players: Bioresorbable hormonal implant technology offers a technology-first wedge into adolescent and provider-independent segments underserved by traditional clinic-dependent insertion models. White-space opportunity concentrates in Scandinavian women's health clinics piloting removal-free contraceptive platforms. Rural telehealth-integrated channels in Medicaid expansion states present the most penetrable geography for subscription-based delivery models bypassing traditional gatekeepers. For Investors and Strategic Acquirers: FDA safety labeling updates for intrauterine devices are the leading indicator that liability-adjusted provider adoption curves are steepening for compliant manufacturers. Long-term viability across the next decade hinges on sterilization validation capabilities and REACH-compliant chemical supply relationships. Acquisition targets should display in-house polymer synthesis infrastructure or exclusive distribution partnerships with Asian silicone processors. Watch for CDSCO manufacturing license compliance among Indian domestic producers as signal of emerging market consolidation readiness.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Silicone Reformulation | Platinum-catalyzed vulcanization migration secures European market access ahead of enforcement deadlines. |
| Telehealth Platform Integration | Remote prescription channels capture millennial urban demographics seeking discretion and automated resupply. |
| Bioresorbable Polymer R&D Investment | Elimination of removal procedures expands addressable markets beyond clinic-dependent patient segments. |
| Sterilization Validation Facility Acquisition | In-clinic applicator assurance protocols reduce FDA combination product submission timelines. |
| Medicaid Network Procurement Partnership | Hospital system contracting secures volume commitments from subsidized access expansion populations. |
Methodological Framework
Document review covered FDA premarket notification filings, EMA medical device registration databases, and REACH substance restriction enforcement schedules, complemented by interviews with hospital GPO contracts managers, women's health clinic medical directors, biomedical engineers at sterilization validation facilities, and polymer procurement leads at Asian silicone processors. Secondary sources included CMS Medicare reimbursement data, CDSCO manufacturing license records, and NMPA medical device registration reform documentation. Bottom-up demand modeling triangulated against top-down market sizing from trade flow analysis.
Segment-level value and volume trajectories emerged from integrated modeling across product type, technology mechanism, application setting, and end-user channel dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical Medicaid expansion enrollment patterns, FDA safety labeling revision impacts on provider insertion rates, and REACH compliance cost pass-through elasticities. Industry-specific forecast inputs incorporated copper alloy processing efficiency improvements and bioresorbable polymer clinical trial progression timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated EPA chemical safety threshold revisions or abrupt Asian silicone supply disruptions. Outputs reflect documented assumptions regarding Medicaid expansion continuation, REACH enforcement adherence timelines, and hormonal implant patent expiration sequences. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Acoustic Puncture Assist Devices Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Removable Partial Dentures Market
Medical Devices
Blood Irradiator Device Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Transcatheter Bioprosthesis Market
Medical Devices
Membrane Oxygenators Market
Medical Devices
Global Single-Use Medical Device Reprocessing Market
Medical Devices
Global Uterine Manipulation Devices Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
UK Artificial Organs and Bionic Implants Market
Medical Devices
Fluidics for Preclinical Market
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market
Medical Devices
Global Artificial Limbs Market