
 Europe Agricultural Tractors Market | 2026-2036
Europe Agricultural Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agricultural Tractors Market Foresight
CE marking under the EU Machinery Directive is rotating the competitive field by mandating exhaustive conformity assessments before market entry. Deere & Company leverages its precision agriculture software stack to command premium positioning across German and French dealer networks. CNH Industrial N.V. anchors southern European demand through localized manufacturing in Italy and Spain. AGCO Corporation differentiates via Fendt-branded high-horsepower systems engineered for Benelux arable operations.
Agricultural tractors are self-propelled power units rated by engine output, typically delivering drawbar or power-take-off force to operate mounted, semi-mounted, or trailed implements across tillage, seeding, and harvesting workflows. Modern units integrate continuously variable transmissions, telematics hardware, and ISOBUS-compliant control architectures to synchronize implement functions with real-time field mapping. Utility tractors and four-wheel-drive configurations command disproportionate margin pools as mid-scale mixed farms upgrade from aging two-wheel-drive fleets. Compact tractors face intensifying competition from utility-class crossover models that stretch horsepower banding across the less than 50 HP and 50-100 HP segments.
The EU Green Deal and F-Gas Regulation shape engine architecture decisions by compressing timelines for particulate matter and nitrogen oxide compliance, while ECHA's REACH protocols govern chemical composition of hydraulic fluids and coating systems. National regulators in France and Germany layer additional type-approval requirements that extend homologation cycles for non-EU manufacturers. Stakeholders must monitor the interplay between Stage V emissions enforcement and subsidy eligibility under national agricultural modernization programs to calibrate product portfolio timing.
Market Dynamics
Stage V emissions enforcement under EU regulations is compressing product development cycles and forcing engine architecture redesigns across European tractor manufacturers, fundamentally restructuring competitive positioning in high-horsepower segments.
Growth Catalysts
- EU Green Deal Farm to Fork:Tightened emissions thresholds for new agricultural equipment are accelerating fleet replacement among large-scale arable cooperatives in Germany and France.
- Precision farming telemetry:ISOBUS-compliant control architectures and real-time field mapping are expanding tractor replacement cycles as data-driven cultivation justifies capital outlays.
- Benelux arable consolidation:Mechanized grain operations across northern plains are concentrating demand for high-horsepower four-wheel-drive configurations.
Market Restraints
- Stage V compliance costs:Particulate matter and nitrogen oxide thresholds under EU emissions frameworks are elevating engine architecture expenses and squeezing margin pools in sub-100 HP segments.
- Hydraulic fluid chemistry constraints:ECHA REACH protocols governing chemical composition of coating systems and hydraulic fluids are extending homologation timelines for imported powertrain components.
- Utility-class crossover encroachment:Compact tractors face intensifying displacement from stretched-horsepower utility models that blur traditional sub-50 HP and 50-100 HP banding.
Strategic Opportunities
- Polish and Romanian cooperative modernization:Underpenetrated Eastern European markets present white space for precision agriculture software stacks as EU structural funds flow into agricultural mechanization.
- Telematics-enabled predictive maintenance:Convergence of continuously variable transmissions with real-time diagnostic hardware is opening subscription revenue streams beyond equipment sales.
- French national agricultural modernization subsidies:Layered type-approval requirements create regulatory tailwinds for manufacturers with established homologation infrastructure.
Industry Challenges
- CE marking conformity assessment bottlenecks:Exhaustive pre-market entry evaluations under the EU Machinery Directive are compressing launch windows and demanding dedicated regulatory affairs capacity.
- ISOBUS integration complexity:Synchronizing legacy implement fleets with modern control architectures requires specialized field engineering resources that concentrate in German and Italian technical service networks.
- Two-wheel-drive fleet obsolescence:Mid-scale mixed farms face capex intensity barriers when upgrading aging mechanical transmissions to precision-capable power units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agricultural Tractors Market |
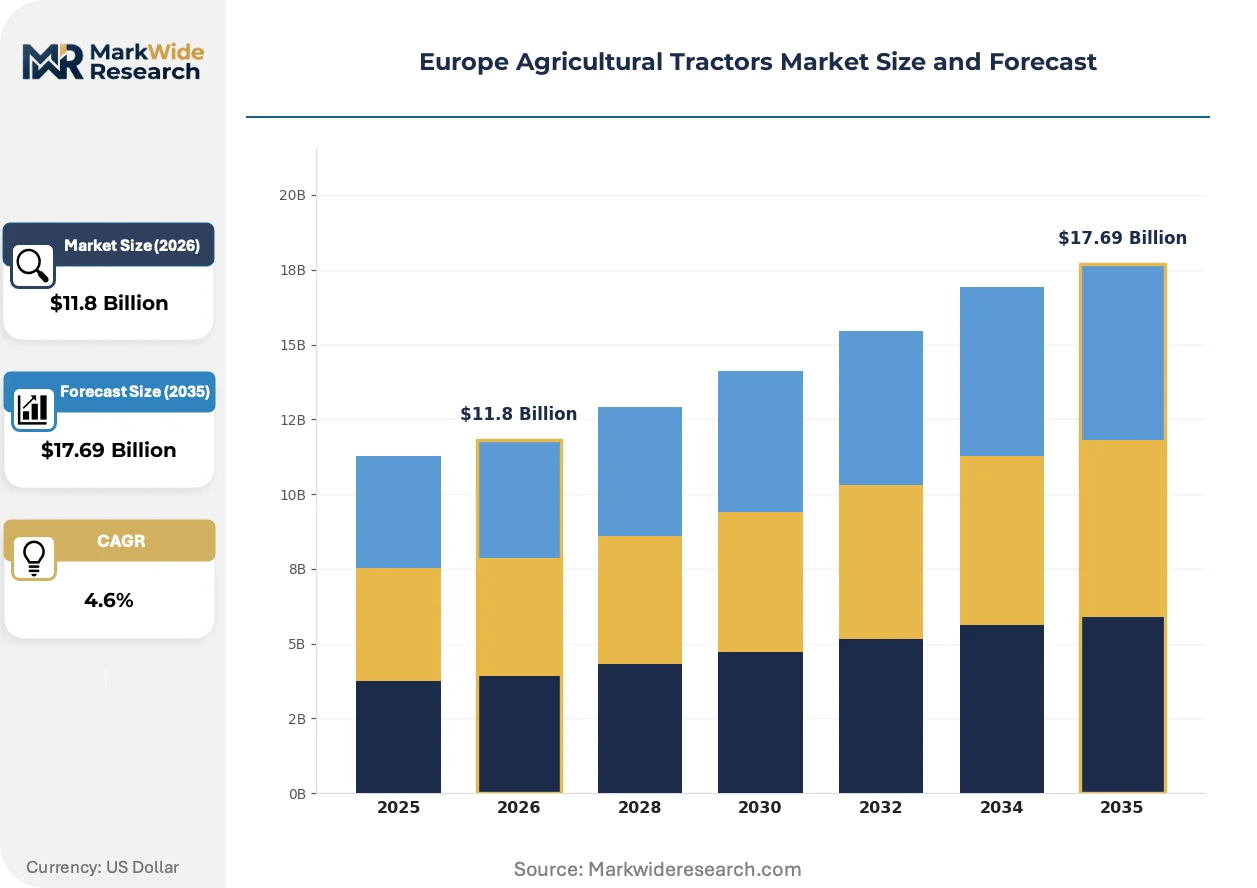
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Utility Tractors, Row Crop Tractors, Specialty Tractors Engine Power: Less than 50 HP, 50-100 HP, 100-150 HP, Above 150 HP Drive Type: Two-Wheel Drive, Four-Wheel Drive, All-Wheel Drive, Dual Drive End User: Farmers, Agricultural Cooperatives, Government Agencies, Contractors |
| Companies Covered | Deere & Company, CNH Industrial N.V., AGCO Corporation, CLAAS KGaA mbH, Kubota Corporation, SDF S.p.A., Argo Tractors S.p.A., Kuhn Group, Lemken GmbH & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agricultural Tractors Market Shifts & Advancements
Powertrain electrification and autonomy-enabling sensor suites are fragmenting traditional horsepower-based segmentation, while regulatory pressure on emissions and chemical composition accelerates architectural divergence between premium and economy equipment tiers.
Continuously variable transmission architectures paired with electro-hydraulic implement control are fragmenting conventional mechanical powertrain supply chains. Large-scale grain cooperatives in northern Germany are adopting these systems at accelerated replacement cycles. The technology is fragmenting historical dealer service revenue models as remote diagnostics displace scheduled maintenance intervals.
EU F-Gas Regulation amendments are tightening refrigerant containment standards for cab climate systems and extending chemical compliance to hydraulic circuit sealing technologies. Engine manufacturers must now certify auxiliary system architectures alongside core powertrain emissions. Italian and Spanish assembly plants face compressed redesign timelines as these requirements layer atop existing Stage V thresholds.
Cooperative procurement consortia are consolidating equipment purchasing decisions across multi-farm memberships in France and Germany. Traditional dealer networks face disintermediation pressure as these consortia negotiate direct manufacturer relationships for fleet-scale orders. This concentration is most visible in Benelux arable operations where acreage scale justifies dedicated procurement functions separate from individual farm decision-making.
Europe Agricultural Tractors Market Segmentation
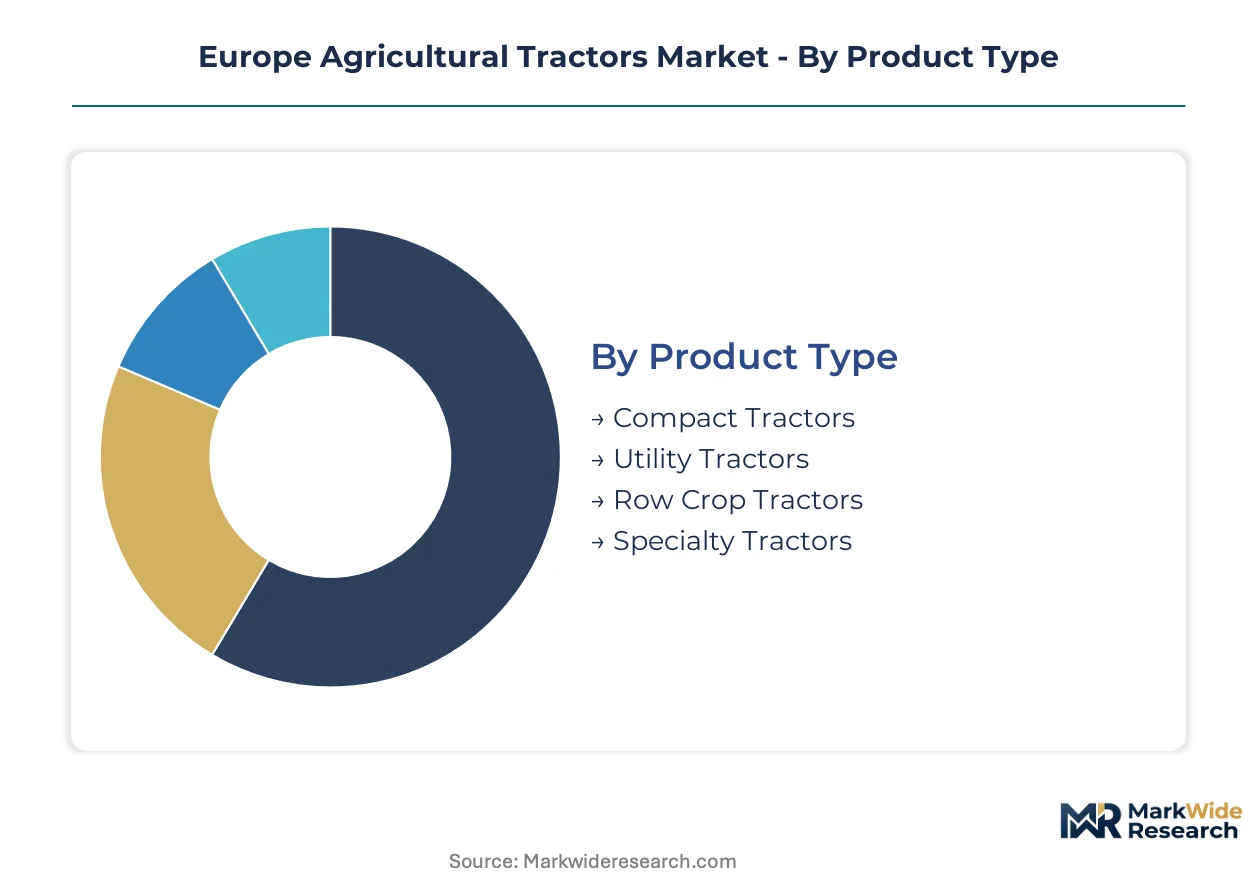
Tractor segmentation in Europe reflects divergent mechanization intensity across national farming structures. German and French procurement patterns favor high-horsepower configurations with precision telemetry, while Eastern European demand concentrates in utility-class units serving smaller consolidated holdings.
Product Type:
Domestic assembly in Italy and Spain anchors southern European supply for compact and specialty configurations, while German and French demand pulls premium utility and row crop units through integrated dealer networks.
- Compact Tractors:Sub-50 HP power units designed for vineyard, orchard, and smallholder mixed operations. Italian manufacturers dominate supply to Mediterranean specialty crop zones, though utility-class crossover models from German OEMs are compressing traditional segment boundaries through stretched horsepower banding.
- Utility Tractors:Versatile 50-100 HP configurations with continuously variable transmissions and ISOBUS-compliant architectures. Polish and Romanian cooperative modernization programs are channeling EU structural funds toward these units as mid-scale farms abandon aging two-wheel-drive fleets.
- Row Crop Tractors:High-clearance designs for mechanized cultivation of cereals and oilseeds across Benelux and northern German plains.
- Specialty Tractors:Narrow-profile and articulated configurations engineered for steep-slope vineyards in France's Champagne region and Italy's Piedmont zone.
Utility tractors command the established base. The steepest expansion runs through compact tractors as Eastern European smallholders mechanize.
Engine Power:
Power banding correlates directly with farm scale and subsidy eligibility under national agricultural modernization frameworks.
- Less than 50 HP:Entry-level mechanical transmissions serving hobby farms and specialty crop holdings. French vineyard operators in Burgundy and Loire Valley represent concentrated demand pockets, though Stage V compliance costs are elevating price points and accelerating consolidation toward utility-class alternatives.
- 50-100 HP:The crossover zone where continuously variable transmission penetration is highest. German mixed farms in Lower Saxony and North Rhine-Westphalia are replacing two-wheel-drive fleets with these precision-capable units, justified by telemetry-enabled cultivation efficiency gains.
- 100-150 HP:Four-wheel-drive configurations standard for arable cooperatives managing consolidated acreage across Denmark and the Netherlands.
- Above 150 HP:Flagship power units with electro-hydraulic implement control for large-scale grain operations.
Above 150 HP configurations anchor revenue concentration. The segment climbing fastest is 50-100 HP as mid-tier farms modernize.
Drive Type:
Mechanical architecture decisions track soil conditions and implement compatibility requirements across European cropping systems.
- Two-Wheel Drive:Mechanical transmissions with rear-axle propulsion, now concentrated in legacy fleet maintenance and Eastern European price-sensitive procurement. Romanian smallholders retain these units longer than Western European counterparts due to capex constraints and less stringent emissions enforcement timelines.
- Four-Wheel Drive:Dominant configuration for arable operations across Germany's northern plains and France's cereal belt, where traction demands and implement weight justify the premium.
- All-Wheel Drive:Articulated chassis designs for extreme terrain and heavy draft applications in Alpine zones and Scandinavian forestry-adjacent farming.
- Dual Drive:Specialized crawler-track or half-track configurations for wet-soil conditions in Dutch polder agriculture and Irish grassland operations.
Four-wheel drive holds the volume base. All-wheel drive is gaining share fastest in terrain-constrained Alpine and Nordic zones.
End User:
Procurement authority is consolidating as cooperative structures and government programs displace individual farm decision-making.
- Farmers:Individual owner-operators managing family-scale holdings, now concentrated in Southern Europe and fragmented Eastern European land structures. Italian and Spanish citrus and olive growers in this category are delaying replacement cycles amid input cost inflation.
- Agricultural Cooperatives:Multi-farm membership organizations consolidating equipment purchasing across pooled acreage. French CUMA structures and German Maschinenring networks are negotiating direct manufacturer relationships, bypassing traditional dealer intermediaries for fleet-scale orders.
- Government Agencies:State procurement for research stations, demonstration farms, and land management authorities under EU Common Agricultural Policy administration.
- Contractors:Custom service providers offering tillage, seeding, and harvesting across non-mechanized holdings, particularly active in Poland's emerging service market.
Agricultural cooperatives command the established base. Contractors represent the steepest expansion trajectory as service-based cultivation models spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cooperative procurement consortia dominate equipment purchasing across northern European arable belts, while fragmented smallholder structures in southern and eastern zones sustain divergent tractor specifications. National subsidy frameworks and emissions enforcement timelines create procurement synchronization effects that ripple through cross-border dealer networks.
Germany
Maschinenring cooperative networks in Lower Saxony and North Rhine-Westphalia consolidate fleet orders for precision-capable four-wheel-drive units. Stage V emissions enforcement through the KBA accelerates replacement of aging two-wheel-drive mechanical transmissions. Stuttgart-based engineering clusters supply continuously variable transmission architectures to OEM assembly plants in Bavaria.
France
CUMA structures across the cereal belt negotiate direct manufacturer relationships for high-horsepower row crop configurations. ANSM type-approval requirements layer atop EU Machinery Directive CE marking, extending homologation cycles for imported powertrain components. Champagne and Burgundy vineyard operators concentrate demand for narrow-profile specialty tractors.
Italy
Piedmont and Emilia-Romagna specialty crop zones sustain compact tractor demand for steep-slope vineyard operations. ECHA REACH protocols governing hydraulic fluid chemistry compress redesign timelines for domestic assembly plants. Localized manufacturing around Modena and Bologna anchors southern European supply for sub-100 HP utility configurations.
Poland
Emerging contractor service models across Masovian and Greater Poland voivodeships displace individual farm procurement authority. EU structural funds channel toward cooperative modernization programs specifying ISOBUS-compliant architectures. Warsaw-based procurement consortia aggregate demand from consolidated post-communist land holdings.
Netherlands
Polder agriculture conditions in Flevoland and Gelderland sustain specialized dual-drive crawler configurations for wet-soil grain operations. Benelux arable consolidation concentrates demand for above-150 HP flagship units with electro-hydraulic implement control. Rotterdam-adjacent logistics clusters facilitate just-in-time component supply to German and Belgian assembly plants.
Europe Agricultural Tractors Market Competitive Landscape
Player mix skews toward integrated full-line manufacturers with captive precision agriculture software stacks. Market structure concentrates around three strategic tiers: premium-positioned telemetry-integrated OEMs, mid-market utility specialists leveraging regional assembly advantages, and compact-focused fabricators serving Mediterranean specialty crop zones. Dominant competitive moves include backward integration into powertrain component supply and strategic partnerships for ISOBUS control architecture licensing.
Among Germany-based precision agriculture specialists, Deere & Company and CLAAS KGaA mbH exemplify the telemetry-integrated tier. Italian-located manufacturers CNH Industrial N.V. and Argo Tractors S.p.A. occupy positions within the southern European supply anchor archetype. AGCO Corporation represents the multi-brand portfolio structure spanning premium Fendt configurations through mass-market utility lines.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial N.V. |
| AGCO Corporation |
| CLAAS KGaA mbH |
| Kubota Corporation |
| SDF S.p.A. |
| Argo Tractors S.p.A. |
| Kuhn Group |
| Lemken GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Ninety-day engine component lead times from Tier 1 powertrain suppliers concentrate pricing power with German and Italian OEMs capable of absorbing inventory carrying costs, while smaller fabricators face margin compression from spot-market steel procurement.
Pricing Analysis
Cost-plus contracts indexed to steel and aluminum London Metal Exchange benchmarks dominate OEM-supplier agreements, with quarterly price adjustments passing through raw material volatility. Pricing stratifies across precision-capable telemetry-integrated premium units, Stage V-compliant standard configurations, and economy mechanical-transmission tiers lacking ISOBUS architecture. Cost compression in sub-100 HP segments intensifies as utility-class crossovers stretch horsepower banding downward. Agricultural cooperatives in France and Germany exhibit lowest price sensitivity due to fleet-scale purchasing and subsidy eligibility, while Romanian smallholders face acute capex constraints.
Supply Chain Analysis
Germany and Italy anchor precision powertrain component fabrication, with Stuttgart engineering clusters supplying continuously variable transmission architectures and Modena-Bologna assembly plants concentrating compact tractor production. Steel forgings, high-pressure common-rail injection systems, and ISOBUS control modules constitute critical input dependencies. Single-source vulnerability concentrates in German-engineered transmission software and Italian hydraulic circuit sealing technologies. Distribution runs through integrated dealer networks in northern Europe and procurement consortia aggregating multi-farm orders, bypassing traditional retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Eastern European cooperative structures and precision agriculture software stacks creates niche entry points as telemetry-enabled cultivation justifies premium positioning among mid-scale farms.
For Market Incumbents: Fortify backward integration into powertrain component supply to capture Stage V compliance cost premiums and defend against utility-class crossover encroachment. Expand captive precision agriculture software licensing to dealer networks, creating switching costs that lock in cooperative procurement consortia. Prioritize homologation infrastructure investment to navigate ANSM and KBA type-approval layering.
For New Entrants and Emerging Players: Anchor in Polish and Romanian cooperative modernization programs channeling EU structural funds, where ISOBUS-compliant utility tractors face supply constraints from established OEMs. Target contractor service models emerging across Masovian and Greater Poland voivodeships with telematics-enabled predictive maintenance subscriptions. Pursue white-label manufacturing partnerships with Italian assembly plants to bypass CE marking conformity assessment bottlenecks.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cooperative procurement centralization and emissions compliance cost escalation will squeeze sub-scale fabricators unable to fund Stage V architecture redesigns. Target mid-market utility specialists with established Eastern European distribution and captive precision agriculture software development. Monitor subsidy eligibility shifts under national agricultural modernization programs as fleet replacement cycle inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powertrain Components | Captures Stage V compliance premiums and reduces exposure to Tier 1 supplier pricing power. |
| Precision Agriculture Software Licensing | Creates recurring revenue streams beyond equipment sales through telemetry-enabled subscription models. |
| Eastern European Cooperative Modernization Partnerships | Secures early positioning in underpenetrated markets as EU structural funds flow into mechanization. |
| Telematics-Enabled Predictive Maintenance Launch | Transforms dealer service revenue models from scheduled intervals to remote diagnostic subscriptions. |
| Homologation Infrastructure Expansion | Accelerates market entry timelines by navigating ANSM and KBA type-approval layering atop CE marking. |
Research Methodology
A spread of perspectives from tractor OEM platform engineers, agricultural cooperative procurement directors, dealer network operations managers, and ECHA regulatory affairs specialists converged on the working assumptions underlying demand modeling. Primary fieldwork combined structured interviews with secondary validation through customs trade data, EU Common Agricultural Policy disbursement records, SEC 10-K filings of listed manufacturers, and KBA type-approval databases. Bottom-up unit shipment estimates triangulated against top-down value projections derived from national subsidy program allocations.
Segmentation dimensions modeled span product type, engine power banding, drive configuration, and end-user procurement authority across the projection horizon. CAGRs emerged from regression analysis against agricultural modernization program budgets, emissions enforcement timelines, and cooperative consolidation trajectories. Forecast inputs incorporated continuously variable transmission penetration rates and ISOBUS architecture adoption curves by farm scale tier.
Material uncertainties — subsidy suspension, Stage V enforcement delays, and steel price volatility — sit outside the modeled envelope. Forecasts reflect assumptions about cooperative procurement centralization and precision agriculture software stack convergence. Recalibration cycles align with material shifts in EU structural fund disbursement patterns and national agricultural modernization program revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
India Tractor Market
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
Agricultural Forestry Machinery Market
Agricultural Machinery
Germany Agricultural Tractor Market
Agricultural Machinery
Wheat Milling Machine Market
Agricultural Machinery
Orchard Tractor Market
Agricultural Machinery
United Kingdom Agricultural Machinery Market
Agricultural Machinery
Driverless Tractor Market
Agricultural Machinery
Autonomous Agricultural Machinery Market
Agricultural Machinery
Agriculture Tire Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
Germany Agricultural Tractor Machinery Market
Agricultural Machinery
Brazil Tractors Market