
 00 Flour Market | 2026-2036
00 Flour Market Size, Share, and Industry Trends Forecast 2026-2036
00 Flour Market Analytics
EU Regulation 1169/2011 on food information to consumers is broadening the cost-of-entry calculus for non-European millers seeking retail placement in member states. Molino Caputo leverages its Naples-based vertical integration to sustain competitive positioning against imported brands. King Arthur Flour differentiates through specialty-distribution partnerships with U.S. artisan pizzerias. Bob's Red Mill anchors its presence in North American natural-channel retail with certified organic milling protocols.
00 flour denotes an ultra-finely milled wheat flour with protein content typically ranging from 11.5% to 13.5% and ash levels below 0.55%, engineered for extensible doughs in pizza, fresh pasta, and laminated pastry applications. The organic and gluten-free product categories command premium shelf positioning as clean-label preferences intensify among restaurant procurement teams. Pasta-making and pizza-dough applications concentrate the highest margin pools due to volume commitments from commercial kitchens and frozen-food processors.
Italy's Ministry of Health enforces strict durum-wheat origin requirements under DOP and IGP frameworks, while the EU's REACH and general food-law standards govern additive limits and labeling transparency across the single market. The U.S. FDA and USDA maintain parallel but non-identical enforcement pathways for enriched-flour fortification and organic certification, creating divergent compliance burdens. Stakeholders must monitor evolving allergen thresholds and carbon-footprint disclosure rules as procurement criteria harden across European and North American foodservice channels.
Market Dynamics
Artisan pizza chains and premium pasta houses now anchor the fastest-growing buyer segment, compressing procurement cycles and forcing millers to certify batch traceability from wheat field to kitchen.
Growth Catalysts
- EU Allergen-Disclosure Mandates:Updated labeling requirements under EU Regulation 1169/2011 are broadening retail placement opportunities for compliant millers in member states.
- Clean-Label Preferences:Restaurant procurement teams now prioritize certified organic milling protocols, pulling premium positioning for transparent supply chains.
- Italy:Reinforced national food-labeling standards and DOP/IGP frameworks concentrate demand validation for authentic 00 flour provenance.
Market Restraints
- Durum-Wheat Input Volatility:Strict origin requirements under Italian Ministry of Health enforcement limit sourcing flexibility and amplify price exposure to Mediterranean harvest cycles.
- Supply Concentration Risk:Naples-based vertical integration by incumbent millers creates captive supply advantages that disadvantage new entrants.
- Regulatory Friction:Divergent FDA and USDA enforcement pathways for enriched-flour fortification versus EU REACH additive limits impose dual compliance burdens on cross-Atlantic suppliers.
Strategic Opportunities
- France:Accelerating offtake across artisan pizzerias and frozen-food processors presents underpenetrated volume expansion for certified importers.
- Carbon-Footprint Disclosure Rules:Emerging procurement criteria across European foodservice channels reward early adopters of verified low-emission milling.
- Gluten-Free Product Convergence:Blending ultra-fine milling technology with alternative grain processing opens shelf positioning in restricted-diet segments.
Industry Challenges
- Certification Timeline Compression:Organic and DOP/IGP audit cycles now run parallel to seasonal procurement windows, straining quality-assurance staffing.
- Legacy Equipment Integration:Stone-milling heritage infrastructure requires retrofitting for real-time batch-tracking compliance without throughput loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 00 Flour Market |
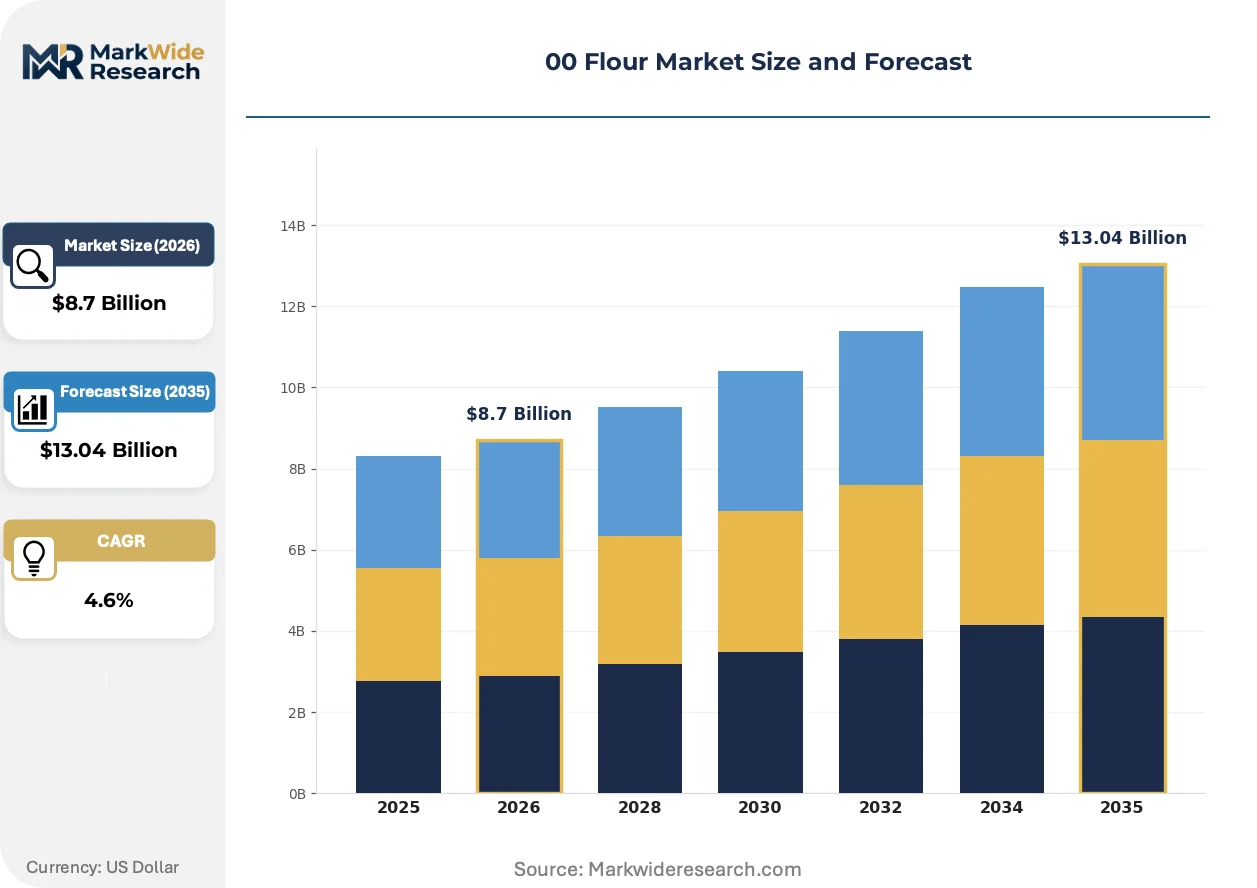
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Gluten-Free, Enriched Application: Baking, Pasta Making, Pizza Dough, Pastry End User: Households, Restaurants, Bakeries, Food Processing Packaging Type: Bags, Boxes, Bulk, Retail Packs |
| Companies Covered | Casillo, Molino Dalla Giovanna, Mulino Caputo, Polselli, Antimo Caputo, King Arthur Flour, Le 5 Stagioni, Granoro, Bob's Red Mill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
00 Flour Market Evolving Landscape
Mechanical and digital advances are compressing production cycles while regulatory layering and buyer sophistication reshape how value is captured across the value chain.
Optical sorting and near-infrared spectroscopy is automating protein and ash content verification at mill intake points. Artisan pizzerias in the United States are adopting these certified-flour specifications fastest, forcing distributors to carry SKU depth that was previously uneconomical. This technology is automating quality gates that once required manual laboratory testing, shrinking batch-release times from days to hours.
REACH and general EU food-law standards now govern additive limits with stricter transparency requirements than parallel FDA frameworks. Industrial consequence includes mandatory reformulation of conditioning agents and enrichment compounds for retail-bound product lines. Frozen-food processors targeting European export markets are responding by segregating production runs and duplicating documentation systems.
Certification-driven preference shifts now dominate restaurant procurement team evaluation protocols. Third-party organic and DOP verification is displacing informal supplier relationships in premium channel placement. This behavioral pivot is most visible across Italy and France, where chain buyers now require documented wheat-field coordinates and mill-audit certificates as standard bid prerequisites.
00 Flour Market Segmentation
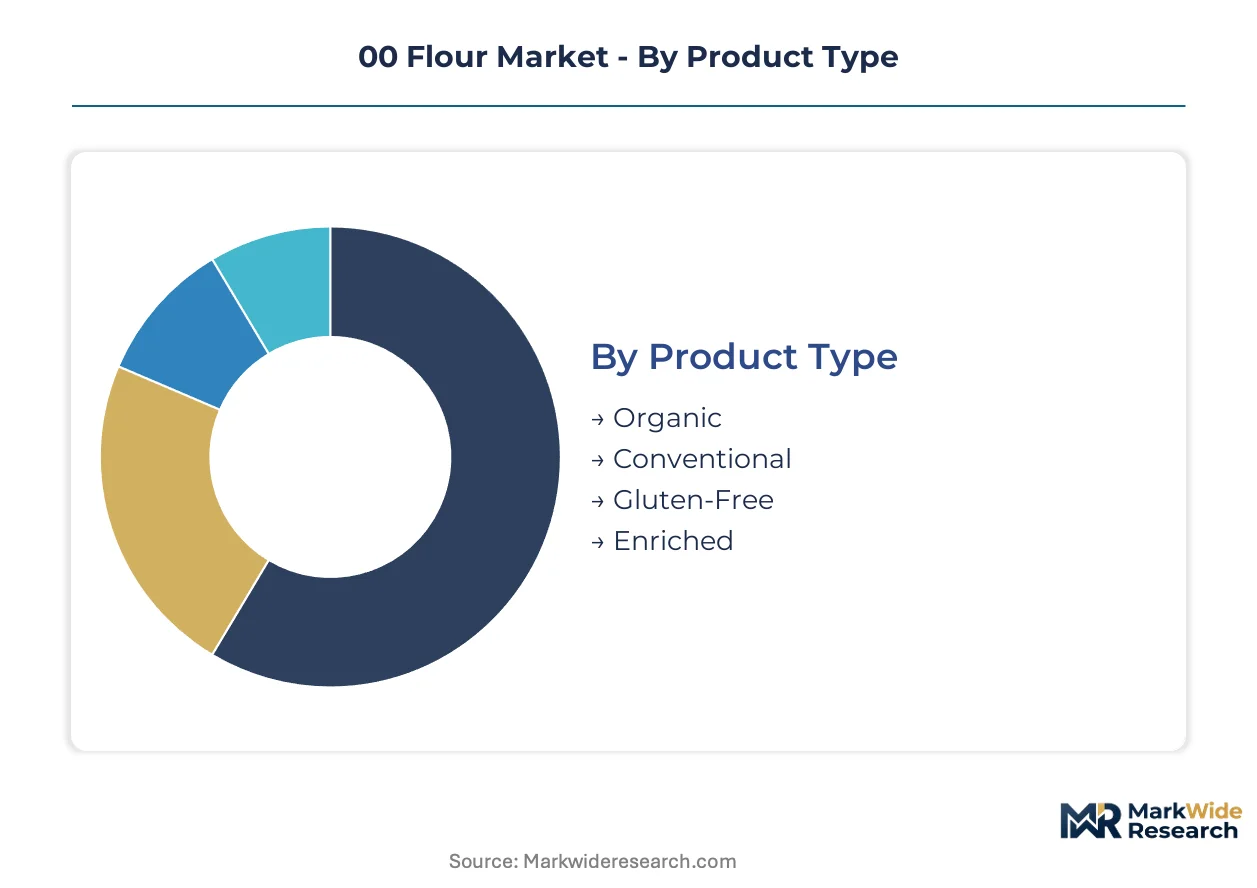
00 flour segmentation tracks how protein specifications, certification tiers, and kitchen workflows split demand across distinct procurement channels. Each axis reveals where margin pools concentrate and which compliance burdens shape supplier selection.
Product Type:
Protein content and ash thresholds define milling precision, while certification status determines channel access and pricing power.
- Organic:Certified organic protocols command shelf positioning in natural-channel retail and premium foodservice procurement. Italian DOP enforcement and EU REACH additive limits pull demand from Naples-based artisan pizzerias and French frozen-food processors seeking documented field-to-mill traceability.
- Conventional:Standard milling specifications dominate volume throughput in commercial baking and mass-market retail. Procurement teams at U.S. pizza chains prioritize batch consistency over certification, compressing price premiums but sustaining baseline margin through scale.
- Gluten-Free:Alternative grain processing with ultra-fine milling technology addresses restricted-diet segments.
- Enriched:FDA-mandated fortification requirements shape U.S. retail formulations separately from EU additive frameworks.
Mature deployment sits with Conventional. Newer deployment is concentrated in Organic.
Application:
End-use dictates dough extensibility requirements and determines whether artisan technique or industrial throughput drives purchasing.
- Pizza Dough:High-hydration formulations demand 11.5-13.5% protein content with ash below 0.55% for optimal extensibility. U.S. artisan pizzerias and Italian chain operators now require certified batch documentation, compressing procurement cycles and forcing SKU depth previously uneconomical for distributors.
- Pasta Making:Fresh pasta applications concentrate margin pools through volume commitments from commercial kitchens and frozen-food processors. France's accelerating offtake across premium pasta houses rewards importers with verified low-emission milling credentials.
- Baking:Laminated pastry and bread applications sustain steady demand in household and bakery channels.
- Pastry:Delicate laminated doughs require precise ash control for tender crumb structure.
Volume leadership rests with Pasta Making. Steepest expansion trajectory belongs to Pizza Dough.
End User:
Procurement sophistication varies sharply between price-sensitive household buyers and specification-driven commercial operators.
- Restaurants:Artisan pizza chains and premium pasta houses anchor the fastest-growing buyer segment. Certification-driven evaluation protocols now require documented wheat-field coordinates and mill-audit certificates as standard bid prerequisites across Italy and France.
- Food Processing:Frozen-food processors targeting European export markets segregate production runs and duplicate documentation systems to satisfy divergent FDA and EU REACH compliance pathways.
- Households:Retail pack purchasers respond to clean-label positioning and organic certification badges.
- Bakeries:Mid-scale operators balance consistency requirements against price sensitivity in bulk procurement.
Established procurement patterns characterize Bakeries. Emerging specification intensity defines Restaurants.
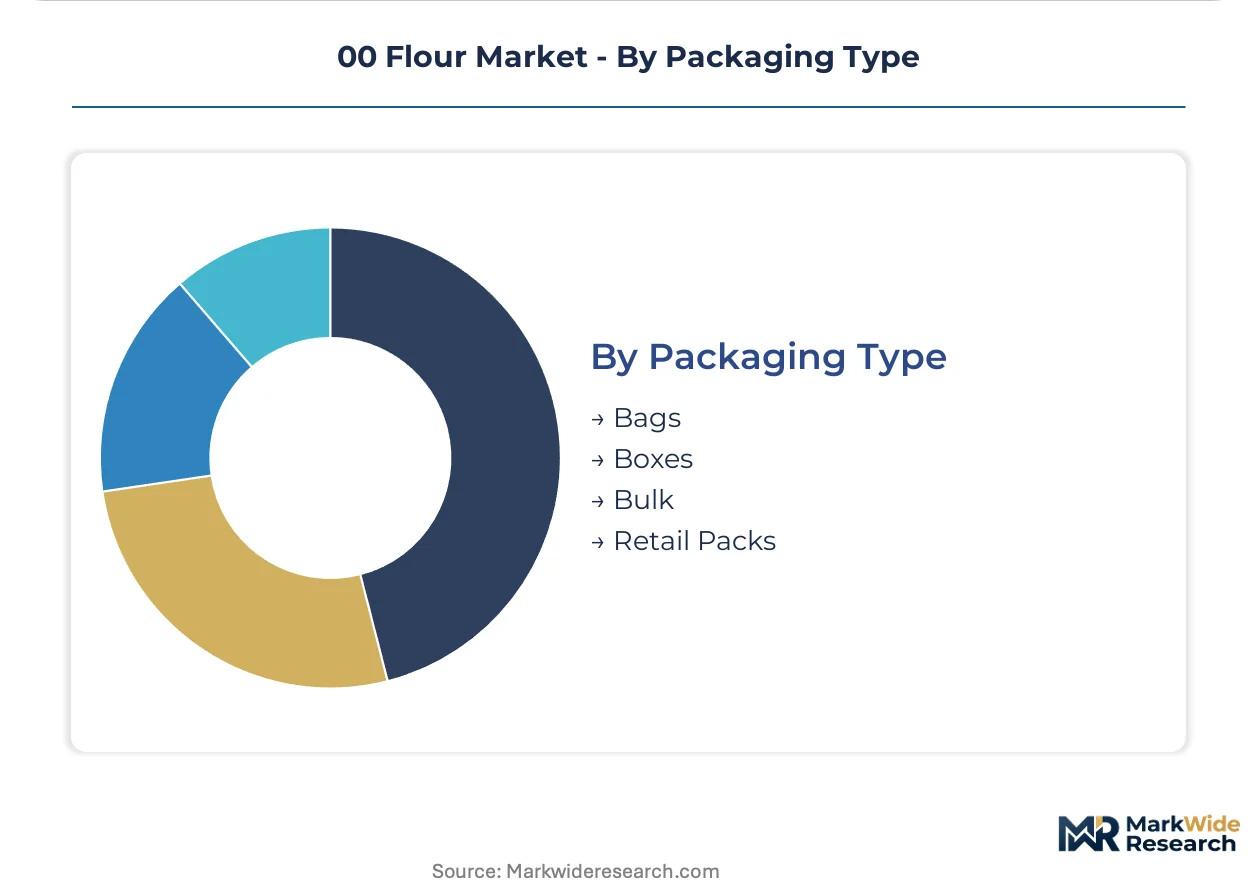
Packaging Type:
Unit economics and shelf-life requirements split logistics strategies between direct foodservice delivery and retail distribution.
- Bulk:Tanker and silo delivery to food processing facilities minimizes per-unit packaging cost. Carbon-footprint disclosure rules across European channels reward bulk shipment consolidation and reduced material intensity.
- Retail Packs:Consumer-facing unit sizes carry premium positioning in natural-channel grocery. King Arthur Flour and Bob's Red Mill compete through specialty-distribution partnerships that satisfy clean-label preferences.
- Bags:Standard foodservice quantities balance handling efficiency with kitchen-scale usability.
- Boxes:Protective corrugated packaging serves premium gift and export segments.
Volume concentration favors Bulk. Premium positioning clusters in Retail Packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Campania's designated origin zones around Naples concentrate premium milling capacity, pulling investment toward certified supply chains that satisfy EU DOP enforcement and U.S. import documentation requirements simultaneously.
Italy
Artisan pizzerias in Naples and Rome drive specification intensity for certified 00 flour with documented wheat-field coordinates. The Ministry of Health enforces strict durum-wheat origin requirements under DOP and IGP frameworks that validate authentic provenance. Emilia-Romagna's frozen-food processors now require parallel organic and low-emission milling certifications for export-bound production runs.
United States
Artisan pizza chains in New York and California compress procurement cycles through distributor SKU depth previously uneconomical at this scale. FDA-mandated fortification requirements for enriched flour create divergent formulation pathways from EU standards. Chicago's specialty distributors now carry certified Italian imports alongside domestic organic milling protocols to satisfy clean-label restaurant procurement teams.
France
Premium pasta houses in Paris and Lyon accelerate offtake for verified low-emission milling credentials that satisfy emerging carbon-footprint disclosure rules. EFSA transparency requirements under REACH govern additive limits with stricter thresholds than parallel U.S. frameworks. Provence-Alpes-Côte d'Azur's commercial kitchens now require documented mill-audit certificates as standard bid prerequisites.
Germany
Industrial bakers in Bavaria and North Rhine-Westphalia balance consistency requirements against price sensitivity in bulk procurement of conventional grades. ECHA enforcement of REACH additive limits governs conditioning agents and enrichment compounds for retail-bound product lines. Baden-Württemberg's mid-scale operators increasingly specify certified organic protocols to access premium channel placement.
United Kingdom
London's restaurant procurement teams prioritize clean-label positioning and organic certification badges in retail pack selection. Divergent post-Brexit enforcement pathways for food labeling create compliance friction against EU REACH standards. The Midlands' frozen-food processors targeting European export markets duplicate documentation systems to satisfy dual regulatory burdens.
00 Flour Market Competitive Landscape
Italian producers anchor one tier; North American specialists hold distribution partnerships that satisfy clean-label preferences through natural-channel retail placement. The vendor base concentrates around vertically integrated millers with captive wheat sourcing and certified organic protocols. Three archetypes dominate: Naples-based heritage millers with DOP vertical integration, U.S. specialty distributors leveraging bakery partnerships, and diversified natural-food companies with certified organic milling infrastructure. Competitive moves center on backward integration into wheat sourcing and certification-driven portfolio diversification.
Among Italian heritage millers, Mulino Caputo and Antimo Caputo occupy positions exemplifying the Naples-based vertical integration archetype, leveraging Campania origin zones for DOP-validated supply chains. King Arthur Flour represents the U.S. specialty distribution model, anchoring presence through artisan pizzeria partnerships that demand specification depth. Bob's Red Mill sits within the natural-channel retail tier, with certified organic milling protocols that satisfy procurement criteria across North American foodservice channels.
| Leading Market Players |
|---|
| Casillo |
| Molino Dalla Giovanna |
| Mulino Caputo |
| Polselli |
| Antimo Caputo |
| King Arthur Flour |
| Le 5 Stagioni |
| Granoro |
| Bob's Red Mill |
| Others |
Value Network & Pricing Analysis
Artisan pizza chains and premium pasta houses now anchor the fastest-growing buyer segment, compressing procurement cycles and forcing millers toward contract-based long-term offtake agreements that lock in batch traceability premiums.
Pricing Analysis
Short lead-time premiums now separate urgent foodservice orders from standard contract cycles, with certified organic protocols commanding shelf positioning in natural-channel retail. Three-tier pricing structure across premium, standard, and economy levels reflects protein content thresholds, DOP/IGP certification status, and documented field-to-mill traceability. Cost compression in conventional grades is intensifying because U.S. pizza chains prioritize batch consistency over certification, squeezing margins. Household retail pack purchasers show highest price sensitivity, while European frozen-food processors demonstrate lowest sensitivity due to carbon-footprint disclosure compliance requirements.
Supply Chain Analysis
Durum wheat supply rests on Mediterranean harvest cycles concentrated in Italy, France, and the United States, with Campania's designated origin zones around Naples anchoring premium milling capacity. Stone-milling heritage infrastructure, optical sorting technology, and near-infrared spectroscopy equipment constitute critical input dependencies. Single-source vulnerability around Naples-based vertical integration creates captive supply advantages that disadvantage new entrants. Distribution runs through specialty-distribution partnerships with U.S. artisan pizzerias and direct bulk delivery to European frozen-food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Regulation 1169/2011 on food information to consumers erects a formidable cost-of-compliance barrier, creating a moat for millers with certified organic protocols and documented batch traceability systems.
For Market Incumbents: Cement competitive positioning through backward integration into Campania wheat sourcing and real-time batch-tracking retrofitting of stone-milling heritage infrastructure. Emerging carbon-footprint disclosure rules across European foodservice channels threaten non-compliant players, making DOP/IGP certification investment the critical defensive lever against imported brands. For New Entrants and Emerging Players: Enter via France's accelerating offtake across artisan pizzerias and frozen-food processors, the most penetrable geography for certified importers with verified low-emission milling credentials. Alternative grain processing for gluten-free product convergence offers white-space positioning in restricted-diet segments, with clean-label restaurant procurement teams as the optimal go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors vertically integrated millers with captive wheat sourcing and certified organic milling infrastructure. Long-term viability hinges on procurement criteria hardening across European and North American foodservice channels. Monitor evolving allergen thresholds and carbon-footprint disclosure rule adoption rates as the key inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wheat Sourcing | Campania origin zones satisfy Italian Ministry of Health DOP enforcement requirements. |
| Certification-Driven Portfolio Diversification | EU REACH additive limits and FDA fortification pathways require segregated production runs. |
| Real-Time Batch-Tracking Technology Deployment | Near-infrared spectroscopy automates protein verification previously requiring manual laboratory testing. |
| Geographic Expansion into France | Paris and Lyon premium pasta houses reward verified low-emission milling credentials. |
| Alternative Grain Processing Capability | Ultra-fine milling technology convergence opens gluten-free restricted-diet market positioning. |
Research Methodology
Independent corroboration across milling operations executives, restaurant procurement managers, frozen-food processor supply chain directors, and specialty-distribution partners underwrites the qualitative findings. Primary interviews with Italian heritage millers, U.S. artisan pizzeria operators, and French commercial kitchen buyers combined with secondary validation from EU customs records, FDA enforcement pathways documentation, and SEC filings of diversified natural-food companies. Bottom-up volume triangulation against top-down value estimates anchored the market sizing envelope.
Rate-of-change decomposition across the projection horizon modeled protein content tiers, certification status, application workflows, and end-user procurement sophistication as core segmentation dimensions. CAGRs derived from historical shipment patterns, import documentation volumes, and channel inventory turns. Wheat harvest cycle volatility, regulatory enforcement intensity, and clean-label preference adoption curves served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Mediterranean climate disruption, abrupt EU allergen-threshold revisions, or divergent FDA-USDA enforcement pathway realignment. Assumptions reflect documented procurement behavior shifts and regulatory layering trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Heritage Grain Market
Grains
IQF Rice Market
Grains
Global Rice Market
Grains
Rice Flour Market
Grains
Oat Flour Market
Grains
Triticale Market
Grains
Africa Maize Market
Grains
Asia-Pacific Rice Market
Grains
Corn Flour Market
Grains
Lentil Market
Grains
North America Oats Market
Grains
Uganda Grains Market
Grains
Global Maize Market
Grains
Organic Oats Market
Grains
Organic Cereals Market
Grains
Rolled Oats Market