
 Europe Rice Market | 2026-2036
Europe Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Rice Market Analysis
Premium-grade and specialty rice tiers is redrawing competitive boundaries across Europe. Riso Gallo leverages its Italian heritage and risotto specialization to dominate premium retail placement. LT Foods sustains its Basmati supply chain from South Asian origins into European distribution networks. KRBL Limited anchors its position through backward integration into Indian milling and aging infrastructure.
Europe rice comprises Oryza sativa grains classified by kernel length, amylose content, and gelatinization temperature, with primary commercial applications spanning direct consumption, foodservice, and processed food manufacturing. Long Grain and Basmati categories lead value contribution due to higher price realization and ethnic cuisine proliferation across the continent. Short Grain rice occupies the fastest-expanding niche as sushi and Mediterranean prepared-food segments deepen their European footprint. Supermarkets and wholesale channels control the bulk of volume flow, though online retail is capturing incremental share among urban households seeking specialty varieties.
EMA and EFSA frameworks govern pesticide residue thresholds and food safety labeling, while the EU Green Deal drives carbon-footprint disclosure requirements across agricultural supply chains. REACH and F-Gas Regulation constrain fumigation protocols and cold-storage refrigerants, elevating compliance costs for importers and distributors. Stakeholders must monitor evolving sustainability certification schemes and origin-traceability mandates as these criteria increasingly determine retail access and procurement contract terms.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing cold-chain logistics options for rice importers while simultaneously mandating carbon-footprint disclosure across agricultural supply chains. These twin pressures are restructuring procurement relationships and elevating compliance costs for distributors serving European retail channels.
Growth Catalysts
- EU Green Deal carbon-accounting mandates:Large retailers now require Scope 3 emissions data from rice suppliers, creating first-mover advantage for traders with certified supply chains and traceability infrastructure.
- Ethnic cuisine proliferation:Sushi, risotto, and South Asian restaurant formats are expanding across Germany, France, and the Netherlands, pulling Basmati and Short Grain volumes into foodservice procurement.
- Italy:Domestic risotto culture and protected-origin labeling for Arborio and Carnaroli varieties sustain premium price realization and defend local milling capacity against commodity imports.
Market Restraints
- REACH and F-Gas Regulation:Phosphine fumigation restrictions and hydrofluorocarbon phase-downs are eliminating low-cost pest control and refrigeration options, forcing capital upgrades at port storage facilities.
- Input cost volatility:Natural gas and electricity price spikes in 2022-2023 permanently reset energy-intensive parboiling and drying economics for European millers.
- South Asian supply concentration:Over 70% of Basmati originates from Punjab and Haryana, exposing European importers to monsoon variability and export policy reversals by Indian authorities.
Strategic Opportunities
- Poland and Romania:Underdeveloped specialty rice penetration in Central and Eastern Europe offers expansion runway for branded premium varieties as disposable incomes converge with Western levels.
- Online direct-to-consumer channels:Urban households in London, Paris, and Berlin are purchasing heirloom and organic rices through subscription models, bypassing traditional wholesale markups.
- CSRD sustainability reporting:Mandatory corporate sustainability disclosures from 2024 are creating procurement preference for rice with certified water-stewardship and deforestation-free credentials.
Industry Challenges
- EFSA maximum residue limit compliance:Batch testing timelines and rejected shipments are stretching working capital cycles for importers sourcing from smallholder-dominated origins with inconsistent pesticide application records.
- Cold-chain reconfiguration:Transitioning port silos and distribution centers from HFC to ammonia or CO2 refrigeration requires engineering retrofit investments that many mid-sized distributors cannot self-finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Rice Market |
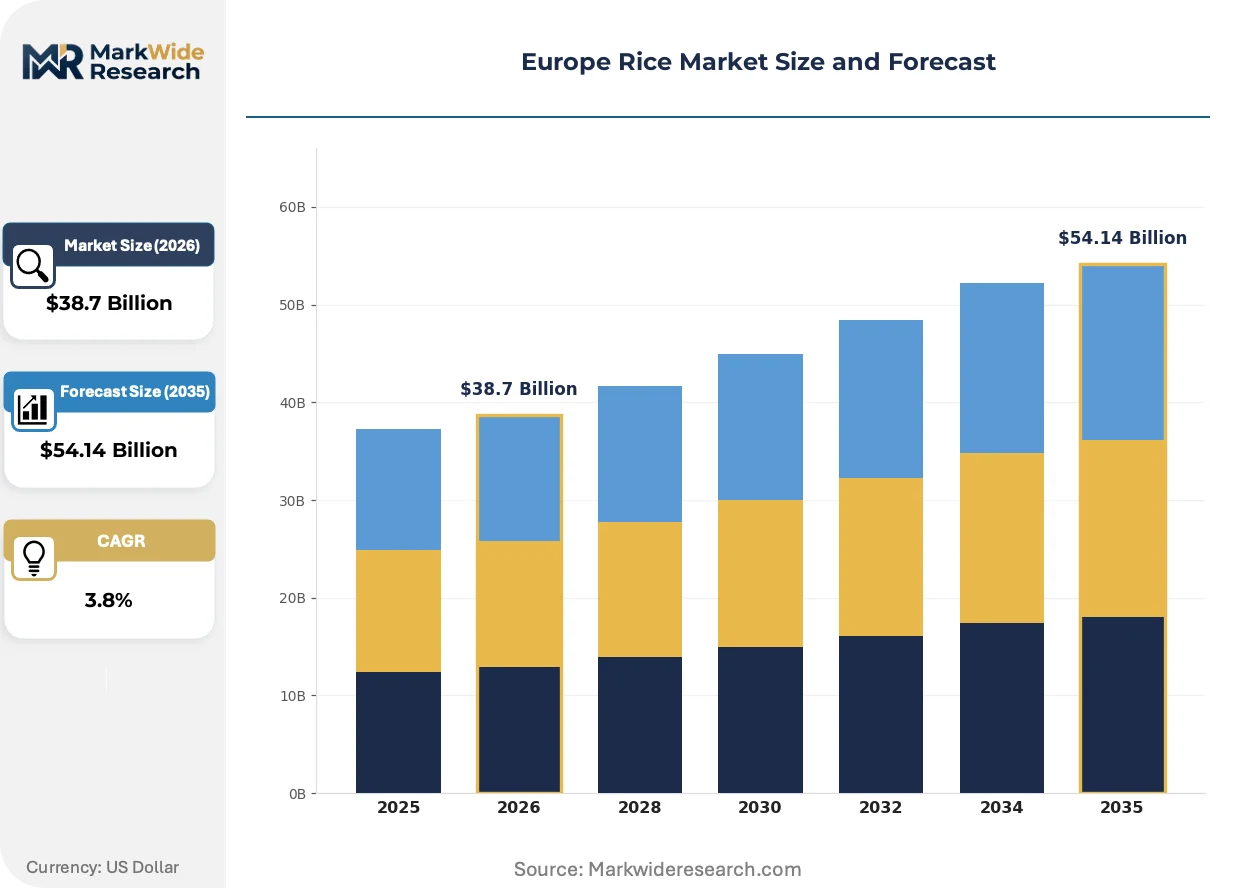
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $54.14 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long Grain, Medium Grain, Short Grain, Basmati End User: Households, Restaurants, Food Processing, Exporters Distribution Channel: Supermarkets, Online Retail, Wholesale, Farmers' Markets Packaging Type: Bags, Boxes, Bulk, Tins |
| Companies Covered | Syngenta, Corteva Agriscience, Riso Gallo, LT Foods, KRBL Limited, Euricom, BASF, Adani Wilmar, Bayer CropScience, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Rice Market Emerging Trajectories
Digital traceability infrastructure and low-carbon processing technologies are converging to reshape how rice moves from Asian origins into European retail. These shifts are compressing traditional quality-assurance timelines while opening new certification-based differentiation pathways.
Blockchain-enabled origin verification is miniaturizing the documentation burden for organic and fair-trade rice consignments. Dutch and German supermarket chains are piloting QR-code scanning that reveals farm-level sourcing data within seconds. This transparency compression is collapsing the information advantage historically held by established trading houses with proprietary supplier relationships.
REACH enforcement against methyl bromide alternatives is tightening fumigation protocols for containerized rice arriving at Rotterdam and Hamburg. ECHA's accelerated substance evaluation timeline is disqualifying several phosphine formulations previously standard in South Asian export packing. Italian and Spanish importers are responding by shifting toward controlled-atmosphere storage investments at destination rather than origin-side chemical treatment.
Foodservice procurement teams are consolidating supplier relationships around full-line distributors capable of delivering both commodity and specialty grades under single contract terms. This buyer concentration is squeezing standalone Basmati specialists who lack Short Grain or Arborio breadth to meet kitchen menu diversity requirements. The compression is most visible in London's restaurant supply chain, where multi-ethnic menu formats demand rice variety portfolios that single-origin traders cannot fulfill.
Europe Rice Market Segmentation
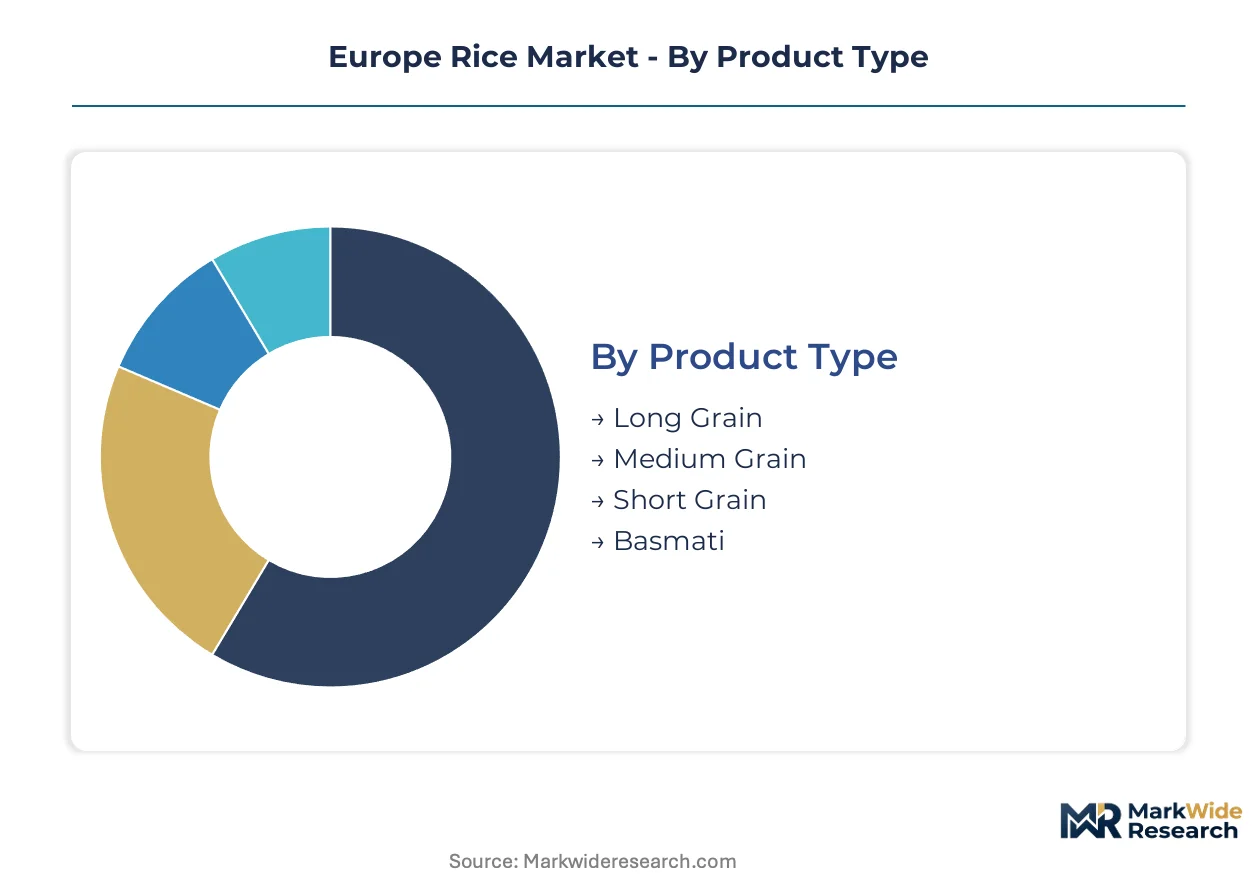
European rice procurement stratifies across four dimensions that determine margin capture and compliance burden. Product type and end-user segmentation exert the strongest influence on pricing power, while distribution and packaging configurations reshape working capital requirements for importers navigating EFSA residue mandates and CSRD disclosure rules.
Product Type:
Substitution pressure runs deepest in commodity-grade segments where Ukrainian wheat and Turkish bulgur erode price positioning, while protected-origin specialty grades defend their placement through culinary tradition and certification barriers.
- Long Grain:High-amylose varieties with firm post-cooking texture dominate industrial food manufacturing and institutional catering across Germany and France. Parboiling capacity in northern Italy and Spain processes substantial volumes for ready-meal manufacturers seeking consistent hydration behavior.
- Basmati:Aromatic long-grain rice from Punjab and Haryana commands premium realization in British and Dutch ethnic retail channels. Import concentration in Indian-origin supply exposes European distributors to DGFT export policy volatility and monsoon-driven volume fluctuations.
- Medium Grain:Balanced starch composition suits Mediterranean pilaf preparations and Spanish paella applications. Italian millers in Lombardy and Veneto maintain regional sourcing networks for restaurant supply contracts.
- Short Grain:High-moisture, waxy varieties with sticky texture profile anchor sushi preparation and Korean restaurant formats expanding across Paris and Berlin. Japanese Japonica genetics dominate this niche, though Italian Carnaroli substitutes penetrate premium risotto applications.
Long Grain retains volume leadership; Short Grain holds the steepest expansion curve.
End User:
Cost tier stratification separates price-sensitive bulk procurement from specification-driven contract manufacturing, with food processors commanding the most stringent traceability documentation.
- Food Processing:Ready-meal manufacturers and snack producers in the Netherlands and Ireland specify moisture content and broken-grain thresholds that dictate milling investment. CSRD Scope 3 reporting requirements now penetrate this segment fastest.
- Restaurants:Multi-ethnic kitchen formats in London and Frankfurt consolidate suppliers around variety breadth rather than single-origin specialization. Full-line distributors capture this consolidation by bundling Basmati, Short Grain, and Arborio under unified contract terms.
- Households:Urban consumers in Milan and Amsterdam purchase heirloom and organic varieties through subscription platforms, bypassing traditional wholesale markups. Packaging size preferences diverge between single-person households and family units.
- Exporters:Rotterdam and Hamburg port operators recondition and relabel Asian-origin rice for onward shipment to African and Middle Eastern destinations. F-Gas Regulation compliance at these facilities now constrains storage economics.
Food Processing commands specification intensity; Restaurants are expanding most quickly.
Distribution Channel:
Volume concentration favors supermarket chains with private-label development capabilities, while margin capture shifts toward direct channels that collapse intermediary layers.
- Supermarkets:Carrefour, Tesco, and REWE control shelf placement and origin-labeling standards across France, Britain, and Germany. Their procurement teams now mandate carbon-footprint disclosure from Basmati suppliers under EU Green Deal implementation timelines.
- Wholesale:Cash-and-carry operators and foodservice distributors in Spain and Italy aggregate restaurant demand across multiple rice categories. Working capital intensity here reflects extended payment terms and inventory holding requirements.
- Online Retail:Amazon and specialized ethnic grocers deliver specialty varieties to urban households in Berlin and Stockholm. Last-mile cold-chain compliance for organic and germinated rice strains adds logistics complexity.
- Farmers' Markets:Direct producer sales of Italian Arborio and Carnaroli operate outside formal wholesale channels, protected by EU protected-geographical-indication frameworks.
Supermarkets retain volume leadership; Online Retail holds the steepest expansion curve.
Packaging Type:
Customer type segmentation separates institutional bulk buyers from retail consumers, with sustainability preferences now penetrating packaging specification.
- Bags:Polypropylene and woven polypropylene formats dominate retail shelf presence across European supermarkets. Recyclability mandates under EU Packaging and Packaging Waste Regulation are forcing material transitions.
- Bulk:Containerized loose rice arrives at Rotterdam and Barcelona for onward milling and repackaging. Fumigation residues and moisture control dominate quality assurance protocols at this stage.
- Boxes:Premium and gift-oriented presentations target holiday demand and specialty retail placement in French and Belgian markets. Unit economics here favor higher-margin organic and fair-trade certifications.
- Tins:Airtight metal packaging preserves aromatic varieties for extended shelf life in export-oriented and emergency-stockpile applications. Italian and Spanish canneries maintain this capacity for institutional clients.
Bags retain volume leadership; Boxes hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rice milling capacity clusters in northern Italy and Spain's Valencia region, with import gateways at Rotterdam and Hamburg handling re-export flows to African and Middle Eastern markets. EFSA residue protocols and EU Green Deal carbon-accounting mandates are reshaping procurement relationships across the continent.
Italy
Domestic risotto culture sustains protected-origin demand for Arborio and Carnaroli varieties in Lombardy and Piedmont. EFSA pesticide maximum residue limits force batch testing timelines that stretch working capital for millers sourcing from smallholder networks. The Po Valley milling corridor maintains regional supply contracts with restaurant chains and ready-meal manufacturers.
Spain
Paella tradition anchors Medium Grain consumption in Valencia and Murcia, while Barcelona port facilities handle containerized Asian imports for re-export. REACH enforcement against phosphine fumigation alternatives is tightening pest control protocols at Mediterranean entry points. Andalusian distributors are consolidating cold-storage investments to comply with F-Gas Regulation hydrofluorocarbon phase-downs.
Germany
Multi-ethnic restaurant formats in Berlin and Frankfurt are pulling Basmati and Short Grain volumes into foodservice procurement channels. CSRD mandatory sustainability disclosures from 2024 create procurement preference for certified water-stewardship credentials. Hamburg port operators face capital upgrade pressure to transition refrigeration infrastructure from HFC to ammonia or CO2 systems.
United Kingdom
British ethnic retail channels concentrate Basmati demand in London and the Midlands, with Indian-origin supply exposing importers to DGFT export policy volatility. Supermarket chains now mandate Scope 3 emissions data from rice suppliers under EU Green Deal implementation timelines. Online direct-to-consumer subscription models are capturing urban households seeking heirloom and organic varieties.
Netherlands
Rotterdam's port infrastructure serves as Europe's primary re-export hub for Asian-origin rice destined for African and Middle Eastern markets. Dutch supermarket chains are piloting blockchain-enabled QR-code scanning that reveals farm-level sourcing data within seconds. Controlled-atmosphere storage investments are displacing origin-side chemical treatment for organic and fair-trade consignments.
Europe Rice Market Vendor Landscape
Concentration sits with heritage millers and integrated South Asian exporters that control aging infrastructure and origin traceability systems. The vendor base spans Italian protected-origin specialists, Indian Basmati traders with backward integration into Punjab milling, and diversified agrochemical conglomerates with seed-to-shelf portfolios. Two strategic archetypes dominate: heritage brands leveraging culinary tradition for premium retail placement, and integrated traders capturing foodservice consolidation through variety breadth. Competitive moves center on cold-chain compliance investments and carbon-footprint certification to secure supermarket procurement contracts.
Within the heritage milling tier, Riso Gallo exemplifies protected-origin specialization through its Italian risotto focus and premium retail placement. LT Foods and KRBL Limited represent the integrated South Asian archetype, with both occupying positions that tie Punjab and Haryana sourcing networks into European distribution channels. Among agrochemical conglomerates, Syngenta and Bayer CropScience sit within seed and crop protection supply rather than downstream milling, anchoring input-side influence over varietal development and yield optimization.
| Leading Market Players |
|---|
| Syngenta |
| Corteva Agriscience |
| Riso Gallo |
| LT Foods |
| KRBL Limited |
| Euricom |
| BASF |
| Adani Wilmar |
| Bayer CropScience |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles at Rotterdam port facilities tether working capital exposure to both EFSA residue testing timelines and the carbon-accounting mandates now penetrating supermarket procurement contracts. This lead-time compression amplifies pricing power for millers with backward integration into South Asian aging infrastructure while squeezing distributors dependent on spot-market sourcing.
Pricing Analysis
EU Green Deal carbon-accounting mandates dictate the pricing tier structure across European rice procurement. Three-tier pricing structure across premium, standard, and economy levels separates protected-origin Italian varieties from commodity-grade imports and bulk foodservice supply. Price differentiation hinges on certification grade and geographic delivery cost, with organic and fair-trade credentials commanding shelf placement premiums at Carrefour and REWE. Cost compression in the economy tier is intensifying because Ukrainian wheat and Turkish bulgur erode rice's relative value proposition in institutional catering. Food processing buyers exhibit the highest price sensitivity due to specification intensity, while direct-to-consumer subscription channels show the least.
Supply Chain Analysis
Strategic stockpile preferences dominate procurement behavior as importers buffer against DGFT export policy volatility and monsoon-driven volume fluctuations from Punjab and Haryana. Geographic supply concentration centers on India, Pakistan, and Thailand for aromatic and long-grain categories, with Italy and Spain retaining captive capacity for protected-origin medium and short grains. Raw material dependencies include phosphine formulations for fumigation, ammonia and CO2 refrigerants for cold-chain compliance, and natural gas for parboiling energy input. Single-source vulnerability from South Asian Basmati concentration exposes European distributors to climate and policy shocks. Distribution runs through Rotterdam and Hamburg port operators for re-export flows, with supermarket chains and wholesale cash-and-carry operators controlling downstream volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe rice sits at a high-growth inflection as CSRD mandatory sustainability disclosures from 2024 restructure procurement preference around certified water-stewardship and deforestation-free credentials.
For Market Incumbents: Compound protected-origin brand equity through controlled-atmosphere storage investments that displace origin-side chemical treatment and satisfy ECHA's accelerated substance evaluation timeline. Deepen backward integration into South Asian milling infrastructure to defend margin position against DGFT export policy volatility. Prioritize cold-chain compliance certification to secure supermarket contracts under F-Gas Regulation hydrofluorocarbon phase-downs.
For New Entrants and Emerging Players: Lead with digital traceability infrastructure as the go-to-market wedge, piloting blockchain-enabled QR-code scanning that collapses the information advantage of established trading houses. Target Poland and Romania for white-space expansion as disposable incomes converge with Western levels and specialty rice penetration remains underdeveloped. Capture urban subscription demand in Berlin, Paris, and Stockholm through heirloom and organic variety curation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cold-chain reconfiguration as port silos transition from HFC to ammonia or CO2 refrigeration. The five-to-ten year viability window favors acquisition of mid-sized distributors with existing traceability infrastructure and supermarket relationships rather than greenfield capacity buildout. Watch for EFSA maximum residue limit enforcement intensity as the signal indicating working capital cycle compression and consolidation opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Storage Investment | Displaces phosphine fumigation and satisfies ECHA substance evaluation timelines for organic consignments. |
| Backward Integration into Punjab Milling | Captures aging infrastructure and insulates against DGFT export policy reversals and monsoon variability. |
| Blockchain-Enabled Origin Verification | Collapses documentation burden and transparency advantage historically held by proprietary supplier networks. |
| Cold-Chain Refrigerant Transition | Secures F-Gas Regulation compliance and supermarket procurement contracts under carbon-accounting mandates. |
| Direct-to-Consumer Subscription Launch | Bypasses wholesale markups and captures urban household demand for heirloom and organic varieties. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with rice millers, import distributors, supermarket category buyers, and foodservice procurement directors; and secondary validation through customs and trade data, EFSA residue limit documentation, SEC filings from listed agribusinesses, and EU regulatory gazettes. Primary fieldwork captured procurement relationship dynamics and carbon-accounting implementation timelines across Italy, Germany, Spain, and the Netherlands. Bottom-up volume modeling triangulated against top-down trade flow analysis.
Across the projection horizon, the analytical framework segmented the market by product type, end-user application, distribution channel, and packaging configuration, with additional granularity on protected-origin certification status. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points and supply concentration risks. Forecast inputs incorporated CSRD disclosure adoption curves, F-Gas Regulation compliance cost trajectories, and South Asian monsoon variability patterns.
The analysis sits within stated boundaries; outcomes outside EFSA enforcement intensity, DGFT policy stability, and EU Green Deal implementation pace would require recalibration. Forecasts reflect documented assumptions regarding supply chain configuration and buyer consolidation trends. Revision becomes warranted when phosphine alternative approval timelines or carbon-border adjustment mechanisms cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Lentil Market
Grains
Chickpeas Market
Grains
Organic Oats Market
Grains
Paraguay Grains Market
Grains
United States Maize Market
Grains
Non-Basmati Rice Market
Grains
Soy Grits Market
Grains
China Wheat Protein Market
Grains
South America Wheat Market
Grains
Corn Flour Market
Grains
South Africa Grain Market
Grains
Global Wheat Market
Grains
United States Rice Market
Grains
Uganda Grains Market
Grains
Africa Wheat Flour Market
Grains
Corn Market