
 Japan Animal Protein Market | 2026-2036
Japan Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Animal Protein Market Foresight
Precision fermentation and alternative protein blending is reconfiguring traditional animal protein processing workflows across Japanese facilities. Maruha Nichiro Corporation leverages its integrated seafood and livestock operations to sustain supply chain control from catch to retail. Nippon Protein Co., Ltd. anchors the industrial collagen and gelatin segment through specialized extraction capabilities. Kerry Group PLC competes in the flavor-protein ingredient space, extending its technical service model into Japanese processed food accounts.
Animal protein encompasses structurally complete proteins derived from livestock, poultry, and aquaculture sources, containing full essential amino acid profiles with biological value scores typically exceeding 0.75 for egg and dairy references. These proteins serve as foundational nutritional inputs for human consumption, pet nutrition, and industrial biochemical applications. Pork and chicken dominate fresh product volumes through established supermarket and wholesale channels, while processed foods and ready-to-eat applications concentrate margin pools as urban household formats shrink. Fish protein differentiates through surimi-based intermediate goods supplying both domestic catering and export-oriented processors.
METI energy efficiency standards and Japan's F-Gas Regulation constrain refrigeration infrastructure investments, directly elevating compliance costs for cold-chain-dependent protein distributors. JIS standards for food-grade gelatin and collagen peptides set compositional thresholds that Nitta Gelatin Inc and domestic competitors must maintain for pharmaceutical and cosmetic market access. Stakeholders must weigh carbon accounting disclosure obligations under evolving CSRD-aligned supply chain reporting against capital deployment timelines for bioreactor-based protein supplementation capacity.
Market Dynamics
Japan's F-Gas Regulation compliance deadlines are forcing cold-chain infrastructure reinvestment across protein distributors, compressing margins while METI energy efficiency standards simultaneously reshape facility capital planning.
Growth Catalysts
- Food service channel expansion:Urban restaurant chains and catering operators drive volume absorption for processed pork and surimi intermediates, with Tokyo's density creating concentrated demand pull.
- Surimi export processing:Domestic surimi-based intermediate goods supply export-oriented processors in Southeast Asia, extending production runs across integrated seafood operations.
- CSRD-aligned carbon accounting:Emerging supply chain disclosure obligations create early-mover advantages for processors with verified emission tracking systems in place.
Market Restraints
- F-Gas refrigeration retrofit costs:Cold-chain-dependent distributors face capital-intensive equipment replacement to meet phase-down schedules for high-GWP refrigerants.
- Feed input price volatility:Compound feed ingredient costs fluctuate with global grain and fishmeal markets, squeezing livestock and aquaculture operation margins.
- Pharmaceutical-grade gelatin concentration:JIS-compliant extraction capabilities cluster with Nitta Gelatin and limited domestic peers, creating supply bottleneck risk for cosmetic and medical applications.
Strategic Opportunities
- Kansai underpenetration:Osaka-Kobe processing infrastructure lags Kanto density, offering greenfield facility placement for collagen peptide and specialized protein fractionation.
- Precision fermentation convergence:Bioreactor-based protein supplementation intersects with traditional blending workflows, enabling hybrid product architectures for processed food accounts.
- Convenience store channel innovation:Lawson and 7-Eleven Japan expand chilled ready-to-eat protein SKUs, creating direct-to-retail bypass of traditional wholesale layers.
Industry Challenges
- Refrigeration technician scarcity:F-Gas-certified service personnel shortages delay compliance retrofit timelines and extend equipment downtime risk.
- Legacy MES integration friction:Bioreactor control systems face protocol mismatch with existing protein processing plant data architectures, complicating automation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Animal Protein Market |
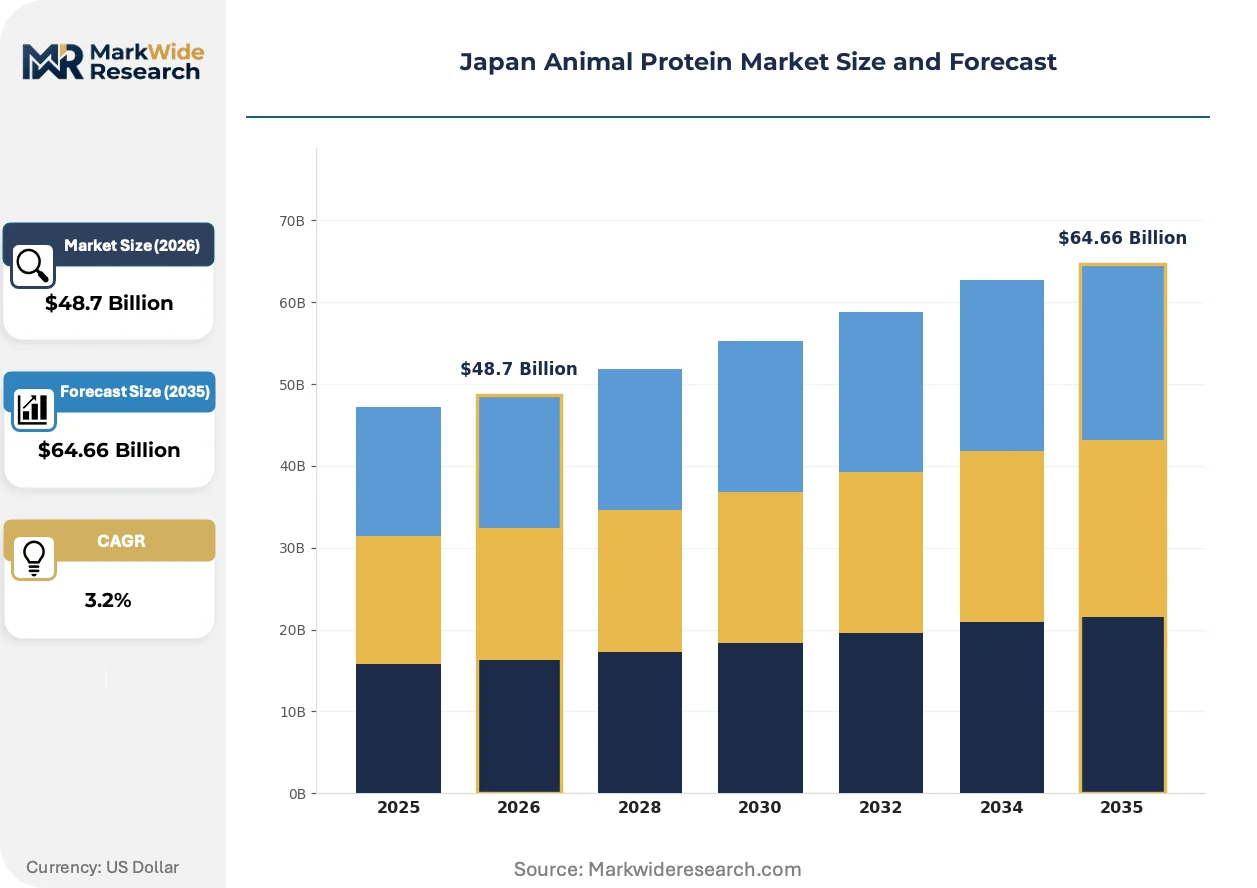
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $64.66 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pork, Chicken, Beef, Fish End User: Retail Consumers, Food Service, Processors, Exporters Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Application: Processed Foods, Fresh Products, Ready-to-Eat, Catering |
| Companies Covered | Lacto Japan Co. Ltd, Maruha Nichiro Corporation, Arla Foods amba, Morinaga Milk Industry Co., Ltd., Nippon Protein Co., Ltd., Darling Ingredients Inc., Royal FrieslandCampina NV, Nitta Gelatin Inc, Kerry Group PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Animal Protein Market Shifts & Advancements
Alternative protein blending technologies and regulatory disclosure mandates are restructuring competitive requirements across Japanese animal protein processing, with facility automation and channel disintermediation emerging as parallel transformation vectors.
Precision fermentation for protein supplementation is collapsing the traditional separation between animal-derived and biotech-enabled ingredient sourcing. Mid-tier processed food manufacturers adopt hybrid blending protocols to maintain label compliance while reducing pure animal protein dependence. This convergence compresses the supplier base toward integrated operations capable of certifying both streams through unified quality systems.
METI's escalating energy efficiency standards and F-Gas Regulation phase-down timelines are accelerating refrigeration infrastructure obsolescence. Cold-chain operators must replace high-GWP equipment ahead of statutory deadlines or face operational shutdown risk. Protein distributors with captive technical service capabilities capture compliance timeline advantages over outsourced maintenance-dependent competitors.
Urban household format shrinkage rotates volume toward single-serve and small-pack protein SKUs. Convenience store chains displace supermarket deli counters as primary chilled ready-to-eat protein access points for younger demographics. This channel shift concentrates procurement power with three national retail operators, compressing supplier negotiation leverage and accelerating private-label penetration in Tokyo and Osaka metropolitan zones.
Japan Animal Protein Market Segmentation
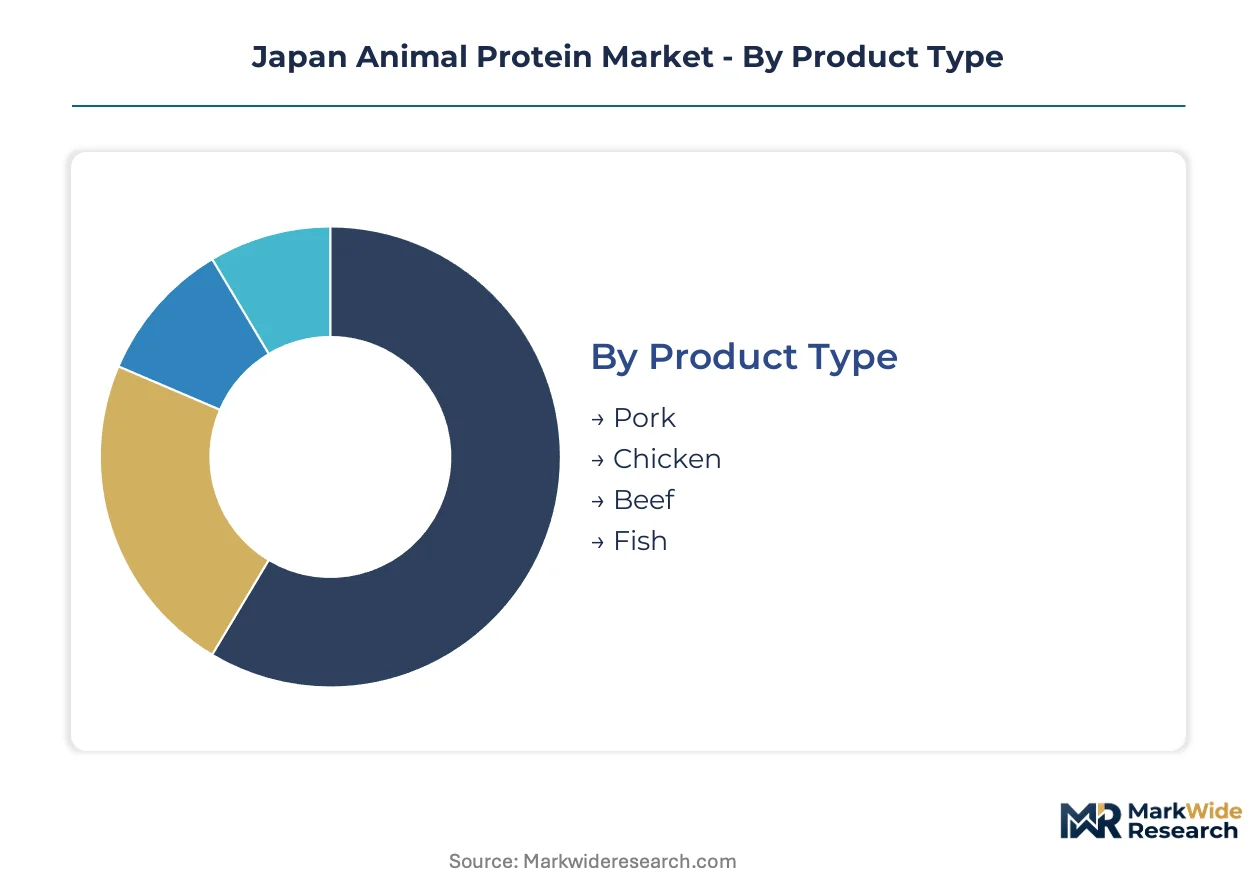
Segmentation in Japan's animal protein market reflects the tension between traditional fresh distribution and processed food innovation. Channel structure and application format determine margin capture more than species selection alone.
Product Type:
Mature categories dominate volume flows while emerging alternatives reshape blending protocols across processing facilities.
- Pork:Domestic breeding stock and imported frozen cuts supply both fresh retail counters and processed ham manufacturing. Tokyo's restaurant density absorbs premium loin volumes while Kyushu processing clusters handle standard-grade conversion for bento and sausage applications.
- Chicken:Broiler operations concentrate in Miyazaki and Kagoshima prefectures with JAS-certified facilities supplying convenience store chains. Breast meat commands premium positioning for ready-to-eat applications; thigh segments flow into yakitori processing and frozen export lots.
- Beef:Wagyu grading systems create extreme price stratification across prefectural brands like Kobe and Matsusaka.
- Fish:Surimi-based intermediates anchor domestic catering supply and Southeast Asian export processing.
Pork retains volume leadership; chicken holds the steepest expansion curve.
End User:
Customer type determines specification rigor, with food service operators demanding tighter delivery windows than retail channels.
- Food Service:Urban restaurant chains and catering operators drive volume absorption for processed pork and surimi intermediates, with Tokyo's density creating concentrated demand pull and just-in-time delivery requirements.
- Retail Consumers:Supermarket deli counters and convenience store chilled sections serve shrinking household formats with single-serve protein SKUs, rotating procurement power toward three national retail operators.
- Processors:Mid-tier manufacturers adopt hybrid blending protocols to maintain label compliance while reducing pure animal protein dependence.
- Exporters:Domestic surimi-based intermediate goods supply export-oriented processors in Southeast Asia, extending production runs across integrated seafood operations.
Food service captures margin concentration; retail consumers show the fastest channel shift toward convenience store access points.
Distribution Channel:
Channel selection directly determines cold-chain compliance burden and METI energy efficiency exposure.
- Supermarkets:Aeon and Ito-Yokado chains maintain fresh meat counters with JAS-certified cutting operations, though deli traffic migrates toward convenience store chilled sections.
- Wholesale:Tsukiji-derived distribution networks and regional produce markets handle institutional volumes with established credit terms for restaurant accounts.
- Online Retail:Amazon Fresh and Rakuten Seiyu expand frozen protein delivery with same-day windows in Tokyo and Osaka metropolitan zones.
- Specialty Stores:Prefectural brand shops and premium butcher counters serve gift-season demand and high-specification Wagyu segments.
Wholesale maintains volume throughput; online retail posts the steepest growth trajectory.
Application:
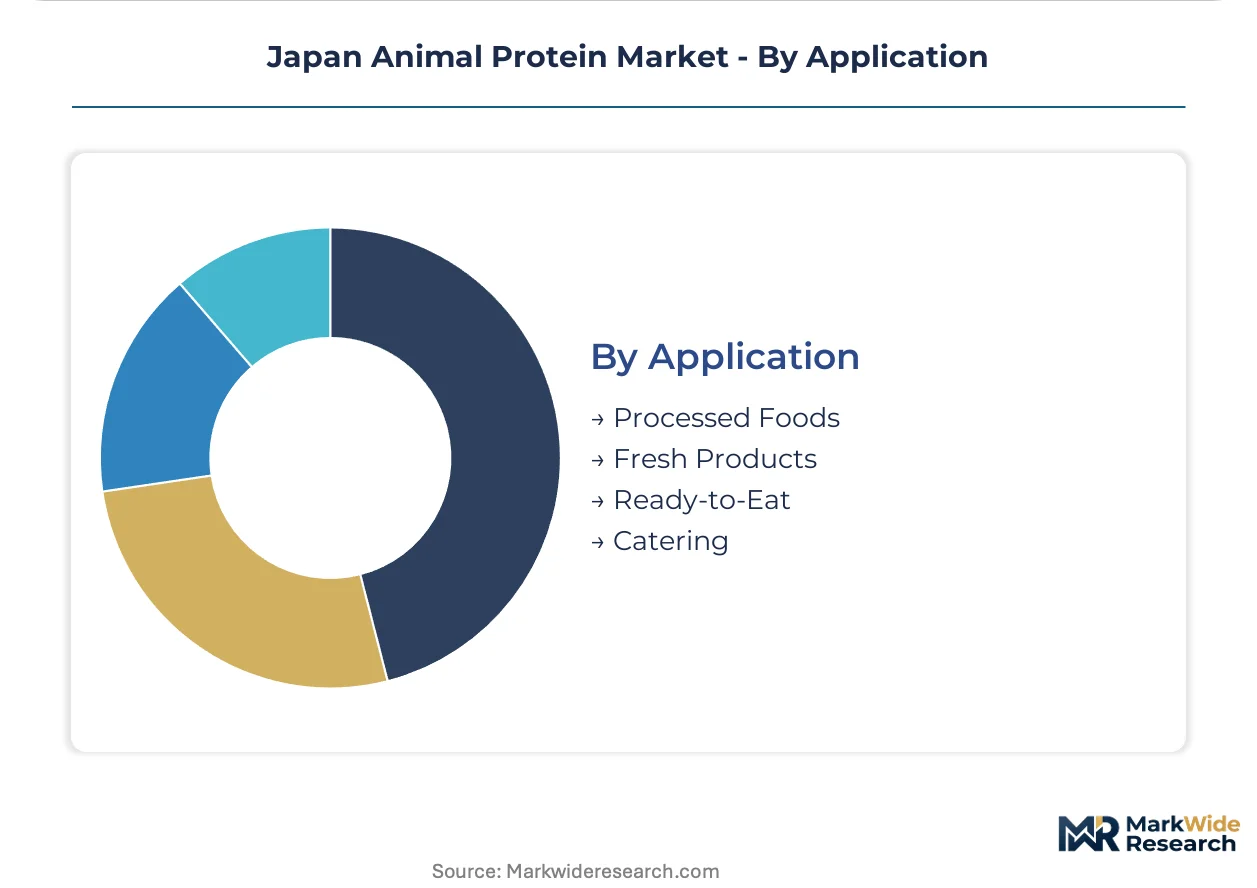
Application format determines processing intensity and margin structure, with fresh products commoditizing against value-added alternatives.
- Processed Foods:Ham, sausage, and surimi-based intermediate goods concentrate margin pools as urban household formats shrink and convenience store chains expand private-label penetration.
- Ready-to-Eat:Lawson and 7-Eleven Japan expand chilled protein SKUs, creating direct-to-retail bypass of traditional wholesale layers with strict shelf-life protocols.
- Fresh Products:Pork and chicken dominate supermarket volumes through established wholesale channels with thin margins and high turnover velocity.
- Catering:Bento manufacturing and institutional food service demand standardized portion formats with JAS-compliant traceability documentation.
Fresh products retain volume leadership; ready-to-eat applications command the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food service buyers concentrate in Tokyo's dense metropolitan core, while Kansai's industrial base offers underexploited processing capacity. Regional protein demand patterns diverge sharply between eastern processing dominance and western consumption growth.
Kanto/Tokyo
Tokyo's restaurant density absorbs premium pork loin volumes and surimi intermediates for urban catering chains. METI energy efficiency standards force cold-chain distributors to retrofit refrigeration infrastructure ahead of F-Gas Regulation deadlines. The Tsukiji-derived distribution network anchors wholesale throughput for institutional food service accounts across the capital region.
Kansai/Osaka
Osaka-Kobe processing infrastructure lags Kanto density, creating greenfield placement opportunities for collagen peptide fractionation. JIS standards for food-grade gelatin constrain pharmaceutical-grade supply to certified extraction facilities. The Hanshin industrial corridor attracts convenience store distribution centers bypassing traditional wholesale layers.
Kyushu
Miyazaki and Kagoshima prefectures host JAS-certified broiler operations supplying convenience store chains with breast meat for ready-to-eat applications. Feed input price volatility from global grain markets squeezes livestock operation margins. Standard-grade pork conversion for bento manufacturing clusters in Fukuoka processing facilities.
Chubu/Nagoya
Nagoya's manufacturing base generates steady institutional food service demand for standardized portion formats. F-Gas-certified refrigeration technician shortages delay compliance retrofit timelines across cold-chain operators. Surimi-based intermediate goods flow through Toyohashi seafood processing hubs toward Southeast Asian export channels.
Hokkaido
Dairy-derived protein processing concentrates in Hokkaido's integrated agricultural operations, supplying collagen and gelatin feedstocks. CSRD-aligned carbon accounting disclosure obligations pressure processors to deploy verified emission tracking systems. Sapporo's wholesale markets handle seasonal fresh protein volumes with established credit terms for regional restaurant accounts.
Japan Animal Protein Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Japan's animal protein market. Maruha Nichiro Corporation and integrated seafood-livestock operators dominate supply chain control from catch to retail, while Nitta Gelatin and Nippon Protein occupy specialized extraction niches. Three strategic archetypes define competitive positioning: integrated conglomerates with captive cold-chain infrastructure, precision fermentation entrants pursuing hybrid protein blending, and regional processors serving convenience store direct procurement. Dominant competitive moves include backward integration into feedstock sourcing and technology licensing for bioreactor-based protein supplementation.
Within the integrated conglomerate tier, Maruha Nichiro Corporation exemplifies supply chain control spanning seafood catch through retail distribution. Nippon Protein Co., Ltd. and Nitta Gelatin Inc occupy positions within specialized industrial protein segments, representing extraction-focused specialists serving pharmaceutical and cosmetic applications. Kerry Group PLC sits within the flavor-protein ingredient space, extending technical service models into Japanese processed food accounts. These three anchors illustrate how competitive positioning stratifies between volume-integrated operations and margin-concentrated specialty niches.
| Leading Market Players |
|---|
| Lacto Japan Co. Ltd |
| Maruha Nichiro Corporation |
| Arla Foods amba |
| Morinaga Milk Industry Co., Ltd. |
| Nippon Protein Co., Ltd. |
| Darling Ingredients Inc. |
| Royal FrieslandCampina NV |
| Nitta Gelatin Inc |
| Kerry Group PLC |
| Others |
Supply & Pricing Matrix
Undercapacity in Kanto region cold-chain infrastructure drives supplier consolidation behavior and reinforces pricing power for integrated distributors with captive technical service capabilities. METI energy efficiency standards and F-Gas Regulation compliance deadlines compress margin flexibility for distributors lacking retrofit capital, concentrating volume flows toward operators with balance-sheet capacity for equipment replacement.
Pricing Analysis
Cost-plus contracts indexed to compound feed ingredient baskets dominate procurement between livestock operators and integrated processors. Three-tier pricing structure across premium, standard, and economy levels separates JAS-certified Wagyu segments from utility-grade pork and chicken cuts. Price differentiation rests on certification grade and volume scale, with pharmaceutical-grade gelatin commanding substantial premia over food-grade alternatives. Cost compression in standard-grade segments is intensifying because feed input volatility passes through contract indexation clauses. Food service operators show highest price sensitivity due to thin restaurant margins, while cosmetic and pharmaceutical buyers absorb premium pricing for JIS-compliant extraction outputs.
Supply Chain Analysis
Tariff exposure between Japan and major grain-exporting economies dominates upstream cost risk for compound feed sourcing. Geographic supply concentration centers on Brazil, the United States, and Argentina for soybean and corn inputs, with fishmeal dependencies drawing from Peruvian and Chilean anchovy fisheries. Raw material dependencies rest on marine protein meal, defatted soybean meal, and corn gluten feed for livestock nutrition formulations. Single-source vulnerability clusters in pharmaceutical-grade gelatin extraction, where Nitta Gelatin and limited domestic peers control JIS-certified capacity. Distribution runs through Tsukiji-derived wholesale networks for institutional food service accounts, with convenience store chains increasingly deploying direct-to-retail procurement bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's animal protein market constitutes a high-growth disruption as precision fermentation convergence with traditional blending workflows reconfigures ingredient sourcing protocols. METI's escalating energy efficiency standards and F-Gas Regulation phase-down timelines create regulatory inflection points that favor capitalized incumbents and technology-licensing entrants.
For Market Incumbents: Build captive cold-chain technical service capabilities as a defensive moat against compliance-driven supplier consolidation. Acquire F-Gas-certified refrigeration technician capacity to compress retrofit timelines and extend equipment uptime advantages over outsourced maintenance-dependent competitors. Backward integration into compound feed sourcing hedges against grain price volatility while securing supply continuity for integrated livestock operations. Precision fermentation licensing agreements represent critical R&D positioning to defend against hybrid protein blending disruption from biotechnology entrants. For New Entrants and Emerging Players: Mid-market collagen peptide fractionation in Kansai represents the most penetrable entry point given Osaka-Kobe processing infrastructure gaps and JIS-compliant extraction capacity constraints. Precision fermentation-enabled protein supplementation for processed food manufacturers offers direct access to hybrid blending demand without requiring full cold-chain infrastructure investment. Go-to-market execution should prioritize technical service partnerships with mid-tier processed food accounts seeking label-compliant animal protein reduction pathways. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cold-chain refrigeration retrofit and bioreactor-based protein supplementation capacity. Long-term viability over the next decade favors integrated conglomerates with captive supply chain control spanning feedstock through retail distribution. Acquisition target archetype: regional processors with convenience store direct procurement relationships and underutilized JAS-certified facility capacity. Signal to watch: F-Gas Regulation enforcement acceleration and METI energy efficiency standard revision schedules as indicators of compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Sourcing | Maruha Nichiro's integrated seafood-livestock operations demonstrate supply chain control from catch through retail distribution. |
| Precision Fermentation Licensing | Bioreactor-based protein supplementation intersects with traditional blending workflows for hybrid product architectures. |
| Cold-Chain Technical Service Capacity Buildout | F-Gas-certified service capabilities capture compliance timeline advantages over outsourced maintenance-dependent competitors. |
| Direct-to-Retail Convenience Store Procurement | Lawson and 7-Eleven Japan expansion creates channel bypass opportunities compressing traditional wholesale layers. |
| JIS-Certified Extraction Facility Investment | Pharmaceutical-grade gelatin concentration with Nitta Gelatin creates supply bottleneck risk for cosmetic and medical applications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with industry stakeholders and systematic secondary validation across regulatory and trade databases. Primary fieldwork encompassed protein processing plant managers, cold-chain distribution operators, compound feed procurement leads at integrated livestock operations, convenience store category buyers, and pharmaceutical-grade extraction facility technical directors. Secondary sources included METI energy efficiency standard filings, JIS certification registries, F-Gas Regulation compliance disclosures, customs trade data for feed ingredient imports, and SEC 10-K filings for multinational ingredient suppliers. Bottom-up capacity and throughput estimates were triangulated against top-down consumption flow analysis.
Forecast inputs considered protein consumption intensity by household format, food service channel expansion rates, surimi export processing volumes, and precision fermentation adoption curves across processed food manufacturing. Segmentation dimensions modeled encompassed product type, end user category, distribution channel structure, and application format across the projection horizon. CAGRs were derived from regression analysis of historical consumption patterns against demographic and regulatory drivers. Industry-specific forecast inputs included F-Gas Regulation phase-down schedules and METI energy efficiency standard escalation timelines.
Practitioners should monitor feed ingredient price volatility, F-Gas Regulation enforcement acceleration, and precision fermentation technology cost curves for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Europe Compound Feed Market
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Mushroom Cultivation Market
Agriculture and Agri Products
Specialty Egg Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market
Agriculture and Agri Products
North America Animal Protein Market
Agriculture and Agri Products
Singapore Floriculture Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Africa Compound Feed Market
Agriculture and Agri Products
Black Sapote Market
Agriculture and Agri Products
Brazil Compound Feed Market
Agriculture and Agri Products
China Compound Feed Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
Australia Animal Protein Market
Agriculture and Agri Products
Global Commercial Seaweeds Market
Agriculture and Agri Products
Indonesia Bamboos Market