
 Wild Rice Market | 2026-2036
Wild Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Wild Rice Market Analytics
Capital-intensity divergence between artisanal harvesters and industrial processors is collapsing as mid-scale operators invest in mechanized lake harvesting and controlled-environment cultivation. Lundberg Family Farms leverages its integrated organic supply chain to sustain premium positioning across retail channels. Moose Lake Wild Rice competes through direct tribal partnerships that anchor authentic provenance claims. SunWest Foods dominates bulk ingredient sales to food manufacturers with standardized grain specifications.
Wild rice comprises the grain of four Zizania species, notably Zizania palustris and Zizania aquatica, characterized by longer kernels, higher protein content than common white rice, and distinctive nutty flavor profiles developed through traditional water-harvesting or paddy cultivation methods. Organic wild rice commands persistent price premiums due to constrained lake harvest volumes and multi-year organic conversion timelines for new paddy acreage. Wild rice blend SKUs occupy the fastest-expanding shelf position as retailers merge heritage appeal with consumer familiarity, while wild rice flour remains a niche ingredient with concentrated demand from gluten-free bakery formulations.
USDA organic standards and FDA food labeling requirements govern product claims and nutritional disclosures across North American distribution, while EU organic regulations and EFSA novel food assessments shape European market access for non-traditional grain products. State-level wild rice management plans in Minnesota and Wisconsin impose seasonal harvesting windows and water quality standards that directly limit annual supply volumes. Stakeholders must monitor evolving organic certification enforcement and indigenous resource rights negotiations as these frameworks increasingly determine who can harvest, process, and label wild rice commercially.
Market Dynamics
Lake harvest cooperatives in Minnesota and Wisconsin face mounting pressure from paddy cultivation expansion as mechanized growers achieve organic certification parity with traditional water-harvested supply. This supply-side bifurcation is compressing provenance premiums while expanding total addressable volume.
Growth Catalysts
- USDA Organic Certification:Federal organic standards for grain handling and processing create transparent quality benchmarks that specialty retailers use to justify shelf space expansion for heritage grain SKUs.
- Gluten-Free Bakery Formulation:Food manufacturers seeking clean-label binding agents drive ingredient demand for wild rice flour in premium bread and pastry applications.
- Minnesota Lake Harvest Concentration:Indigenous cooperative stewardship maintains ecological harvesting practices that command persistent price premiums in direct-to-consumer channels.
Market Restraints
- Input Cost Volatility:Diesel fuel and marine equipment maintenance costs for lake harvesting create margin pressure that paddy growers avoid through controlled-environment mechanization.
- Supply Geographic Concentration:Over 70 percent of authentic wild rice volume originates from Minnesota and Wisconsin lake regions, creating weather-dependent supply risk no alternative geography can replicate.
- Regulatory Friction:EU EFSA novel food assessments impose multi-year approval timelines for non-traditional grain products that block market access for unprocessed wild rice exports.
Strategic Opportunities
- Underpenetrated European Retail:German and Dutch organic specialty chains represent expansion white space where heritage grain positioning remains underdeveloped relative to North American penetration.
- Controlled-Environment Cultivation:Greenhouse and vertical farming convergence with hydroponic grain systems enables year-round organic production outside traditional lake harvest windows.
- Direct E-Commerce Channel:Tribal cooperative-owned platforms bypass wholesale margin compression while capturing full provenance premium through authenticated origin storytelling.
Industry Challenges
- Multi-Year Organic Conversion Timeline:New paddy acreage requires 36-month soil transition periods under USDA standards before certification eligibility, constraining rapid supply response to demand spikes.
- Mechanized Harvesting Skill Gap:Lake harvest cooperatives face operator shortages for specialized airboat and pole-threshing equipment that traditional knowledge transfer cannot scale quickly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wild Rice Market |
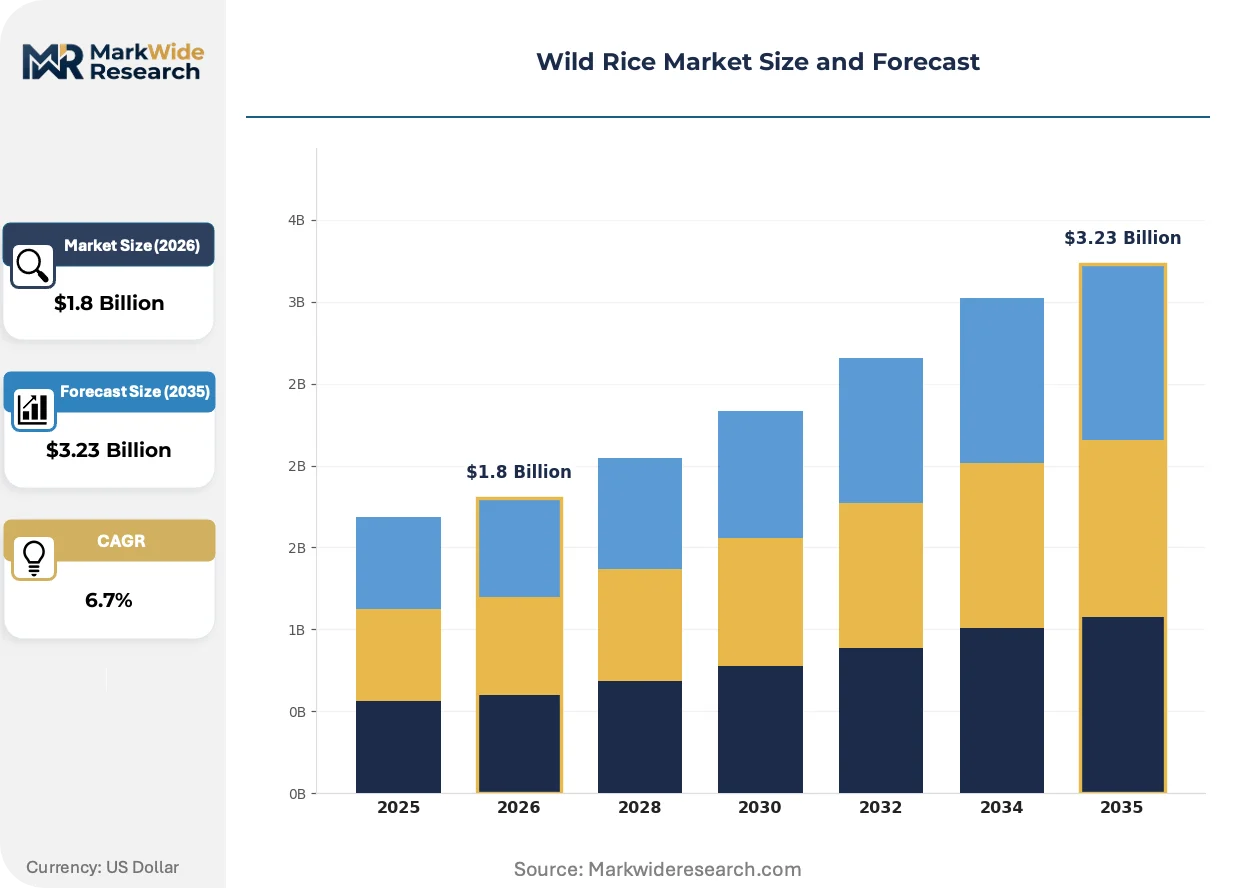
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Wild Rice, Conventional Wild Rice, Wild Rice Flour, Wild Rice Blend End Use: Food Processing, Restaurants, Retail, Meal Kits Packaging Type: Bags, Boxes, Bulk Containers, Pouches Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Farmers' Markets |
| Companies Covered | Moose Lake Wild Rice, Origins Wild Rice Co., Native Harvest, Northern Latitude Foods, Battle River Wild Rice, Lundberg Family Farms, SunWest Foods, Amira Nature Foods Ltd, Wild Rice Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wild Rice Market Evolving Landscape
Mechanized harvesting systems and controlled-environment cultivation are collapsing the historical divide between artisanal lake production and industrial grain supply chains. These converging forces reshape competitive positioning across organic certification tiers.
Mechanized airboat harvesting with GPS-guided lake mapping is fragmenting the traditional cooperative monopoly on authentic wild rice supply. Paddy operators in California and Idaho adopt these systems to achieve organic yield parity with Minnesota lake harvesters. The technology is fragmenting premium pricing power previously concentrated in indigenous water-harvested provenance claims.
EU organic regulations under the EU Green Deal framework tighten supply chain accountability for imported heritage grains. The industrial consequence forces North American exporters to implement batch-level traceability systems that lake cooperatives lack capital to deploy. German organic retailers now demand blockchain-verified origin documentation that only vertically integrated paddy operators can currently supply.
Specialty food buyers increasingly specify certified organic wild rice blends rather than pure varietal SKUs. This procurement evolution displaces single-origin positioning in favor of standardized flavor and texture profiles that food service distributors can reliably source. The shift concentrates most visibly in California restaurant supply chains where menu consistency requirements override provenance storytelling.
Wild Rice Market Segmentation
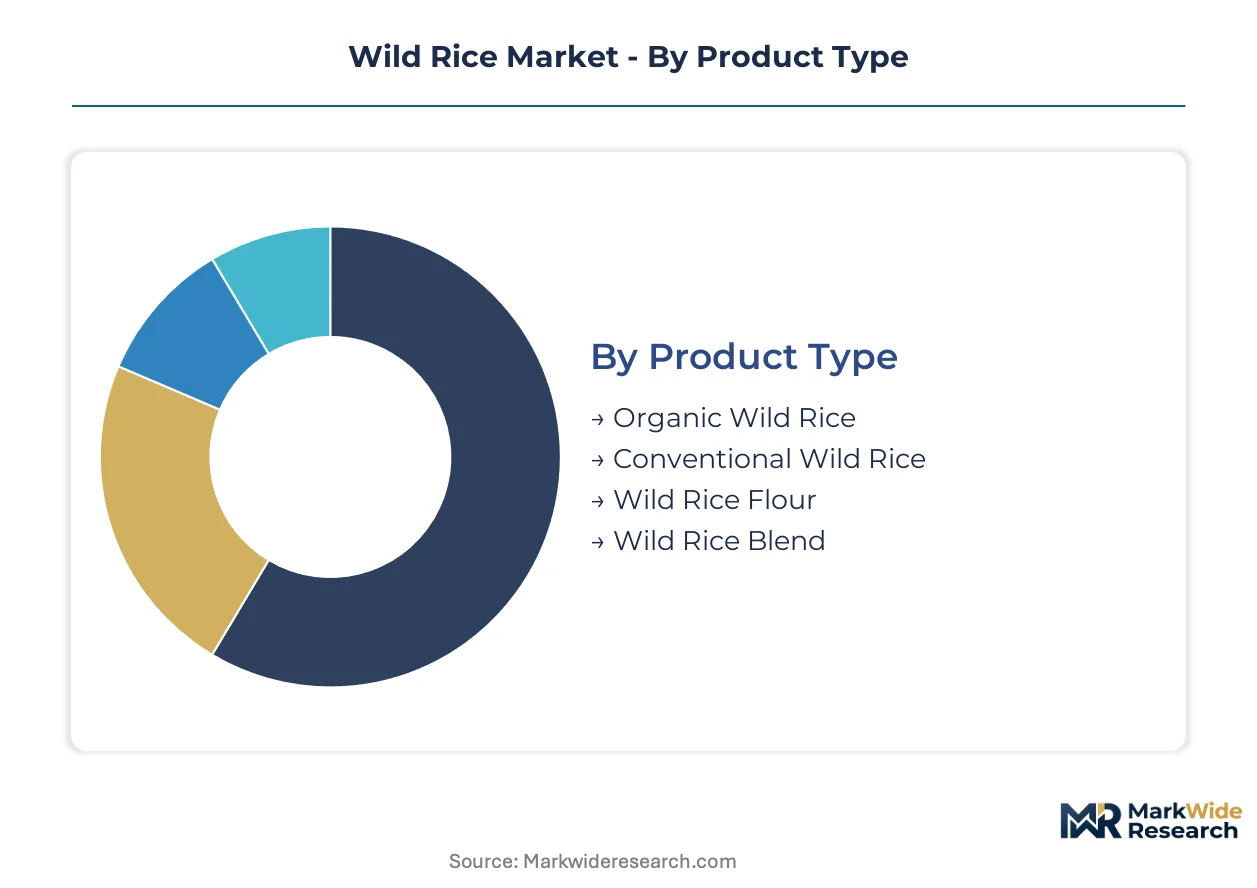
Wild rice market segmentation reveals how certification tiers, packaging formats, and channel strategies fragment revenue concentration across artisanal harvesters and industrial processors. Understanding these divisions exposes where paddy cultivation encroaches on lake-harvested premiums and which distribution pathways preserve provenance value.
Product Type:
Substitution pressure from conventional paddy-grown supply intensifies most acutely against non-certified segments, while organic lake-harvested varieties defend positioning through scarcity mechanics and indigenous stewardship claims.
- Organic Wild Rice:Grown under USDA or EU organic standards with 36-month soil transition requirements and prohibited synthetic inputs. Minnesota and Wisconsin lake harvesters command persistent premiums through indigenous cooperative stewardship and constrained annual volumes.
- Conventional Wild Rice:Paddy-cultivated grains from California and Idaho operations using mechanized harvesting and controlled irrigation. Food manufacturers specify this grade for cost-sensitive blend formulations where provenance claims carry minimal weight.
- Wild Rice Flour:Milled from broken kernels and specialty grades for gluten-free bakery binding applications.
- Wild Rice Blend:Mixed with white, brown, or red rice varieties to reduce per-unit cost while retaining heritage grain menu positioning.
Conventional Wild Rice anchors the volume base while Organic Wild Rice gains share at the steepest rate.
End Use:
Cost tier stratification separates commodity ingredient buyers from premium direct-to-consumer channels, with food service distributors occupying the contested middle ground.
- Food Processing:Bulk ingredient procurement by cereal manufacturers, soup producers, and frozen meal packagers demanding standardized grain specifications and year-round supply security. Paddy operators dominate this tier through volume scale and organic certification parity.
- Restaurants:Menu placement driven by chef preference for single-origin lake-harvested grains in fine-dining contexts, though California supply chains increasingly specify certified organic blends for consistency.
- Retail:Grocery and specialty store shelf placement where packaging storytelling and certification badges drive consumer selection.
- Meal Kits:Pre-portioned heritage grain components for subscription box services seeking differentiated ingredient narratives.
Food Processing commands the largest revenue pool while Meal Kits expand most quickly as subscription services proliferate.
Packaging Type:
Volume scale determines format selection, with bulk containers serving industrial buyers and smaller formats capturing retail premium realization.
- Bags:Standard 1-2 pound paper or plastic retail packages with resealable closures and organic certification callouts. Minnesota-based cooperatives favor kraft paper with tribal provenance storytelling for direct-to-consumer sales.
- Boxes:Rigid cardboard containers for gift sets and premium retail positioning, often paired with recipe cards and origin documentation.
- Bulk Containers:25-50 pound food-grade totes for food service and manufacturing procurement where unit economics override brand presentation.
- Pouches:Lightweight flexible packaging for meal kit portioning and outdoor recreation markets.
Bulk Containers generate the highest tonnage movement while Pouches climb fastest on meal kit channel expansion.
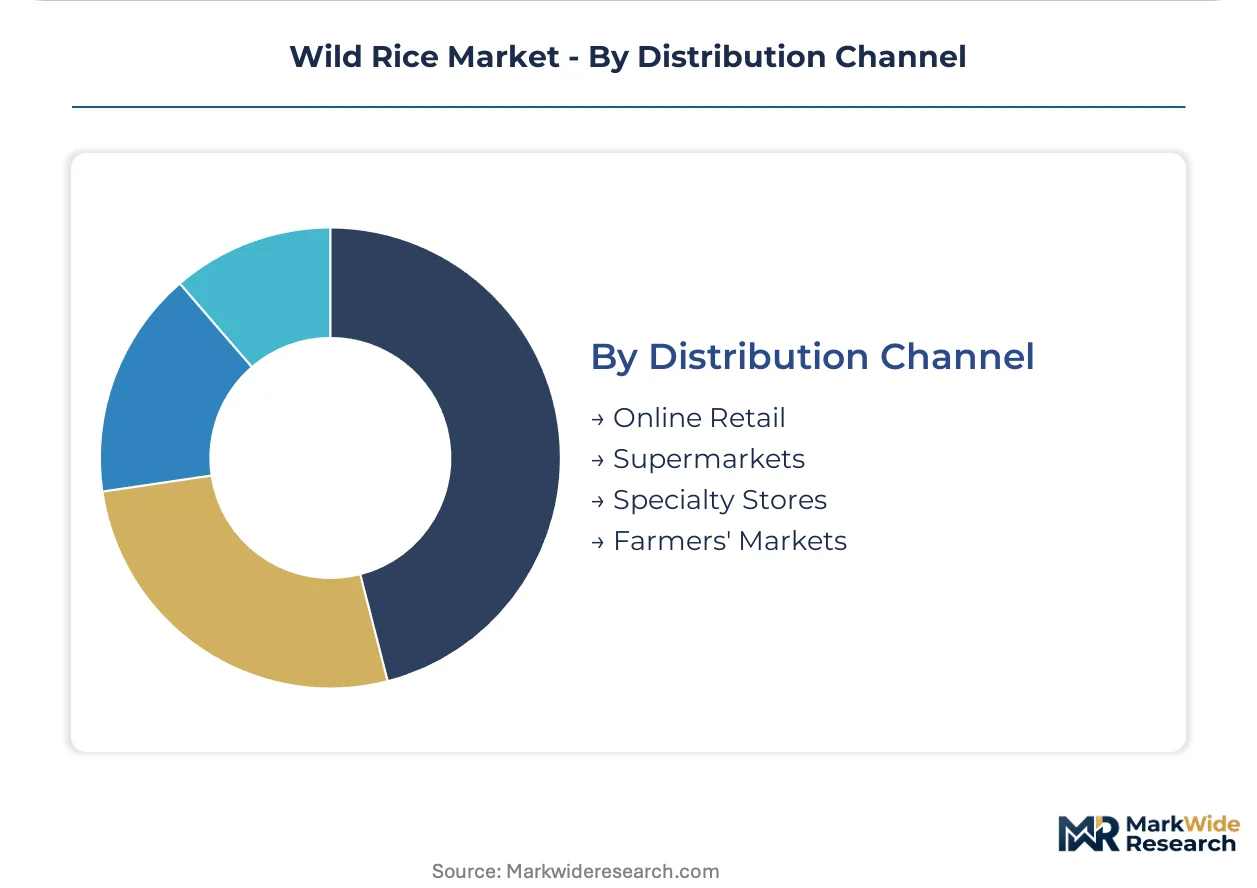
Distribution Channel:
Customer type fragmentation splits between convenience-seeking digital natives and experience-driven physical retail shoppers, with specialty intermediaries defending margin capture.
- Online Retail:Direct-to-consumer platforms operated by tribal cooperatives and vertically integrated paddy growers, bypassing wholesale margin compression. EFSA novel food assessment barriers limit European market access for unprocessed lake-harvested exports.
- Supermarkets:Mass-market shelf placement requiring organic certification and consistent supply volumes that only California and Idaho paddy operations reliably deliver.
- Specialty Stores:Heritage grain positioning in natural food co-ops and gourmet retailers where Minnesota lake-harvested provenance commands price premiums.
- Farmers' Markets:Seasonal direct sales by indigenous harvest cooperatives in Minneapolis, St. Paul, and Madison preserving maximum margin and authentic origin narrative.
Supermarkets dominate volume throughput while Online Retail expands most rapidly on cooperative platform investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lake-harvested wild rice from Minnesota commands price premiums that California paddy operations cannot replicate, while Canadian supply chains struggle with EU market access barriers that American exporters navigate more successfully.
United States
Minnesota and Wisconsin lake regions generate over seventy percent of authentic wild rice volume through indigenous cooperative harvesting. USDA organic certification requirements under the National Organic Program impose thirty-six-month soil transition periods that constrain rapid supply expansion. California paddy operators in the Sacramento Valley now achieve organic parity through mechanized cultivation, fragmenting traditional premium structures.
Canada
Saskatchewan and Manitoba lake harvesters supply heritage grain to North American specialty retailers with strong indigenous provenance claims. Health Canada food labeling regulations govern nutritional disclosures and organic equivalency agreements with the United States. Toronto-based distributors increasingly bypass European markets due to EFSA novel food assessment timelines that favor processed over unprocessed grain exports.
Germany
Berlin and Munich organic specialty chains represent underpenetrated expansion territory for heritage grain positioning. EU organic regulations under the EU Green Deal framework tighten supply chain accountability with blockchain-verified origin documentation requirements. Hamburg importers now demand batch-level traceability systems that strain Minnesota cooperative capital reserves.
Netherlands
Amsterdam and Rotterdam distribution hubs channel wild rice into continental European retail through established organic commodity trading networks. EFSA novel food assessments create multi-year approval bottlenecks for unprocessed lake-harvested imports. Dutch meal kit subscription services drive fastest-growing demand for pre-portioned heritage grain components.
France
Paris gourmet retailers and Lyon food service distributors seek certified organic wild rice blends rather than pure varietal SKUs. ANSM food safety oversight intersects with EU organic certification requirements for imported grains. Provence-based natural food cooperatives experiment with wild rice flour integration in gluten-free bakery formulations.
Wild Rice Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the wild rice supply chain. Lake harvest cooperatives retain authentic provenance positioning through ecological stewardship practices that mechanized operators cannot replicate. The vendor base separates into three strategic archetypes: indigenous cooperative harvesters defending premium tiers, vertically integrated paddy growers capturing scale economies, and bulk commodity traders serving food manufacturers. Competitive moves concentrate on organic certification parity investments and direct-to-consumer platform development that bypass wholesale margin compression.
Among heritage grain specialists, Lundberg Family Farms and Moose Lake Wild Rice occupy positions that exemplify divergent sourcing strategies, while SunWest Foods anchors the bulk ingredient tier serving food manufacturing procurement. These three entities represent the structural split between provenance-driven premium positioning and volume-driven standardization that defines current competitive dynamics.
| Leading Market Players |
|---|
| Moose Lake Wild Rice |
| Origins Wild Rice Co. |
| Native Harvest |
| Northern Latitude Foods |
| Battle River Wild Rice |
| Lundberg Family Farms |
| SunWest Foods |
| Amira Nature Foods Ltd |
| Wild Rice Co. |
| Others |
Value Network & Pricing Analysis
California paddy-grown wild rice displacing Minnesota lake-harvested supply simultaneously shifts production geography toward mechanized operations and compresses provenance premiums that once anchored pricing power in indigenous cooperative channels.
Pricing Analysis
The customization-premium spread between single-origin lake-harvested grains and standardized paddy supply defines market economics. Three-tier pricing structure across premium organic lake-harvested, mid-tier certified organic paddy, and economy conventional paddy levels stratifies buyer access. Price differentiation hinges on USDA organic certification tier and indigenous provenance authentication. Cost compression in mid-tier certified organic segments intensifies as California operators achieve yield parity with traditional harvesters. Food manufacturers exhibit highest price sensitivity, while direct-to-consumer specialty buyers absorb persistent premiums for authenticated tribal sourcing.
Supply Chain Analysis
Minnesota and Wisconsin anchor authentic wild rice production through indigenous lake harvest cooperatives, while California and Idaho dominate mechanized paddy cultivation. Raw material flows draw from diesel fuel, specialized marine airboat equipment, and controlled-environment irrigation systems. Single-source vulnerability concentrates in Minnesota lake regions where weather-dependent harvest windows create annual volume uncertainty. Distribution runs through tribal cooperative direct platforms, specialty retail intermediaries, and bulk commodity traders serving food manufacturing procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against quinoa and heritage grain substitutes eroding wild rice's positioning in gluten-free and premium whole-grain categories.
For Market Incumbents: Shield authentic provenance value through blockchain-verified origin documentation that German organic retailers now demand under EU Green Deal traceability requirements. Deepen backward integration into lake harvest cooperative partnerships to secure constrained supply volumes. Invest in USDA organic certification maintenance as California paddy operators achieve parity.
For New Entrants and Emerging Players: Lead with controlled-environment cultivation in underutilized paddy regions to bypass Minnesota supply concentration risks. Target German and Dutch organic specialty chains where heritage grain positioning remains underdeveloped relative to North American penetration. Deploy direct e-commerce platforms with authenticated tribal storytelling to capture full provenance premium.
For Investors and Strategic Acquirers: EU EFSA novel food assessment streamlining reshapes the acquisition landscape for export-oriented processing assets. Long-term viability centers on vertically integrated operators with batch-level traceability systems that satisfy tightening EU organic regulations. Monitor indigenous resource rights negotiations as the critical inflection signal determining commercial harvest access.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Implementation | German organic retailers demand batch-level origin verification under EU Green Deal frameworks. |
| Controlled-Environment Cultivation Expansion | Greenhouse and vertical farming enable year-round organic production outside traditional harvest windows. |
| Direct E-Commerce Platform Launch | Tribal cooperative-owned channels bypass wholesale margin compression while capturing full premium. |
| Organic Certification Investment | USDA thirty-six-month soil transition requirements create barriers to rapid supply scaling. |
| Heritage Grain Blend Formulation | California restaurant supply chains specify certified organic blends for menu consistency requirements. |
Research Methodology
Cross-validation between cooperative harvest manager interviews and USDA organic certification records anchors the qualitative findings. Primary fieldwork engaged lake harvest cooperative leaders, California paddy operation agronomists, German organic retail buyers, and food manufacturing procurement directors. Secondary validation drew from FDA food labeling databases, EU organic regulation filings, Minnesota state wild rice management plans, and customs trade records. Bottom-up volume estimates from harvest cooperative reporting triangulate against top-down demand modeling from retail channel audits.
Sensitivity analysis around organic certification adoption rates and paddy yield improvements tests forecast robustness across the projection horizon. Segmentation dimensions modeled include certification tier, cultivation method, end-use application, packaging format, and distribution channel. CAGRs derive from logistic adoption curves fitted to historical organic penetration patterns and projected paddy capacity expansion. Industry-specific inputs incorporate diesel fuel cost volatility for lake harvesting and EFSA novel food assessment timeline assumptions for European market access.
Forecasts assume regulatory continuity in USDA organic standards and EU Green Deal traceability frameworks; material policy shifts would require re-modeling. Supply disruption risks from extreme weather events in Minnesota lake regions and indigenous resource rights renegotiations could revise volume projections. Recalibration cycles align with material shifts in organic certification enforcement and European import regulatory streamlining.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Red Rice Market
Grains
Cornmeal Market
Grains
Oat Bran Market
Grains
Global Wheat Market
Grains
Grain Storage Systems Market
Grains
Italy Rice Market
Grains
IQF Rice Market
Grains
Africa Maize Market
Grains
Green Banana Flour Market
Grains
Asia-Pacific Guar Market
Grains
Global Grain Analysis Market
Grains
Precooked Flour Market
Grains
Argentina Maize Market
Grains
Pea Grits Market
Grains
South America Rice Market
Grains
Grain Storage Silos Market