
 South Africa Maize Market | 2026-2036
South Africa Maize Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Maize Market Analytics
Mpumalanga's highveld grain belt is reshaping South Africa's maize production geography as irrigation expansion and cultivar improvements lift yields. BF GLOBAL TRADING (PTY) LTD leverages its logistics network to control movement from silo to port. Chezlynne Trading (Pty) Ltd anchors informal sector distribution through township retail channels. GLOBAL B2B IMPORT AND EXPORT TRADE (PTY) LTD competes on cross-border sourcing into neighboring SADC markets.
Maize, Zea mays, is a cereal grain with kernel moisture content typically dried to 13.5% for safe storage, processed through dry milling into grits, meal, or flour for food and feed applications. White maize dominates human consumption channels, where per capita intake remains among the highest globally, while yellow maize leads animal feed formulations due to superior metabolizable energy content. Maize meal commands the deepest margin pools in retail distribution, whereas biofuel applications remain nascent pending policy clarity on blending mandates.
South Africa's Department of Agriculture regulates cultivar certification and GMO approval under the Genetically Modified Organisms Act, while the Department of Trade, Industry and Competition monitors export licensing and price stabilization mechanisms. BIS standards for grain grading and the Agricultural Product Standards Act enforce quality tiers that determine market access for domestic and export shipments. Stakeholders must track water allocation reforms and electricity reliability as these variables determine milling cost structures and storage economics.
Market Dynamics
Animal feed processors are consolidating yellow maize procurement as poultry production scales across Gauteng and Mpumalanga, tightening the link between grain logistics and protein supply chains.
Growth Catalysts
- Poultry sector expansion:Integrated broiler operations in the highveld are lifting compound feed demand, pulling yellow maize through dedicated supply contracts.
- Cultivar registration rules:The Department of Agriculture, Land Reform and Rural Development enforces seed quality standards that accelerate adoption of higher-yielding certified varieties.
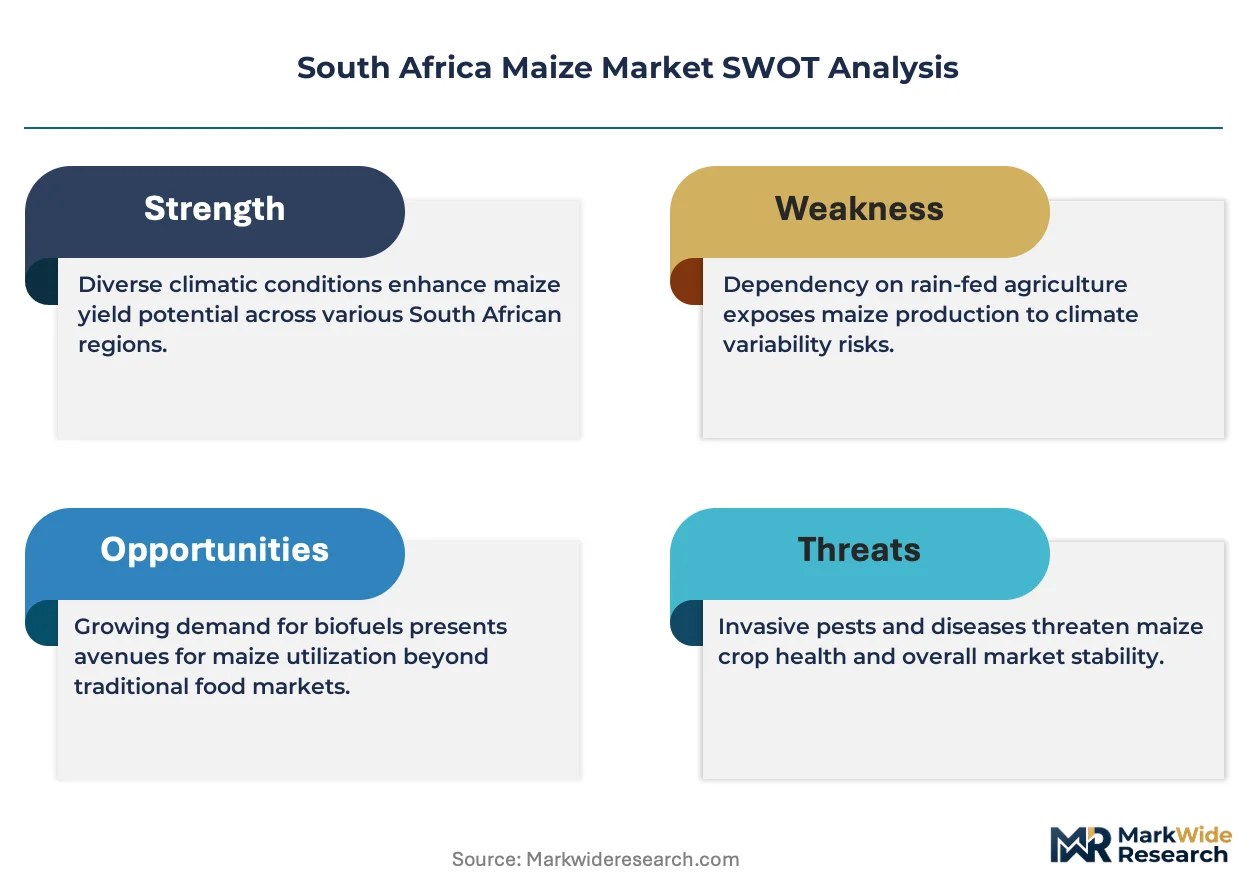
- Logistics hub clustering:Milling and storage infrastructure concentrates around Johannesburg and Pretoria, reducing inland transport costs for processors.
Market Restraints
- Electricity reliability constraints:Eskom load-shedding disrupts irrigation scheduling and milling operations, elevating diesel generator costs for grain elevators.
- Water allocation uncertainty:Reform of water-use licensing in Mpumalanga threatens irrigation expansion timelines for commercial maize farms.
- Input cost volatility:Fertilizer and fuel price swings compress farm-gate margins, deterring planting commitment in marginal rainfall zones.
Strategic Opportunities
- SADC cross-border sourcing:Deficit markets in Zimbabwe and Mozambique present arbitrage channels for South African traders with bonded warehouse access.
- Biofuel blending clarity:Pending policy resolution on ethanol mandates under the Biofuels Industrial Strategy would unlock dedicated industrial offtake.
- Township retail formalization:Informal distribution networks in Gauteng townships offer consolidation targets for branded meal packagers.
Industry Challenges
- Silos and storage capex intensity:Modern temperature-controlled grain elevators require substantial capital outlay, disadvantaging smaller cooperatives.
- GMO certification timelines:Approval pathways under the Genetically Modified Organisms Act delay cultivar commercialization, compressing effective seed life cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Maize Market |
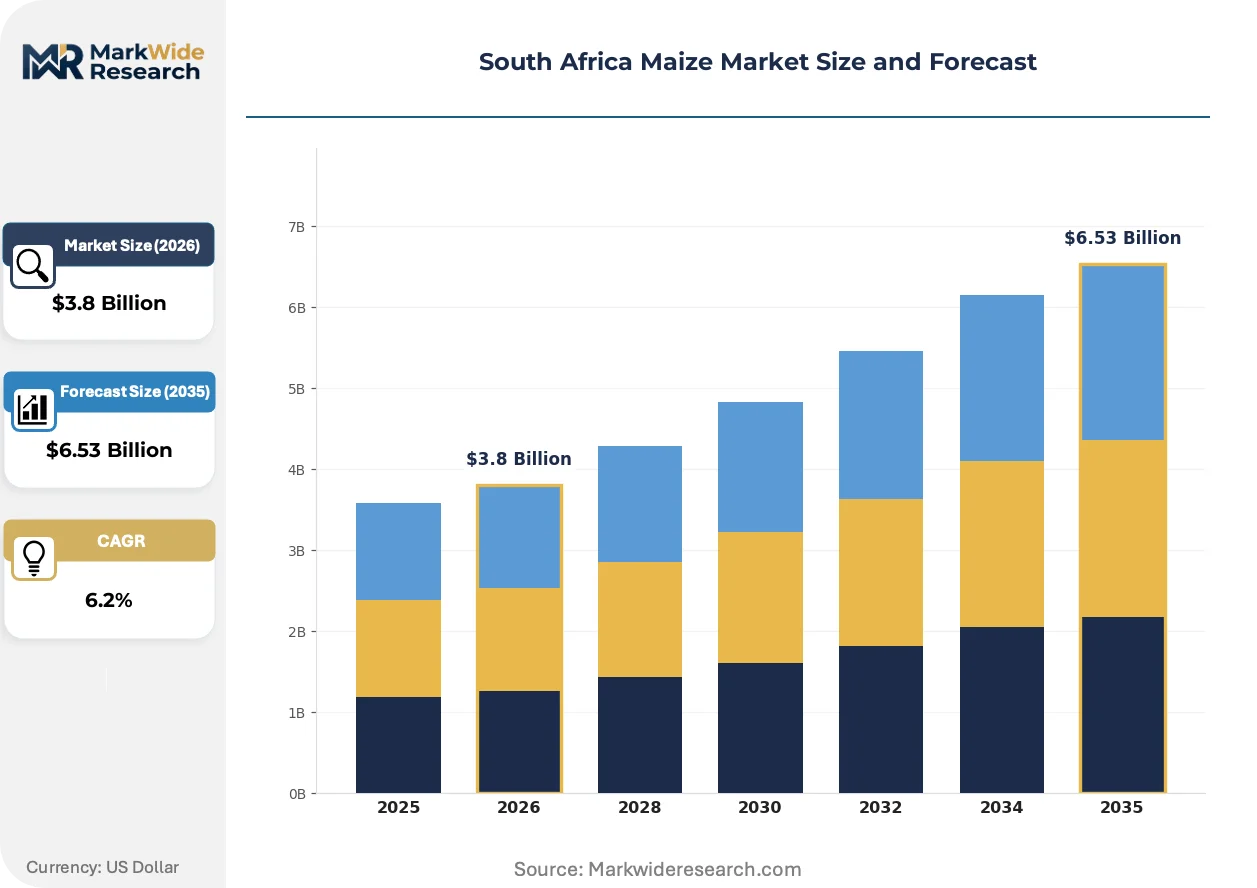
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Maize, Yellow Maize, Maize Meal, Maize Flour Application: Animal Feed, Human Consumption, Biofuel, Industrial Use Distribution Channel: Wholesale, Retail, Direct Supply, Export End User: Agricultural Sector, Food Manufacturers, Retail Chains, Exporters |
| Companies Covered | Foshan Mafrika Stock And Supplies, Chezlynne Trading (Pty) Ltd, Luswepo Warehouse & Logistics, Galiano Gold, Absa Kenya, GLOBAL B2B IMPORT AND EXPORT TRADE (PTY) LTD, BF GLOBAL TRADING (PTY) LTD, Global South Utilities, Takalash, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Maize Market Evolving Landscape
Precision agriculture tools and digital grain trading platforms are compressing information asymmetries between farmers and processors, while regulatory scrutiny of genetically modified traits intensifies cultivar development cycles.
Gene-edited drought-tolerant maize varieties are hybridizing conventional breeding pipelines with CRISPR-based trait stacking. Seed companies serving the Mpumalanga highveld are piloting these materials under confined trial permits. The technology is hybridizing yield stability expectations across rain-fed production zones previously considered marginal.
The Agricultural Product Standards Act enforcement is tightening mycotoxin thresholds for human-consumption white maize. Millers in Gauteng are retrofitting optical sorting equipment to meet grade specifications. Packaged meal brands targeting retail shelves face the steepest compliance investment burden.
Direct farmer-to-processor contracting is displacing spot-market sales at silo delivery points. Poultry integrators in the highveld are locking in six-month forward supply agreements to secure volume certainty. This pattern concentrates procurement leverage with vertically integrated feed compounders at the expense of independent traders.
South Africa Maize Market Segmentation
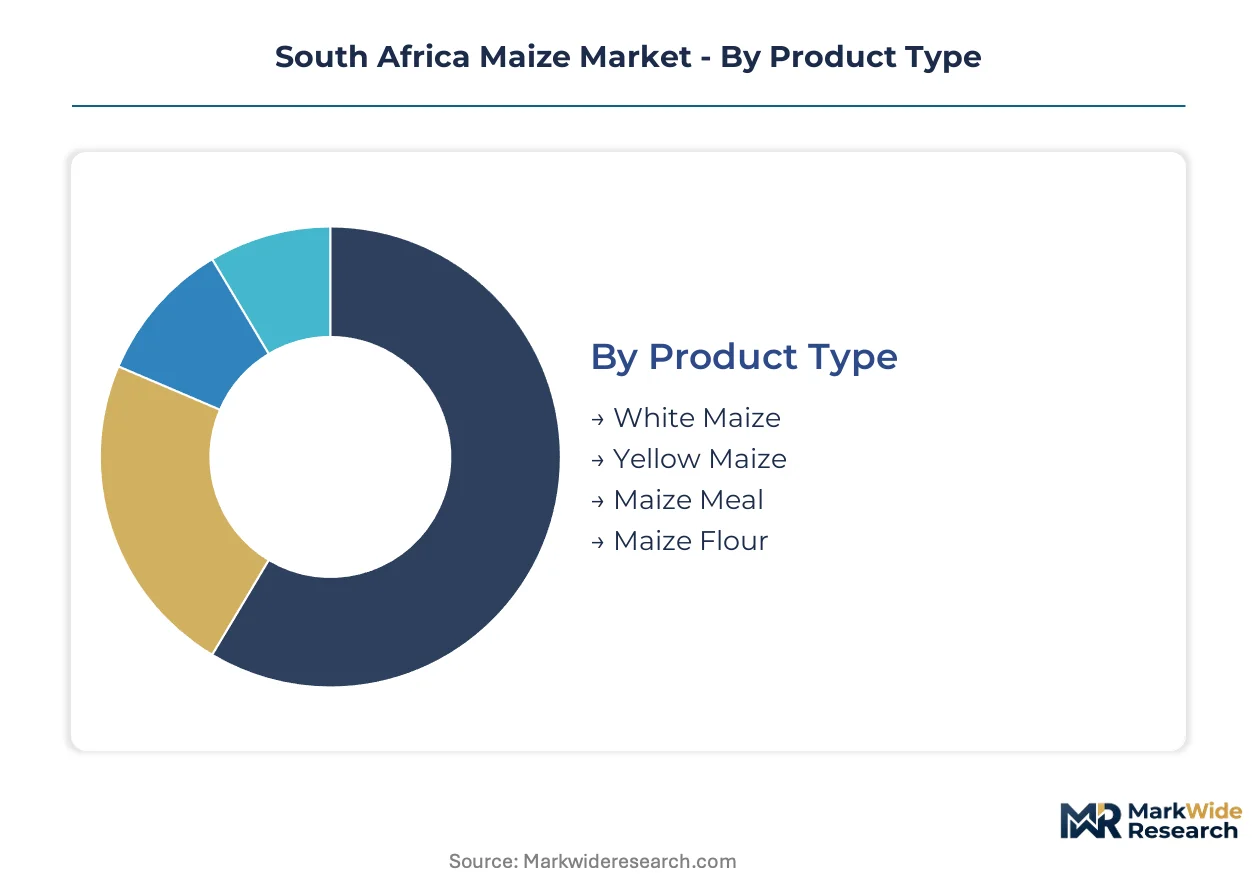
Maize segmentation in South Africa reflects divergent quality standards, regulatory pathways, and logistics requirements across food safety and feed energy specifications. Procurement contracts, storage infrastructure, and cultivar registration rules create distinct commercial dynamics for each segment category.
Product Type:
White maize turns over fastest through human consumption channels, while yellow maize cycles more slowly through bulk feed contracts with longer forward commitments.
- White Maize:Hard endosperm varieties with low-fat content dominate milling specifications for human consumption. Per capita intake in Gauteng townships and KwaZulu-Natal rural districts sustains volume concentration, though mycotoxin thresholds under the Agricultural Product Standards Act tighten procurement screening.
- Yellow Maize:Higher metabolizable energy content suits poultry and livestock feed formulations. Integrated broiler operations in Mpumalanga's highveld lock in six-month supply agreements, compressing spot-market liquidity.
- Maize Meal:Degermed and bolted products command retail shelf placement in branded packaging. Township distribution networks in Soweto and Tembisa drive informal sector throughput.
- Maize Flour:Finer particle size specifications serve industrial baking and snack manufacturing. Food manufacturers in Johannesburg's milling clusters specify moisture content below 14% for extended production runs.
White maize anchors the volume base while yellow maize gains share at the steepest rate through poultry sector procurement consolidation.
Application:
Cost tiers separate commodity feed formulations from food-grade certification investments and prospective biofuel capex.
- Animal Feed:Compound feed processors blend yellow maize with oilcake meals to hit protein-energy targets. Poultry integrators in the highveld are displacing spot purchases with direct farmer contracting.
- Human Consumption:White maize meal preparation follows nixtamalization or dry-milling pathways depending on regional taste preferences. Retail packagers face optical sorting equipment upgrades to meet tightened mycotoxin enforcement.
- Biofuel:Ethanol distillation applications await policy clarity on blending mandates under the Biofuels Industrial Strategy. Industrial offtake remains speculative pending regulatory resolution.
- Industrial Use:Starch extraction and fermentation feedstocks serve paper, textile, and pharmaceutical manufacturers. Processing economics hinge on electricity reliability for wet-milling operations.
Animal feed absorbs the largest procurement volumes while biofuel applications present the most uncertain demand trajectory pending mandate implementation.
Distribution Channel:
Volume concentration favors wholesale and export channels, whereas retail and direct supply segments carry higher per-unit margin structures.
- Wholesale:Silo aggregation and bulk shipment to milling clusters defines this channel. BF GLOBAL TRADING's logistics network controls movement from Mpumalanga highveld elevators to Johannesburg processors.
- Retail:Packaged maize meal moves through supermarket chains and township spaza shops. Chezlynne Trading anchors informal distribution networks with localized delivery frequency.
- Direct Supply:Poultry integrators and large millers contract directly with commercial farms, bypassing silo intermediaries. Forward agreements secure volume certainty at the expense of price flexibility.
- Export:SADC deficit markets in Zimbabwe and Mozambique absorb surplus through bonded warehouse channels. GLOBAL B2B IMPORT AND EXPORT TRADE leverages cross-border sourcing permits.
Wholesale channels handle the greatest tonnage while direct supply contracts expand most quickly through feed sector consolidation.
End User:
Maturity differentiates established food manufacturing demand from emerging exporter requirements and fragmented agricultural sector procurement.
- Agricultural Sector:On-farm consumption and seed retention cycles characterize this segment. Commercial farms in the Free State and North West provinces balance retained stocks against cash sales.
- Food Manufacturers:Millers and baking operations specify grade and moisture parameters in supply agreements. Gauteng milling clusters around Pretoria enforce strict delivery windows to maintain production schedules.
- Retail Chains:Supermarket groups and independent grocers stock branded meal packages with barcode traceability. Packaged goods face the steepest compliance burden under the Agricultural Product Standards Act.
- Exporters:SADC market access requires phytosanitary certification and GMO trait documentation. Traders navigate cultivar registration rules and the Genetically Modified Organisms Act approval pathways.
Food manufacturers represent the most stable demand anchor while exporters face the most volatile regulatory and logistics constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Department of Agriculture, Land Reform and Rural Development anchors South Africa's maize regulatory framework through cultivar registration and GMO approval protocols. Provincial production zones exhibit divergent irrigation access and logistics connectivity. Sub-regional clusters concentrate milling capacity and poultry integration around established infrastructure corridors.
Gauteng Province
Poultry integrators in Johannesburg and Pretoria lock in six-month forward supply agreements for yellow maize feedstock. The Agricultural Product Standards Act enforces mycotoxin thresholds that millers must meet through optical sorting upgrades. Milling clusters around Johannesburg's industrial zones retrofit equipment to handle tightened grade specifications for retail-packaged meal.
Mpumalanga Highveld
Commercial farms expand irrigation-fed maize production as cultivar improvements lift yield stability across rain-fed zones. Water-use licensing reforms under national water allocation policy threaten expansion timelines for new irrigation infrastructure. Poultry operations in the grain belt consolidate procurement through direct farmer contracting rather than silo spot markets.
Free State
On-farm consumption and seed retention cycles characterize agricultural sector demand in this province. The Genetically Modified Organisms Act approval pathways delay commercialization of drought-tolerant cultivars bred for marginal rainfall zones. Commercial farms balance retained stocks against cash sales to Johannesburg milling clusters.
KwaZulu-Natal
Per capita white maize intake in rural districts sustains volume concentration for human consumption channels. BIS standards for grain grading determine market access for domestic shipments moving to Gauteng processors. Durban's port infrastructure positions the province for prospective export expansion into SADC deficit markets.
North West Province
Commercial farms manage retained stocks against cash sales amid input cost volatility affecting planting commitments. Electricity reliability constraints from Eskom load-shedding disrupt irrigation scheduling and elevate diesel generator costs. Mafikeng and Rustenburg serve as logistics nodes connecting highveld production to Johannesburg milling demand.
South Africa Maize Market Competitive Landscape
Integrated logistics operators and specialized trading houses split the market into distinct capability tiers. Market structure tilts toward procurement leverage concentration with vertically integrated poultry feed compounders and bonded warehouse operators. Three archetypes dominate: logistics-network controllers, cross-border arbitrage specialists, and informal distribution anchors. Competitive moves center on silo-to-port corridor locking and forward supply contract scaling.
Among South Africa-based trading entities, BF GLOBAL TRADING (PTY) LTD exemplifies the logistics-network controller archetype through its elevator-to-processor movement coordination. Chezlynne Trading (Pty) Ltd occupies a position within informal distribution anchoring, while GLOBAL B2B IMPORT AND EXPORT TRADE (PTY) LTD represents cross-border arbitrage specialization into SADC markets. These three entities collectively illustrate how procurement leverage concentrates with players controlling bonded warehouse access and township retail channels.
| Leading Market Players |
|---|
| Foshan Mafrika Stock And Supplies |
| Chezlynne Trading (Pty) Ltd |
| Luswepo Warehouse & Logistics |
| Galiano Gold |
| Absa Kenya |
| GLOBAL B2B IMPORT AND EXPORT TRADE (PTY) LTD |
| BF GLOBAL TRADING (PTY) LTD |
| Global South Utilities |
| Takalash |
| Others |
Value Network & Pricing Analysis
Mpumalanga highveld production concentration feeds margin pools toward Johannesburg milling clusters and bonded warehouse operators controlling SADC export corridors. Diesel generator costs from Eskom load-shedding now embed into elevator pricing, compressing farm-gate returns while logistics-network controllers capture upstream-downstream spreads.
Pricing Analysis
Gauteng-to-Durban price spreads widen during harvest pressure periods as inland silo aggregation competes with port export premiums. Contract-based long-term offtake dominates poultry integrator procurement, with price differentiation driven by cultivar certification grade and volume scale commitments. Pricing pressure stems from fertilizer input volatility squeezing commercial farm margins. Independent traders show highest price sensitivity; vertically integrated feed compounders absorb cost swings through captive supply agreements.
Supply Chain Analysis
Yellow maize feedstock from Mpumalanga, Free State, and North West provinces supplies poultry operations across the highveld belt. The chain rests on certified seed stock, diesel fuel for irrigation backup, and temperature-controlled elevator infrastructure. Single-source vulnerability concentrates in Eskom grid reliability for wet-milling and irrigation scheduling. Distribution runs through silo aggregation points to Johannesburg milling clusters, with bonded warehouse channels serving SADC deficit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene-edited drought-tolerant cultivar commercialization under confined trial permits signals regulatory inflection that will reshape competitive positioning across rain-fed production zones.
For Market Incumbents: Entrench procurement leverage through backward integration into Mpumalanga irrigation infrastructure and captive seed development pipelines. Lock six-month forward supply agreements before GMO certification timelines compress effective seed life cycles. Prioritize optical sorting equipment upgrades to defend margin position against tightened mycotoxin enforcement under the Agricultural Product Standards Act. For New Entrants and Emerging Players: Build out township retail formalization networks in Soweto and Tembisa where informal distribution fragmentation creates white-space opportunity. Target branded maize meal packaging with barcode traceability compliance as the most penetrable segment. Pursue direct farmer contracting models bypassing silo intermediaries to secure volume certainty. For Investors and Strategic Acquirers: Secondary-cycle assets sit with logistics-network controllers holding elevator-to-port corridor dominance and bonded warehouse access. Five-to-ten year viability hinges on water allocation reform resolution and biofuel blending mandate clarity. Watch for Eskom grid stability improvements as the signal indicating milling cost structure normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Irrigation Infrastructure | Captive water access in Mpumalanga insulates against licensing reform uncertainty threatening expansion timelines. |
| Gene-Edited Cultivar Development Partnership | CRISPR-based trait stacking accelerates drought-tolerant variety commercialization ahead of conventional breeding cycles. |
| Bonded Warehouse Network Expansion | SADC cross-border arbitrage channels into Zimbabwe and Mozambique unlock premium pricing during regional deficit periods. |
| Optical Sorting Equipment Retrofit | Compliance with tightened Agricultural Product Standards Act mycotoxin thresholds secures retail shelf access. |
| Direct Farmer Contracting Platform | Six-month forward supply agreements displace spot-market liquidity and concentrate procurement leverage with integrators. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with grain elevator operators, poultry procurement managers, seed company agronomists, and Agricultural Product Standards Act enforcement officers; and secondary validation through South African Grain Information Service trade statistics, Department of Agriculture cultivar registration databases, Eskom load-shedding incident reports, and SADC customs clearance records. Bottom-up farm-gate production estimates triangulated against top-down milling cluster consumption surveys.
Forecast inputs across the analysis window incorporated product type segmentation by white and yellow maize varieties, application splits across animal feed and human consumption channels, distribution channel dynamics from wholesale silo aggregation to retail township networks, and end-user concentration among poultry integrators and packaged meal manufacturers. CAGRs derived from regression analysis against historical production volatility, input cost indices, and regulatory implementation timelines. Irrigation expansion assumptions and GMO approval pathway speeds served as scenario-weighting variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by gene-edited seed commercializers or bonded warehouse consolidators would shift outcomes beyond modeled ranges. Cross-checking against South African Futures Exchange white maize contract pricing and regional rainfall anomaly indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Sorghum Market
Grains
Gluten Free Ancient Grain Market
Grains
Soybean Market
Grains
White Beans Market
Grains
Gluten Feed Market
Grains
Ancient Grain Market
Grains
Barley Market
Grains
China Rice Market
Grains
Uganda Grains Market
Grains
Millet Flour Market
Grains
Torrified Wheat Market
Grains
Non-Basmati Rice Market
Grains
Grain Augers Market
Grains
Corn Market
Grains
Global Oats Market
Grains
Rolled Oats Market