
 Turkey Poultry Market | 2026-2036
Turkey Poultry Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Poultry Market Insights
Skilled veterinary labor availability is collapsing across Turkey's Anatolian processing belt, forcing integrators to automate or consolidate. Banvit Bandirma Vitaminli Yem Sanayi A.S. leverages full-cycle feed-to-retail integration to offset labor scarcity in Bandirma. Pinar Et ve Sut Mamulleri Sanayi A.S. anchors its position through branded chilled distribution across Aegean retail corridors. Cargill Turkey competes by importing genetics and nutrition expertise from its North American parent network.
Turkey poultry encompasses the commercial raising, processing, and distribution of Meleagris gallopavo for human consumption, with birds typically harvested at 14-22 weeks depending on end-product specifications for breast yield or whole-bird market weight. The primary purpose spans retail fresh meat, further-processed deli items, and food-service portion-controlled cuts. Whole Turkey and Turkey Breasts dominate volume, though Turkey Sausages command disproportionate margin pools as processors push value-added formats. Fresh and Frozen forms split the retail channel, while Processed and Cooked variants concentrate in Food Service and Catering Services where labor cost pressures favor ready-to-prepare inputs.
Turkish Ministry of Agriculture and Forestry veterinary protocols, BIS-aligned feed safety standards, and EU export-oriented sanitary certifications shape product specifications and facility investment requirements across the value chain. These frameworks elevate capital barriers for small processors while rewarding integrated operators with in-house laboratory and cold-chain capabilities. Stakeholders must weigh genetics sourcing strategies against evolving domestic antibiotic-residue thresholds and third-country export eligibility criteria.
Market Dynamics
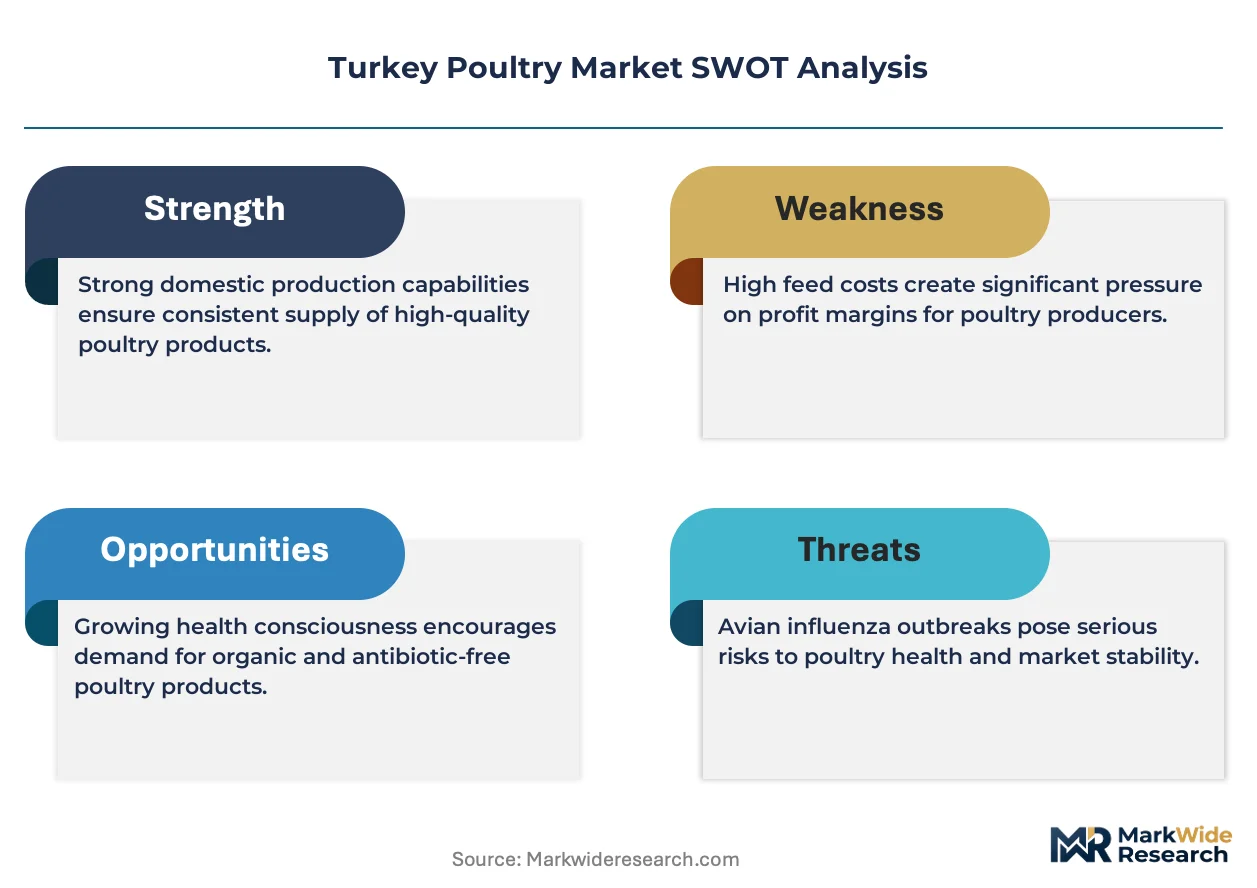
Veterinary labor scarcity across Turkey's Anatolian processing belt is compressing operational flexibility, forcing integrators toward automation and consolidation to maintain throughput.
Growth Catalysts
- Food Service Lean Protein Demand:Institutional buyers in Istanbul and Marmara region are substituting turkey breast for higher-fat proteins in portion-controlled applications, expanding chilled distribution requirements.
- EU Export Sanitary Certification Alignment:Turkish Ministry of Agriculture and Forestry protocols are upgrading cold-chain compliance standards, qualifying integrated operators for premium export channels.
- Genetics Import Liberalization:North American parent-stock genetics are improving feed conversion ratios and breast yield specifications for 16-20 week harvest cycles.
Market Restraints
- Feed Input Cost Volatility:Maize and soybean meal price swings compress margin predictability for non-integrated processors lacking captive feed milling.
- Cold-Chain Infrastructure Concentration:Refrigerated distribution capacity clusters in Istanbul and Aegean coastal corridors, leaving Anatolian interior processors with higher logistics exposure.
- Antibiotic Residue Threshold Tightening:Veterinary inspection protocols are reducing therapeutic flexibility, raising mortality risk in high-density housing systems.
Strategic Opportunities
- Underpenetrated Black Sea Retail:Urbanization in Samsun and Trabzon is outpacing chilled poultry distribution coverage, creating first-mover positioning for branded chilled networks.
- Further-Processed Deli Expansion:Sliced and marinated turkey formats are displacing unbranded whole-bird sales in Aegean supermarket channels.
- Automation Capital Subsidies:Ministry of Agriculture and Forestry equipment modernization programs are offsetting robotics investment for labor-constrained Bandirma processors.
Industry Challenges
- Veterinary Specialist Recruitment Gap:Licensed poultry veterinarians are concentrating in Istanbul and Izmir, leaving Bandirma and Konya facilities dependent on rotating contract staff.
- Legacy Chiller System Retrofit Costs:Pre-2015 processing plants require ammonia refrigeration upgrades to meet updated export certification standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Poultry Market |
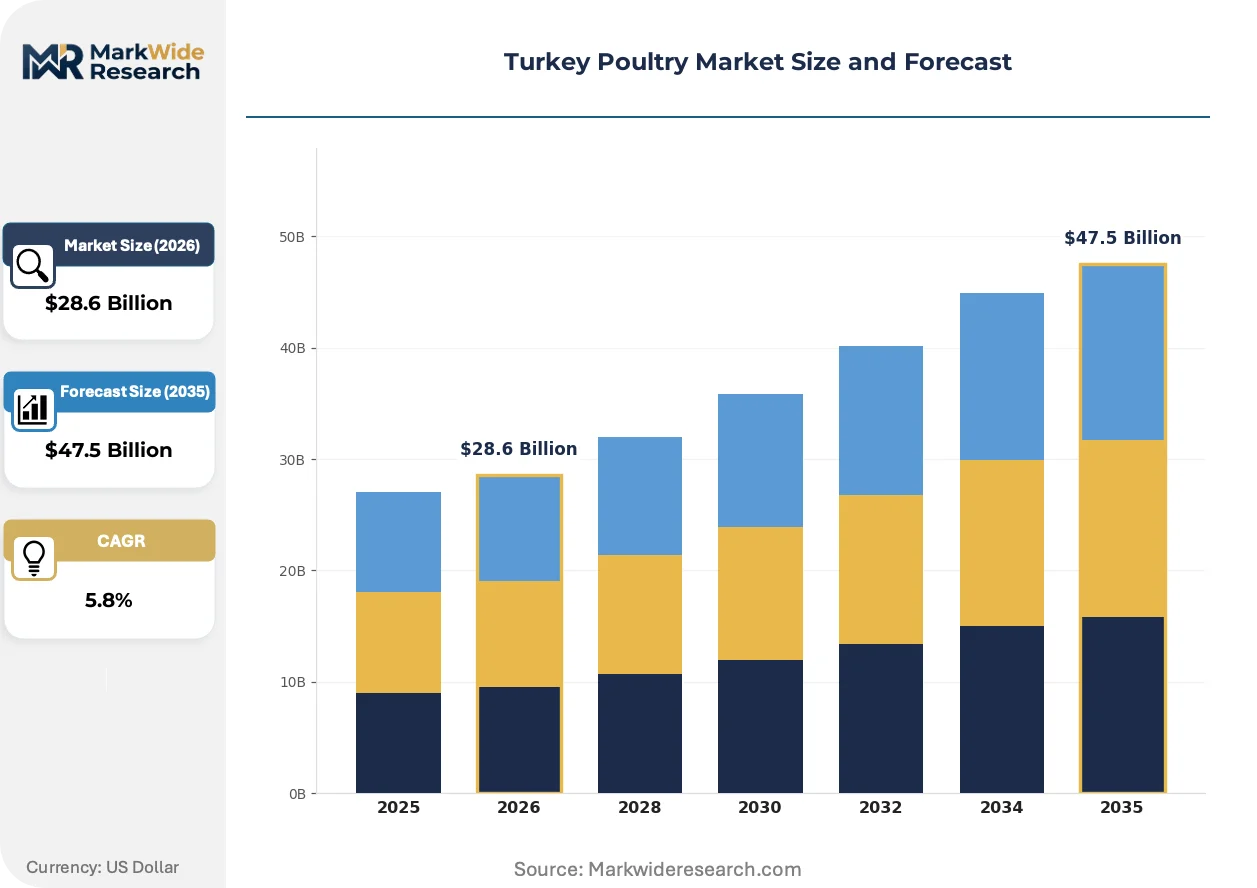
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Turkey, Turkey Breasts, Turkey Thighs, Turkey Sausages Distribution Channel: Supermarkets, Online Retail, Meat Shops, Food Service Customer Type: Residential, Food Service Providers, Restaurants, Catering Services Form: Fresh, Frozen, Processed, Cooked |
| Companies Covered | Banvit Bandirma Vitaminli Yem Sanayi A.S., Pinar Et ve Sut Mamulleri Sanayi A.S., Karkas Tavuk Sanayi A.S., Torku Gida Sanayi A.S., Aytac Food Industry and Trade Inc., Cargill Turkey, Meysu Gida Sanayi A.S., Sutas Sut ve Besi Hayvancilik A.S., Yasar Holding A.S., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Poultry Market Trends and Innovations
Automation and genetics sourcing are restructuring competitive advantage, while regulatory alignment and channel evolution are redrawing market access boundaries across Turkey's poultry value chain.
Automated vent-cutting and evisceration systems are replacing manual line labor in high-throughput Bandirma facilities. Mid-scale integrators with 50,000-100,000 bird daily capacity are deploying robotic carcass handling to offset veterinary staff shortages. The technology is bifurcating the processing landscape into capital-intensive automated facilities and labor-dependent operations facing throughput ceilings.
Turkish Ministry of Agriculture and Forestry veterinary inspection protocols are mandating real-time temperature logging and blockchain-traceable batch records for export-eligible production. Cold-chain compliance investments are diverting capital from expansion budgets at smaller processors. Aegean region operators with existing laboratory capabilities are capturing disproportionate EU export quota allocations.
Branded chilled distribution is displacing traditional wet-market whole-bird transactions in Istanbul and Izmir supermarket channels. Pinar Et and integrated retail networks are investing in MAP packaging and dedicated cold-chain logistics to secure shelf space. This channel rotation is most visible in Marmara region hypermarkets, where private-label chilled turkey breast commands price premiums over frozen alternatives.
Turkey Poultry Market Segmentation
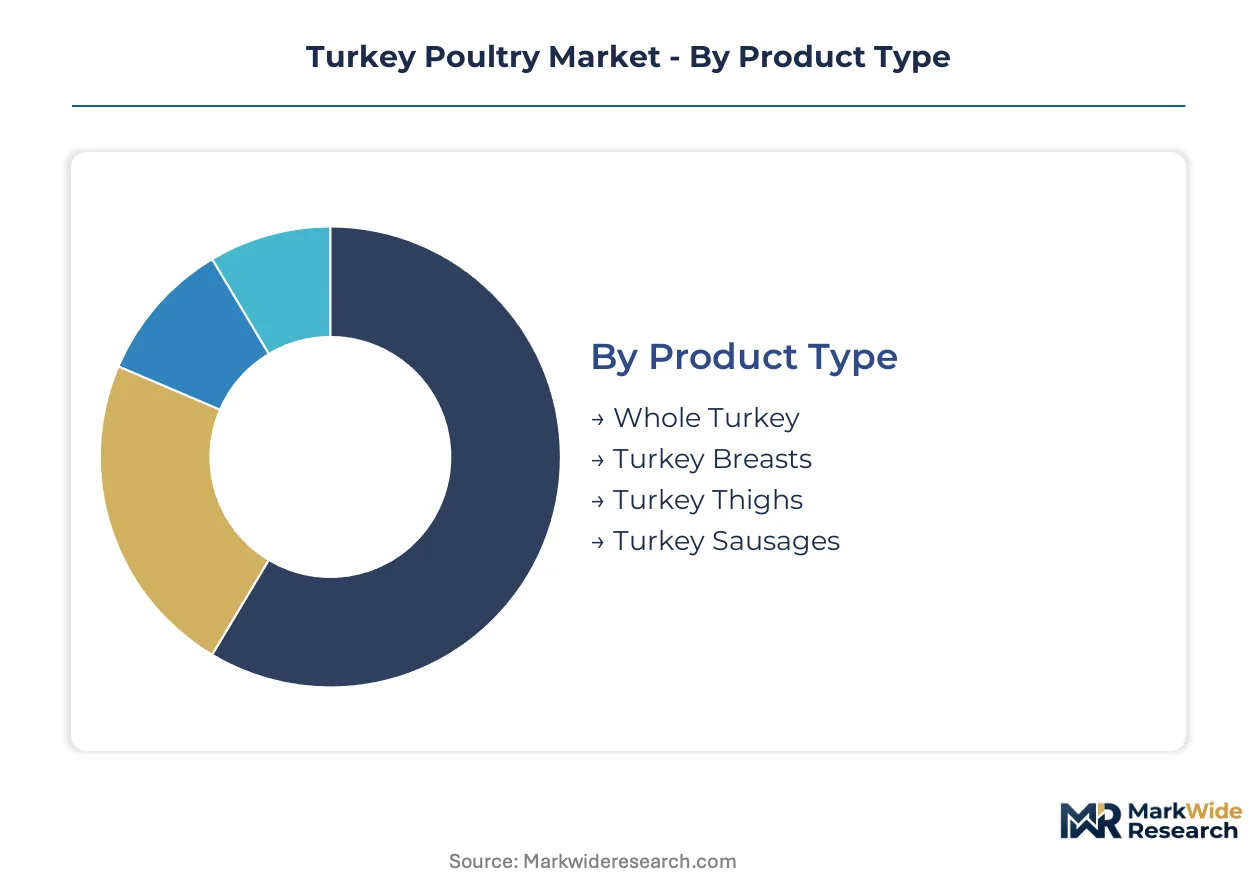
Turkey poultry segmentation reflects divergent channel economics and processing intensity levels across Turkey's value chain. Product form and distribution pathway determine margin capture, cold-chain investment requirements, and regulatory compliance burdens for operators.
Product Type:
Channel flow separates commodity whole-bird sales through wet markets from value-added cuts commanding supermarket premium placement.
- Whole Turkey:Unprocessed carcasses typically 5-9 kg live-weight equivalent dominate traditional meat shop channels in Anatolian interior provinces. Istanbul wet-market vendors and seasonal holiday demand in Black Sea coastal cities sustain volume throughput for Bandirma processors lacking downstream cutting capacity.
- Turkey Breasts:Boneless skinless portions with 16-20 week harvest specifications concentrate in Marmara region supermarket delis and food-service portion-control programs. Aegean retail corridors show fastest chilled breast penetration as Pinar Et branded networks displace frozen alternatives.
- Turkey Thighs:Dark-meat cuts with higher collagen content serve stew and ground-meat applications in residential kitchens and mid-tier restaurant chains.
- Turkey Sausages:Emulsified and fermented formats carry spice and casing cost premiums through supermarket refrigerated sections and hotel breakfast catering contracts.
By volume, Whole Turkey leads. By growth pace, Turkey Breasts is climbing the fastest.
Distribution Channel:
Customer access cost tiers stratify from capital-intensive supermarket chains to fragmented meat shop networks with minimal cold-chain compliance.
- Supermarkets:Organized retail with dedicated poultry refrigeration and MAP packaging requirements captures branded chilled premiums in Istanbul, Izmir, and Bursa. Turkish Ministry of Agriculture and Forestry veterinary protocols favor these channels with streamlined batch-traceability compliance.
- Online Retail:Delivery-platform partnerships with dark-store fulfillment are expanding in Marmara region urban cores where refrigerated last-mile logistics justify subscription-model penetration.
- Meat Shops:Independent wet-market vendors with ambient display cases dominate whole-bird transactions in Konya and interior Anatolian provinces with lower per-capita supermarket density.
- Food Service:Institutional procurement contracts for portion-controlled cuts concentrate in Istanbul hotel chains and corporate cafeteria networks seeking labor-cost reduction through ready-to-cook inputs.
Supermarkets command the highest margin per kilogram. Meat Shops still handle the largest absolute tonnage.
Customer Type:
Volume scale and price sensitivity diverge sharply between fragmented residential purchasers and consolidated food-service procurement.
- Residential:Household consumers purchasing for home preparation split between whole-bird value buying in traditional channels and premium breast cuts in organized retail. Aegean and Marmara urbanization trends are shifting this segment toward chilled packaged formats.
- Food Service Providers:Institutional buyers with centralized procurement and HACCP compliance requirements favor frozen and cooked formats to minimize kitchen labor and waste.
- Restaurants:Full-service and quick-service operators in Istanbul and Izmir are substituting turkey breast for higher-cost proteins in sandwich and salad applications.
- Catering Services:Event and airline catering contractors with batch-cooking requirements source cooked and processed variants to reduce on-site preparation time and equipment needs.
Residential buyers generate the widest product-mix dispersion. Food Service Providers concentrate the most predictable contract volumes.
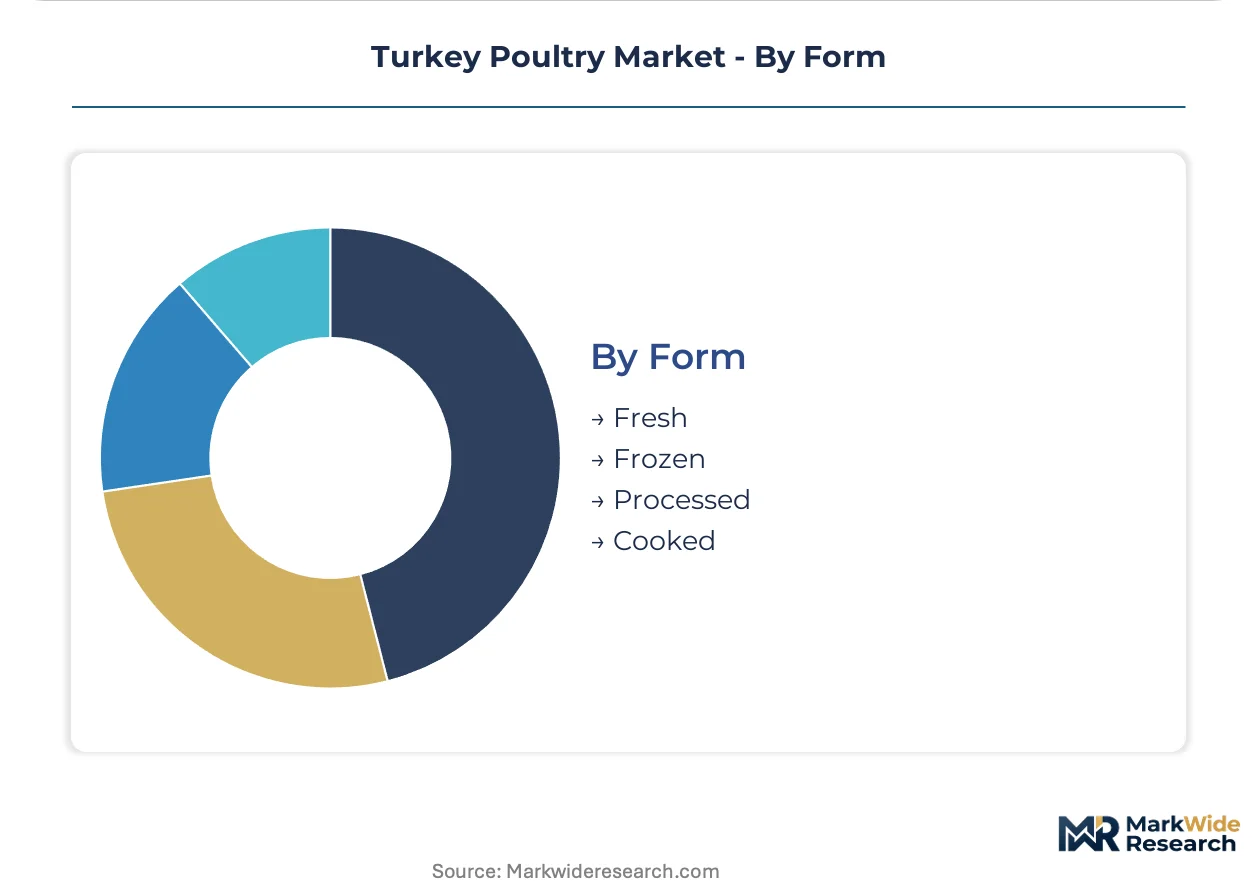
Form:
Processing intensity and shelf-life extension create four tiers of capital requirement and margin structure.
- Fresh:Chilled carcasses and primal cuts with 7-14 day shelf life command price premiums in supermarket channels but require continuous cold-chain integrity from Bandirma processing plants through retail display. Turkish Ministry of Agriculture and Forestry real-time temperature logging mandates elevate compliance costs for this segment.
- Frozen:Blast-frozen at -18°C for 12-24 month stability, this form dominates export shipments and interior Anatolian distribution where refrigerated logistics gaps persist. Konya and central plateau processors rely on frozen formats to reach distant markets.
- Processed:Marinated, seasoned, or mechanically separated products with added-value ingredients concentrate in supermarket private-label programs and food-service portion packs.
- Cooked:Ready-to-eat roast breast and deli slices with pasteurization or sous-vide processing serve catering and institutional channels seeking minimal final preparation.
Frozen holds the largest inventory volume. Fresh is gaining share fastest in coastal urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Turkish Ministry of Agriculture and Forestry anchors regulatory frameworks across Turkey's poultry belt, with cold-chain compliance requirements concentrating investment in coastal processing corridors. Regional performance splits between Marmara's supermarket penetration and Anatolia's wet-market dependency.
Marmara Region
Istanbul's hotel chains and corporate cafeterias drive chilled turkey breast procurement for portion-controlled applications. Turkish Ministry of Agriculture and Forestry veterinary protocols mandate real-time temperature logging for export-eligible production. Bandirma processing clusters deploy automated vent-cutting systems to offset veterinary labor scarcity.
Aegean Region
Izmir supermarket delis displace frozen alternatives with MAP-packaged chilled formats. BIS-aligned feed safety standards elevate capital barriers for small processors lacking in-house laboratory capabilities. Pinar Et branded networks anchor distribution across coastal retail corridors.
Central Anatolia
Konya facilities rely on frozen formats to reach distant markets where refrigerated logistics gaps persist. Antibiotic residue threshold tightening reduces therapeutic flexibility in high-density housing systems. Interior meat shops with ambient display cases dominate whole-bird transactions.
Black Sea Region
Samsun and Trabzon urbanization outpaces chilled poultry distribution coverage. EU export-oriented sanitary certifications reward operators with blockchain-traceable batch records. First-mover positioning opportunities emerge for branded chilled networks.
Mediterranean Region
Antalya tourism corridors sustain hotel breakfast catering contracts for turkey sausage formats. Feed input cost volatility compresses margin predictability for non-integrated processors. Coastal integrators leverage captive feed milling to offset maize and soybean meal price swings.
Turkey Poultry Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Turkey's poultry value chain. The market structures around three tiers: integrated feed-to-retail operators with captive genetics programs, regional processors dependent on third-party parent stock, and commodity whole-bird traders serving wet-market channels. Dominant competitive moves include backward integration into feed milling and automation capital deployment to offset labor scarcity.
Among integrated specialists, Banvit Bandirma Vitaminli Yem Sanayi A.S. exemplifies full-cycle feed-to-retail positioning, while Pinar Et ve Sut Mamulleri Sanayi A.S. occupies a branded chilled distribution anchor across Aegean retail corridors. Cargill Turkey represents the multinational archetype, leveraging parent-network genetics and nutrition expertise against domestic labor constraints.
| Leading Market Players |
|---|
| Banvit Bandirma Vitaminli Yem Sanayi A.S. |
| Pinar Et ve Sut Mamulleri Sanayi A.S. |
| Karkas Tavuk Sanayi A.S. |
| Torku Gida Sanayi A.S. |
| Aytac Food Industry and Trade Inc. |
| Cargill Turkey |
| Meysu Gida Sanayi A.S. |
| Sutas Sut ve Besi Hayvancilik A.S. |
| Yasar Holding A.S. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Bandirma integrators and Marmara hotel chains lock in chilled breast supply and insulate processors from spot maize volatility. Turkish Ministry of Agriculture and Forestry cold-chain compliance investments feed into contract premiums, concentrating price-setting power among operators with captive feed milling and in-house laboratory capabilities.
Pricing Analysis
Istanbul chilled breast premiums exceed Anatolian frozen whole-bird benchmarks by substantial spreads, reflecting cold-chain infrastructure gaps and veterinary labor scarcity costs. Three-tier pricing structure across premium MAP-packaged supermarket lines, standard frozen bulk formats, and economy wet-market whole birds stratifies margin capture. Pricing pressure stems from soybean meal import dependency and currency fluctuation exposure. Food service procurement teams show lowest price sensitivity due to labor-cost reduction value, while residential wet-market buyers concentrate price elasticity.
Supply Chain Analysis
Inventory cycles compress toward 7-14 days for fresh chilled formats, stretching to 12-24 months for frozen export shipments. Supply concentrates in Turkey's Bandirma processing belt and Aegean coastal corridors, with genetics inputs drawing from North American parent-stock networks and feed components resting on Black Sea maize and imported soybean meal. Single-source vulnerability runs through veterinary specialist concentration in Istanbul and Izmir. Distribution runs through supermarket cold-chain networks in coastal urban cores and fragmented meat shop channels in interior provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey poultry sits in early-cycle expansion as branded chilled penetration accelerates across Marmara and Aegean supermarket channels, displacing traditional wet-market transactions.
For Market Incumbents: Shield margin pools by accelerating automation deployment in Bandirma facilities to offset veterinary labor scarcity, and secure backward integration into captive feed milling to neutralize maize and soybean meal volatility. Banvit-style full-cycle integration and Pinar Et branded distribution networks represent defensible archetypes against multinational genetics importers. For New Entrants and Emerging Players: Anchor in underpenetrated Black Sea retail corridors where Samsun and Trabzon urbanization outpaces chilled distribution coverage, and target further-processed deli formats displacing unbranded whole-bird sales. Ministry of Agriculture and Forestry equipment modernization subsidies provide capital-efficient entry mechanics for automation-ready processors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated operators with laboratory and cold-chain capabilities over fragmented commodity traders. Five-to-ten year viability hinges on EU export certification alignment and genetics sourcing relationships. Watch veterinary protocol enforcement intensity as inflection signal for regulatory barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Processing Line Deployment | Robotic vent-cutting systems offset Bandirma veterinary labor scarcity and sustain throughput. |
| Cold-Chain Infrastructure Expansion | Real-time temperature logging compliance opens EU export quota allocations for Aegean operators. |
| Captive Feed Milling Investment | In-house maize and soybean meal processing insulates margins from commodity price swings. |
| Branded Chilled Network Buildout | MAP-packaged distribution secures supermarket shelf space against frozen alternatives in Izmir. |
| EU Sanitary Certification Alignment | Blockchain-traceable batch records qualify integrated operators for premium export channels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Turkish Ministry of Agriculture and Forestry veterinary protocol filings, BIS-aligned feed safety standards, and EU export certification databases. Primary inputs drew from integrator operations directors, supermarket category buyers, food service procurement managers, and cold-chain logistics operators. Secondary validation incorporated customs trade data, poultry processing capacity registries, and genetics import licensing records. Bottom-up facility capacity modeling triangulated against top-down consumption estimates across the analysis window.
Segmentation dimensions modeled include product form, distribution channel, customer type, and processing intensity level. Volume and value outputs reflect reconciliation between processor throughput estimates and channel flow analysis throughout the forecast period. CAGRs derived from trend extrapolation of chilled format penetration, automation adoption curves, and regulatory compliance investment cycles. Genetics import liberalization and veterinary labor supply constraints served as industry-specific demand-side and supply-side forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued Turkish Ministry of Agriculture and Forestry protocol enforcement, stable genetics import pathways, and sustained Marmara food service demand; material deviation in feed input costs or EU export eligibility criteria would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poultry Farming Equipment
Poultry Brooder Market
Poultry Farming Equipment
Poultry House Ventilation System Market
Poultry Farming Equipment
Egg Grading Machines Market
Poultry Farming Equipment
Duck Plucker Machine Market
Poultry Farming Equipment
Rabbit Cages Market
Poultry Farming Equipment
Automated Poultry Farm Market
Poultry Farming Equipment
Poultry Keeping Machinery Market
Poultry Farming Equipment
Commercial Chicken Plucker Market
Poultry Farming Equipment
Poultry Plucker Market
Poultry Farming Equipment
Multi-Layer Poultry Cage Market
Poultry Farming Equipment
Poultry Brooders, Feeders, and Waterers Market
Poultry Farming Equipment
Egg Breaking Machine Market
Poultry Farming Equipment
Poultry Farming Equipment Market
Poultry Farming Equipment
Asia Pacific Poultry Market
Poultry Farming Equipment
Poultry Incubator Market