
 Global Grain Mill Products Market | 2026-2036
Global Grain Mill Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Grain Mill Products Market Foresight
Plant-based protein formulations in snack production is realigning procurement priorities across milling operations. Archer Daniels Midland Company leverages its North American origination network to secure hard red winter wheat for high-protein flour streams. Cargill, Incorporated sustains ocean freight and port elevation assets that anchor its export competitiveness into Asian markets. King Arthur Baking Company differentiates through specialty and organic SKUs that command premium positioning in retail channels.
Grain mill products encompass mechanically processed cereal grains reduced to flour, semolina, bran, cornmeal, or grits through roller or hammer milling, with particle size distribution and ash content serving as critical quality parameters for downstream functionality. These intermediates supply baking, brewing, pasta manufacturing, and animal feed compounding as their primary commercial endpoints. Flour maintains the dominant revenue position across product types given its ubiquity in bread and confectionery applications, while bran extracts gain traction from nutrition supplement producers seeking fiber enrichment. Within applications, pasta manufacturing offers concentrated margin pools due to durum wheat premiums and brand-driven pricing power.
The FDA enforces Food Safety Modernization Act rules that mandate preventive controls for human food across U.S. milling facilities, elevating capital requirements for sanitation and hazard analysis. EFSA and national regulators under the EU Green Deal impose pesticide residue thresholds and sustainable sourcing disclosures that reshape supplier qualification for European offtake. China's SAMR enforces GB standards for cereal product labeling and additive limits that condition market access. Stakeholders must monitor divergence between regional sustainability mandates and the capital intensity of compliance infrastructure as they allocate milling capacity across geographies.
Market Dynamics
The EU Green Deal's sustainable sourcing mandates are compressing supplier qualification timelines across European milling operations, forcing capital reallocation toward traceability infrastructure and regenerative agriculture verification systems.
Growth Catalysts
- Urban processed food consumption:India's accelerating city migration expands demand for packaged bakery and convenience foods requiring standardized flour inputs.
- REACH chemical disclosure rules:European pesticide residue thresholds drive premium positioning for certified organic grain streams in retail channels.
- Pulse milling integration:Pea and lentil protein extraction technologies diversify mill product portfolios beyond cereal bases.
Market Restraints
- Input cost volatility:Natural gas and electricity price swings destabilize thermal drying and tempering operations across Midwest US facilities.
- Supply concentration risk:Black Sea region wheat export disruptions expose Asian buyers to origination bottlenecks and freight rate spikes.
- Regulatory friction:China's SAMR additive limits and labeling GB standards create compliance barriers for imported specialty flour blends.
Strategic Opportunities
- Underpenetrated geography:Vietnam's nascent industrial baking sector offers first-mover positioning for durum semolina supply contracts.
- Regulatory tailwind:India's PLI scheme for food processing incentivizes capital investment in automated milling lines and cold-chain adjacent storage.
- Technology convergence:Near-infrared spectroscopy and blockchain traceability combine to enable real-time quality verification for export shipments.
Industry Challenges
- Skill gap in automation maintenance:Roller mill calibration and PLC system troubleshooting require technicians scarce in rural milling clusters.
- Capex intensity for sanitation:FDA Food Safety Modernization Act preventive controls demand stainless steel equipment upgrades and environmental monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Grain Mill Products Market |
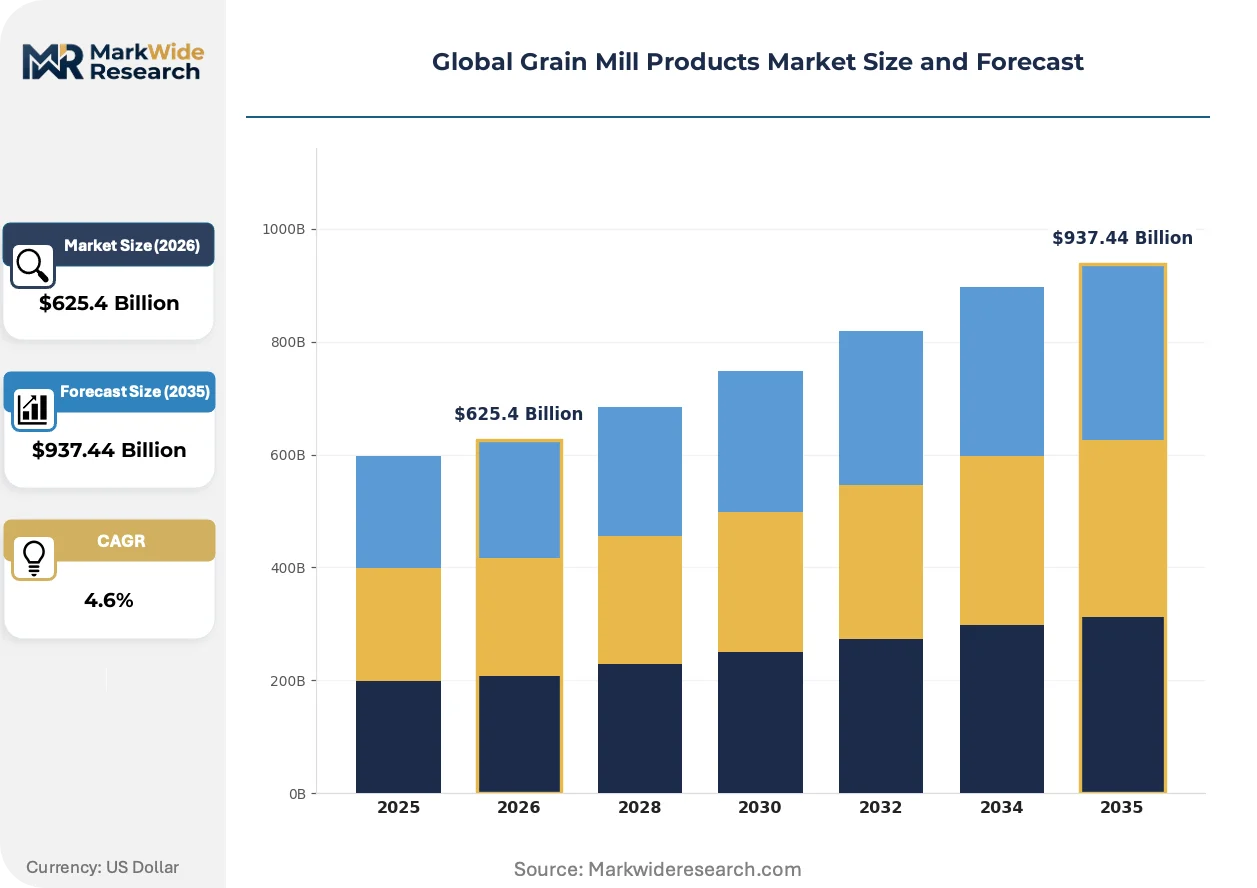
| Market Size in 2026 | $625.4 Billion |
| Market Size in 2035 | $937.44 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flour, Semolina, Bran, Cornmeal, Grits Application: Baking, Brewing, Animal Feed, Snack Production, Pasta Manufacturing End User Industry: Food Processing Units, Beverage Manufacturers, Livestock Farms, Confectionery Companies, Nutrition Supplement Producers Packaging Type: Sacks, Bulk Bags, Paper Bags, Polypropylene Bags, Vacuum Packs |
| Companies Covered | Archer Daniels Midland Company, Ardent Mills, Cargill, Incorporated, General Mills Inc., Conagra Brands, Inc., Grain Millers, Inc., Oy Karl Fazer Ab, King Arthur Baking Company, Goodman Fielder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Grain Mill Products Market Shifts & Advancements
Digital quality assurance systems and sustainability verification protocols are compressing traditional procurement cycles while fragmenting buyer-seller relationships across specialty grain segments.
Optical sorting technology paired with machine learning algorithms is automating defect detection and protein content classification in wheat intake streams. Large-scale pasta manufacturers in Italy and Turkey deploy these systems at elevator receipt points to enforce durum purity standards. The technology is automating manual laboratory testing workflows and accelerating load acceptance decisions.
The EU Green Deal's Farm to Fork strategy tightens pesticide residue thresholds and mandates supply chain sustainability disclosures for grain entering European food channels. Milling operations must now maintain regenerative agriculture certifications and carbon footprint documentation across supplier networks. Organic and specialty flour SKUs face the steepest compliance cost escalations as verification infrastructure scales.
Direct contracting between artisan bakeries and regional mills is displacing commodity spot purchasing for high-protein and heritage wheat varieties. Specialty bakery chains in France and California now specify kernel hardness and falling number parameters in annual supply agreements. This procurement consolidation concentrates volume with mid-scale mills capable of segregated storage and custom blending.
Global Grain Mill Products Market Segmentation
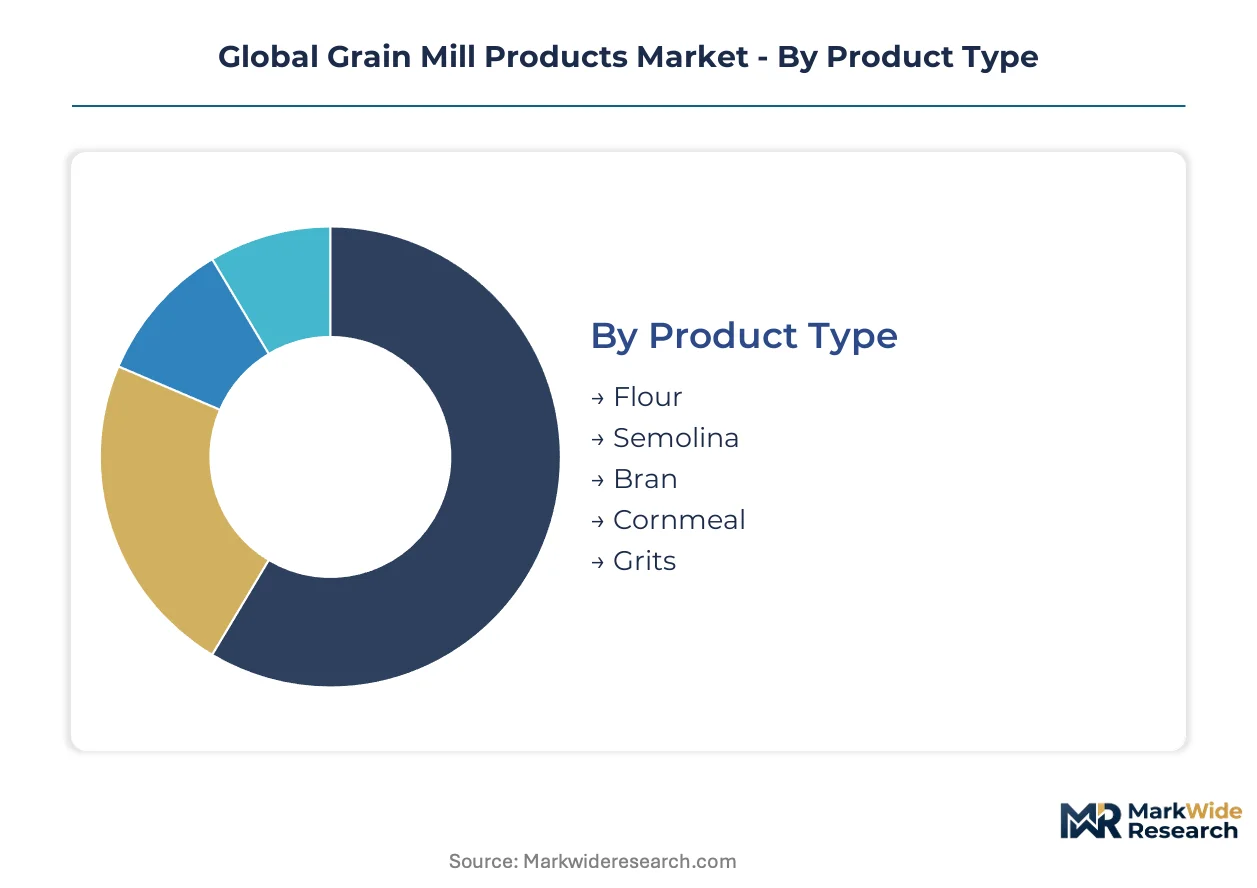
Grain mill product segmentation reveals how milling capacity allocates across downstream value chains. Product type and application dimensions determine equipment configuration, raw material sourcing, and margin capture potential for operators.
Product Type:
Supply concentration in wheat-based streams dominates milling infrastructure investment, with durum and hard red winter varieties commanding segregated processing lines.
- Flour:Roller-milled wheat flour with particle size distribution between 100-300 microns and ash content below 0.55% serves as the foundational intermediate for bread and confectionery. Industrial bakeries in India and China absorb standardized flour volumes as urban processed food consumption accelerates.
- Semolina:Coarse durum wheat endosperm with protein content exceeding 13% delivers the gluten strength required for pasta extrusion. Italian and Turkish pasta manufacturers enforce strict purity standards through optical sorting at elevator receipt points.
- Bran:Outer kernel layers separated during milling contain dietary fiber and micronutrients targeted by nutrition supplement producers seeking enrichment additives.
- Cornmeal:Degermed or whole-grain maize fractions ground to medium or fine consistency supply tortilla and cornbread manufacturing in North American and Latin American markets.
- Grits:Coarsely ground corn with particle sizes above 300 microns serves breakfast food and brewing applications requiring specific gelatinization properties.
Flour absorbs the bulk of installed capacity; bran is expanding most quickly as fiber enrichment demand climbs.
Application:
Cost tier differentiation separates commodity-scale animal feed from premium pasta manufacturing, with margin pools concentrating in brand-driven downstream segments.
- Baking:Bread, pastry, and biscuit production consumes the largest flour volumes, with artisan bakery chains in France and California now specifying kernel hardness and falling number parameters in direct annual supply agreements.
- Pasta Manufacturing:Durum semolina extrusion commands concentrated margin pools due to wheat premiums and pricing power held by branded finished goods producers in Italy.
- Brewing:Malted barley and adjunct grains require specific enzymatic profiles for starch conversion, with craft brewery proliferation diversifying specialty grain procurement.
- Animal Feed:Compound feed operations consume lower-grade milling byproducts and whole grains at volume scale with minimal quality differentiation.
- Snack Production:Extruded and baked snack formulations increasingly incorporate pulse flours alongside cereal bases as plant-based protein trends reshape ingredient sourcing.
Baking commands the greatest volume throughput; pasta manufacturing delivers the steepest margin expansion trajectory.
End User Industry:
Customer type fragmentation spans multinational food processors, regional livestock operations, and specialized nutrition formulators with divergent procurement protocols.
- Food Processing Units:Industrial bakeries and prepared meal manufacturers require consistent flour functionality across high-volume production runs.
- Confectionery Companies:Cake and pastry producers demand low-protein soft wheat flours with specific starch damage levels for tender crumb structure.
- Nutrition Supplement Producers:Fiber and protein extraction operations source bran and specialty milled fractions for functional ingredient isolation.
- Beverage Manufacturers:Brewing and malt-based drink producers secure specific barley and adjunct grain specifications for enzymatic performance.
- Livestock Farms:Feedlot and poultry operations purchase bulk grain and milling residuals on commodity pricing formulas with minimal quality premiums.
Food processing units represent the dominant demand concentration; nutrition supplement producers are gaining share fastest.
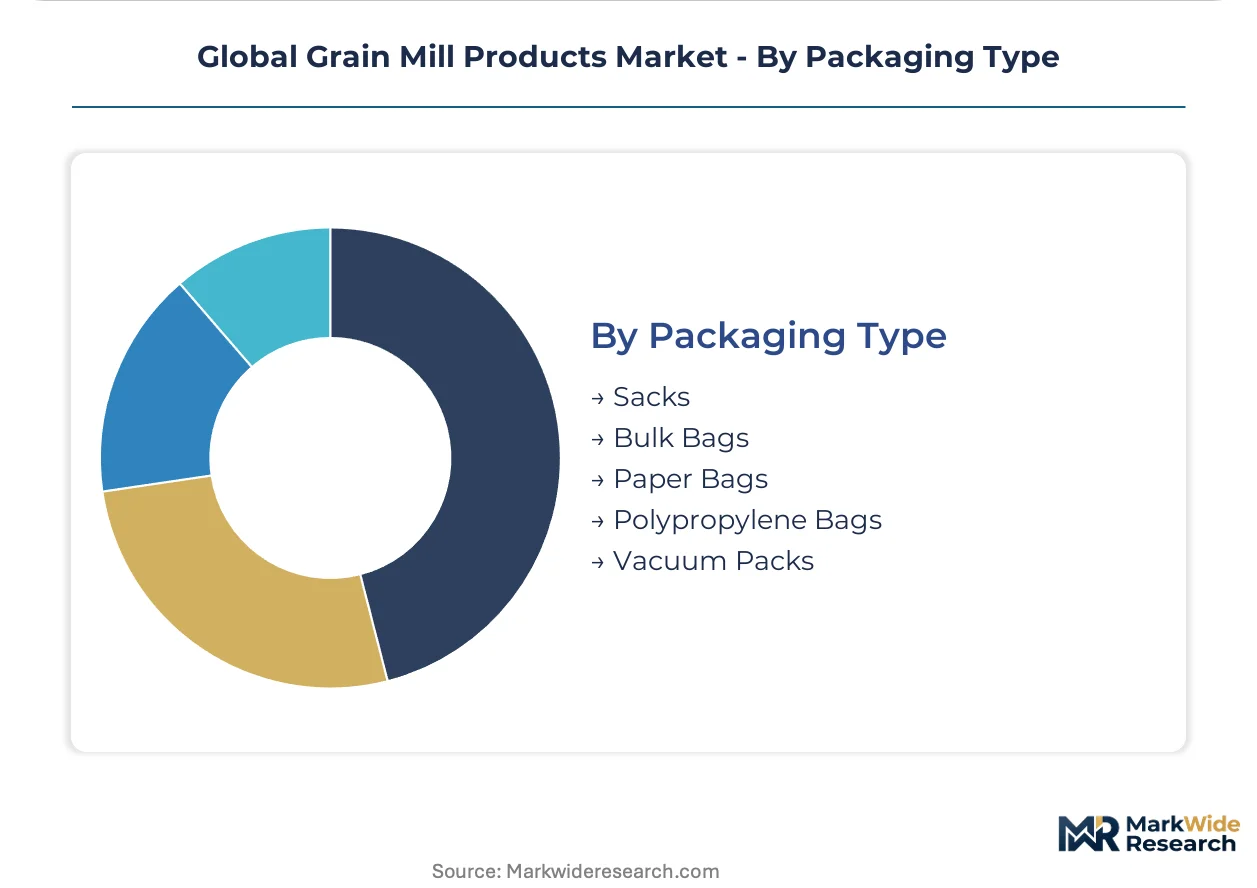
Packaging Type:
Volume scale and shelf-life requirements determine packaging selection, with export logistics favoring bulk formats and retail channels demanding branded consumer units.
- Bulk Bags:Flexible intermediate bulk containers holding 500-2000 kg dominate ocean freight shipments to Asian pasta manufacturers and industrial bakeries.
- Sacks:Multi-wall paper or woven polypropylene bags of 25-50 kg serve traditional wholesale distribution to small and mid-scale food processors.
- Vacuum Packs:Oxygen-barrier packaging extends shelf life for specialty and organic flour SKUs commanding premium retail positioning.
- Paper Bags:Consumer-facing retail units with printed branding target home bakers and specialty food channels.
- Polypropylene Bags:Durable woven plastic sacks resist moisture and pest intrusion in tropical storage conditions prevalent in Southeast Asian markets.
Bulk bags capture the majority of export volume; vacuum packs are climbing the fastest as organic and specialty SKU proliferation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Mega Food Parks scheme and dedicated food processing zones concentrate milling investment in Gujarat and Maharashtra. Special economic zones offering capital subsidies and single-window clearance accelerate automated facility deployment.
United States
Hard red winter wheat procurement from Kansas and Oklahoma supports high-protein flour streams for industrial bakeries. The FDA's Food Safety Modernization Act mandates preventive controls that elevate sanitation capital requirements across Midwest milling clusters. Minneapolis-St. Paul anchors North American grain trading infrastructure with integrated elevator and processing capacity.
China
Urbanization in the Yangtze River Delta and Pearl River Delta expands packaged bakery consumption requiring standardized flour inputs. SAMR enforces GB standards for cereal product labeling and additive limits that condition import market access. Zhengzhou hosts concentrated durum processing capacity serving domestic pasta manufacturing expansion.
Germany
EU Green Deal sustainability mandates compress supplier qualification timelines for regenerative agriculture verification. EFSA pesticide residue thresholds reshape procurement protocols toward certified organic grain streams. Hamburg's port elevation assets anchor export competitiveness into Mediterranean and Asian markets.
Italy
Durum wheat premiums and brand-driven pricing power concentrate margin pools in pasta manufacturing. REACH chemical disclosure rules drive premium positioning for certified organic semolina in retail channels. Parma and Naples industrial zones host optical sorting deployment at elevator receipt points for purity enforcement.
India
Accelerating city migration expands demand for packaged bakery and convenience foods requiring standardized flour inputs. The PLI scheme for food processing incentivizes capital investment in automated milling lines and cold-chain adjacent storage. Gujarat's Mega Food Park clusters concentrate wheat processing capacity near procurement origination points.
Global Grain Mill Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium retail channels favoring identity-preserved flour positioning while industrial bakeries prioritize volume scale and specification consistency. The vendor base organizes around three archetypes: diversified agribusiness conglomerates with origination-to-processing integration, mid-scale regional mills serving artisan bakery direct contracts, and specialty organic operators commanding certification premiums. Competitive moves concentrate on M&A for geographic origination access and capacity expansion for export shipment scale.
Among North American agribusiness conglomerates, Archer Daniels Midland Company and Cargill, Incorporated exemplify integrated origination-network positioning that secures hard red winter wheat streams for protein-specific flour production. King Arthur Baking Company occupies a branded specialist tier where specialty and organic SKUs command premium retail positioning through segregated storage and custom blending capabilities.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Ardent Mills |
| Cargill, Incorporated |
| General Mills Inc. |
| Conagra Brands, Inc. |
| Grain Millers, Inc. |
| Oy Karl Fazer Ab |
| King Arthur Baking Company |
| Goodman Fielder |
| Others |
Supply & Pricing Matrix
Roller mill calibration specialists concentrated in Minnesota and Kansas command wage premiums that compress margin spreads between premium specialty flour and commodity-grade streams. Labor-cost differentials between automated urban facilities and rural milling clusters amplify pricing-tier separation as FDA sanitation mandates elevate capital barriers.
Pricing Analysis
Short lead-time premiums for certified organic semolina command substantial markups over spot-market commodity flour. Three-tier pricing structure across premium, standard, and economy levels separates identity-preserved heritage wheat from bulk hard red winter and feed-grade residuals. Price differentiation hinges on EU Green Deal regenerative agriculture certification and volume-scale contract terms. Industrial bakeries exhibit highest price sensitivity, while artisan bakery chains absorb premiums for specified kernel hardness parameters.
Supply Chain Analysis
EU Green Deal sustainability certification gates supplier qualification timelines and elevates origination verification costs. Supply concentrates in the United States, Canada, and Australia for high-protein wheat; durum sourcing centers on Italy, Turkey, and North Dakota. Raw material dependencies include natural gas for thermal drying, ocean freight capacity for Asian export routes, and phosphate fertilizers for regenerative agriculture transitions. Single-source vulnerability runs through Black Sea export corridors disrupted by geopolitical friction. Distribution runs through Minneapolis-St. Paul trading hubs, Hamburg port elevation assets, and Zhengzhou processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU Green Deal compliance costs and FDA sanitation mandates force sub-scale operators toward exit or acquisition.
For Market Incumbents: Extend traceability infrastructure investments to capture regenerative agriculture premiums before certification bottlenecks intensify. Backward integration into origination networks in Kansas and Saskatchewan secures hard red winter wheat streams against Black Sea supply disruptions. Capacity consolidation in automated milling lines defends margin position against labor-cost inflation in rural clusters. For New Entrants and Emerging Players: Direct-to-artisan-bakery digital platforms bypass commodity spot markets and establish identity-preserved supply relationships. Vietnam's nascent industrial baking sector offers first-mover positioning for durum semolina contracts with minimal incumbent saturation. Pulse milling integration for pea and lentil protein extraction diversifies portfolio beyond saturated cereal bases. For Investors and Strategic Acquirers: The window for entry favors mid-scale regional mills with segregated storage capabilities and existing organic certification infrastructure. Long-term viability centers on automated facilities capable of custom blending for direct bakery contracts. Watch for Black Sea export corridor stabilization as inflection indicator for Asian demand recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origination Networks | Captive supply of hard red winter wheat from Kansas and Oklahoma secures protein-specific flour streams against spot-market volatility. |
| Regenerative Agriculture Certification Program | EU Green Deal compliance unlocks premium positioning in European retail channels and accelerates supplier qualification timelines. |
| Optical Sorting Technology Deployment | Machine learning-driven defect detection at Italian and Turkish elevator receipt points enforces durum purity standards for pasta manufacturers. |
| Pulse Milling Capacity Addition | Pea and lentil protein extraction diversifies product portfolios beyond cereal bases as plant-based snack formulations accelerate. |
| Direct-to-Bakery Digital Platform Launch | Bypassing commodity intermediaries captures margin from artisan chains in France and California specifying kernel hardness parameters. |
Research Methodology
Independent corroboration across milling operations executives, grain origination specialists, and food processing procurement directors underwrites the qualitative findings. Primary interviews with FDA compliance officers, EU sustainability auditors, and Asian import logistics coordinators combined with secondary validation from EFSA pesticide residue databases, USDA crop production reports, SAMR GB standard filings, and customs trade flow records. Bottom-up capacity assessments and top-down consumption models triangulate volume estimates.
Comparable-period anchoring to pre-urbanization baselines in India and China established demand trajectory parameters across the projection horizon. Segmentation dimensions modeled include product type, application tier, end-user industry, packaging format, and regional regulatory cluster. CAGRs derived from installed capacity expansion rates, per-capita processed food consumption elasticities, and trade flow acceleration patterns. Industry-specific inputs encompass durum wheat premium spreads, natural gas cost pass-through coefficients, and ocean freight rate volatility indices.
The model holds under stable Black Sea export corridor conditions and sustained EU Green Deal implementation timelines; deviation in geopolitical friction intensity or regulatory enforcement suspension would shift origination patterns and margin distributions. A model refresh is warranted upon material change in FDA preventive controls enforcement posture or SAMR additive limit revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
South Africa Grain Market
Grains
Wheat Flour Market
Grains
Grain Roller Market
Grains
Cultured Wheat Market
Grains
Mexico Rice Market
Grains
Corn Gluten Feed Market
Grains
Spelt Wheat Market
Grains
Organic Rice Flour Market
Grains
South America Rice Market
Grains
North America Maize Market
Grains
Sorghum Market
Grains
Organic Rice Market
Grains
IQF Rice Market
Grains
China Wheat Protein Market
Grains
Torrified Wheat Market
Grains
North America Rice Market