
 White Beans Market | 2026-2036
White Beans Market Size, Share, and Industry Trends Forecast 2026-2036
White Beans Market Analytics
Plant-based protein isolates is restructuring white bean product economics as food manufacturers reformulate meat alternatives around pulse-derived ingredients. Bush Brothers & Company leverages its Tennessee canning infrastructure to anchor supply reliability across southeastern retail networks. Hanover Foods Corp. competes through vertical control over Mid-Atlantic agricultural sourcing. Carmelina Brands differentiates via Italian-origin Cannellini positioning in premium specialty channels.
White beans comprise dried seeds of Phaseolus vulgaris cultivars, typically containing 20-25% protein by dry weight and processed through hydration, blanching, and thermal stabilization for shelf-stable delivery. The crop serves as a staple protein and starch source across canned goods, dried retail, and food-ingredient applications. Great Northern and Navy varieties dominate volume in North American supermarkets due to established canning compatibility and neutral flavor profiles. Cannellini commands margin premiums in specialty stores and Italian-focused restaurants where provenance signaling supports price realization. Online retailers represent the fastest-expanding distribution channel as direct-to-consumer pulse subscriptions and bulk pantry delivery gain traction among household buyers.
The USDA's Agricultural Marketing Service sets grading standards for dry bean quality, moisture content, and defect tolerances that govern domestic procurement and export eligibility. FDA food safety regulations under the Food Safety Modernization Act mandate preventive controls for processing facilities handling ready-to-eat canned legumes. Stakeholders must monitor evolving EU deforestation-free supply chain rules and their documentation requirements for agricultural imports entering European ports.
Market Dynamics
Plant-forward protein reformulation is restructuring procurement patterns across North American food manufacturing, with pulse-derived isolates displacing commodity bean sales into ingredient channels and compressing traditional canning margins.
Growth Catalysts
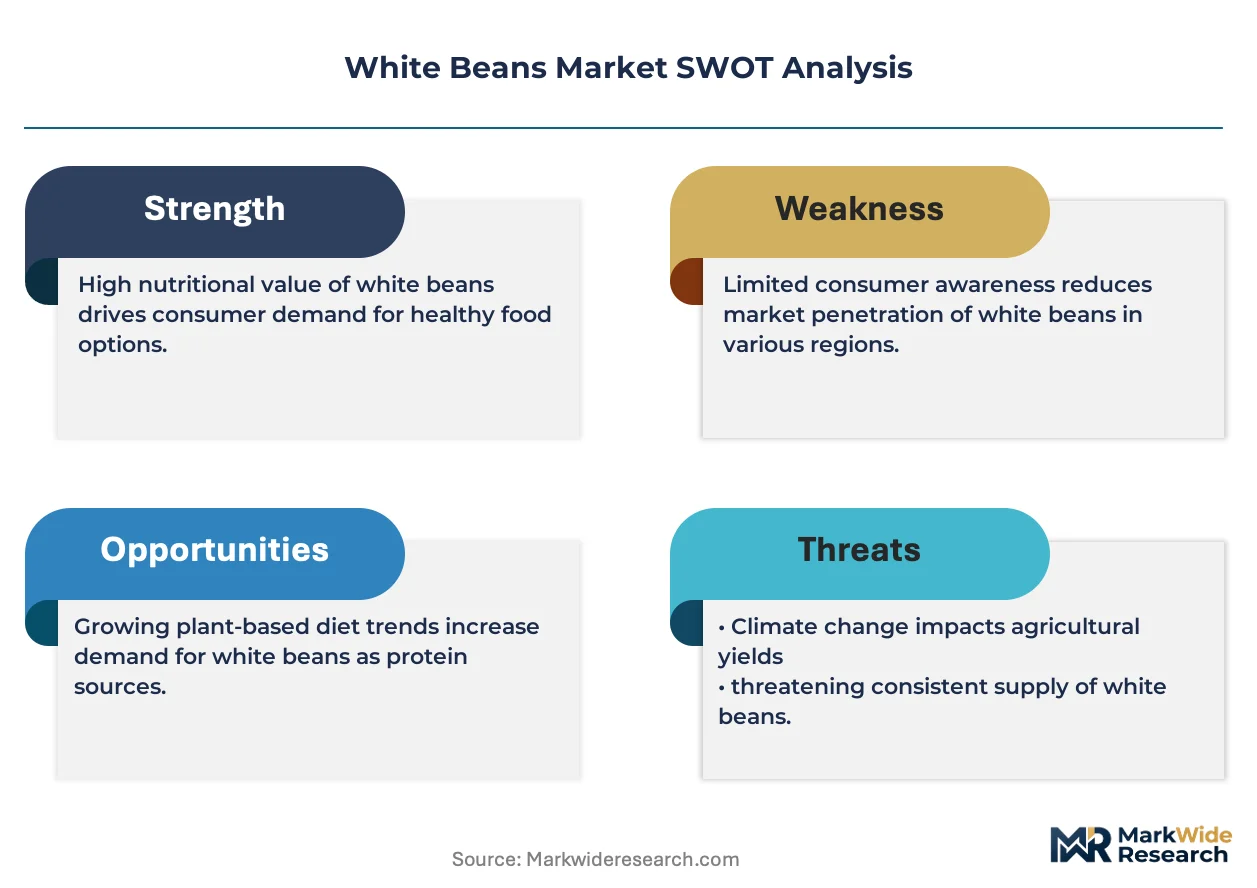
- EU Farm to Fork Strategy:Tightening pesticide residue thresholds for imported legumes is accelerating certified organic acreage expansion among contract growers.
- Food service plant-forward menus:North American restaurant chains are expanding white bean procurement volumes for protein-forward bowl concepts and meat-alternative formulations.
- Hydration and thermal stabilization:Advances in reduced-sodium canning processes are opening institutional channels previously closed to pulse products.
Market Restraints
- Input cost volatility:Nitrogen fertilizer price swings directly compress grower margins in Mexico's central plateau states.
- Supply concentration risk:Domestic canning infrastructure clusters in Tennessee and Pennsylvania create single-point vulnerability for southeastern retail networks.
- Substitution threat:Chickpea and lentil protein isolates compete for identical meat-alternative formulation slots.
Strategic Opportunities
- Direct-to-consumer pulse subscriptions:Online retailers represent underpenetrated channel expansion for bulk pantry delivery models.
- Provenance signaling:Italian-origin Cannellini positioning commands margin premiums in specialty retail and food service.
- EU deforestation-free supply chain rules:Early compliance documentation creates preferential port access for prepared exporters.
Industry Challenges
- Preventive controls implementation:FDA Food Safety Modernization Act mandates require capital-intensive facility upgrades for ready-to-eat canned legume processors.
- Grading standard harmonization:USDA Agricultural Marketing Service moisture content tolerances conflict with EU import specifications, forcing dual-certification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Beans Market |
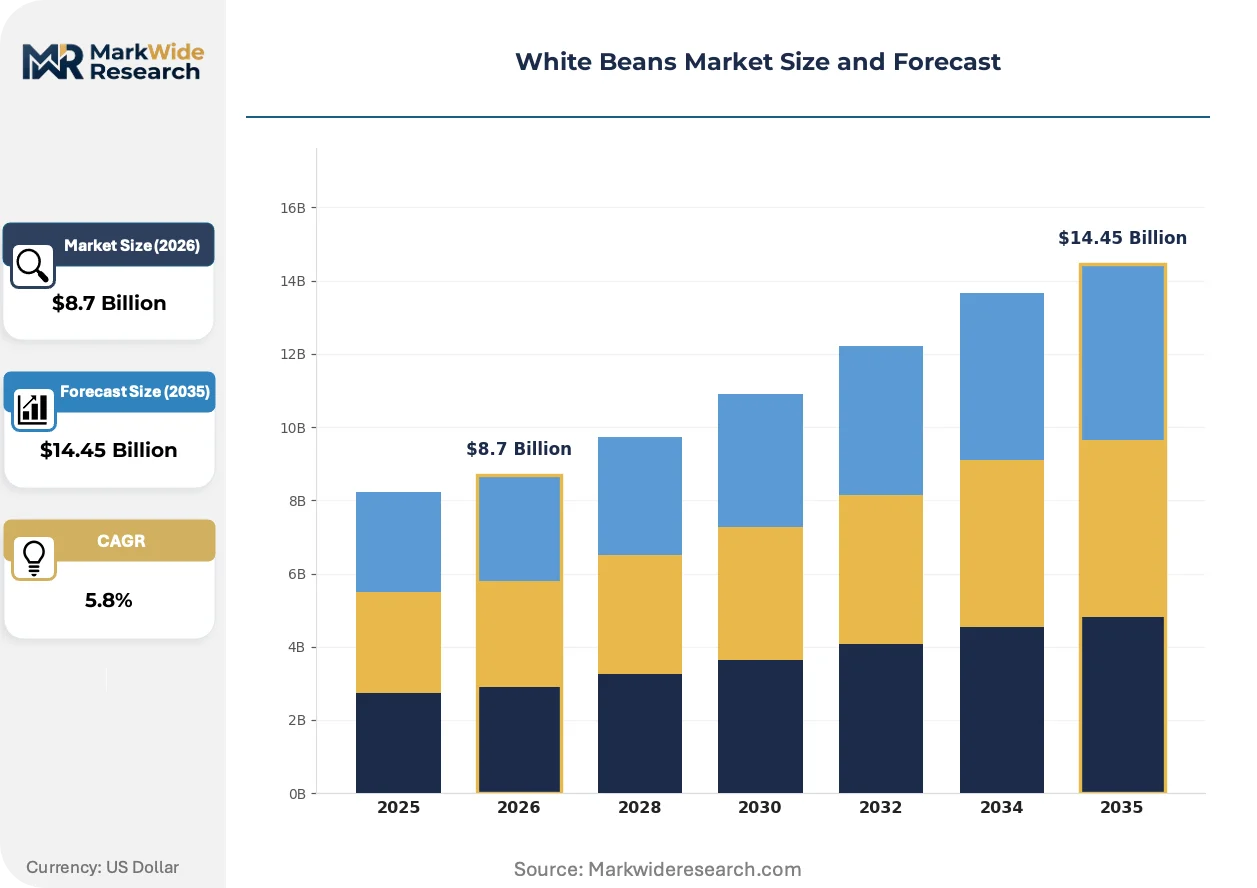
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Great Northern, Navy, Cannellini, Baby Lima Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Farmers' Markets End User: Food Service, Households, Restaurants, Cuisines Packaging Type: Bags, Cans, Jars, Bulk |
| Companies Covered | Progresso Ltd, Molinera Pvt. Ltd, Bush Brothers & Company, Shah Trading Company, Epicure, C&F Foods Inc., Hanover Foods Corp., Carmelina Brands, Faribault Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Beans Market Evolving Landscape
Pulse protein extraction technology is fragmenting traditional commodity flows, while regulatory documentation requirements and channel disintermediation reshape how value is captured across the supply chain.
High-pressure processing for cold-stable bean purees is rewriting shelf-life economics for refrigerated plant-based dairy alternatives. Specialty food manufacturers in the Northeast are adopting these systems at pilot scale. The technology is compressing the advantage held by thermal-canning incumbents and opening fresh-channel placement previously inaccessible to pulse ingredients.
The EU Deforestation Regulation is mandating geolocation traceability for agricultural imports entering European ports. Processors must now document farm-level sourcing coordinates through their entire supply base. Bulk exporters with established farmer-information systems are capturing preferential tender access while laggards face exclusion from EU procurement.
Restaurant chains are consolidating purchasing through specialized produce distributors rather than traditional broadline food service houses. This disintermediation strips margin from legacy canning brands and rewards processors with direct food service sales capabilities. The shift is most visible in fast-casual chains across the Southwest and Pacific states where bowl-format menus dominate.
White Beans Market Segmentation
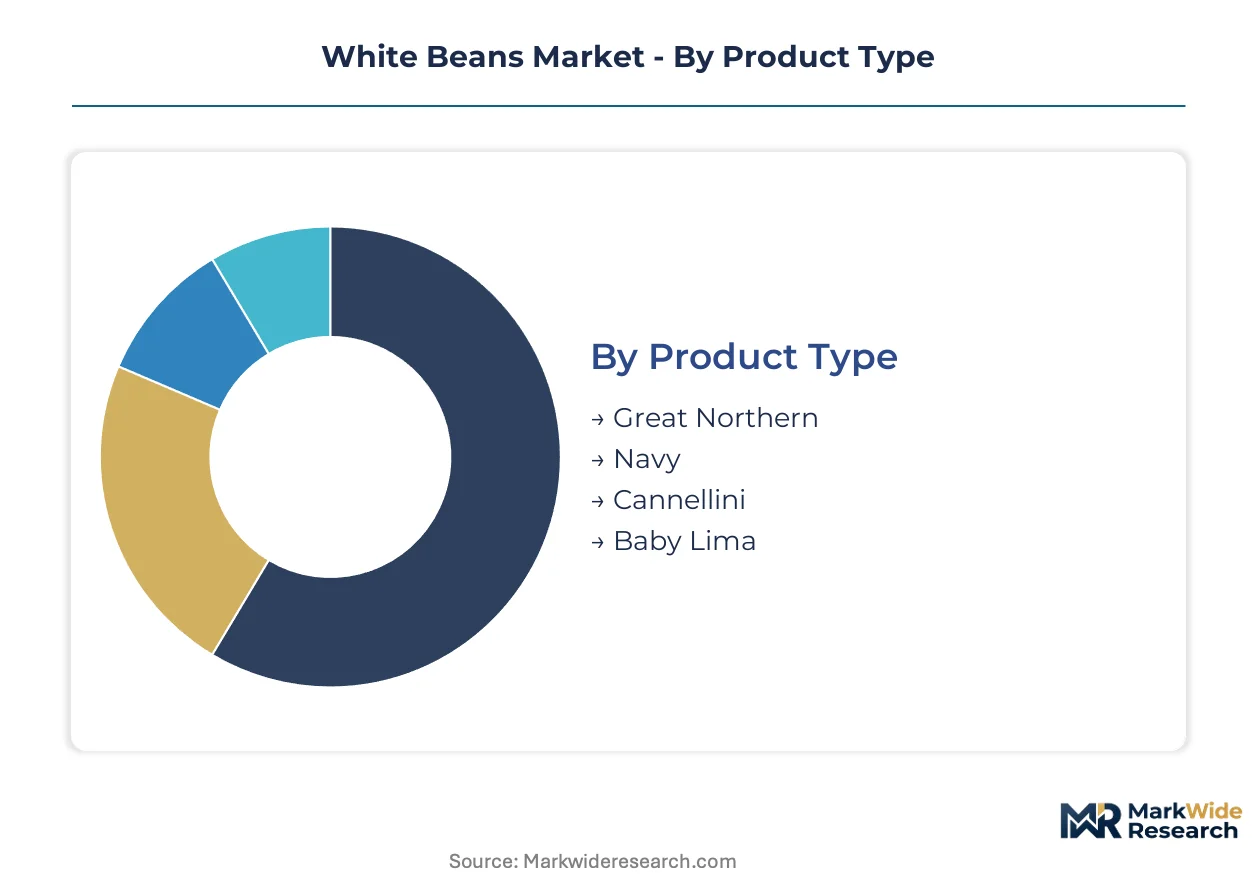
White bean procurement patterns diverge sharply across product grades, channel formats, and end-use specifications. Each segmentation axis carries distinct margin structures and regulatory exposure that reshape how processors configure their supply chains and pricing architectures.
Product Type:
Upgrade cycles in product positioning are accelerating as food manufacturers reformulate around protein isolate specifications and retail buyers tighten origin documentation requirements.
- Great Northern:These large, oval-shaped seeds with thin skins deliver 20-22% protein content and superior hydration retention during thermal processing. Demand concentrates in institutional canning contracts across the US Midwest, where neutral flavor profiles support versatile menu applications and USDA school nutrition programs drive volume commitments.
- Navy:Smaller, denser seeds with higher starch ratios suit baked bean formulations and soup bases. Procurement is shifting toward organic-certified acreage in Michigan and North Dakota as EU Farm to Fork residue thresholds reshape export eligibility for conventional supply.
- Cannellini:Italian-origin positioning commands specialty retail premiums through provenance signaling in Northeast urban markets.
- Baby Lima:Butter bean applications in Southern US cuisine sustain regional processing infrastructure.
Great Northern sits at the top of the volume ranking, with Cannellini climbing the fastest.
Distribution Channel:
Channel economics stratify around fulfillment cost structures and buyer information requirements, with digital platforms capturing margin through disintermediation.
- Supermarkets:Dominant volume channel with established slotting fee structures and private-label penetration. Retail consolidation in the US Southeast and Pacific states is concentrating procurement decisions among fewer banner operators, squeezing processor margins while demanding traceability documentation.
- Online Retailers:Direct-to-consumer pulse subscriptions and bulk pantry delivery models are expanding fastest among urban household segments. Amazon and specialty platforms capture value through subscription lock-in and reduced price transparency versus brick-and-mortar alternatives.
- Specialty Stores:Italian-focused independents and natural food cooperatives sustain Cannellini premiums through origin storytelling.
- Farmers' Markets:Local sourcing channels support heirloom variety preservation and direct grower relationships in agricultural states.
Supermarkets retain volume leadership, though online retailers are expanding most quickly.
End User:
Application specifications diverge across food service, retail, and ingredient channels, with protein isolate demand restructuring traditional commodity flows.
- Food Service:Plant-forward bowl concepts and meat-alternative formulations are expanding procurement volumes among fast-casual chains. Direct purchasing through specialized produce distributors is stripping margin from legacy broadline relationships and rewarding processors with technical service capabilities.
- Households:Pantry stockpiling behavior and health-conscious protein substitution sustain retail dried and canned demand.
- Restaurants:Independent operators favor frozen and canned formats for labor efficiency.
- Cuisines:Ethnic food manufacturers specify heirloom varieties for authenticity requirements.
Food Service leads current volume, with Cuisines gaining share fastest on export expansion.
Packaging Type:
Packaging format selection trades shelf-life extension against material cost and sustainability positioning, with regulatory pressure on single-use plastics reshaping investment priorities.
- Cans:Thermal-stabilized shelf-stable formats dominate institutional and retail ambient channels. Tennessee and Pennsylvania canning infrastructure clusters create supply security for southeastern US networks, though sodium reduction mandates are forcing process reformulation investments.
- Bags:Dried retail formats offer lowest unit cost and minimal processing energy, sustaining price-sensitive household demand.
- Jars:Premium positioning in specialty retail supports organic and low-sodium variants.
- Bulk:Food service and ingredient channel formats minimize packaging cost for high-volume buyers.
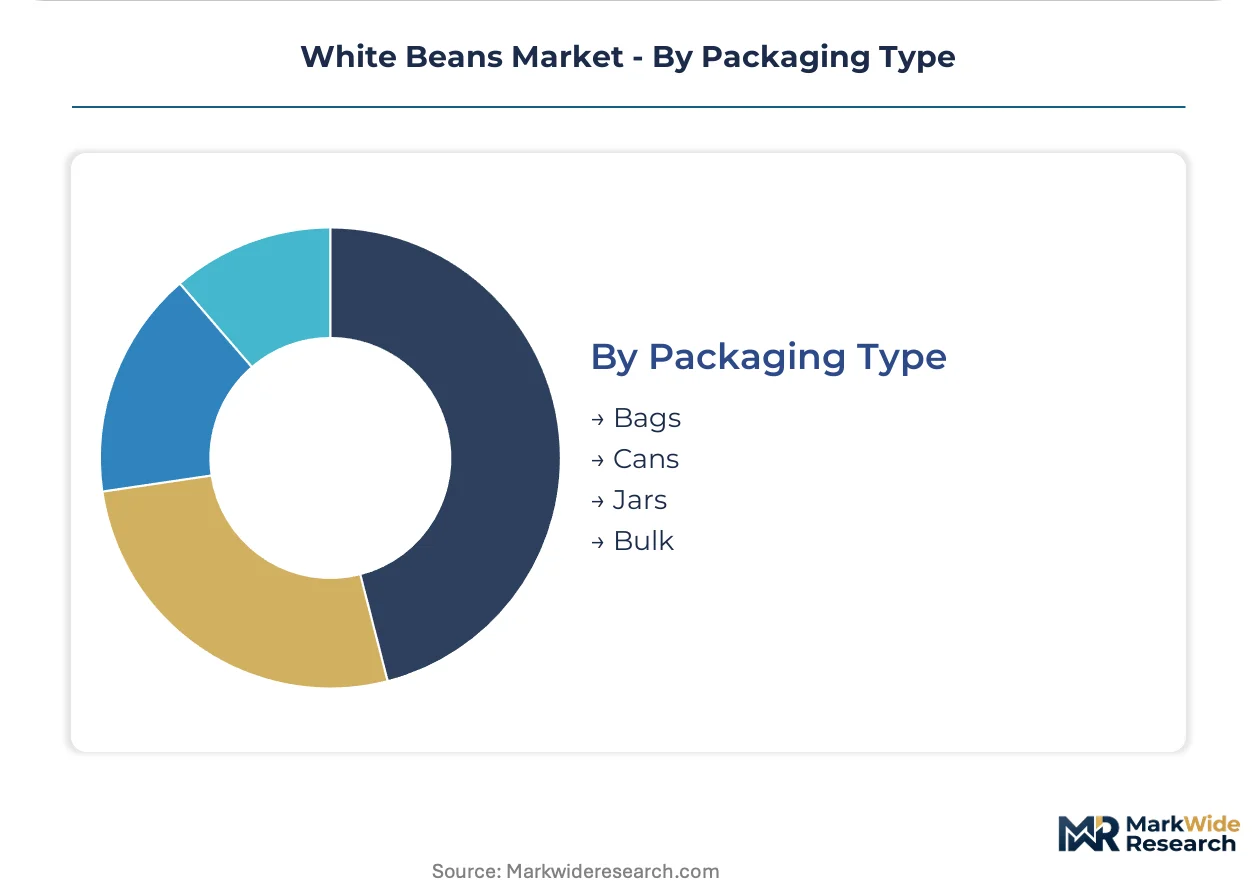
Cans hold the volume advantage, with Bags showing steepest expansion on pantry stockpiling trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tennessee's canning infrastructure anchors North American supply security for white bean processors serving southeastern retail networks. The analysis spans five countries where cultivation, processing, and regulatory frameworks concentrate market activity.
United States
USDA school nutrition programs and fast-casual bowl concepts drive Great Northern procurement across the Midwest. FDA preventive controls under FSMA mandate capital-intensive facility upgrades for ready-to-eat processors. Michigan and North Dakota organic acreage is expanding as growers respond to EU residue thresholds.
Mexico
Domestic canning infrastructure in the central plateau states supports regional supply security for food service chains. Input cost volatility from nitrogen fertilizer price swings compresses grower margins in Guanajuato and Querétaro. Contract growers are accelerating certified organic transitions to maintain export eligibility.
Italy
Provenance signaling for Cannellini varieties commands margin premiums in Northeast US urban markets and specialty European retail. EU Farm to Fork Strategy pesticide thresholds are tightening documentation requirements for Italian-origin exports. Processing clusters in Tuscany and Umbria maintain heirloom variety preservation programs.
Canada
Pulse protein isolate demand from plant-based meat manufacturers is restructuring traditional commodity flows in prairie provinces. Health Canada regulations align with FDA preventive control frameworks for cross-border processed legume trade. Manitoba and Saskatchewan drying facilities are expanding capacity for ingredient-channel supply.
Spain
EU deforestation-free supply chain rules are mandating geolocation traceability for white bean exports entering European ports. Spanish processors with established farmer-information systems capture preferential tender access. Andalusian and Castilian cultivation regions are consolidating documentation systems for compliance.
White Beans Market Competitive Landscape
Capacity expansion dominates the current landscape as processors invest in high-pressure processing systems for cold-stable bean purees. The vendor base stratifies around thermal-canning incumbents, specialty provenance marketers, and ingredient-channel suppliers. Three archetypes define competitive positioning: scale-driven canners with regional infrastructure lock-in, premium-origin specialists leveraging geographic signaling, and protein-isolate processors serving reformulation demand. M&A activity and backward integration into contract growing are the primary competitive moves reshaping supply control.
Among North American canners, Bush Brothers & Company and Hanover Foods Corp. exemplify scale-driven infrastructure anchoring. Carmelina Brands occupies the provenance-specialist position through Italian-origin positioning. These three represent the dominant strategic vectors: captive supply security, vertical control over agricultural sourcing, and premium-channel margin capture through origin storytelling.
| Leading Market Players |
|---|
| Progresso Ltd |
| Molinera Pvt. Ltd |
| Bush Brothers & Company |
| Shah Trading Company |
| Epicure |
| C&F Foods Inc. |
| Hanover Foods Corp. |
| Carmelina Brands |
| Faribault Foods |
| Others |
Value Network & Pricing Analysis
Captive canning infrastructure in Tennessee and Pennsylvania anchors supply security and pricing power for southeastern US retail networks, while Mexican contract growers face margin compression from input cost volatility that reshapes procurement economics across the value chain.
Pricing Analysis
Nitrogen fertilizer price swings pass through directly to Mexican grower margins, forcing contract renegotiations with central plateau processors. Three-tier pricing structure across premium Cannellini, standard Great Northern, and economy Navy varieties reflects provenance signaling and hydration quality differentials. Pricing pressure stems from chickpea and lentil protein isolates competing for identical meat-alternative formulation slots. Institutional buyers in USDA school nutrition programs exhibit highest price sensitivity, while Italian-origin specialty retailers show least.
Supply Chain Analysis
EU Farm to Fork Strategy pesticide residue thresholds are reshaping sourcing toward certified organic acreage in Michigan and North Dakota. White bean supply concentrates in the United States, Mexico, and Italy, with Canadian prairie provinces expanding pulse protein isolate capacity. The chain draws from nitrogen fertilizers, irrigation water rights, and thermal processing energy inputs. Single-source vulnerability clusters in Tennessee-Pennsylvania canning infrastructure create regional supply risk. Distribution runs through specialized produce distributors consolidating fast-casual chain procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pulse protein isolate demand creates margin expansion through premium-tier ingredient positioning, while high-pressure processing technology opens fresh-channel placement previously inaccessible to thermal-canning incumbents.
For Market Incumbents: Hedge against substitution threats by securing backward integration into Michigan and North Dakota organic acreage. Invest in high-pressure processing pilots for cold-stable bean purees before refrigerated plant-based dairy alternatives commoditize thermal-canning margins. Channel control through direct food service sales capabilities protects against produce distributor disintermediation. For New Entrants and Emerging Players: Enter via direct-to-consumer pulse subscriptions in urban household segments where Amazon and specialty platforms have established subscription lock-in infrastructure. Target online retailers as the fastest-expanding distribution channel with bulk pantry delivery models. Provenance signaling for Italian-origin Cannellini offers the most penetrable premium positioning in Northeast urban markets. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale canners with regional infrastructure lock-in because retail consolidation is squeezing processor margins and demanding traceability documentation that smaller players cannot fund. Long-term viability hinges on EU deforestation-free compliance documentation systems. Watch for preferential tender access signals at European ports as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | Cold-stable bean purees compress thermal-canning advantage in refrigerated plant-based dairy alternatives. |
| Organic Acreage Expansion | Michigan and North Dakota growers respond to EU Farm to Fork Strategy residue thresholds for export eligibility. |
| Direct Food Service Sales | Specialized produce distributor relationships strip margin from legacy broadline food service houses. |
| EU Compliance Documentation | Geolocation traceability systems capture preferential tender access under deforestation-free supply chain rules. |
| Pulse Protein Isolate Capacity | Canadian prairie facilities restructure traditional commodity flows toward ingredient-channel supply. |
Research Methodology
Coverage spans the United States, Mexico, Italy, Canada, and Spain, with primary inputs from each market through structured interviews with canning facility operations managers, contract growers in Guanajuato and Querétaro, fast-casual chain procurement directors, EU regulatory affairs specialists, and pulse protein isolate processors. Secondary validation draws from USDA Agricultural Marketing Service grading standards, FDA FSMA preventive controls guidance, EU Farm to Fork Strategy documentation, and customs trade data. Bottom-up acreage and processing capacity estimates triangulate against top-down demand segmentation.
Rate-of-change decomposition separates volume growth from price realization across the projection horizon. Segmentation dimensions modeled include product variety, distribution channel, end-user application, and packaging format. CAGRs derive from historical growth pattern analysis adjusted for structural shifts in protein isolate demand and regulatory threshold tightening. Forecast inputs incorporate nitrogen fertilizer price trajectories and EU deforestation-free compliance adoption curves.
The model holds under stable EU import specification regimes and continued fast-casual chain expansion; deviation in nitrogen fertilizer volatility or FDA facility upgrade mandates would shift processor margin assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Global Maize Market
Grains
Soy Grits Market
Grains
Mesquite Flour Market
Grains
Red Rice Market
Grains
Organic Cereals Market
Grains
Green Pea Grits Market
Grains
Durum Wheat Flour Market
Grains
Rice Flour Market
Grains
GMO Corn Market
Grains
Grain Storage Systems Market
Grains
Corn Gluten Feed Market
Grains
Grain Dryers Market
Grains
Ancient Grain Market
Grains
Mexico Rice Market
Grains
Europe Wheat Protein Market
Grains
Global Quinoa Market