
 Antiglaucoma Drugs Market | 2026-2036
Antiglaucoma Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Antiglaucoma Drugs Market Analysis
Preservative-free formulations are recalibrating product economics across the antiglaucoma landscape as benzalkonium chloride-free alternatives command premium positioning and reduce long-term ocular surface toxicity. Alcon AG leverages its manufacturing scale to supply broad-spectrum prostaglandin analogues across multiple continents. Pfizer Inc. sustains competitive presence through established beta-blocker portfolios and hospital formulary relationships. Santen Pharmaceutical Company Ltd. specializes in preservative-free and novel delivery innovations for the Japanese and European markets.
Antiglaucoma drugs constitute pharmacological agents that reduce intraocular pressure through mechanisms including aqueous humor suppression or enhanced uveoscleral outflow, with topical prostaglandin analogues typically achieving 25-33% pressure reduction as monotherapy. These therapeutics serve the primary commercial purpose of preventing optic nerve damage and visual field loss in glaucoma management. Prostaglandin analogues occupy the largest revenue pool due to once-daily dosing convenience and superior efficacy profiles, while sustained-release devices represent the fastest-expanding delivery mode as clinicians seek to address adherence failures. Ophthalmology clinics anchor end-user demand through direct patient monitoring and repeat prescription cycles, though home care settings are gaining traction with patient-administered sustained-release options.
FDA ophthalmic drug approval standards and EMA's MDR requirements for combination device-drug products shape development timelines and market access pathways for novel delivery systems. The EPA regulates manufacturing discharge for active pharmaceutical ingredients, while ISO 14155 governs clinical investigation standards for ophthalmic therapeutic trials. Stakeholders must monitor sustained-release device reimbursement decisions and preservative-free formulation patent expiries to align portfolio investments with shifting clinical preference and competitive generic entry.
Market Dynamics
Sustained-release ocular delivery systems are compressing dosing frequency from daily to quarterly, restructuring patient adherence economics and forcing reformulation of legacy prostaglandin analogues into depot-compatible matrices.
Growth Catalysts
- Japan's PMDA breakthrough therapy designation:Accelerated review pathways for sustained-release devices reduce development-to-commercialization timelines for novel glaucoma implants targeting refractory patients.
- Ophthalmology clinic consolidation:Large multi-site eye care networks in the United States negotiate volume-based contracts for preservative-free prostaglandin analogues, concentrating procurement power with formulary gatekeepers.
- Biodegradable polymer platforms:PLGA-based intracameral implants enable tunable drug release kinetics, allowing manufacturers to differentiate beyond efficacy into dosing convenience metrics.
Market Restraints
- Active pharmaceutical ingredient concentration:Bimatoprost and latanoprost supply chains cluster among Indian and Chinese contract manufacturers, creating single-source vulnerability for Western formulators.
- Combination device-drug regulatory friction:FDA's 21 CFR Part 3 product jurisdiction determinations add 12-18 months to sustained-release device approvals compared to standalone drug pathways.
- Generic prostaglandin analogue substitution:Patent-expired latanoprost formulations priced at 80-90% below originator levels erode branded pricing power in reimbursement-constrained European markets.
Strategic Opportunities
- Germany's AMNOG early benefit assessment:Sustained-release devices demonstrating non-inferiority to daily drops can secure premium reimbursement through added clinical benefit ratings.
- Home administration training protocols:Remote patient monitoring platforms enable ophthalmology practices to delegate sustained-release device maintenance to trained caregivers, expanding addressable patient populations beyond clinic-proximate urban centers.
- Neuroprotection indication expansion:Rho kinase inhibitors with demonstrated retinal ganglion cell preservation properties position for label expansion beyond intraocular pressure reduction into disease modification claims.
Industry Challenges
- Ocular pharmacokinetic modeling expertise:Sustained-release formulation development requires specialized corneal penetration and aqueous humor clearance simulation capabilities scarce among traditional ophthalmic CROs.
- Good Manufacturing Practice facility retooling:Transition from sterile solution filling to aseptic implant manufacturing demands ISO 14644-1 Class 7 cleanroom investments exceeding typical ophthalmic liquid facility capital intensity.
- Preservative-free packaging integrity:Multi-dose bottles without benzalkonium chloride require advanced barrier systems to prevent microbial ingress, complicating stability validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiglaucoma Drugs Market |
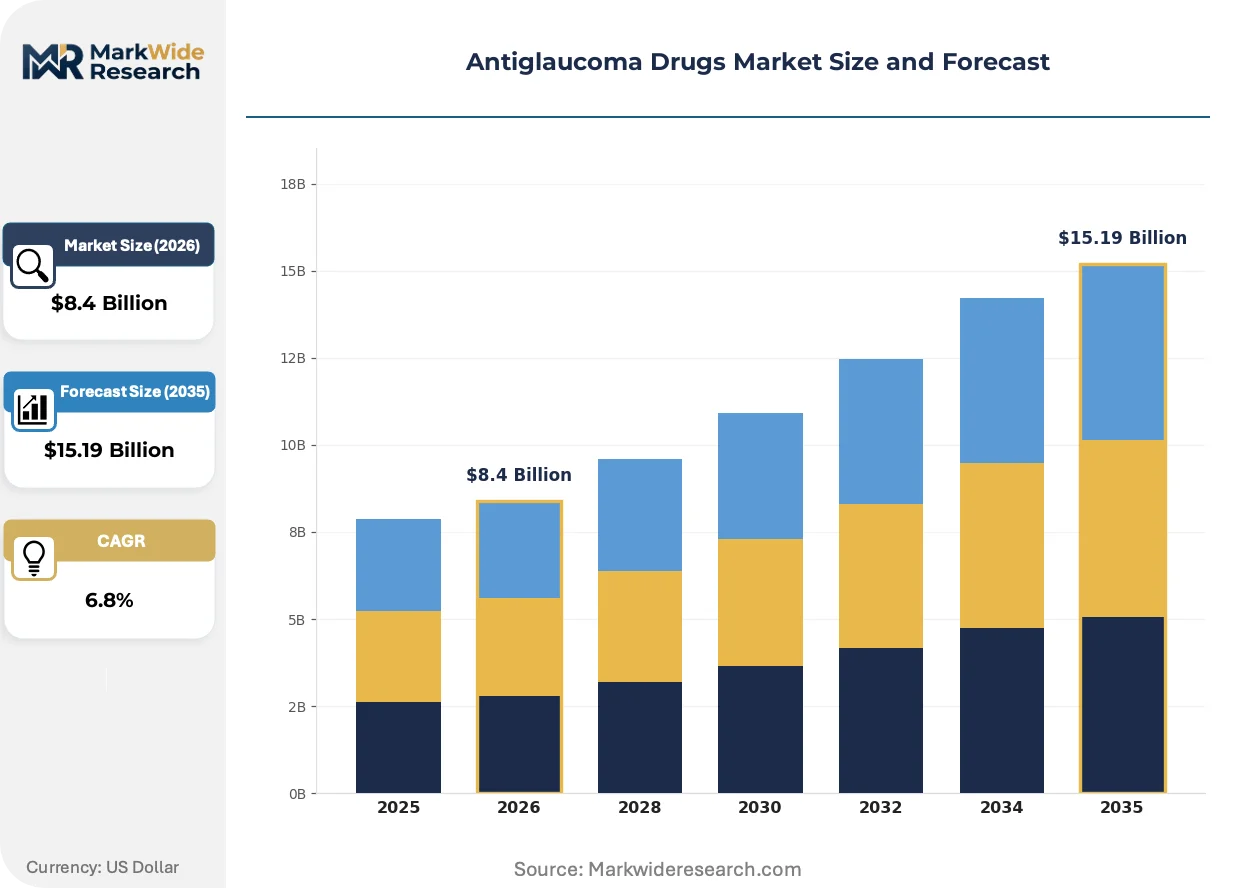
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prostaglandin Analogues, Beta-Blockers, Alpha Agonists, Carbonic Anhydrase Inhibitors Delivery Mode: Topical Solutions, Injectable Forms, Oral Tablets, Sustained-Release Devices End User: Ophthalmology Clinics, Hospitals, Ambulatory Surgical Centers, Home Care Settings Therapy Area: Open-Angle Glaucoma, Angle-Closure Glaucoma, Normal Tension Glaucoma, Secondary Glaucoma |
| Companies Covered | Alcon AG, Bausch + Lomb Inc., Aerie Pharmaceuticals Inc., Merck & Co. Inc., Pfizer Inc., Allergan Inc., Santen Pharmaceutical Company Ltd., Johnson & Johnson, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiglaucoma Drugs Market Emerging Trajectories
Antiglaucoma therapeutics are pivoting from chemical innovation toward delivery mechanism differentiation, with implantable depot systems and preservative-free multi-dose platforms commanding development priority over novel molecular entities.
Biodegradable intracameral implants incorporating prostaglandin analogues into PLGA matrices are consolidating first-line therapy positioning against daily eye drops. Ophthalmology clinics in the United States and Germany are adopting quarterly-administered sustained-release devices for patients with documented adherence failures. This consolidation is compressing the addressable market for conventional topical formulations while expanding the premium device segment.
EMA's Medical Device Regulation (MDR) 2017/745 reclassification of drug-eluting ocular implants as Class III devices imposes notified body conformity assessment requirements previously exempt under the Medical Devices Directive. European manufacturers face extended technical documentation and clinical evaluation report obligations. German and French ophthalmic device sponsors are responding by front-loading PMCF study designs to satisfy post-market surveillance mandates.
Patient-administered therapy protocols are displacing clinic-dependent administration for select sustained-release formats. Home care settings in Japan and the United States now accommodate caregiver-trained bimatoprost implant maintenance, reducing ophthalmology clinic visit burden. This channel rotation is most visible among elderly glaucoma populations in rural prefectures where specialist access constrains conventional follow-up schedules.
Antiglaucoma Drugs Market Segmentation
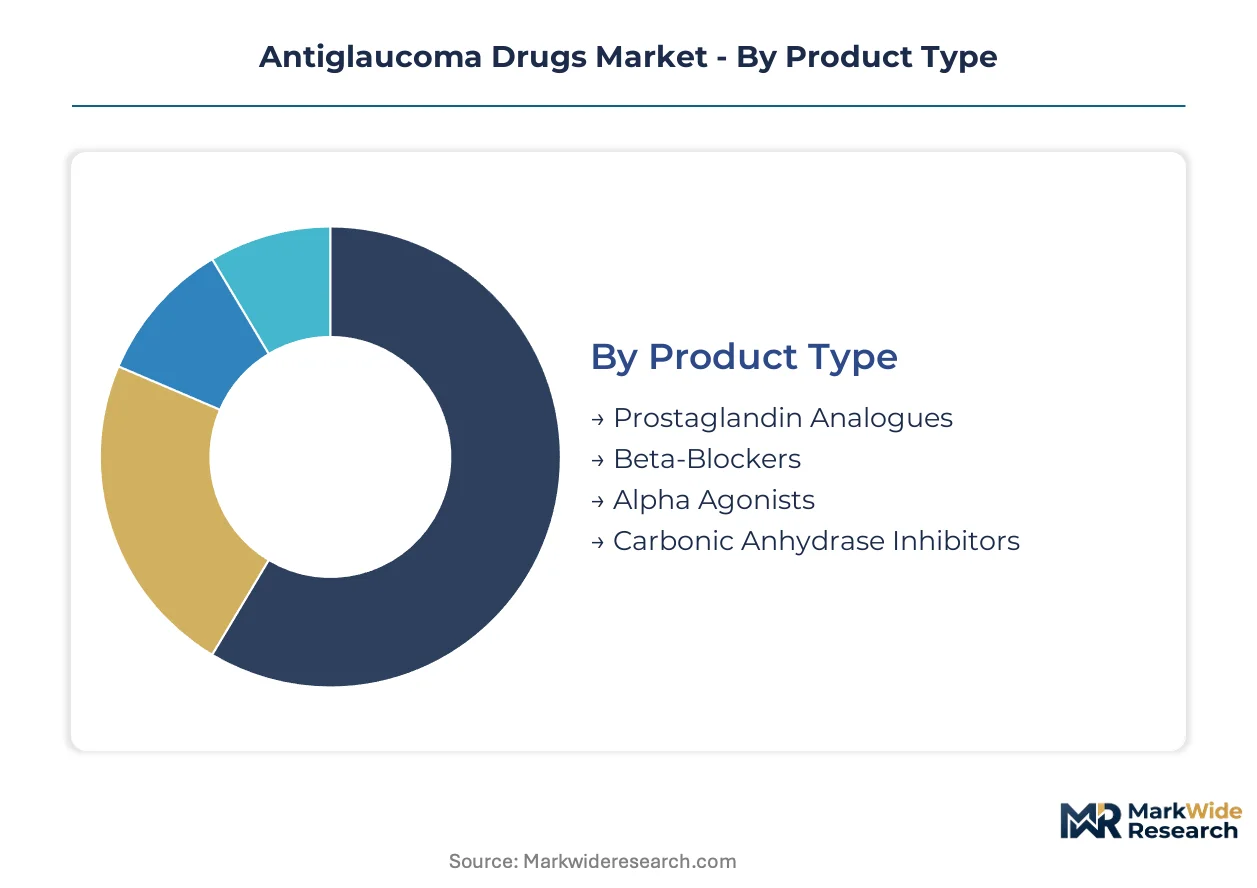
Antiglaucoma drug segmentation reveals how delivery innovation and site-of-care economics are restructuring commercial priorities. Product type and delivery mode classifications now determine reimbursement pathways more than molecular novelty alone.
Product Type:
Integration depth varies sharply across pharmacological classes, with standalone monotherapy agents dominating first-line protocols while combination-ready molecules embed into fixed-dose regimens.
- Prostaglandin Analogues:These agents enhance uveoscleral outflow through FP receptor agonism, typically achieving 25-33% intraocular pressure reduction. Demand concentrates in United States ophthalmology clinics where once-daily dosing drives formulary preference and patient adherence metrics. Branded formulations face accelerating generic substitution pressure in European markets.
- Beta-Blockers:Non-selective beta-adrenergic antagonists suppress aqueous humor production through ciliary body action. Volume placements cluster in hospital settings across Germany and Japan where combination therapy with prostaglandins anchors refractory patient protocols. Manufacturing concentrates among established Indian API suppliers.
- Alpha Agonists:Dual-mechanism agents reducing aqueous production and enhancing uveoscleral outflow serve adjunctive therapy roles.
- Carbonic Anhydrase Inhibitors:Systemic and topical formulations target enzymatic suppression of bicarbonate formation in ciliary epithelium.
Volume placements concentrate in prostaglandin analogues; the faster expansion belongs to preservative-free reformulations of established molecules.
Delivery Mode:
Cost tier stratification separates commodity topical solutions from premium implantable systems requiring specialized administration infrastructure.
- Sustained-Release Devices:Biodegradable intracameral implants incorporating PLGA matrices enable quarterly dosing intervals. German and United States clinics are adopting these systems for documented adherence failures, with reimbursement contingent upon prior authorization demonstrating drop instillation incompetence. FDA's 21 CFR Part 3 jurisdiction determinations extend approval timelines versus conventional drug pathways.
- Topical Solutions:Multi-dose and unit-dose eye drops constitute the volume base across all geographies. Japanese and European markets command premium pricing for benzalkonium chloride-free alternatives addressing ocular surface toxicity concerns. Manufacturing scale advantages accrue to suppliers with integrated sterile filling capabilities.
- Injectable Forms:Intravitreal and intracameral bolus injections serve acute pressure management in surgical settings.
- Oral Tablets:Systemic carbonic anhydrase inhibitors retain niche utility for short-term pressure control perioperatively.
Procurement volumes favor topical solutions; the steepest expansion trajectory characterizes sustained-release devices as adherence economics reshape prescribing patterns.
End User:
Customer type segmentation tracks the migration from facility-dependent administration toward patient-managed therapy protocols.
- Ophthalmology Clinics:Multi-site eye care networks in the United States negotiate volume-based contracts for prostaglandin analogues, concentrating procurement power with formulary gatekeepers. These sites anchor initial diagnosis and chronic disease monitoring.
- Home Care Settings:Caregiver-trained administration of select sustained-release formats is expanding addressable populations beyond clinic-proximate urban centers in Japan and rural United States regions. Remote monitoring platforms enable delegation of device maintenance.
- Hospitals:Acute care facilities manage refractory cases and surgical interventions.
- Ambulatory Surgical Centers:Same-day procedure sites handle selective laser trabeculoplasty and implant placements.
Patient volume concentrates in ophthalmology clinics; home care settings are climbing the fastest as delivery innovation enables channel rotation.
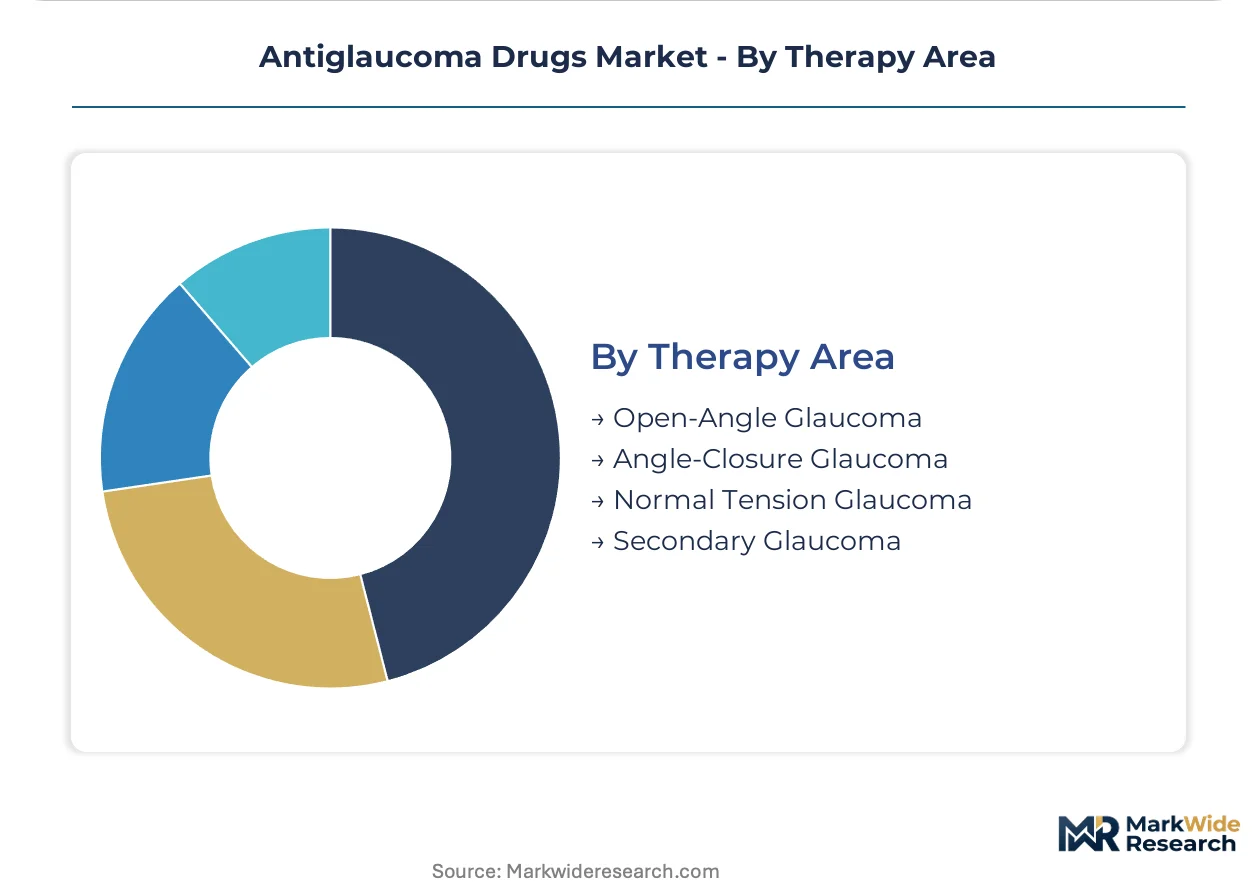
Therapy Area:
Disease severity and pathophysiology determine whether topical monotherapy suffices or surgical intervention becomes necessary.
- Open-Angle Glaucoma:Chronic progressive optic neuropathy with normal anterior chamber anatomy constitutes the predominant addressable population. United States and German prescribing patterns favor prostaglandin analogue monotherapy as first-line, with sustained-release devices reserved for documented adherence failures.
- Angle-Closure Glaucoma:Acute or chronic presentations with anatomically compromised drainage require laser or surgical intervention beyond pharmacological management alone.
- Normal Tension Glaucoma:Optic nerve damage without elevated intraocular pressure challenges conventional pressure-centric therapeutic paradigms.
- Secondary Glaucoma:Post-surgical, traumatic, or steroid-induced etiologies demand etiology-specific management protocols.
Treatment volume concentrates in open-angle presentations; normal tension glaucoma represents the most underserved segment awaiting neuroprotective label expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States ophthalmology clinics concentrate the highest per-capita demand for sustained-release glaucoma devices. Aging demographics and established reimbursement infrastructure anchor advanced therapy adoption across urban and suburban markets.
United States
Multi-site eye care networks negotiate volume-based contracts for preservative-free prostaglandin analogues, concentrating procurement power with formulary gatekeepers. FDA's 21 CFR Part 3 jurisdiction determinations extend sustained-release device approval timelines. Boston and San Francisco clusters host specialized ophthalmic CROs supporting PLGA implant development.
Germany
Germany's AMNOG early benefit assessment enables premium reimbursement for sustained-release devices demonstrating added clinical benefit. EMA's MDR 2017/745 reclassification imposes Class III notified body conformity obligations on drug-eluting ocular implants. The Rhine-Main region anchors ophthalmic device manufacturing with integrated sterile filling capabilities.
Japan
PMDA breakthrough therapy designation accelerates review pathways for novel glaucoma implants targeting refractory patients. METI supports domestic biodegradable polymer platform development through innovation procurement programs. Osaka-based specialists pioneer caregiver-trained home administration protocols for rural prefecture expansion.
India
Domestic API manufacturing clusters supply bimatoprost and latanoprost to Western formulators, though single-source vulnerabilities persist. CDSCO streamlined approval pathways for generic prostaglandin analogues accelerate market entry. Hyderabad and Ahmedabad host contract manufacturing organizations serving European and North American ophthalmic sponsors.
China
NMPA priority review vouchers for innovative ophthalmic delivery systems compress development-to-commercialization timelines. MIIT biomedical materials initiatives fund PLGA matrix research through provincial technology grants. Shanghai and Suzhou clusters integrate sterile solution filling with emerging aseptic implant manufacturing capabilities.
Antiglaucoma Drugs Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with originator pharmaceutical companies commanding premium pricing for preservative-free formulations while Indian and Chinese API suppliers anchor generic cost structures. The vendor base organizes around three archetypes: diversified ophthalmic conglomerates with manufacturing scale, mid-cap delivery innovation specialists, and regional generic formulators with API backward integration. Competitive dynamics center on M&A activity targeting sustained-release device platforms and strategic partnerships linking polymer science expertise with ophthalmic commercial infrastructure.
Among diversified ophthalmic conglomerates, Alcon AG and Pfizer Inc. exemplify scale-driven archetypes with established hospital formulary relationships. Santen Pharmaceutical Company Ltd. occupies a position within the delivery innovation specialist tier, representing Japanese and European market focus on preservative-free and novel administration formats. These three companies anchor competitive positioning across the branded-prescription and device-drug combination segments without dominating any single therapeutic class.
| Leading Market Players |
|---|
| Alcon AG |
| Bausch + Lomb Inc. |
| Aerie Pharmaceuticals Inc. |
| Merck & Co. Inc. |
| Pfizer Inc. |
| Allergan Inc. |
| Santen Pharmaceutical Company Ltd. |
| Johnson & Johnson |
| Novartis AG |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up ophthalmic device specialists now control sustained-release implant manufacturing, compressing procurement timelines for PLGA matrix suppliers while enforcing quarterly volume commitments that stabilize API pricing for Western formulators.
Pricing Analysis
Volume placements concentrate in commodity topical solutions while margins accrue to sustained-release devices and preservative-free formulations. Three-tier pricing structure across premium implantable systems, standard branded drops, and economy generic analogues reflects differentiation by dosing convenience and benzalkonium chloride-free certification. Pricing pressure stems from latanoprost generic substitution eroding originator revenues in European reimbursement markets. Hospital formulary gatekeepers exhibit lowest price sensitivity; retail pharmacy channels in India and China show highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Indian and Chinese contract manufacturers supplying bimatoprost and latanoprost active pharmaceutical ingredients to Western formulators. PLGA polymer feedstock draws from specialized chemical producers in Germany and the United States, while sterile filling capacity concentrates in Switzerland and Japan. Tariff exposure on Chinese-sourced raw materials threatens margin stability for mid-tier generic formulators. Distribution runs through ophthalmology clinic networks and hospital procurement consortia in the United States and Germany, with emerging direct-to-patient channels for home-administered sustained-release formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antiglaucoma landscape is becoming a vertical-integration race as manufacturers pursue captive control over PLGA polymer synthesis and sterile implant fabrication to defend margin structures against API cost volatility.
For Market Incumbents: Anchor formulary positioning through preservative-free portfolio breadth and sustained-release device placement in United States multi-site eye care networks. Backward integration into PLGA polymer production mitigates raw material cost spikes from European chemical suppliers. Counter generic latanoprost substitution with adherence-monitoring services that demonstrate sustained-release device value to German AMNOG assessors. For New Entrants and Emerging Players: The price-point gap between quarterly-administered sustained-release implants and daily generic drops creates entry space for mid-tier preservative-free formulations. Target Japanese rural prefectures where caregiver-trained home administration protocols expand addressable populations beyond clinic-proximate urban centers. Pursue CDSCO accelerated approval pathways for benzalkonium chloride-free latanoprost to capture Indian ophthalmology clinic procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap delivery innovation specialists with PLGA implant platforms and Japanese regulatory expertise. Long-term viability hinges on sustained-release device reimbursement securing premium positioning against generic commoditization. Monitor FDA 21 CFR Part 3 jurisdiction determination timelines as inflection signal for device-drug combination approval risk.| Strategic Initiative | Industry Significance |
|---|---|
| PLGA Polymer Backward Integration | Captive supply of biodegradable matrices insulates German and United States manufacturers from specialty chemical price volatility. |
| Preservative-Free Formulation Expansion | Benzalkonium chloride-free multi-dose platforms command Japanese and European premium positioning against ocular surface toxicity concerns. |
| Sustained-Release Device Reimbursement Strategy | Prior authorization protocols demonstrating drop instillation incompetence unlock United States clinic adoption for quarterly-administered implants. |
| Caregiver-Trained Home Administration Protocols | Remote monitoring platforms enable rural prefecture expansion in Japan beyond specialist-proximate urban centers. |
| Regulatory Affairs Specialization in Combination Products | EMA MDR Class III notified body expertise accelerates European market access for drug-eluting ocular implants. |
Methodological Framework
Independent corroboration across regulatory filings, hospital procurement databases, and pharmaceutical trade data underwrites the qualitative findings in this study. Primary interviews with drug development executives, formulary directors at United States multi-site eye care networks, regulatory affairs leads specializing in FDA 21 CFR Part 3 submissions, and payer access specialists were combined with secondary validation through FDA approval databases, EMA MDR submission records, ClinicalTrials.gov entries, and CMS Medicare reimbursement data. Bottom-up patient volume modeling and top-down pharmaceutical market sizing were triangulated to cross-verify segment estimates.
Comparable-period anchoring to historical prostaglandin analogue prescription volumes and sustained-release device placement rates established the forecast baseline across the analysis window. Segmentation modeling incorporated pharmacological class, delivery mode, end-user channel, and regional regulatory cluster dimensions. CAGRs were derived from trend extrapolation of adherence economics and reimbursement pathway evolution, with specific inputs including PMDA breakthrough therapy designation timelines and AMNOG early benefit assessment outcomes for novel delivery systems.
Underlying measurement precision varies by segment; sustained-release device forecasts carry tighter precision than oral tablet projections due to concentrated manufacturer visibility. Forecasts reflect assumptions regarding FDA approval pathway efficiency and European generic substitution rates, with revision risk from regulatory friction in combination product classifications or API supply disruptions from Indian and Chinese contract manufacturers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Nasal Vaccines Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Trisenox Market
Pharmaceuticals
Global Sterile Injectable Drugs Market
Pharmaceuticals
United Kingdom OTC Drugs Market
Pharmaceuticals
Japan Diabetes Drugs Market
Pharmaceuticals
Blood Clotting Accelerant Market
Pharmaceuticals
Global Cholera Vaccines Market
Pharmaceuticals
Global Specialty Pharmaceuticals Market
Pharmaceuticals
Global Paracetamol Market
Pharmaceuticals
AI Drug Development Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Radiopharmaceutical (Oral Route) Market
Pharmaceuticals
H2-Receptor Antagonists Market