
 Laser Vision Correction Market | 2026-2036
Laser Vision Correction Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Vision Correction Market Outlook
Femtosecond laser integration is tilting procedural workflows away from mechanical microkeratomes toward all-laser platforms. NIDEK CO., LTD. anchors its position through advanced diagnostic-to-surgical system integration. Alcon Inc. dominates the femtosecond laser segment with proprietary flap creation technology. ZEISS competes through its SMILE platform, which eliminates flap creation entirely.
Laser vision correction encompasses refractive surgical procedures that reshape the corneal stroma using excimer or femtosecond laser energy, typically operating at 193 nm wavelength with sub-micron tissue ablation precision, to modify the eye's optical power and eliminate dependence on corrective lenses. SMILE technology now leads growth trajectories as flapless single-incision protocols reduce dry eye incidence and preserve corneal biomechanical strength. Ophthalmology practices capture concentrated margin pools by bundling diagnostic imaging, surgical fees, and post-operative monitoring into unified care pathways.
The FDA governs excimer laser PMA approvals and femtosecond laser 510(k) clearances in the United States, while the EU MDR and CE marking framework governs commercialization across European markets, with both regimes intensifying clinical evidence requirements for new ablation algorithms. China's NMPA accelerates review timelines for domestically manufactured laser platforms under its innovative medical device priority pathway. Stakeholders must monitor evolving reimbursement banding for enhancement procedures versus primary corrections across national health systems.
Market Dynamics
The transition from mechanical microkeratomes to femtosecond laser platforms is compressing procedural variability while elevating capital intensity requirements across ophthalmology practices. This equipment refresh cycle concentrates purchasing power among multi-site surgical networks capable of absorbing platform migration costs.
Growth Catalysts
- Young Adult Myopia Prevalence:Demographic concentration of myopia cases among 18-35 year-olds in China and the United States sustains primary procedure volumes. China's NMPA priority pathway accelerates domestic laser platform approvals, expanding accessible supply.
- Wavefront-Guided Ablation:Topography-linked treatment planning reduces enhancement rates and improves night vision outcomes. Outpatient surgical centers bundle diagnostic imaging with surgical fees to capture margin concentration.
- SMILE Protocol Adoption:Flapless single-incision techniques preserve corneal biomechanical strength and reduce post-operative dry eye incidence. Germany's advanced reimbursement frameworks support premium technology uptake.
Market Restraints
- Capital Equipment Intensity:Femtosecond laser platforms require substantial upfront investment, constraining independent practice participation. Excimer laser maintenance contracts and consumable excimer gas supply chains add recurring cost burdens.
- Reimbursement Band Compression:National health systems in Germany and selective US commercial payers apply differential coverage between primary corrections and enhancement procedures, limiting revision revenue.
- Corneal Thickness Limitations:Patient candidacy restrictions based on residual stromal bed requirements exclude hyperopic and high-myopic cases from standard LASIK protocols, capping addressable populations.
Strategic Opportunities
- Phakic IOL Convergence:Combination of corneal laser platforms with implantable collamer lens workflows enables practices to address patients outside traditional ablation candidacy. This hybrid service architecture expands per-patient lifetime value.
- Telemedicine-Enabled Screening:Remote corneal topography and wavefront analysis reduce geographic access barriers. China's tier-two cities present underpenetrated demand pools reachable through digital triage channels.
- Biomechanical Modeling Integration:Finite element analysis of corneal response to laser ablation is virtualizing preoperative planning. Software licensing models create recurring revenue streams distinct from capital equipment sales.
Industry Challenges
- Fellowship-Trained Surgeon Scarcity:Refractive surgery subspecialty programs produce limited annual graduates relative to equipment deployment rates. Surgical volume thresholds for competency maintenance strain rural and secondary market staffing.
- Legacy Diagnostic Interoperability:Wavefront aberrometers from prior technology generations lack seamless data export to contemporary laser platforms. Practices face workflow fragmentation or costly parallel system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Vision Correction Market |
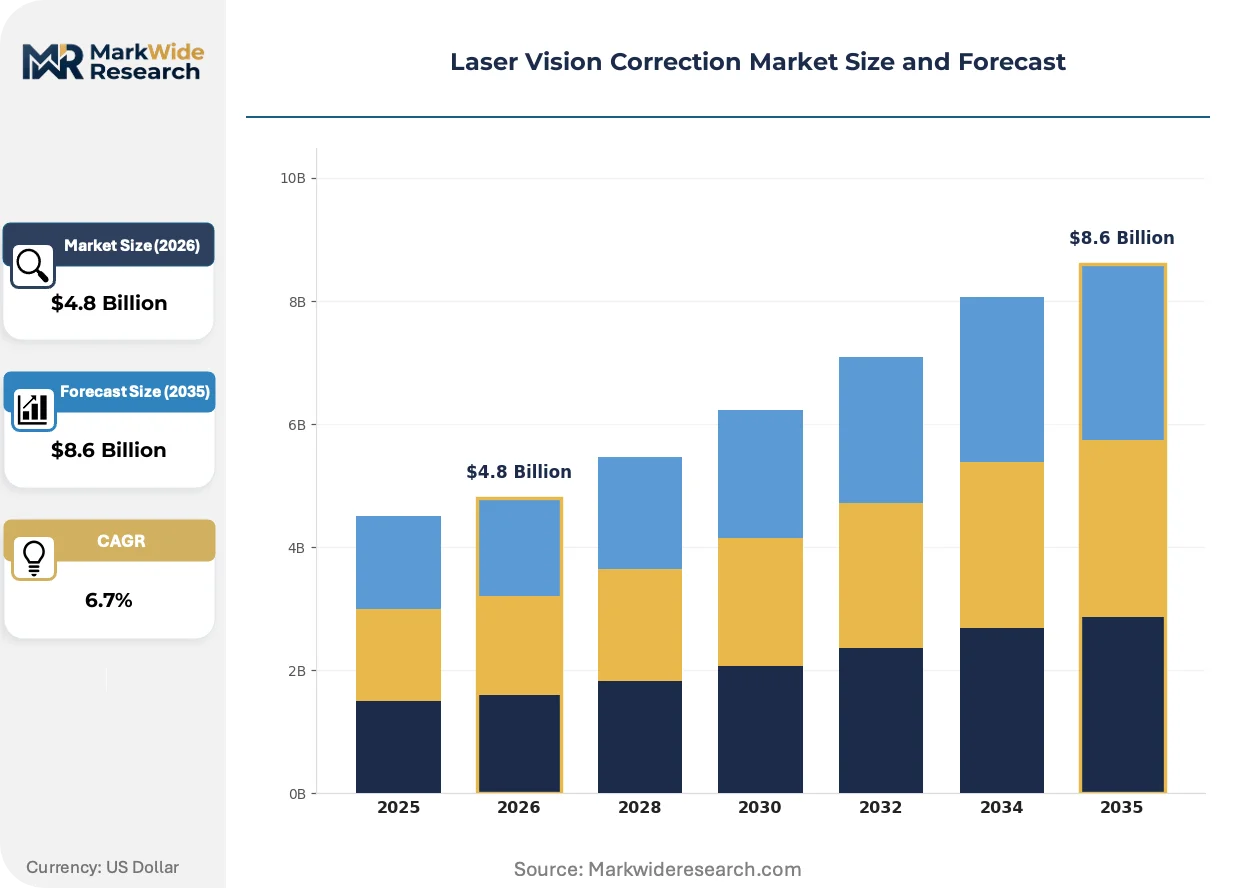
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LASIK, PRK, SMILE, LASEK End User: Hospitals, Clinics, Ophthalmology Practices, Mobile Surgical Units Procedure Type: Refractive Surgery, Enhancement Procedures, Vision Therapy, Follow-up Care Equipment: Laser Systems, Diagnostic Devices, Surgical Instruments, Patient Monitoring Tools |
| Companies Covered | NIDEK CO., LTD., Bausch + Lomb, Johnson & Johnson Vision, Excelsius Medical, Abbott, Alcon Inc., Ziemer Ophthalmic Systems AG, TLC Vision, ZEISS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Vision Correction Market Strategic Shifts
Digital diagnostic integration is collapsing the latency between preoperative measurement and surgical execution, compressing patient throughput timelines while elevating precision requirements. These developments are reconfiguring competitive advantage toward software-enabled platform ecosystems.
Femtosecond laser technology is virtualizing flap creation protocols through computer-guided tissue dissection at specified corneal depths. High-volume ambulatory surgery centers in the United States deploy these platforms to standardize outcomes across surgeon skill variations. The elimination of mechanical microkeratome blade variables is compressing enhancement procedure rates and reducing malpractice exposure.
The EU MDR intensifies clinical evidence requirements for new ablation algorithms seeking CE marking, extending regulatory timelines for algorithmic refinements. Manufacturers must generate prospective clinical data rather than relying on predicate device equivalency. European ophthalmology practices face delayed access to topography-optimized treatment profiles as firms prioritize FDA PMA pathways for US market entry.
Patient acquisition models are fragmentating from optometrist-referral dependence toward direct-to-consumer digital channels. Large US refractive surgery chains deploy search-engine marketing and financing partnerships to bypass traditional co-management relationships. This channel shift concentrates marketing expenditure among platforms capable of national brand awareness investment, pressuring regional practice groups.
Laser Vision Correction Market Segmentation
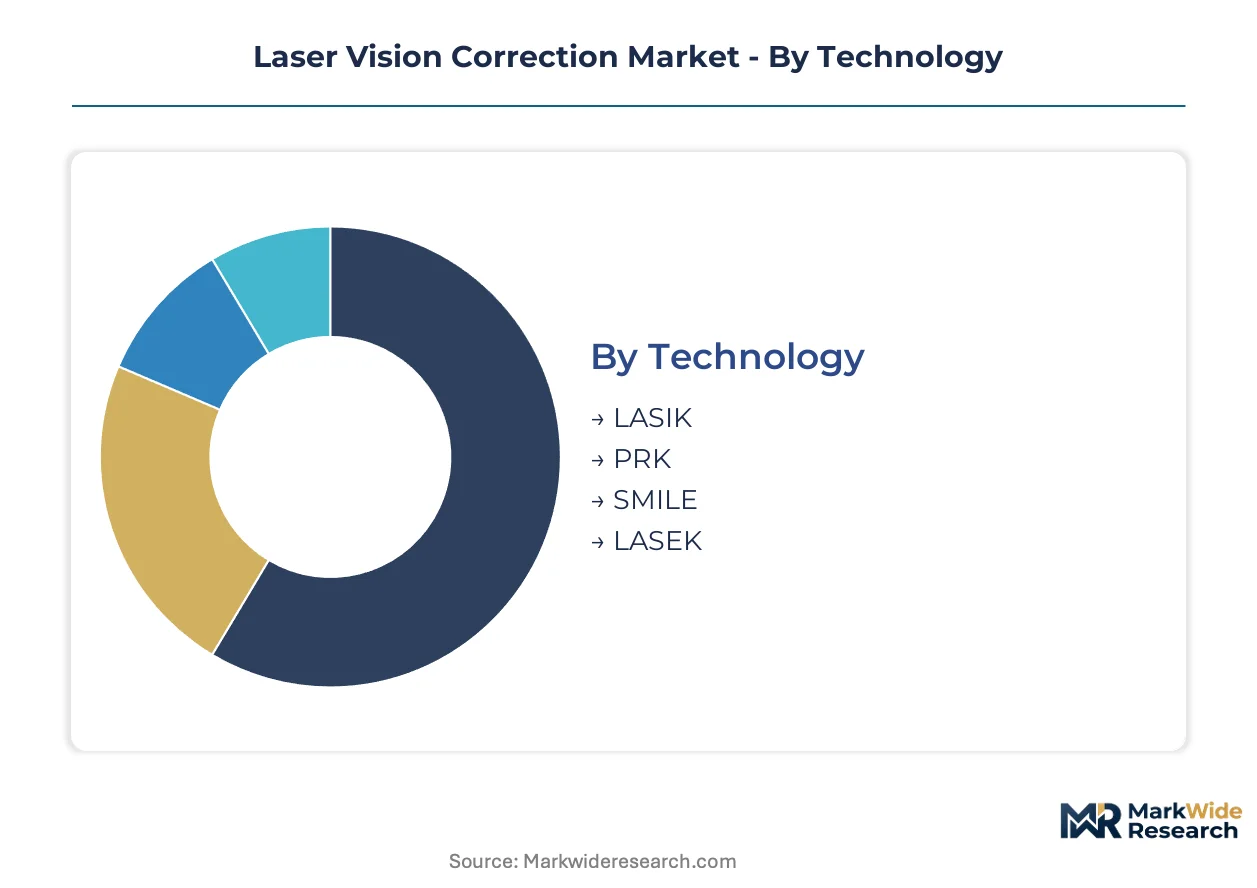
Segmentation in laser vision correction reveals how technology choices, care settings, and equipment investments concentrate margin pools. Understanding these divisions helps stakeholders identify where capital deployment yields highest returns.
Technology:
Mature platforms dominate procedural volume while emerging techniques reshape clinical standards.
- LASIK:Flap-based excimer ablation remains the most performed refractive procedure worldwide. Demand concentrates in United States outpatient surgical centers where femtosecond laser flap creation has displaced mechanical microkeratomes.
- PRK:Surface ablation without flap creation serves patients with thin corneas or occupational trauma risk. Germany's reimbursement frameworks support PRK for military and aviation candidates excluded from LASIK protocols.
- SMILE:Flapless single-incision lenticule extraction preserves corneal biomechanical integrity. China drives adoption through NMPA-accelerated domestic platform approvals.
- LASEK:Epithelial flap variant combines PRK safety with faster visual recovery. Secondary markets deploy LASEK where excimer laser access exceeds femtosecond platform availability.
LASIK handles the majority of throughput; SMILE is expanding most quickly on share.
End User:
Cost tier differentiation separates capital-intensive settings from leaner delivery models.
- Hospitals:Academic medical centers combine refractive surgery with corneal transplantation and complex anterior segment reconstruction. China's tier-one cities concentrate hospital-based laser platforms serving high-myopia cases with comorbidities.
- Clinics:Dedicated ambulatory facilities optimize throughput through dedicated excimer laser suites. United States multi-site networks achieve scale economies in consumable purchasing and maintenance contracts.
- Ophthalmology Practices:Solo and group practices integrate diagnostic imaging with surgical scheduling. Germany's private practice density supports premium technology adoption through direct patient payment models.
- Mobile Surgical Units:Transportable laser platforms extend access to underserved regions. China's tier-two and tier-three cities present deployment opportunities where fixed infrastructure remains sparse.
Clinics generate the highest revenue concentration; mobile surgical units are gaining share fastest.
Procedure Type:
Application focus distinguishes one-time corrections from recurring service revenue.
- Refractive Surgery:Primary LASIK, PRK, and SMILE procedures address myopia, hyperopia, and astigmatism. Young adult demographics in China and the United States sustain volume concentration.
- Enhancement Procedures:Secondary ablations correct residual refractive error or regression. Reimbursement band compression in Germany and selective United States commercial payers limits revenue contribution.
- Vision Therapy:Non-surgical interventions address accommodative dysfunction and convergence insufficiency. Pediatric ophthalmology practices bundle therapy with refractive screening.
- Follow-up Care:Post-operative monitoring generates recurring encounters through enhancement warranty programs. Outpatient surgical centers capture margin concentration by bundling follow-up into global surgical fees.
Refractive surgery commands the dominant share; enhancement procedures face steepest reimbursement pressure.
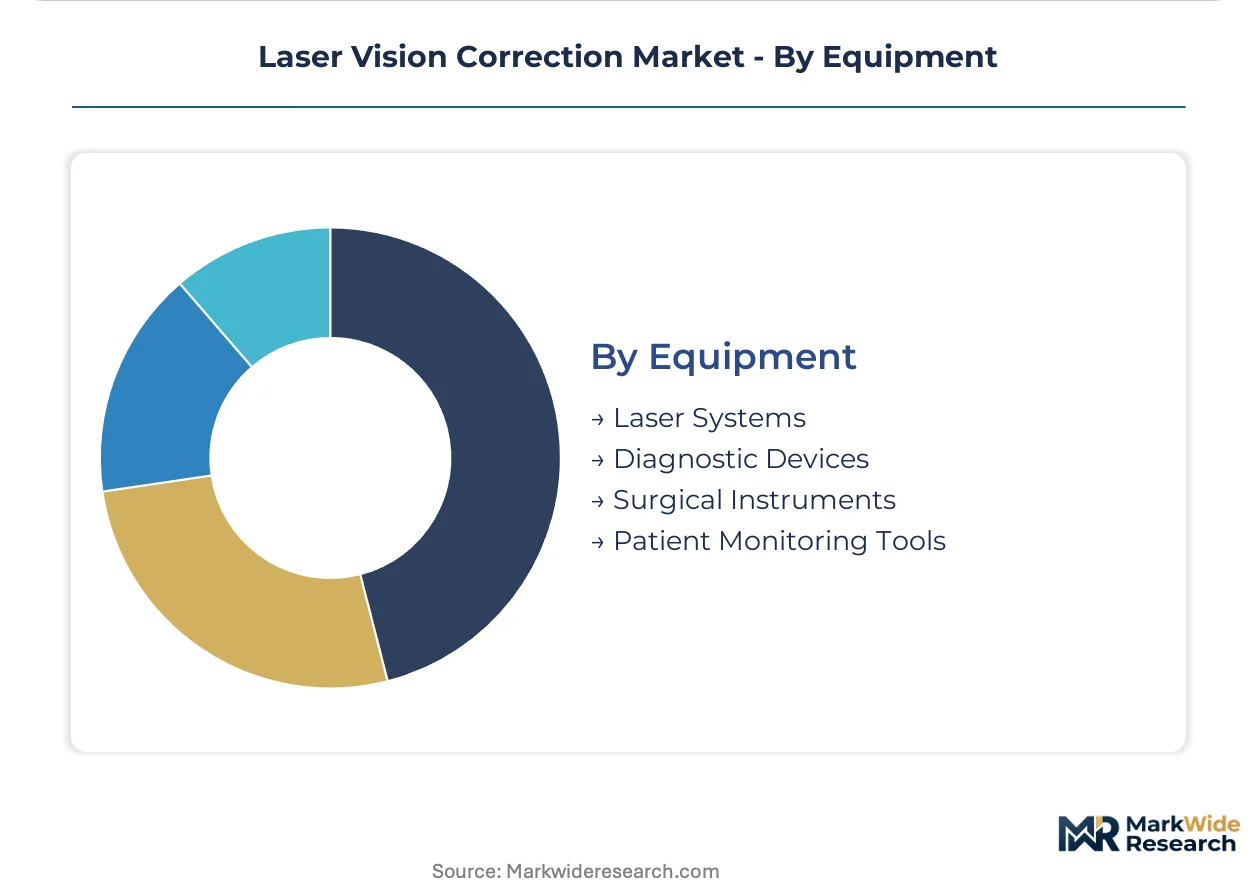
Equipment:
Supply concentration favors integrated platform vendors over component specialists.
- Laser Systems:Excimer and femtosecond platforms constitute the capital core of refractive surgery suites. Equipment refresh cycles concentrate purchasing power among United States multi-site surgical networks.
- Diagnostic Devices:Wavefront aberrometers and corneal topographers enable treatment planning. Interoperability gaps between legacy diagnostic systems and contemporary laser platforms create workflow fragmentation.
- Surgical Instruments:Microkeratomes, speculums, and suction rings support procedural execution. Declining mechanical flap creation has compressed microkeratome demand.
- Patient Monitoring Tools:Intraoperative aberrometry and post-operative topography track outcomes. Software licensing models for biomechanical modeling create recurring revenue streams distinct from capital sales.
Laser systems absorb the largest capital allocation; diagnostic devices show the steepest technology turnover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German laser platform manufacturers export femtosecond systems to outpatient surgical networks across the United States and China. Equipment trade flows concentrate capital expenditure in these three markets, where procedure volumes and reimbursement frameworks sustain premium technology adoption.
United States
Young adult myopia correction drives procedure volumes in dedicated ambulatory surgery centers. FDA PMA pathways for excimer laser approvals and 510(k) clearances for femtosecond platforms govern commercialization. Multi-site surgical networks in California and Texas concentrate purchasing power for platform refresh cycles.
China
High myopia prevalence among urban 18-35 year-olds sustains primary correction demand in tier-one cities. NMPA accelerates review timelines for domestically manufactured laser platforms under innovative medical device priority pathways. Shanghai and Beijing hospital systems combine refractive surgery with complex anterior segment reconstruction for high-myopia cases.
Germany
Advanced reimbursement frameworks support premium femtosecond and SMILE technology uptake in private ophthalmology practices. EU MDR intensifies clinical evidence requirements for new ablation algorithms seeking CE marking. Bavaria and Baden-Württemberg concentrate diagnostic-to-surgical system integration capabilities.
Japan
Aging demographics and high myopia rates sustain demand for both primary corrections and enhancement procedures. PMDA oversight of excimer laser approvals maintains rigorous clinical evidence standards. Tokyo and Osaka metropolitan areas concentrate fellowship-trained refractive surgeons and high-volume clinic networks.
South Korea
Cosmetic-conscious young adult populations drive adoption of flapless SMILE protocols in Seoul Capital Area clinics. MFDS regulates laser platform approvals with emphasis on optical safety validation. Busan-Ulsan region emerges as secondary hub for mobile surgical unit deployment to underserved markets.
Laser Vision Correction Market Competitive Environment
Channel-controlling players compete with product-specialist players across three discernible tiers. The vendor base consolidates around integrated platform ecosystems capable of bundling diagnostic imaging, surgical execution, and post-operative monitoring. Archetypes include diversified ophthalmic conglomerates with full-suite portfolios, precision laser specialists with proprietary ablation technologies, and regional surgical service chains with captive equipment demand. Dominant competitive moves center on strategic partnerships between equipment manufacturers and multi-site surgical networks, plus technology licensing arrangements that monetize software-enabled treatment planning.
Among diversified ophthalmic conglomerates, Alcon Inc. and Johnson & Johnson Vision exemplify full-suite platform strategies spanning diagnostic devices through surgical lasers. ZEISS occupies a distinct position within the precision laser specialist tier, anchoring flapless refractive technology development. NIDEK CO., LTD. represents the integrated diagnostic-to-surgical system archetype, while Ziemer Ophthalmic Systems AG sits within the femtosecond laser specialist category. TLC Vision exemplifies the regional surgical service chain model with concentrated United States market presence. These named entities illustrate competitive positioning without exhaustively cataloging strategic actions or financial performance.
| Leading Market Players |
|---|
| NIDEK CO., LTD. |
| Bausch + Lomb |
| Johnson & Johnson Vision |
| Excelsius Medical |
| Abbott |
| Alcon Inc. |
| Ziemer Ophthalmic Systems AG |
| TLC Vision |
| ZEISS |
| Others |
Value Chain & Pricing Dynamics
German and Swiss femtosecond laser manufacturers concentrate precision optics manufacturing, anchoring margin capture downstream at United States multi-site surgical networks and China's tier-one hospital systems. This upstream equipment concentration translates into pricing power for integrated platform vendors while compressing margin pools for independent ophthalmology practices locked into maintenance contracts and consumable excimer gas supply chains.
Pricing Analysis
Next-generation SMILE platforms command substantial premiums over prior-generation mechanical microkeratome systems and current-generation femtosecond-LASIK configurations. Three-tier pricing structure across premium, standard, and economy levels reflects FDA PMA tier, excimer laser wavelength precision, and bundled diagnostic-to-surgical software integration. Pricing pressure stems from NMPA-accelerated domestic Chinese platform approvals expanding accessible supply. Multi-site surgical networks exhibit lowest price sensitivity due to volume-scale purchasing power, while independent solo practices face acute cost compression from capital equipment refresh cycles.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from German equipment manufacturers enable United States outpatient surgical networks to absorb femtosecond platform migration costs. Manufacturing concentrates in Germany, Switzerland, and Japan for precision laser optics, while excimer laser consumables draw from specialized gas suppliers in the United States and Germany. Single-source vulnerability persists for femtosecond laser cavity components and excimer gas purification systems. Distribution runs through direct manufacturer-to-hospital contracts in China, multi-site network purchasing consortia in the United States, and specialized ophthalmic equipment distributors serving European private practices.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser vision correction is recovering from cyclical capital expenditure compression as young adult myopia prevalence in China and the United States drives procedure volume expansion. Equipment refresh cycles and SMILE protocol adoption create differentiated recovery trajectories across vendor tiers.
For Market Incumbents: Build software-enabled ecosystem moats by integrating biomechanical modeling licensing with diagnostic-to-surgical platform bundles. Deepen backward integration into excimer gas supply chains to offset consumable cost pressure. Defend against NMPA-accelerated Chinese domestic manufacturers through FDA PMA pathway prioritization and proprietary ablation algorithm patent estates. For New Entrants and Emerging Players: Pursue telemedicine-enabled screening white-space in China's tier-two cities where fixed laser infrastructure remains sparse. Target mobile surgical unit deployment partnerships with regional hospital networks in South Korea's Busan-Ulsan corridor. Leverage digital direct-to-consumer patient acquisition channels to bypass established optometrist-referral networks. For Investors and Strategic Acquirers: Capital is best deployed toward precision laser specialists with proprietary flapless technology and established CE marking under EU MDR. Long-term viability over the mid-decade horizon rests on software recurring revenue models decoupled from capital equipment cyclicality. Monitor NMPA approval velocity for domestic Chinese platforms as inflection indicator for global pricing pressure intensity.| Strategic Initiative | Industry Significance |
|---|---|
| SMILE Platform Expansion | Flapless protocols reduce dry eye incidence and preserve corneal biomechanical strength for ZEISS and competing vendors. |
| Diagnostic Integration Partnership | Wavefront aberrometer-to-laser data seamlessness addresses workflow fragmentation for NIDEK and Alcon system architectures. |
| Reimbursement Strategy Development | Enhancement procedure banding differentiation in Germany and selective United States payers protects revision revenue streams. |
| Telemedicine Screening Deployment | Remote corneal topography extends geographic access for China's tier-two city demand pools beyond fixed infrastructure constraints. |
| Biomechanical Modeling Licensing | Finite element analysis software creates recurring revenue distinct from capital equipment sales for platform vendors. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with refractive surgeons, ophthalmology practice administrators, hospital purchasing committee members, and femtosecond laser platform engineers. Secondary validation drew from FDA PMA filings, NMPA innovative medical device priority pathway disclosures, EU MDR CE marking databases, and hospital procurement contract repositories. Bottom-up procedure volume estimates triangulated against top-down equipment installation base and utilization rate assumptions.
Calibration against historical platform refresh cycles and regulatory approval timelines anchored projections across the analysis window. Segmentation dimensions modeled include technology generation, end-user facility type, procedure category, and equipment component tier. CAGRs were derived from equipment shipment data, procedure volume surveys, and pricing trend analysis. Forecast inputs incorporated NMPA approval velocity, EU MDR clinical evidence requirement intensity, and young adult myopia prevalence trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by NMPA-accelerated Chinese domestic manufacturers or rapid SMILE protocol share gains would shift outcomes materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Lasers Therapeutic Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
Aesthetic Ophthalmology Device Market
Ophthalmology
Fungal Eye Infection Market
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Retinoblastoma Treatment Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Keratoconus Treatment Market
Ophthalmology
Astigmatism Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Nystagmus Market
Ophthalmology
Meibomian Gland Dysfunction Treatment Market