
 Eye Allergy Treatment Market | 2026-2036
Eye Allergy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Allergy Treatment Market Analysis
India is tilting toward contract manufacturing of active pharmaceutical ingredients for ophthalmic formulations. Alcon leverages its vertically integrated supply chain for antihistamine eye drops across North American retail channels. Santen Pharmaceutical anchors its position in Asia through specialized R&D on mast cell stabilizer formulations. Pfizer competes on manufacturing scale for multi-ingredient combination therapies.
Eye allergy treatment encompasses pharmacological interventions designed to interrupt histamine-mediated inflammatory cascades in the conjunctival mucosa, typically formulated with pH-buffered aqueous vehicles at osmolarity matching human tear film to prevent corneal epithelial disruption. These products serve to relieve pruritus, erythema, and chemosis while preventing secondary complications in chronic allergic conjunctivitis. Antihistamines dominate current prescription volumes due to rapid onset of action, though mast cell stabilizers represent the fastest-expanding category as allergists emphasize prophylactic regimens. Ophthalmic solutions command the largest share of delivery mode revenue, while online pharmacies emerge as the highest-growth distribution channel driven by subscription refill models and telehealth prescribing.
The FDA oversees ophthalmic drug safety through its Division of Ophthalmology and Ear, Nose, and Throat within the Center for Drug Evaluation and Research, requiring stringent sterility validation and preservative toxicology data for topical ocular products. EMA's MDR framework and REACH chemical registration obligations in Europe impose additional formulation disclosure requirements that shape multinational product registration strategies. Stakeholders must monitor evolving regulatory divergence between preservative-free mandates in the European Union and the United States' risk-based approach to benzalkonium chloride thresholds, as this split will determine regional manufacturing configuration and portfolio prioritization.
Market Dynamics
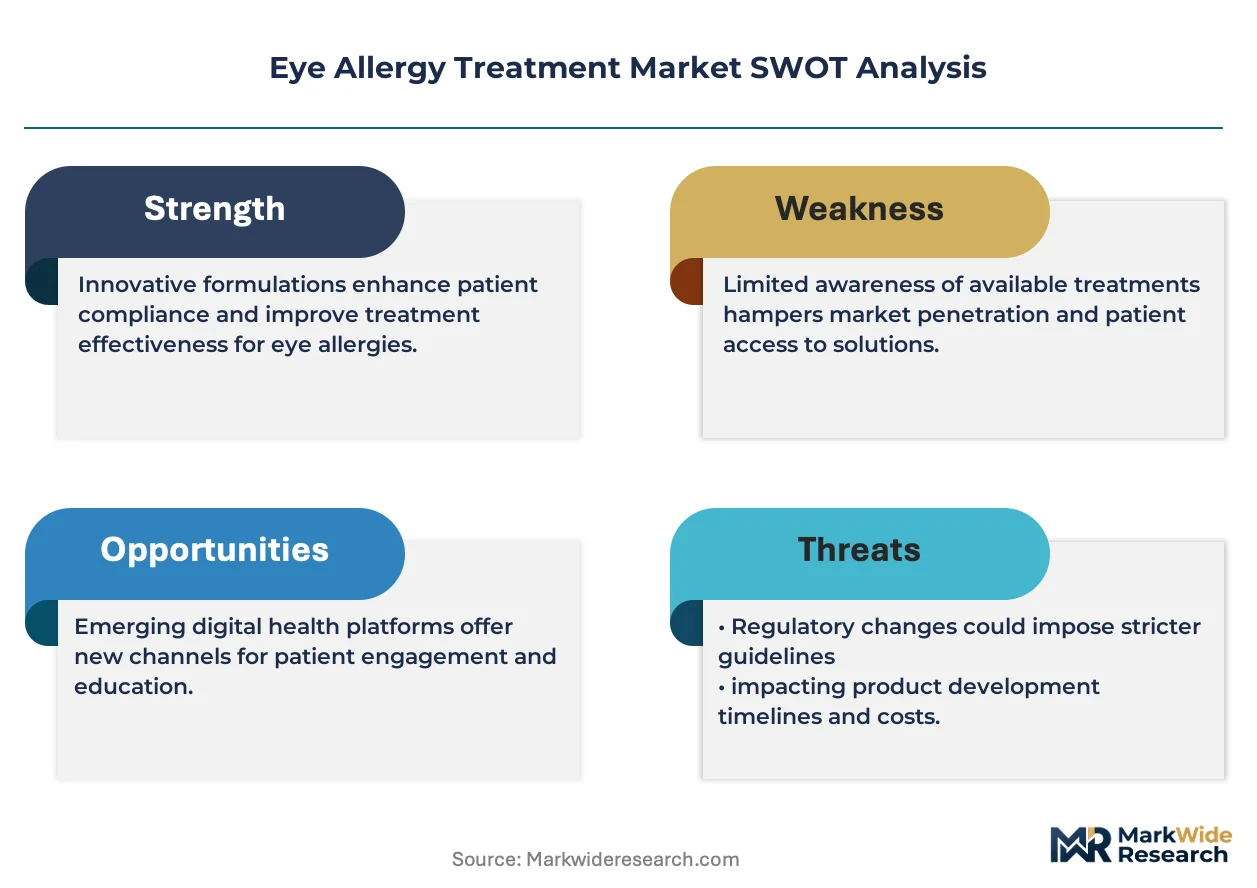
FDA's tightened guidance on topical ophthalmic corticosteroid safety is forcing manufacturers to reallocate R&D budgets toward preservative-free antihistamine formulations and mast cell stabilizer combinations, compressing development timelines for legacy steroid-dependent portfolios.
Growth Catalysts
- Pediatric ophthalmology clinic expansion:Specialized pediatric eye care facilities across the United States are standardizing preservative-free drop protocols for chronic allergic conjunctivitis management in children.
- EMA MDR framework:Europe's stringent sterility validation requirements for topical ocular products are accelerating adoption of single-use vial formats that eliminate benzalkonium chloride exposure.
- Telehealth prescribing:Digital health platforms are embedding ophthalmology consultations into subscription refill models for antihistamine eye drops.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for ophthalmic antihistamines clusters in Indian contract manufacturers, creating single-source vulnerability for Western formulators.
- Preservative toxicology costs:REACH chemical registration obligations in Europe impose disclosure burdens that inflate regulatory compliance spend for multi-market portfolios.
- Generic ketotifen saturation:Patent-expired mast cell stabilizers flood retail channels, compressing branded pricing power for novel combination therapies.
Strategic Opportunities
- Subscription pharmacy models:Online pharmacies in the United States are capturing recurring revenue through automated refill algorithms tied to seasonal pollen forecasting.
- Dual-acting formulation R&D:Convergence of antihistamine and mast cell stabilizer mechanisms into single-drop solutions addresses allergist preference for simplified prophylactic regimens.
- Asian market underpenetration:Japan's PMDA pathway for preservative-free ophthalmics remains less crowded than FDA routes, offering first-mover positioning for specialized entrants.
Industry Challenges
- Sterility validation timelines:FDA Division of Ophthalmology review cycles for novel aqueous vehicle formulations extend commercialization windows by 12-18 months versus reformulation approvals.
- Osmolarity matching complexity:pH-buffered formulations must precisely mirror human tear film parameters to prevent corneal epithelial disruption, requiring specialized biopharmaceutical expertise scarce in generic manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Allergy Treatment Market |
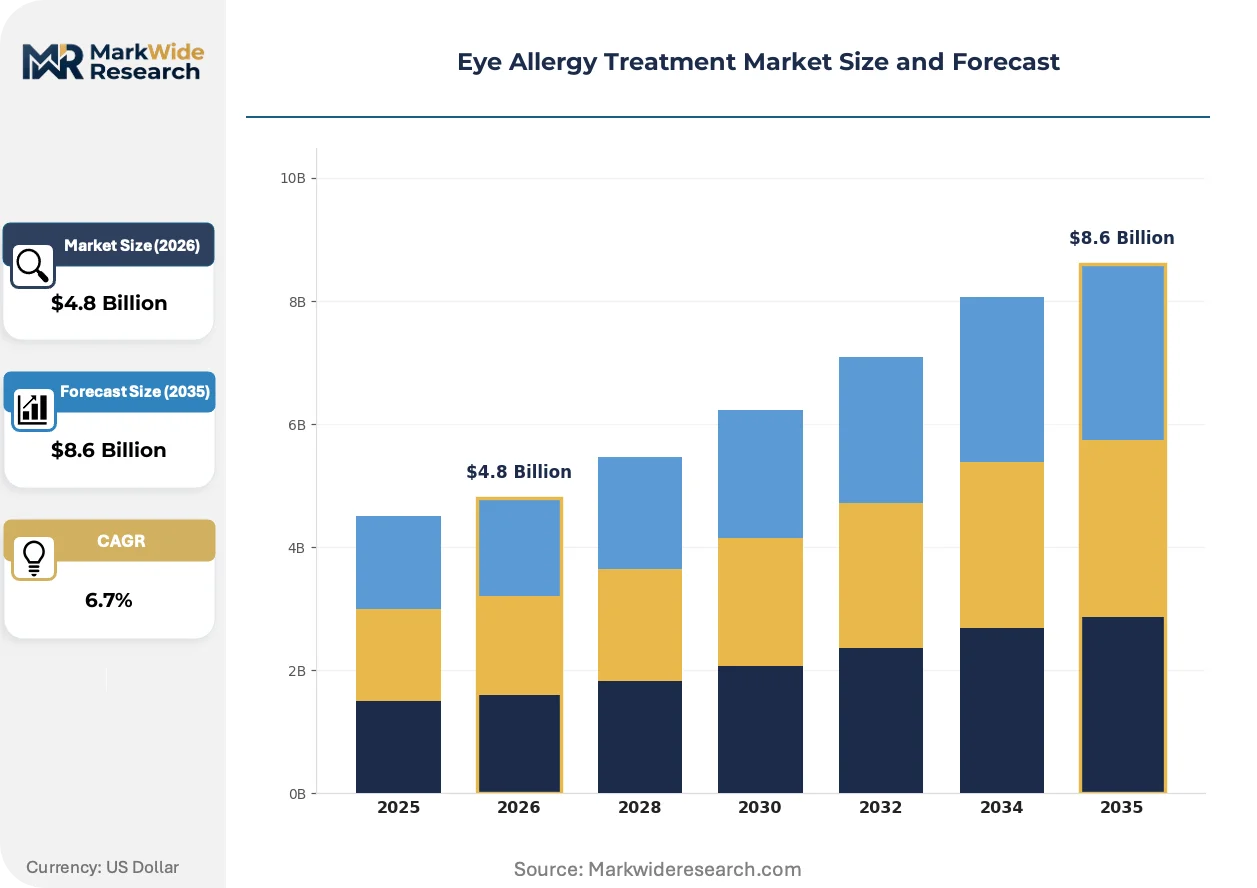
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Decongestants, Mast Cell Stabilizers, Corticosteroids Delivery Mode: Topical, Oral, Injectable, Ophthalmic Solutions End User: Retail Pharmacies, Hospitals, Clinics, Online Pharmacies Application: Seasonal Allergies, Perennial Allergies, Allergic Conjunctivitis, Others |
| Companies Covered | Alcon, Santen Pharmaceutical, Allergan (AbbVie), Pfizer, Sun Pharmaceutical Industries, Bausch Health Companies, Johnson & Johnson, Regeneron Pharmaceuticals, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Allergy Treatment Market Emerging Trajectories
Formulation science and distribution infrastructure are undergoing parallel transformation as preservative-free technologies mature and direct-to-consumer channels capture prescription volume previously routed through traditional pharmacy networks.
Single-use polymer vial technology is rendering obsolete multi-dose bottles dependent on benzalkonium chloride preservation. Pediatric ophthalmology clinics in the United States are adopting these units at accelerating pace to eliminate cumulative preservative toxicity in chronic users. This shift is compressing manufacturing economics toward high-speed aseptic filling lines capable of unit-dose scale.
REACH chemical registration obligations in Europe now mandate full formulation disclosure for ophthalmic preservatives, creating competitive friction for manufacturers with undisclosed vehicle compositions. Formulators are responding by developing entirely preservative-free portfolios that bypass disclosure requirements. Multi-ingredient combination therapies face the steepest reformulation burden under this framework.
Subscription-based pharmacy platforms are disintermediating traditional retail dispensing for maintenance antihistamine regimens. Allergists in pollen-heavy United States regions are directing patients toward telehealth-integrated refill services that synchronize drop delivery with forecasted symptom peaks. This behavioral shift concentrates patient data with platform operators, altering prescriber-pharmacist relationships.
Eye Allergy Treatment Market Segmentation
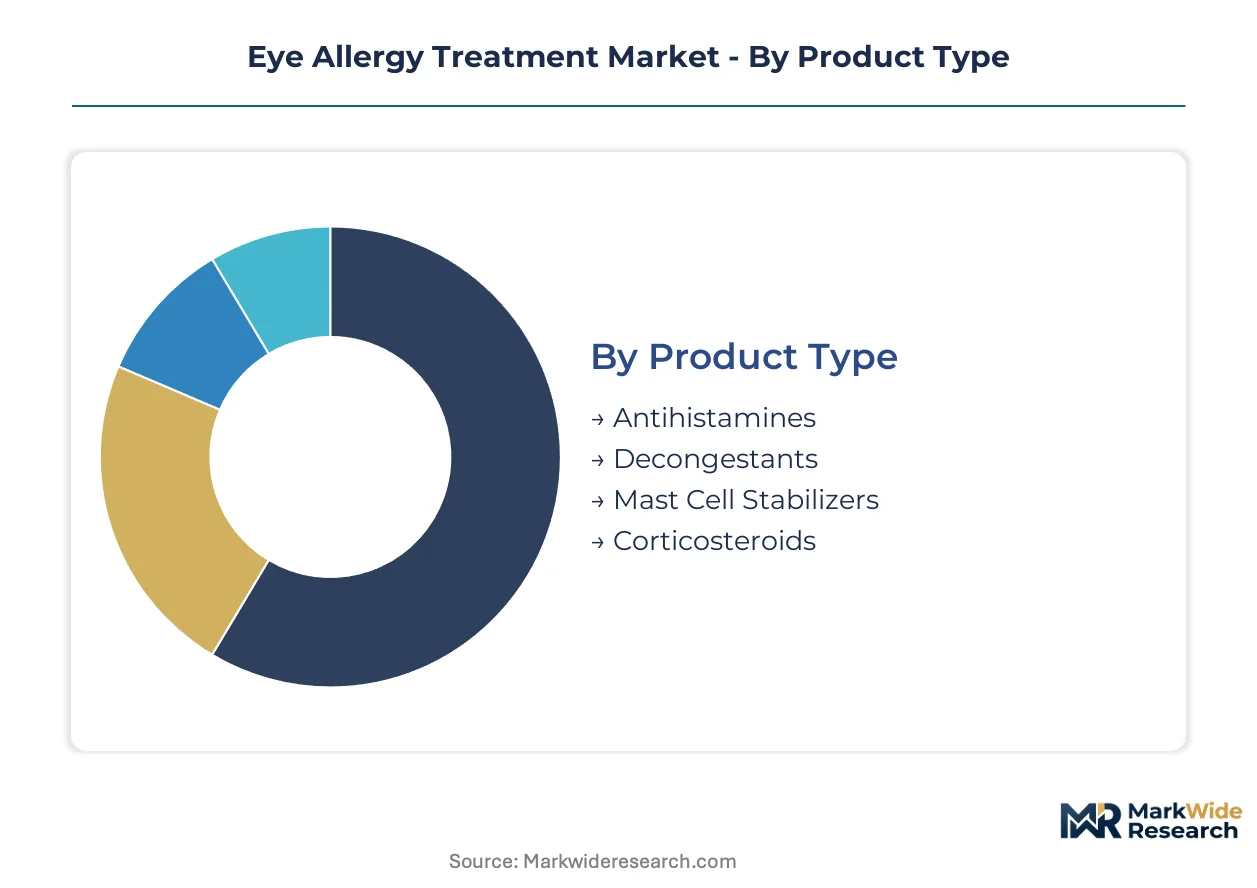
Segmentation in eye allergy treatment reveals how formulation science, delivery technology, and distribution infrastructure align with distinct patient pathways. Each category exposes different margin structures and regulatory burdens that determine portfolio prioritization for manufacturers.
Product Type:
Use-case spectrum spans acute symptom relief through chronic prophylaxis, with mechanism of action dictating prescription setting and reimbursement tier.
- Antihistamines:H1-receptor antagonists formulated as topical drops deliver rapid pruritus relief within minutes of instillation. Demand concentrates in United States retail settings where direct-to-consumer advertising drives patient self-identification and physician request patterns. Seasonal pollen burden in southeastern states generates concentrated prescription volume during spring peaks.
- Mast Cell Stabilizers:Cromolyn sodium and lodoxamide derivatives prevent degranulation rather than block histamine post-release, requiring 2-4 week loading periods before therapeutic effect. Pediatric ophthalmology clinics favor these for chronic allergic conjunctivitis management in children to avoid corticosteroid exposure. Prophylactic regimens are expanding fastest among allergists seeking to reduce acute flare dependency.
- Decongestants:Alpha-adrenergic agonists reduce hyperemia through vasoconstriction.
- Corticosteroids:Potent anti-inflammatory agents restricted to severe refractory cases due to IOP elevation risk.
Established volume favors Antihistamines; emerging adoption favors Mast Cell Stabilizers.
Delivery Mode:
Cost tier stratification separates commodity oral generics from premium-priced ophthalmic formulations requiring specialized manufacturing infrastructure.
- Ophthalmic Solutions:Aqueous vehicles buffered to pH 7.4 with osmolarity matched to tear film prevent corneal epithelial disruption during chronic use. United States demand concentrates in preservative-free unit-dose formats as FDA guidance tightens on benzalkonium chloride toxicology. High-speed aseptic filling lines command capital investment barriers that protect margin structures.
- Topical:Non-ocular dermal and nasal formulations for adjacent allergy symptom management.
- Oral:Systemic antihistamines with ocular side effect profiles limiting dedicated eye allergy use.
- Injectable:Biologic agents for severe atopic conditions with ocular involvement.
Volume concentration sits with Ophthalmic Solutions; steepest expansion trajectory belongs to preservative-free topical innovations.
End User:
Customer type determines fulfillment speed requirements and regulatory compliance intensity, from hospital sterility protocols to direct-to-consumer subscription logistics.
- Online Pharmacies:Digital platforms embed automated refill algorithms synchronized with pollen forecasting services in pollen-heavy United States regions. Telehealth prescribing integrations capture patient data that alters traditional prescriber-pharmacist relationships. Subscription models generate recurring revenue with lower acquisition costs than retail channels.
- Retail Pharmacies:Community dispensing maintains dominance in acute symptom onset scenarios requiring same-day fulfillment.
- Hospitals:Emergency department and inpatient settings for severe allergic reactions with ocular complications.
- Clinics:Specialized ophthalmology and allergy practices driving protocol standardization for chronic management.
Transaction volume remains with Retail Pharmacies; patient data capture and retention economics favor Online Pharmacies.
Application:
Geography and seasonality create distinct demand pulses that inventory and manufacturing must anticipate.
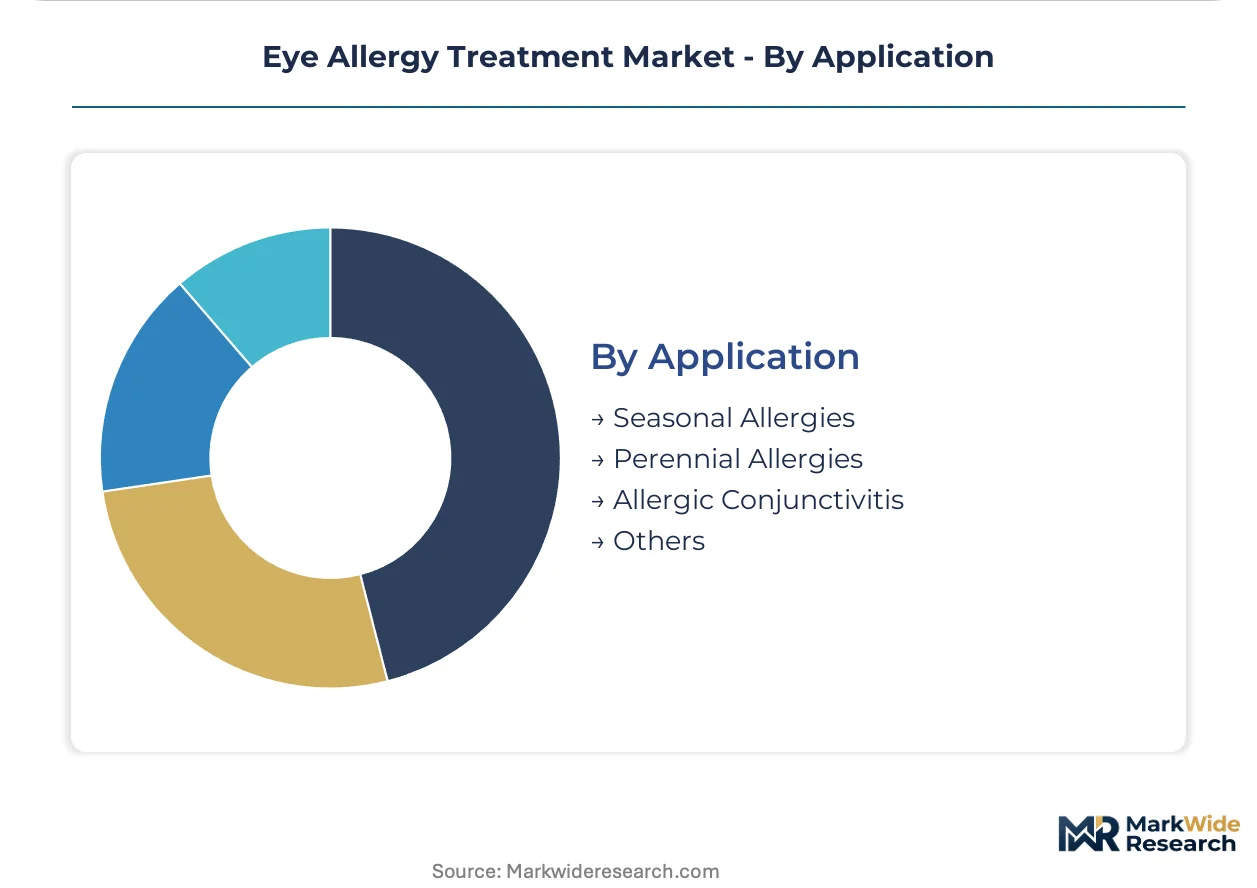
- Seasonal Allergies:Pollen-driven rhinoconjunctivitis generates predictable demand spikes requiring flexible manufacturing capacity. United States southeastern and midwestern regions concentrate prescription volume March through June. Forecasting services enable pre-positioning inventory to retail and online channels before symptom onset.
- Allergic Conjunctivitis:Isolated ocular inflammation without nasal symptoms presents distinct diagnostic and treatment pathways.
- Perennial Allergies:Dust mite, pet dander, and mold triggers create year-round demand with lower amplitude but higher chronicity.
- Others:Contact lens-associated giant papillary conjunctivitis and vernal keratoconjunctivitis variants.
Peak revenue intensity clusters in Seasonal Allergies; prescription stability and compliance rates are strongest in Perennial Allergies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of ophthalmic drug safety anchors United States market dynamics, while divergent preservative regulations across Europe and Asia create distinct commercialization pathways for multinational formulators.
United States
Seasonal pollen burden in southeastern states generates concentrated prescription volume during spring peaks. FDA's Division of Ophthalmology mandates stringent sterility validation for novel aqueous vehicle formulations. Pediatric ophthalmology clinics in Atlanta and Dallas are standardizing preservative-free drop protocols for chronic allergic conjunctivitis management in children.
Germany
REACH chemical registration obligations impose full formulation disclosure requirements for ophthalmic preservatives. EMA's MDR framework accelerates adoption of single-use vial formats that eliminate benzalkonium chloride exposure. Manufacturing clusters in Baden-Württemberg specialize in high-speed aseptic filling lines for unit-dose scale production.
Japan
PMDA pathway for preservative-free ophthalmics remains less crowded than FDA routes, offering first-mover positioning for specialized entrants. METI standards on pharmaceutical manufacturing quality align with domestic preferences for advanced formulation technologies. Tokyo-based R&D facilities anchor Santen Pharmaceutical's specialized work on mast cell stabilizer formulations.
India
Contract manufacturing of active pharmaceutical ingredients for ophthalmic formulations clusters in Hyderabad and Ahmedabad. CDSCO regulatory pathways for ophthalmic generics create export-oriented production economics. Indian formulators supply Western markets with ketotifen API despite single-source vulnerability concerns.
United Kingdom
Telehealth prescribing integrations capture patient data that alters traditional prescriber-pharmacist relationships. MHRA post-Brexit regulatory divergence from EMA creates parallel registration requirements for preservative-free portfolios. London-based digital health platforms embed ophthalmology consultations into subscription refill models for antihistamine eye drops.
Eye Allergy Treatment Market Vendor Landscape
Vertically integrated multinationals and specialized ophthalmic developers split the market between scale-driven manufacturing and formulation innovation. The competitive structure favors players with captive API supply or proprietary delivery technology. Two archetypes dominate: diversified pharmaceutical conglomerates leveraging manufacturing scale, and eye-care specialists concentrating R&D on preservative-free mechanisms. Competitive moves center on backward integration into API production and geographic expansion through localized regulatory approvals.
Among diversified pharmaceutical conglomerates, Pfizer and Novartis AG exemplify scale-driven positioning through multi-ingredient combination therapy portfolios. Alcon anchors the eye-care specialist archetype with vertically integrated supply chain control over antihistamine drop distribution across North American retail channels. Sun Pharmaceutical Industries occupies a position bridging both archetypes through contract manufacturing scale and emerging market penetration.
| Leading Market Players |
|---|
| Alcon |
| Santen Pharmaceutical |
| Allergan (AbbVie) |
| Pfizer |
| Sun Pharmaceutical Industries |
| Bausch Health Companies |
| Johnson & Johnson |
| Regeneron Pharmaceuticals |
| Novartis AG |
| Others |
Supply Flow & Price Mechanics
Indian API manufacturing clusters for ophthalmic antihistamines concentrate upstream supply leverage, directing margin capture toward Western formulators with captive filling capacity and preservative-free unit-dose technology. Pricing power downstream rests on sterility validation capabilities and single-use polymer vial formats that command premium positioning in pediatric and chronic use segments.
Pricing Analysis
Geographic price spreads between North American retail channels and European hospital procurement diverge sharply, with United States direct-to-consumer advertising sustaining branded antihistamine premiums against EMA MDR-driven generic substitution in Germany. Three-tier pricing structure across preservative-free premium, benzalkonium chloride-preserved standard, and contract-manufactured economy levels segments buyer archetypes. Pricing pressure stems from ketotifen API commoditization flooding retail channels. Hospital procurement committees exhibit highest price sensitivity; specialized pediatric ophthalmology clinics demonstrate lowest sensitivity due to protocol-driven formulary adherence.
Supply Chain Analysis
Export-control regimes on pharmaceutical manufacturing equipment limit aseptic filling line proliferation, constraining capacity expansion for preservative-free ophthalmic formulations. Active pharmaceutical ingredient production clusters in India and China, with specialized polymer vial manufacturing anchored in Germany and Japan. Supply chain risk centers on single-source ketotifen API dependency from Hyderabad contract manufacturers. Distribution runs through vertically integrated multinational wholesalers controlling North American retail pharmacy networks alongside direct-to-consumer subscription platforms capturing recurring refill volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase driven by seasonal pollen burden intensification in southeastern United States regions, which resynchronizes prescription volume peaks with manufacturing capacity planning cycles.
For Market Incumbents: Insulate formulation portfolios from FDA corticosteroid safety tightening by accelerating preservative-free antihistamine R&D and securing captive API supply through backward integration into Indian contract manufacturing relationships. Sterility validation bottlenecks at the FDA Division of Ophthalmology represent the primary regulatory threat requiring pre-submission engagement protocols.
For New Entrants and Emerging Players: Japan's PMDA pathway for preservative-free ophthalmics represents the most penetrable entry point, offering first-mover positioning with reduced competitive congestion versus FDA routes. Pediatric ophthalmology clinic protocols in the United States present a secondary white-space target for mast cell stabilizer combination therapies. Telehealth-integrated subscription pharmacy partnerships provide the optimal go-to-market angle for patient data capture and retention economics.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ophthalmic specialty developers possessing unit-dose manufacturing infrastructure but lacking global regulatory filing capabilities. Long-term viability over a five-to-ten year horizon hinges on portfolio migration toward prophylactic mast cell stabilizer regimens and away from acute antihistamine commoditization. Monitor FDA guidance publication timelines on benzalkonium chloride thresholds as the critical inflection signal for preservative-free manufacturing asset valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Formulation R&D | FDA Division of Ophthalmology guidance on benzalkonium chloride toxicology accelerates category migration toward single-use vial formats. |
| API Backward Integration | Captive ketotifen supply from Indian contract manufacturers mitigates single-source vulnerability and secures margin control. |
| Telehealth Platform Partnership | Subscription refill algorithms synchronized with pollen forecasting services alter traditional prescriber-pharmacist data relationships. |
| EMA MDR Compliance Investment | REACH chemical registration disclosure requirements for European market access impose reformulation burdens on multi-ingredient portfolios. |
| Pediatric Protocol Standardization | Atlanta and Dallas pediatric ophthalmology clinic adoption of preservative-free drop protocols creates reference site influence for national formulary expansion. |
Methodological Framework
Cross-validation between primary interviews with ophthalmic drug development executives, regulatory affairs leads at multinational formulators, pediatric ophthalmology clinic directors, and hospital pharmacy procurement managers anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, EMA centralized procedure submissions, ClinicalTrials.gov ophthalmology trial registries, and United States pollen forecasting service data. Bottom-up prescription volume modeling triangulates against top-down market sizing from wholesaler distribution records.
Calibration against historical antihistamine and mast cell stabilizer prescription patterns across the analysis window employs segmented modeling by product mechanism, delivery mode, end-user channel, and application seasonality. CAGRs derive from elasticity-adjusted volume projections incorporating allergist prescribing behavior shifts and telehealth platform penetration curves. Industry-specific forecast inputs include FDA review cycle duration assumptions for novel aqueous vehicle formulations and REACH chemical registration compliance cost trajectories.
Practitioners should monitor FDA guidance publication timelines, EMA MDR enforcement intensity, and Indian API export policy shifts for early signals of forecast revision requirements. Material shifts in seasonal pollen burden patterns or breakthrough biologic therapy approvals for allergic conjunctivitis would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Fungal Eye Infection Market
Ophthalmology
Retinal Detachment Diagnostic Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Global Ophthalmic Sutures Market
Ophthalmology
North America Vision Care Market
Ophthalmology
Synoptophore Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Global Therapeutic Lenses Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Global Automated Ophthalmic Perimeters Market
Ophthalmology
Leber Congenital Amaurosis Market