
 Macular Edema Treatment Market | 2026-2036
Macular Edema Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Macular Edema Treatment Market Intelligence
Project finance for sustained-release implant manufacturing is tilting competitive dynamics toward asset-light biotech platforms. Novartis AG leverages its ophthalmology infrastructure to anchor European distribution for corticosteroid implants. Regeneron Pharmaceuticals sustains R&D intensity through captive antibody production, while Roche Holding AG dominates anti-VEGF biosimilar defense via Genentech's manufacturing scale.
Macular edema treatment encompasses pharmacological and procedural interventions targeting fluid accumulation in the macula's intraretinal or subretinal spaces, with anti-VEGF agents like ranibizumab and aflibercept binding vascular endothelial growth factor-A to reduce vascular permeability. These therapies preserve central visual acuity in patients with diabetic retinopathy, retinal vein occlusion, and postoperative inflammation. Anti-VEGF injections command the largest revenue pool among product types due to chronic retreatment requirements, while sustained-release implants represent the fastest-expanding segment as physicians seek to reduce injection burden. Diabetic macular edema applications absorb the majority of clinical volume, though uveitic macular edema offers higher per-patient margins given smaller treatable populations and limited therapeutic alternatives.
FDA ophthalmology division review timelines and EMA's MDR conformity requirements for intraocular delivery devices govern market access trajectories for new entrants. Reimbursement coding decisions by CMS in the United States and NICE technology appraisals in the United Kingdom directly shape physician prescribing economics across delivery modes. Stakeholders must monitor biosimilar anti-VEGF litigation outcomes and sustained-release implant durability data as these will determine whether manufacturing scale or formulation innovation becomes the decisive competitive advantage.
Market Dynamics
Anti-VEGF injection burden is driving physician preference toward sustained-release corticosteroid implants, compressing retreatment economics and reshaping manufacturing investment priorities across ophthalmology supply chains.
Growth Catalysts
- FDA Accelerated Approval:The FDA ophthalmology division's streamlined pathways for sustained-release intraocular devices compress development-to-commercialization timelines for implant manufacturers targeting diabetic macular edema populations.
- Diabetic Retinopathy Prevalence:Rising diabetes incidence in the United States, Germany, and Japan expands the addressable patient base for intravitreal therapies, with ophthalmology clinics now absorbing the majority of injection volumes.
- Reimbursement Expansion:CMS coding decisions in the United States and NICE technology appraisals in the United Kingdom have broadened coverage for intravitreal anti-VEGF and corticosteroid therapies, reducing out-of-pocket barriers to chronic treatment.
Market Restraints
- Anti-VEGF Biosimilar Litigation:Patent disputes surrounding ranibizumab and aflibercept biosimilars create regulatory friction, delaying market entry and maintaining originator pricing power in key European and North American markets.
- Retreatment Cost Accumulation:Chronic monthly or bimonthly anti-VEGF injection requirements impose cumulative financial burden on payers and patients, constraining market penetration in price-sensitive healthcare systems.
- Intraocular Device MDR Compliance:EMA's Medical Device Regulation conformity assessments for sustained-release implants extend approval timelines and elevate documentation burdens for European market access.
Strategic Opportunities
- Uveitic Macular Edema Segment:Smaller treatable populations and limited therapeutic alternatives in uveitic macular edema generate higher per-patient margins, attracting specialty-focused development programs.
- EMA Adaptive Licensing:The European Medicines Agency's adaptive pathways enable conditional approval based on surrogate endpoints, allowing earlier revenue generation for novel sustained-release formulations.
- Retinal Vein Occlusion Expansion:Underpenetrated diagnosis and treatment rates in retinal vein occlusion-associated macular edema present volume expansion potential as screening protocols improve in Japan and Germany.
Industry Challenges
- Vitreoretinal Surgeon Training Bottleneck:The specialized skill set required for intravitreal injection and implant placement limits service capacity expansion, constraining volume growth in emerging treatment centers.
- Captive Antibody Production Requirements:Anti-VEGF manufacturing demands in-house biologics production capabilities or contracted GMP facilities, elevating capital intensity for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Macular Edema Treatment Market |
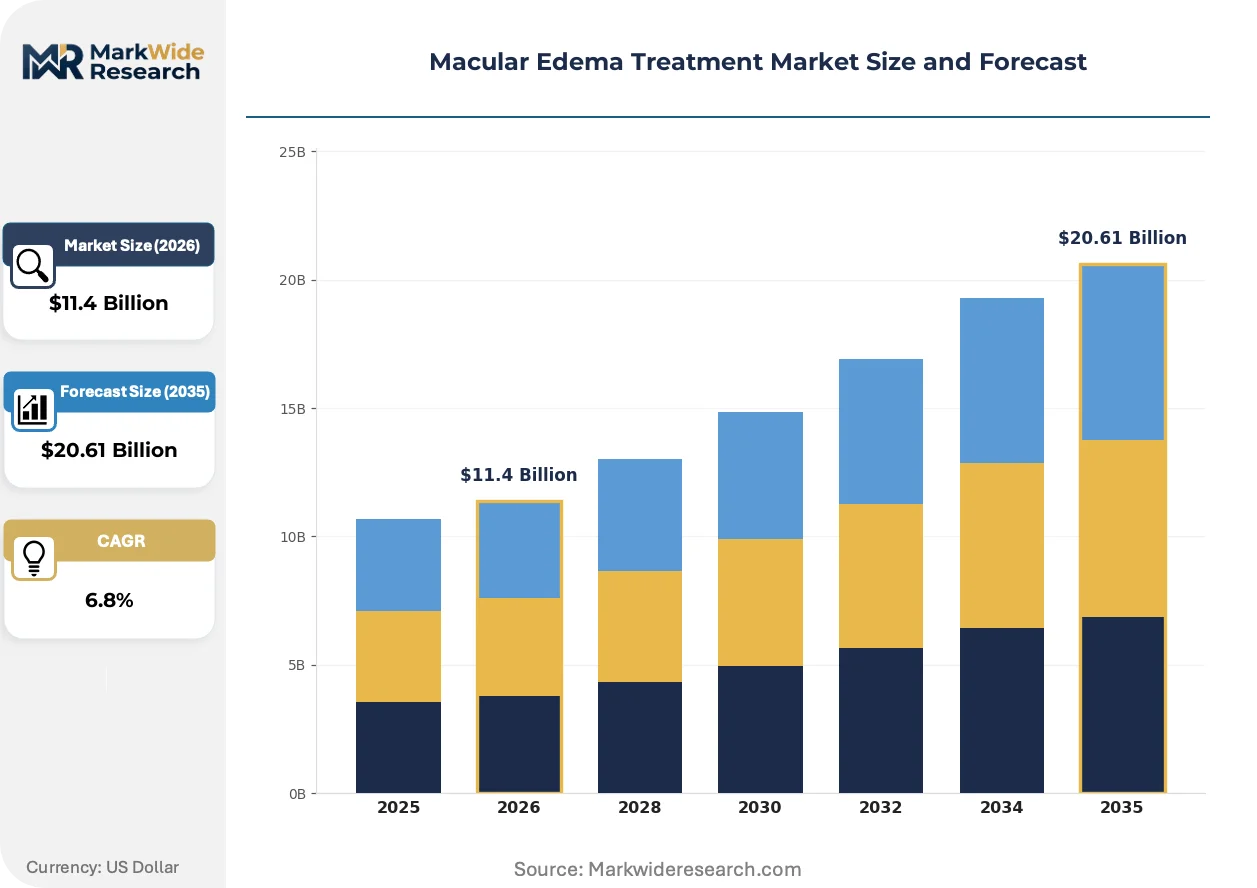
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-VEGF Injections, Corticosteroid Implants, NSAID Eye Drops, Laser Therapy Application: Diabetic Macular Edema, Retinal Vein Occlusion, Uveitic Macular Edema, Postoperative Cystoid Macular Edema End User: Ophthalmology Clinics, Specialty Eye Hospitals, Ambulatory Surgical Centers, Research Laboratories Delivery Mode: Intravitreal Injection, Sustained-release Implants, Topical Administration, Laser Photocoagulation |
| Companies Covered | Regeneron Pharmaceuticals, Novartis AG, Roche Holding AG, Bayer AG, AbbVie Inc., Genentech, Alimera Sciences, Kodiak Sciences, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Macular Edema Treatment Market Strategic Shifts & Innovations
Sustained-release formulation science is compressing treatment intervals while biosimilar entry pressures reshape competitive economics. Regulatory science advances and payer contracting evolution are simultaneously altering market access pathways.
Dexamethasone intravitreal implants are migrating from rescue therapy for refractory cases to first-line chronic management in diabetic macular edema. Retina specialists in high-volume United States ophthalmology clinics are adopting these devices for treatment-naive patients seeking reduced injection frequency. This shift is compressing anti-VEGF market share in chronic maintenance settings while expanding corticosteroid implant manufacturing scale requirements.
EMA's Medical Device Regulation (MDR) implementation is elevating clinical evidence standards for intraocular drug delivery systems. Manufacturers must now submit enhanced biocompatibility and durability data for CE marking renewal, extending regulatory timelines for sustained-release implant portfolios. European ophthalmology practices are responding by consolidating procurement around established MDR-compliant suppliers with demonstrated post-market surveillance capabilities.
Physician compensation models are decoupling procedure volume from reimbursement in select United States accountable care organizations. Retina specialists in these systems are prioritizing sustained-release implants that reduce injection visit frequency, aligning treatment selection with total cost-of-care metrics rather than fee-for-service economics. This behavioral shift concentrates in Medicare Advantage networks with delegated ophthalmology risk arrangements.
Macular Edema Treatment Market Segmentation
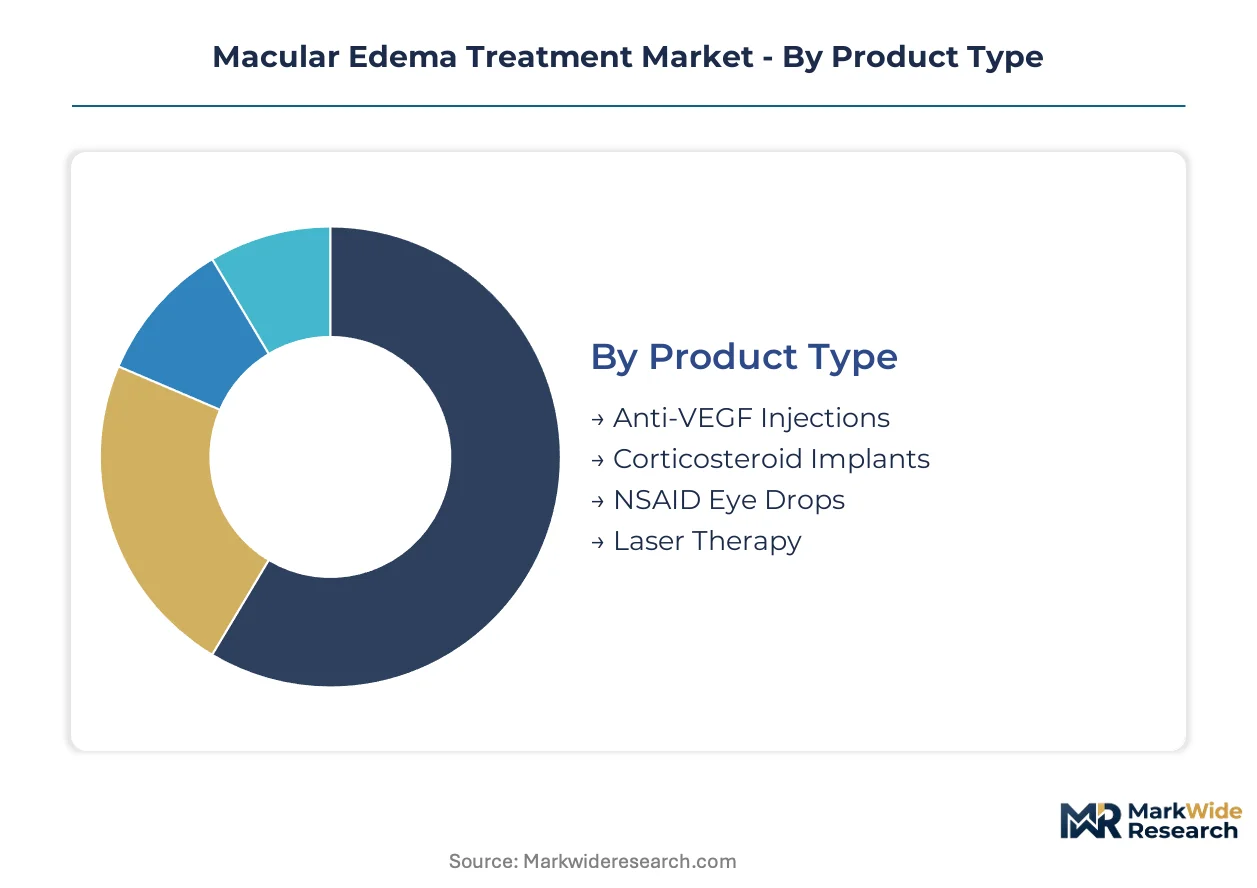
Segmentation in macular edema treatment reveals how reimbursement economics, injection burden, and surgical capability constraints distribute value across delivery modes and care settings. Understanding these divisions exposes where pricing power concentrates and where volume expansion faces structural bottlenecks.
Product Type:
Mature biologics dominate revenue pools while emerging sustained-release technologies reshape retreatment economics and manufacturing investment priorities.
- Anti-VEGF Injections:These agents bind vascular endothelial growth factor-A to reduce vascular permeability and preserve central visual acuity. Demand concentrates in high-volume United States ophthalmology clinics where diabetic retinopathy prevalence drives chronic monthly or bimonthly retreatment requirements.
- Corticosteroid Implants:Dexamethasone intravitreal devices deliver sustained corticosteroid release over months, reducing injection frequency. Japanese and German retina specialists are adopting these for treatment-naive patients seeking reduced clinic visit burden, compressing anti-VEGF share in chronic maintenance.
- NSAID Eye Drops:Nonsteroidal anti-inflammatory formulations target postoperative inflammation with topical delivery avoiding intraocular procedures.
- Laser Therapy:Photocoagulation remains reserved for select cases where pharmacological intervention is contraindicated or fails.
Anti-VEGF injections retain volume leadership; corticosteroid implants hold the steepest expansion curve.
Application:
Cost tier stratification separates high-volume chronic conditions from niche indications commanding premium pricing due to limited therapeutic alternatives.
- Diabetic Macular Edema:Fluid accumulation secondary to diabetic retinopathy represents the largest addressable population. United States CMS reimbursement expansion and rising diabetes incidence across Germany and Japan sustain injection volumes in ophthalmology clinics.
- Uveitic Macular Edema:Inflammatory-driven edema affects smaller treatable populations with constrained therapeutic options. Higher per-patient margins attract specialty-focused development programs from manufacturers seeking premium positioning outside commodity anti-VEGF competition.
- Retinal Vein Occlusion:Underpenetrated diagnosis rates in Japanese screening protocols present volume expansion potential as awareness improves.
- Postoperative Cystoid Macular Edema:Cataract surgery complication management absorbs NSAID and corticosteroid volumes in ambulatory surgical centers.
Diabetic macular edema retains volume leadership; uveitic macular edema holds the steepest margin expansion trajectory.
End User:
Customer type fragmentation reflects how procedure complexity and reimbursement structure concentrate advanced therapies in specialized settings while simpler modalities diffuse toward outpatient facilities.
- Ophthalmology Clinics:These settings now absorb the majority of anti-VEGF injection volumes as diabetic retinopathy prevalence climbs and retina specialists consolidate practice.
- Specialty Eye Hospitals:Academic medical centers in the United States and Germany handle complex uveitic cases and sustained-release implant placements requiring vitreoretinal surgical expertise.
- Ambulatory Surgical Centers:Laser photocoagulation and select corticosteroid implants migrate to these lower-cost settings where Medicare Advantage risk arrangements prioritize total cost reduction.
- Research Laboratories:Clinical trial sites and translational research facilities drive pipeline evaluation for novel sustained-release formulations seeking FDA accelerated approval pathways.
Ophthalmology clinics retain volume leadership; ambulatory surgical centers are gaining share fastest as reimbursement shifts toward site-of-care neutrality.
Delivery Mode:
Supply concentration around intraocular device manufacturing capabilities creates competitive moats that topical and laser alternatives cannot replicate.
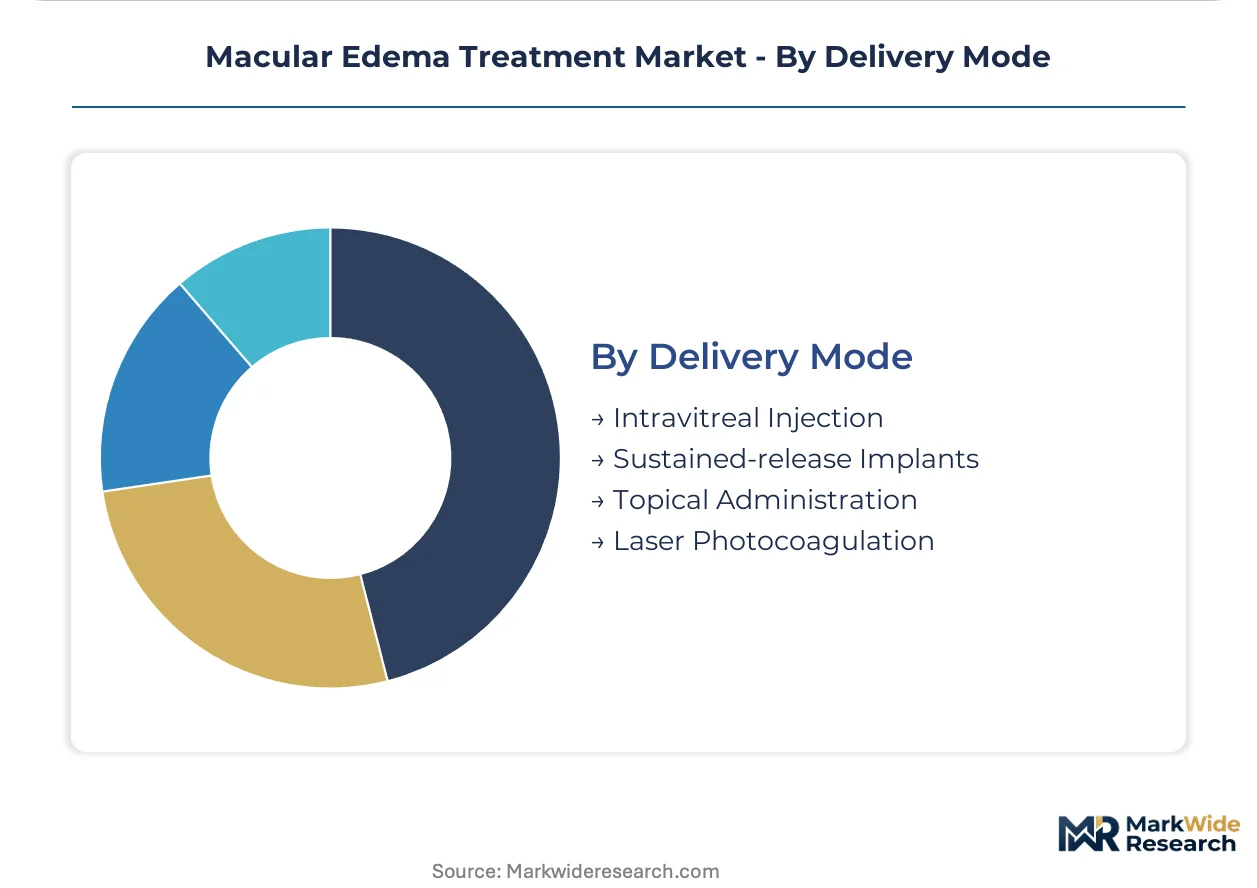
- Intravitreal Injection:Direct anti-VEGF or corticosteroid delivery into the vitreous cavity demands specialized training and sterile compounding infrastructure. United States ophthalmology clinics have built service capacity around monthly injection schedules.
- Sustained-release Implants:Biodegradable or non-biodegradable reservoirs extend therapeutic duration from months to years. EMA MDR conformity requirements for intraocular devices extend approval timelines, favoring established manufacturers with post-market surveillance infrastructure.
- Topical Administration:NSAID eye drops avoid procedural risk but achieve limited posterior segment penetration, constraining efficacy in established macular edema.
- Laser Photocoagulation:Thermal ablation of leaking microaneurysms persists in select geographies with constrained anti-VEGF reimbursement or patient access barriers.
Intravitreal injection retains volume leadership; sustained-release implants hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS reimbursement expansion for intravitreal therapies and EMA adaptive licensing pathways are reshaping commercial prioritization across major ophthalmology markets. Regulatory divergence between FDA accelerated approval and EMA MDR conformity requirements creates asymmetric entry timelines for sustained-release implant manufacturers.
United States
Diabetic retinopathy prevalence drives anti-VEGF injection volumes in high-capacity ophthalmology clinics across the Sun Belt and Midwest. FDA ophthalmology division review timelines compress development-to-commercialization for novel sustained-release formulations. Retina specialist consolidation in Florida, Texas, and California concentrates treatment capacity in metropolitan corridors.
Germany
EMA adaptive licensing enables conditional approval based on surrogate endpoints for diabetic macular edema therapies entering European markets. NICE technology appraisals in neighboring jurisdictions indirectly shape German payer contracting for intravitreal corticosteroid implants. Bavarian and Baden-Württemberg ophthalmology centers absorb sustained-release implant placements requiring vitreoretinal surgical expertise.
Japan
PMDA consultation pathways for sustained-release intraocular devices accelerate regulatory dialogue for manufacturers targeting retinal vein occlusion populations. METI industrial policy supports domestic ophthalmology device manufacturing scale. Tokyo and Osaka academic medical centers drive adoption of extended-duration implants among treatment-naive patients seeking reduced injection frequency.
United Kingdom
NICE technology appraisals directly constrain or enable intravitreal therapy access through National Health Service commissioning decisions. MHRA post-Brexit regulatory autonomy creates parallel review pathways distinct from EMA centralized procedures. London and Manchester ophthalmology networks pilot outcome-based contracting models that prioritize sustained-release implants reducing total cost-of-care.
India
CDSCO regulatory frameworks for intraocular drug delivery systems are evolving toward harmonization with ICH guidelines for sustained-release ophthalmic devices. Rising diabetes incidence expands the addressable patient base for anti-VEGF therapies in urban centers. Maharashtra and Karnataka ophthalmology chains build injection service capacity to absorb chronic retreatment requirements.
Macular Edema Treatment Market Key Industry Players
On the supply side, the industry is consolidating around integrated biologics manufacturers with captive antibody production and established ophthalmology distribution infrastructure. Three strategic archetypes dominate: originator pharmaceutical companies defending anti-VEGF franchises, sustained-release implant specialists pursuing formulation differentiation, and biosimilar developers targeting price-sensitive reimbursement environments. Competitive intensity concentrates in M&A activity acquiring sustained-release platform technologies and strategic partnerships securing GMP manufacturing capacity for intraocular delivery systems.
Among integrated pharmaceutical conglomerates, Novartis AG and Roche Holding AG occupy positions anchored by ophthalmology infrastructure and biologics manufacturing scale. Regeneron Pharmaceuticals exemplifies the captive production archetype through in-house antibody capabilities. Bayer AG and AbbVie Inc. sit within diversified portfolios where ophthalmology represents a specialty therapeutic vertical.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals |
| Novartis AG |
| Roche Holding AG |
| Bayer AG |
| AbbVie Inc. |
| Genentech |
| Alimera Sciences |
| Kodiak Sciences |
| GlaxoSmithKline |
| Others |
Cost & Logistics Intelligence
Captive antibody production facilities in the United States and Switzerland concentrate upstream margin capture for anti-VEGF therapies, while downstream pricing power accrues to ophthalmology clinics managing chronic retreatment schedules for diabetic macular edema populations.
Pricing Analysis
Certification level creates the primary spread, with FDA-approved originator biologics commanding premium positioning against EMA-cleared biosimilars and non-CE-marked alternatives in price-sensitive markets. Three-tier pricing structure across premium, standard, and economy levels reflects GMP compliance grade, injection frequency bundling, and after-sales physician training support. Cost compression in the standard tier is intensifying because biosimilar litigation delays are compressing effective patent windows. Hospital procurement committees exhibit highest price sensitivity, while specialty retina practices in consolidated United States metropolitan markets demonstrate lowest sensitivity due to risk-based contracting insulation.
Supply Chain Analysis
Contract manufacturing concentration rests with Lonza, Catalent, and Samsung Biologics for sterile fill-finish of intravitreal formulations, with additional capacity held by specialized ophthalmic device foundries in Germany and Japan for sustained-release implant fabrication. Active pharmaceutical ingredient sourcing draws from Swiss and Irish biologics fermentation facilities, while implant polymer matrices hinge on Japanese and German precision extrusion capabilities. Single-source vulnerability permeates the sterile compounding tier, where limited GMP-certified sites service global ophthalmology demand. Distribution runs through specialty pharmaceutical wholesalers with cold-chain infrastructure, direct-to-clinic models for high-volume United States practices, and hospital-centric procurement in European national health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as sustained-release implant ecosystems achieve interoperability with electronic health record systems, enabling outcome-based contracting that rewards reduced injection frequency rather than procedure volume alone.
For Market Incumbents: Pre-empt biosimilar erosion by securing captive manufacturing slots at GMP-certified sterile compounding facilities in Switzerland and Ireland, while accelerating MDR-compliant post-market surveillance infrastructure to defend European implant positioning against emerging formulation specialists. For New Entrants and Emerging Players: Build out uveitic macular edema development programs targeting the specialty indication's premium margin structure, leveraging EMA adaptive licensing pathways to achieve conditional approval ahead of full diabetic macular edema data packages, with go-to-market execution anchored by academic medical center partnerships in Germany and Japan. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sustained-release platform technologies possessing MDR-ready dossiers but lacking commercial infrastructure; long-term viability hinges on five-to-ten year durability data generation and reimbursement code consolidation, with the signal to watch being CMS decisions on site-of-care neutrality for ambulatory surgical center implant placement.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Surrogate endpoint validation accelerates FDA ophthalmology division review timelines for novel sustained-release formulations. |
| Manufacturing Scale-Up | GMP facility expansion in Switzerland and Ireland secures sterile fill-finish capacity for chronic anti-VEGF demand. |
| Regulatory Approval Pathway | EMA adaptive licensing enables conditional European market entry before full diabetic macular edema efficacy datasets mature. |
| Reimbursement Strategy | Outcome-based contracting with Medicare Advantage networks aligns sustained-release implant adoption with total cost-of-care metrics. |
| Hospital System Partnership | Academic medical center alliances in Tokyo and Munich establish vitreoretinal surgical training pipelines for implant placement capacity. |
Research Approach
A standing panel of vitreoretinal surgeons, formulary directors at United States payers, EMA regulatory affairs specialists, and ophthalmology clinic procurement managers provided ongoing calibration across the study period, with primary interview findings triangulated against FDA 510(k) filings, EMA EPAR assessments, ClinicalTrials.gov protocol records, and CMS Medicare claims data, combining bottom-up patient volume estimates with top-down manufacturer revenue reconciliation.
Scenario-bracketing framed the analytical framework across the projection horizon, modeling patient flow through anti-VEGF injection schedules versus sustained-release implant adoption curves by treatment line, delivery mode, and regional regulatory cluster, with CAGRs derived from procedure volume elasticity to reimbursement rate changes and diabetes incidence projections, incorporating implant durability assumptions and biosimilar entry timing as industry-specific sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cash-backed sustained-release specialists or accelerated FDA breakthrough designations would shift outcomes beyond modeled ranges. Quarterly review of CMS coding decisions, EMA MDR renewal timelines, and anti-VEGF biosimilar litigation dockets is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
India Ophthalmic Clinical Trials Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Choroideremia Treatment Market
Ophthalmology
Choroidal Neovascularization Market
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Global Aphakia Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market
Ophthalmology
Global Ophthalmology PACS Market
Ophthalmology
Diabetic Macular Edema Treatment Market
Ophthalmology
Amblyopia Treatment Market
Ophthalmology
United Kingdom Ophthalmology Devices Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
Astigmatism Market