
 Choroideremia Treatment Market | 2026-2036
Choroideremia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Choroideremia Treatment Market Outlook
The capital-intensity gap between large-cap gene therapy developers and mid-stage biotechs is collapsing as platform manufacturing costs fall and CDMO partnerships standardize. Novartis AG leverages its cell-and-gene therapy infrastructure to anchor ophthalmology pipelines across multiple retinal degeneration targets. Spark Therapeutics competes through its established AAV vector expertise, while MeiraGTx Holdings plc specializes in precision genetic medicine for inherited retinal diseases.
Choroideremia treatment encompasses therapeutic interventions targeting the CHM gene mutation that causes progressive retinal degeneration and blindness, primarily through AAV-mediated gene replacement delivered via subretinal injection to restore REP-1 protein function in photoreceptors. Gene therapy segments command premium development investment due to curative intent and orphan pricing potential, while intravitreal delivery modes attract formulation innovation aimed at reducing surgical complexity relative to subretinal approaches. Small molecule research occupies earlier-stage positions with lower capital barriers but unproven clinical endpoints.
FDA orphan drug and fast-track designations shape trial enrollment incentives and exclusivity timelines, while EMA's PRIME scheme accelerates European access pathways for gene therapies addressing unmet retinal disease burden. The central monitoring priority for stakeholders centers on durability of gene expression data beyond initial Phase I/II readouts, as sustained therapeutic effect determines both reimbursement viability and competitive differentiation in this indication.
Market Dynamics
AAV vector manufacturing standardization is collapsing cost barriers between platform gene therapy developers and mid-stage biotechs, while FDA orphan drug designations compress clinical trial timelines and reshape competitive entry sequencing.
Growth Catalysts
- FDA Fast-Track Designation:Accelerated review pathways compress Phase I/II enrollment timelines for CHM gene replacement candidates, reducing capital-at-risk periods for developers.
- Subretinal Surgical Infrastructure:Vitreoretinal specialist networks in the United States expand screening protocols and referral pathways for inherited retinal disease identification.
- EMA PRIME Scheme:Priority medicines status in Europe expedites scientific advice and health technology assessment preparation for gene therapy submissions.
Market Restraints
- Single-Site Vector Production:Concentrated AAV manufacturing capacity in contract development organizations creates supply bottlenecks and batch-to-batch variability risks.
- Subretinal Delivery Complexity:Surgical precision requirements limit treatable patient populations to specialized ophthalmology centers with vitrectomy capabilities.
- Gene Expression Durability Uncertainty:Long-term REP-1 protein maintenance data beyond five years remains incomplete, complicating reimbursement negotiations.
Strategic Opportunities
- Intravitreal Formulation Innovation:Non-surgical delivery modes targeting suprachoroidal or intravitreal routes could expand addressable patient pools beyond subretinal surgical candidates.
- Japan's Sakigake Designation:Early approval pathways for regenerative medicines offer priority review benefits for CHM gene therapies entering Japanese markets.
- Retinal Specialist Network Consolidation:Integrated practice management platforms in the United States enable centralized patient identification and streamlined referral logistics.
Industry Challenges
- Vitreoretinal Surgical Training Pipeline:Limited fellowship positions and complex subretinal injection techniques constrain treatment capacity expansion.
- Vector Immunogenicity Management:Pre-existing neutralizing antibodies against AAV serotypes exclude substantial patient subsets from gene therapy eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Choroideremia Treatment Market |
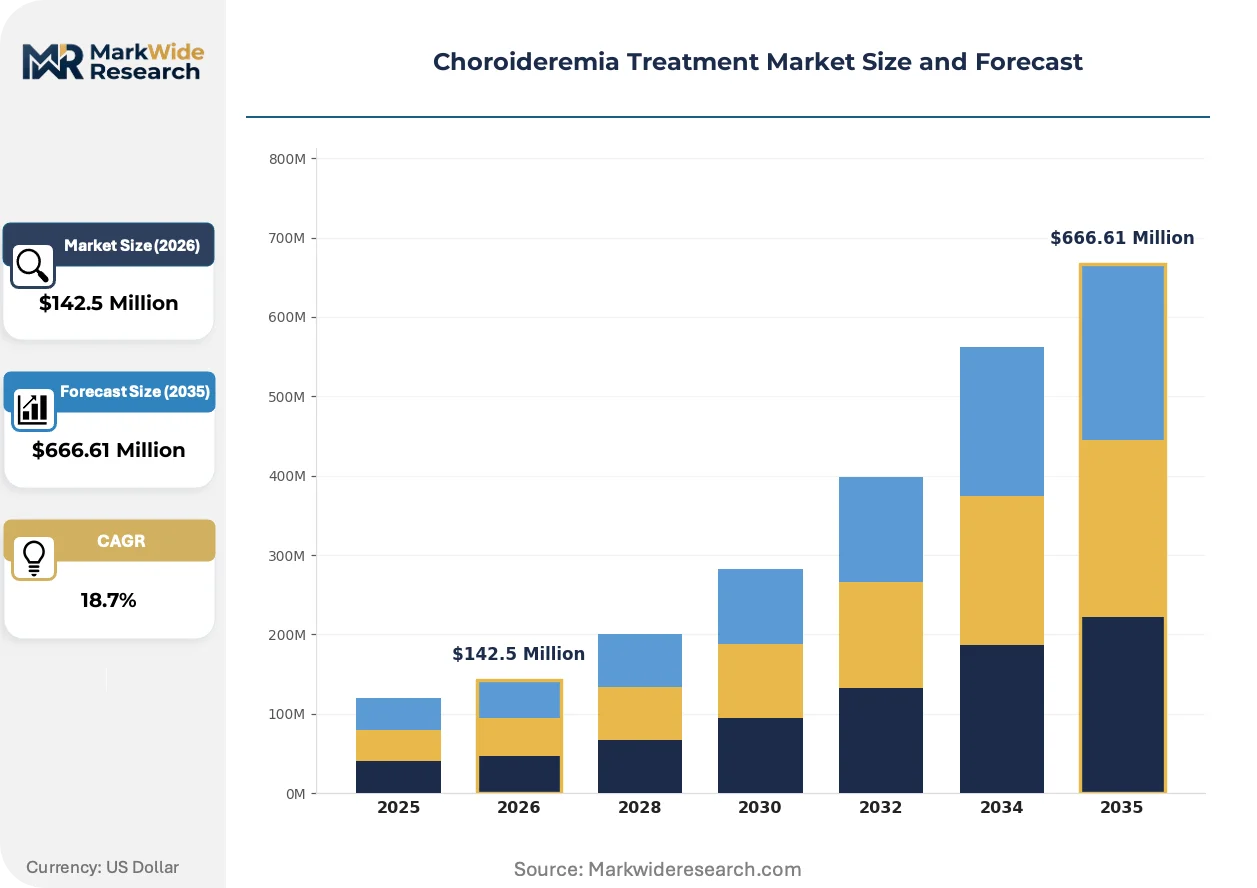
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $666.61 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adeno-Associated Virus, Gene Therapy, Small Molecules, Clinical Trials Delivery Mode: Intravitreal Injection, Systemic Administration, Surgical Intervention, Oral Administration End User: Hospitals, Specialty Clinics, Research Laboratories, Homecare Settings Therapy Area: Ophthalmology, Rare Diseases, Genetic Disorders, Retinal Degenerations |
| Companies Covered | Hoffmann-La Roche Ltd, Astellas Pharma Inc., Novartis AG, MeiraGTx Holdings plc, Applied Genetic Technologies Corporation, Spark Therapeutics, 4D Molecular Therapeutics, Adverum Biotechnologies, Biogen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Choroideremia Treatment Market Strategic Shifts
Vector engineering and delivery platform advances are compressing surgical complexity while regulatory pathways mature for one-time curative interventions in inherited retinal diseases.
Next-generation AAV capsid variants with enhanced retinal tropism and reduced immunogenicity profiles are miniaturizing the surgical footprint required for effective CHM gene transfer. Specialty clinics adopt these engineered vectors for earlier-stage patient treatment before significant photoreceptor loss occurs. The technology is miniaturizing procedure duration and recovery windows, enabling same-day discharge protocols that reduce hospital infrastructure requirements.
EMA's PRIME scheme and FDA's regenerative medicine advanced therapy designation are converging to standardize accelerated assessment frameworks for gene therapies addressing unmet ophthalmology burdens. Manufacturers now structure development programs around simultaneous US-European regulatory submissions rather than sequential geographic rollouts. European retinal specialist networks respond by building gene therapy treatment centers with harmonized surgical training and patient monitoring protocols.
Academic medical centers increasingly unbundle clinical trial participation from exclusive manufacturer relationships, enabling multi-sponsor patient access platforms. Retinal degeneration foundations coordinate centralized registries that aggregate natural history data and streamline trial matching across competing therapeutic programs. This structural shift concentrates patient identification capacity in the United States, where foundation-driven advocacy networks maintain deepest penetration among diagnosed choroideremia populations.
Choroideremia Treatment Market Segmentation
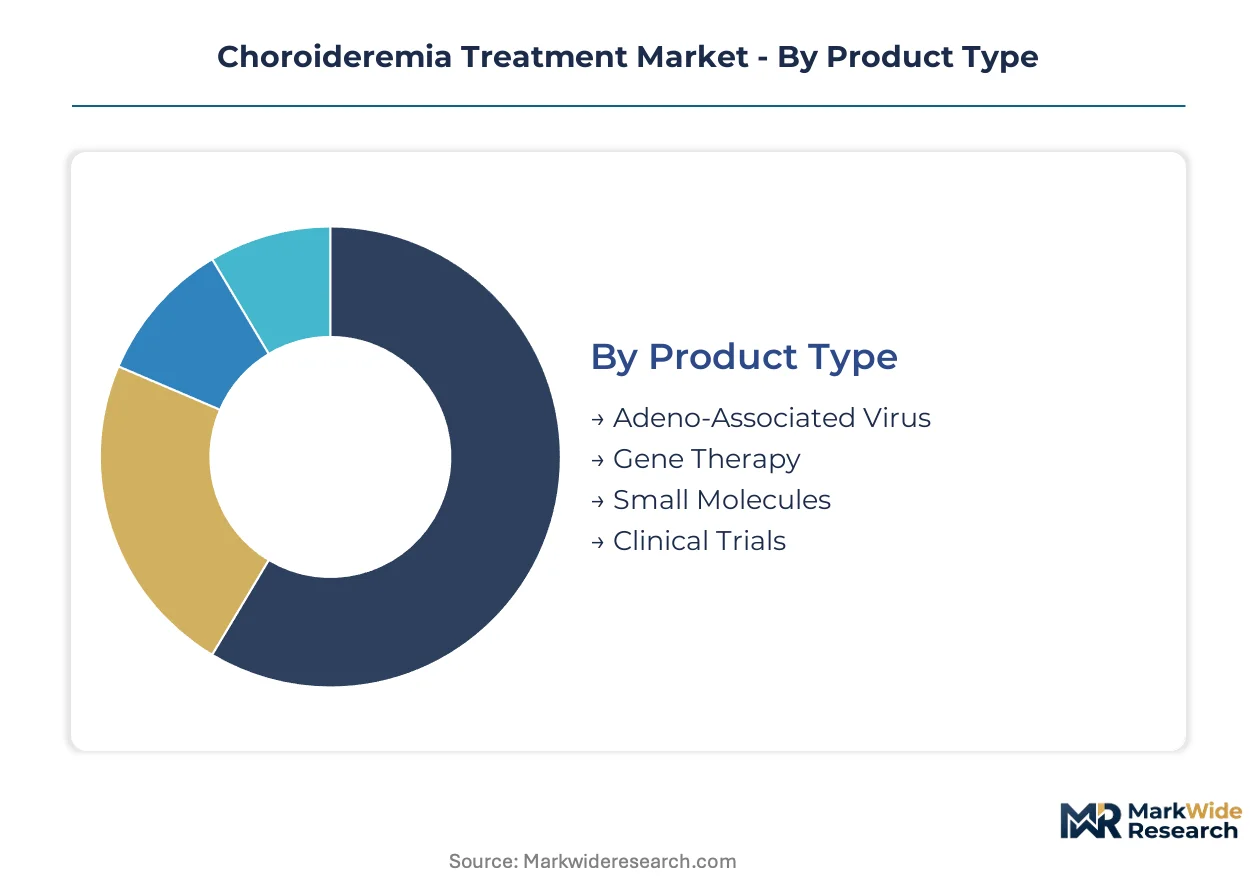
Choroideremia treatment segmentation reveals how vector engineering, surgical infrastructure, and patient access channels determine commercial viability across this orphan indication. Product and delivery heterogeneity creates distinct investment profiles for developers targeting curative versus symptomatic interventions.
Product Type:
Gene therapy platforms face substitution pressure from small molecule programs pursuing neuroprotective mechanisms, though clinical validation gaps protect AAV-based candidates near term.
- Adeno-Associated Virus:Recombinant AAV5 and AAV2 serotypes engineered for retinal pigment epithelium transduction dominate current pipelines. Manufacturing scale-up at CDMO facilities in the United States and Switzerland determines batch release timelines for subretinal delivery programs.
- Gene Therapy:CHM gene replacement using REP-1 coding sequences delivered via subretinal injection represents the curative standard. FDA regenerative medicine advanced therapy designation accelerates review timelines for candidates demonstrating sustained visual field preservation.
- Small Molecules:Oral isoprenoid pathway modulators target protein prenylation defects downstream of CHM mutations.
- Clinical Trials:Expanded access protocols and Phase I/II basket studies concentrate patient recruitment at academic medical centers with inherited retinal disease registries.
AAV-based modalities retain volume leadership among funded programs; small molecules hold the steepest expansion trajectory if neuroprotective endpoints achieve regulatory acceptance.
Delivery Mode:
Cost tier stratification separates surgical subretinal approaches requiring vitrectomy infrastructure from office-based intravitreal alternatives with lower facility overhead.
- Intravitreal Injection:Suprachoroidal and intravitreal routes using engineered capsids with enhanced retinal penetration reduce surgical complexity. Formulation stability at standard refrigeration temperatures expands treatable sites beyond academic centers.
- Systemic Administration:Intravenous AAV delivery avoids ocular surgery but requires higher vector doses with systemic immunogenicity management. Liver sequestration challenges limit current clinical translation for choroideremia indications.
- Surgical Intervention:Subretinal injection via pars plana vitrectomy remains the efficacy benchmark for photoreceptor transduction.
- Oral Administration:Small molecule candidates targeting downstream metabolic pathways offer non-invasive dosing schedules.
Surgical intervention maintains efficacy leadership in current trials; intravitreal injection climbs the fastest as capsid engineering matures.
End User:
Customer type fragmentation concentrates high-value gene therapy administration at sites with surgical credentialing while pushing screening and monitoring toward distributed specialty networks.
- Specialty Clinics:Retina-focused practices with inherited retinal disease expertise handle patient identification, genetic counseling, and post-treatment monitoring. Foundation-driven registries in the United States channel diagnosed patients toward these centers for trial matching.
- Hospitals:Academic medical centers with vitreoretinal surgery fellowship programs perform subretinal gene therapy administration. Operating room block scheduling and anesthesia availability constrain treatment throughput at these sites.
- Research Laboratories:Preclinical vector development and natural history study coordination occur at university-affiliated facilities.
- Homecare Settings:Remote monitoring technologies enable visual field tracking outside clinical sites for post-treatment surveillance.
Hospitals retain procedural volume leadership; specialty clinics gain share fastest as screening protocols broaden and referral networks mature.
Therapy Area:
Application scope determines reimbursement coding complexity, with pure orphan designations commanding premium pricing versus broader ophthalmology indications requiring indication-specific evidence generation.
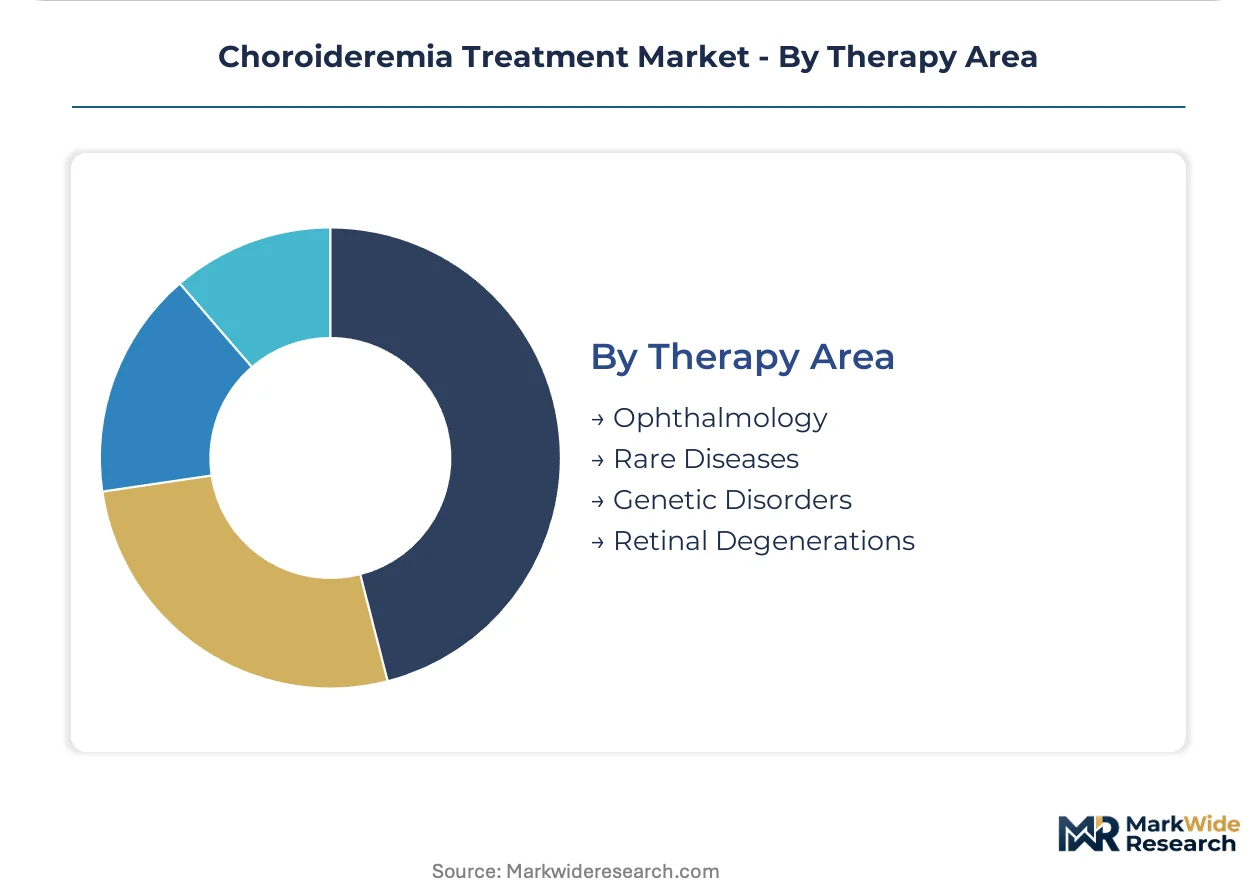
- Retinal Degenerations:Disease-specific endpoints including microperimetry and dark-adapted visual field testing define regulatory pathways for CHM-targeted interventions. Natural history data from multi-center registries establishes comparator baselines for single-arm trials.
- Rare Diseases:Orphan drug exclusivity provisions in the United States and European Union create market protection windows for first movers. Payer engagement strategies must address one-time curative pricing models versus chronic therapy budgets.
- Ophthalmology:Brotherapeutic categorization enables cross-pollination of surgical training and vector manufacturing expertise from age-related macular degeneration programs.
- Genetic Disorders:Precision medicine infrastructure including CLIA-certified genetic testing laboratories supports diagnostic confirmation and treatment eligibility determination.
Rare diseases anchor current commercial focus; retinal degenerations expand most quickly as phenotype-specific endpoints achieve regulatory qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where gene therapy reimbursement frameworks for rare retinal diseases command premium orphan drug rates. European markets operate under tighter health technology assessment constraints. Japanese regulators offer accelerated pathways that compress development-to-commercialization timelines.
United States
Foundation-driven patient registries and vitreoretinal specialist networks dominate choroideremia identification and trial recruitment. FDA regenerative medicine advanced therapy designation accelerates review timelines for subretinal gene replacement candidates. Academic medical centers in Boston, Philadelphia, and Baltimore anchor surgical treatment capacity with established inherited retinal disease programs.
Germany
EMA centralized marketing authorization procedures enable rapid European market access following German reimbursement negotiations. The country's statutory health insurance funds apply outcome-based pricing assessments to one-time gene therapies. Heidelberg and Tübingen university hospitals coordinate multi-center natural history registries that support regulatory submissions.
Japan
PMDA's Sakigake designation for regenerative medicines prioritizes scientific advice and review resources for CHM-targeted interventions. Domestic ophthalmology societies build subretinal surgical training pipelines to address vitreoretinal specialist shortages. Tokyo and Osaka medical centers lead patient identification through collaboration with retinal degeneration advocacy foundations.
United Kingdom
NICE technology appraisals impose cost-effectiveness thresholds that complicate orphan gene therapy pricing negotiations. The NHS specialized commissioning framework concentrates treatment administration at designated supraregional centers. Moorfields Eye Hospital in London and Oxford University Hospitals anchor clinical trial participation and post-treatment monitoring infrastructure.
Switzerland
Swissmedic's streamlined assessment procedures for advanced therapy medicinal products attract European headquarters decisions from gene therapy developers. Cantonal hospital networks in Zurich, Geneva, and Basel coordinate patient referral pathways for ultra-rare retinal diseases. Federal orphan drug reimbursement provisions reduce access barriers for insured populations.
Choroideremia Treatment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes in choroideremia treatment development. Large-cap pharmaceutical conglomerates with cell-and-gene therapy infrastructure dominate vector manufacturing scale and regulatory navigation. Mid-stage biotechnology specialists concentrate precision genetic medicine capabilities and inherited retinal disease expertise. Platform technology developers occupy earlier-stage positions with novel capsid engineering approaches. Competitive dynamics center on CDMO partnership consolidation and simultaneous US-European regulatory submission strategies.
Among large-cap developers, Novartis AG and Roche Holding exemplify integrated ophthalmology pipeline strategies spanning multiple retinal degeneration targets. Spark Therapeutics occupies a specialist position within this tier, leveraging established adeno-associated virus vector expertise. MeiraGTx Holdings plc represents the precision genetic medicine archetype with dedicated inherited retinal disease focus. These three entities anchor distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Hoffmann-La Roche Ltd |
| Astellas Pharma Inc. |
| Novartis AG |
| MeiraGTx Holdings plc |
| Applied Genetic Technologies Corporation |
| Spark Therapeutics |
| 4D Molecular Therapeutics |
| Adverum Biotechnologies |
| Biogen Inc. |
| Others |
Value Chain & Pricing Dynamics
Batch release timelines spanning 90-120 days for AAV vector manufacturing concentrate pricing power with CDMOs possessing validated GMP suites, while gene therapy developers absorb inventory carrying costs that compress margins on pre-revenue programs. This lead-time band forces developers to lock in multi-year manufacturing slots before clinical proof-of-concept, embedding supply commitments into early-stage capital allocation.
Pricing Analysis
The customization-premium spread separates standard AAV5 vector contracts from configured-to-order capsid engineering programs with enhanced retinal tropism. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification grade, batch scale, and analytical testing depth. Pricing pressure stems from CDMO capacity expansion in Switzerland and the United States as platform manufacturing commoditizes. Academic medical centers exhibit highest price sensitivity due to fixed grant funding, while large-cap pharmaceutical developers leverage volume commitments for preferential slotting.
Supply Chain Analysis
Strategic stockpile preferences dominate AAV manufacturing as developers secure 18-24 month vector inventories to mitigate single-site production risks. Plasmid DNA sourcing concentrates in the United States and Germany, with HEK293 cell banks anchored in Switzerland and California facilities. Supply chain risk centers on single-source serotype-specific plasmid suppliers subject to FDA regulatory inspection delays. Distribution runs through cold-chain logistics networks terminating at academic medical center pharmacies with minus-eighty storage infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in intravitreal delivery formulation as patient identification expands beyond surgical candidates, creating niche entry points for non-invasive alternatives. Foundation-driven registry growth in the United States channels diagnosed populations toward multiple competing therapeutic modalities simultaneously.
For Market Incumbents: Shield vector manufacturing relationships through exclusive CDMO partnerships with capacity reservation clauses, while accelerating capsid engineering programs to differentiate from emerging intravitreal competitors. Pre-existing neutralizing antibody screening protocols represent a defensive moat requiring reinforcement through proprietary diagnostic alliances.
For New Entrants and Emerging Players: Lead with suprachoroidal delivery platform development targeting specialty clinics lacking vitrectomy infrastructure, the most penetrable channel as screening protocols broaden. Japan's Sakigake designation pathway offers a regulatory-first go-to-market angle with compressed review timelines and priority scientific advice access.
For Investors and Strategic Acquirers: Long-term, this sits as a platform-technology play because AAV capsid engineering capabilities transfer across multiple inherited retinal disease indications beyond choroideremia. Acquisition target archetype: mid-stage biotechs with validated retinal tropism data and orphan drug designation momentum. The signal to watch is durability-of-expression readouts beyond five years, which determine reimbursement viability and competitive differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase I/II basket studies at Moorfields Eye Hospital and Johns Hopkins accelerate patient recruitment across multiple CHM mutations. |
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy designation compresses review timelines for subretinal gene replacement candidates. |
| Manufacturing Scale-Up | CDMO partnerships with Lonza and Catalent standardize AAV5 vector production for multi-center trial supply. |
| Pipeline Diversification | Intravitreal formulation programs hedge against subretinal surgical capacity constraints in emerging markets. |
| Licensing Agreement | Academic center technology transfers from University of Pennsylvania and University of Florida expand capsid engineering access. |
Study Parameters
Desk research of FDA orphan drug designations, ClinicalTrials.gov entries, and EMA PRIME scheme approvals preceded structured interviews with gene therapy development executives, regulatory affairs leads at ophthalmology-focused biotechs, vitreoretinal surgeons at academic medical centers, and payer access specialists at major US health plans. Secondary validation drew from SEC 10-K filings, EMA assessment reports, and foundation-driven natural history registry publications. Bottom-up patient population estimates triangulated against top-down orphan drug market sizing frameworks.
Variance decomposition across therapy modality, delivery route, and end-user channel anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include vector serotype, surgical versus non-surgical administration, specialty clinic versus hospital site of care, and regional regulatory cluster. CAGRs derived from log-linear trend fitting to historical gene therapy adoption curves, with adjustments for reimbursement policy inflections and manufacturing scale-up timelines. Forecast inputs incorporated vitreoretinal surgeon fellowship graduation rates and foundation registry expansion trajectories.
The analysis sits within stated boundaries; outcomes outside sustained gene expression durability assumptions or favorable health technology assessment rulings would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway standardization and CDMO capacity expansion schedules. Gene immunogenicity exclusion rates and payer willingness-to-pay for one-time curative interventions represent specific risk factors that could revise projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
North America Ophthalmic Devices and Drugs Market
Ophthalmology
Vernal Keratoconjunctivitis Treatment Market
Ophthalmology
Global Retinal Vein Occlusion Market
Ophthalmology
India Ophthalmology Devices Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Ophthalmic Eye Drops Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market
Ophthalmology
Ophthalmic Devices Market
Ophthalmology
Tonometry Market
Ophthalmology
Retinal Detachment Diagnostic Market
Ophthalmology
Optic Nerve Glioma Market