
 Processed Cheese Market | 2026-2036
Processed Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Cheese Market Analysis
Asset-light contract manufacturing and third-party dairy processing agreements is tilting competitive dynamics toward firms that outsource production rather than build captive plants. Kraft Heinz leverages its North American brand equity and retail shelf presence to sustain volume leadership in sliced and block formats. Fonterra Co-operative Group anchors its position through backward integration into New Zealand milk powder supply, securing cost advantages on dairy solids. Arla Foods competes via cooperative ownership structures that stabilize farmer milk pricing and buffer margin volatility.
Processed cheese denotes a dairy product manufactured by blending natural cheese with emulsifiers, salts, and milk solids, then heating to create a homogeneous melt with controlled moisture content between 40% and 60%. Its primary commercial purpose is delivering consistent texture, extended shelf stability, and uniform melting behavior for food service operators and industrial food manufacturers. Slice formats dominate retail channel revenue due to convenience positioning in sandwich applications, while spreadable varieties represent the fastest-growing grade as breakfast and snacking occasions expand. Bulk packaging for industrial end users captures concentrated margin pools where long-term supply contracts reduce price volatility.
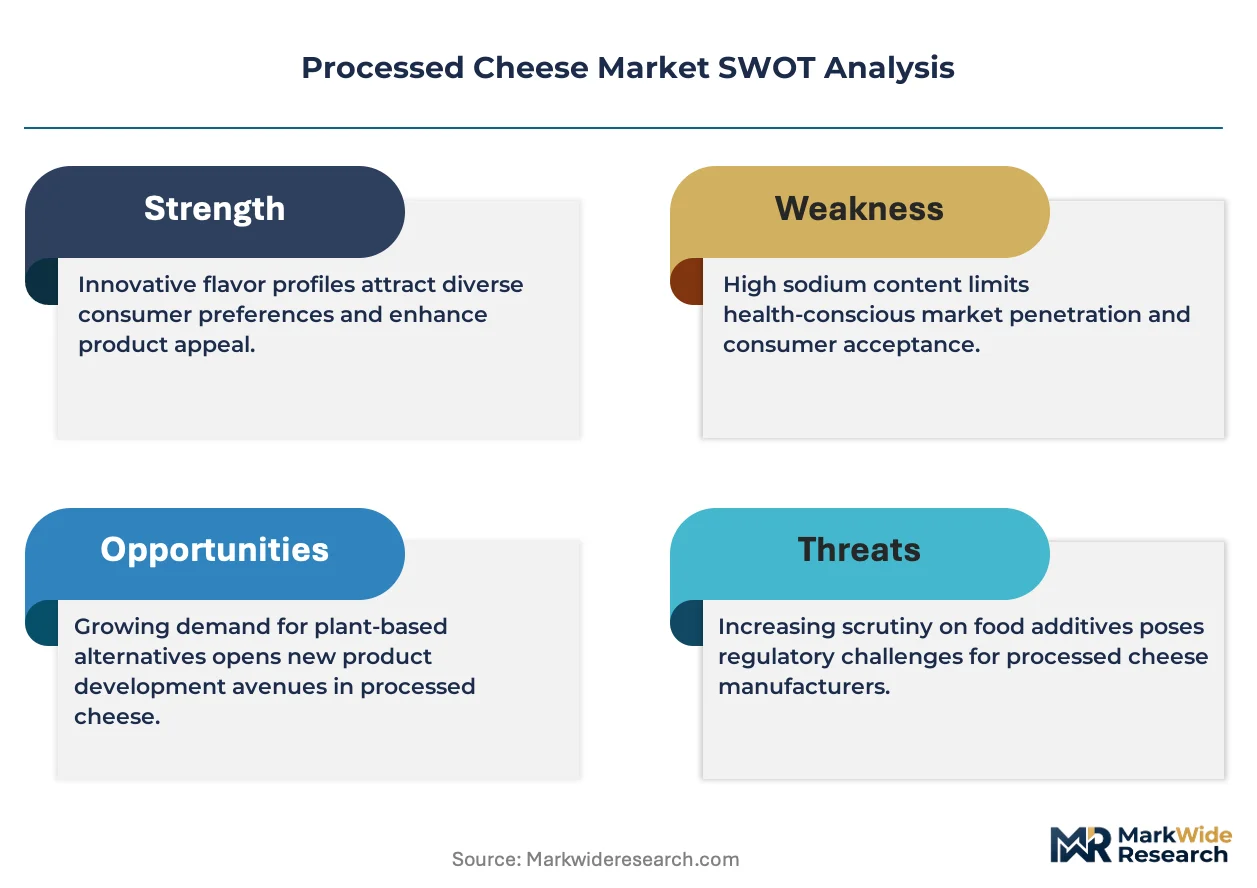
The FDA governs cheese identity standards and labeling requirements in the United States, while the EFSA and EU Green Deal frameworks shape dairy processing emissions targets and sustainable packaging mandates across European production facilities. BIS certification requirements in India and FSSAI quality standards constrain import access and shape local formulation adaptations for tropical climate stability. Stakeholders must monitor evolving front-of-pack labeling regulations and carbon accounting rules that will reshape sourcing decisions and product reformulation priorities.
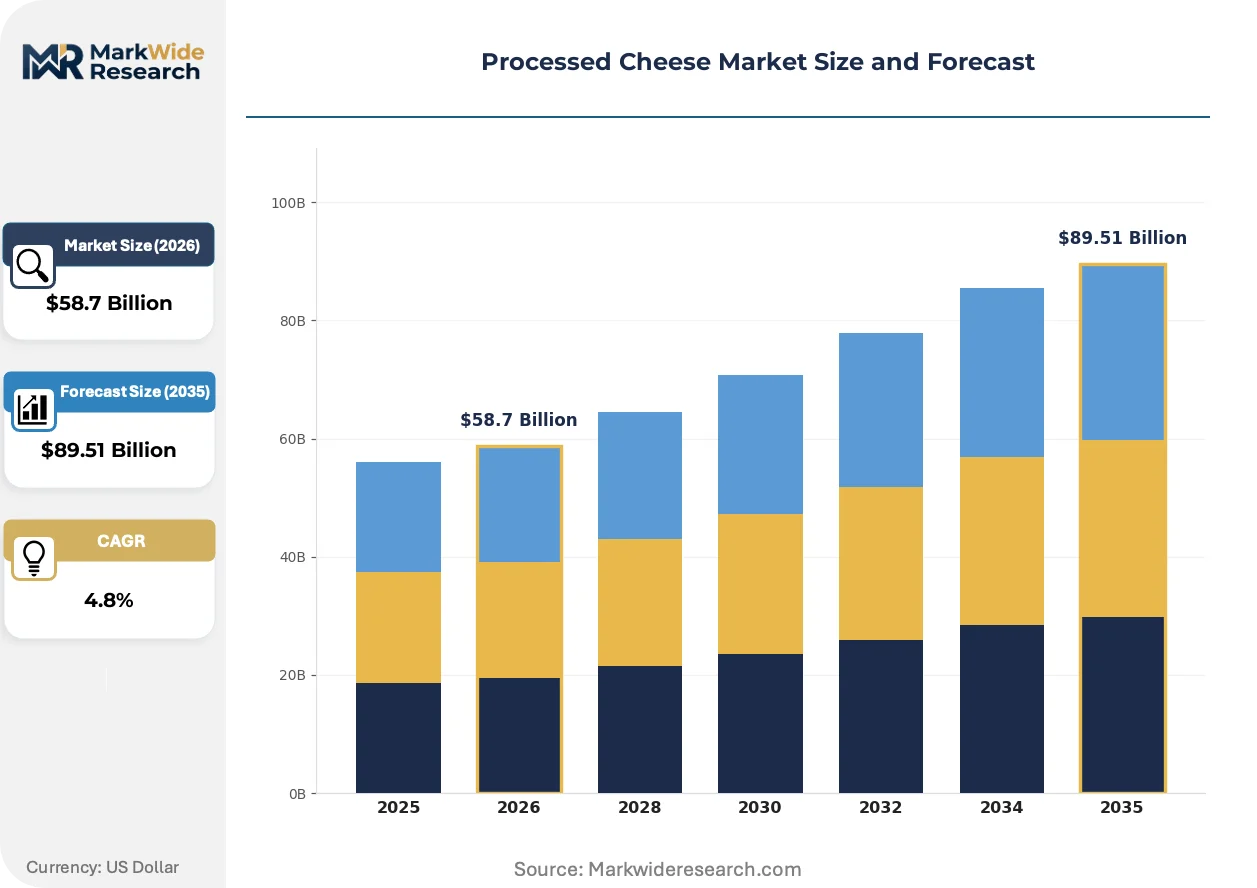
Market Dynamics
Asset-light contract manufacturing is tilting competitive dynamics toward firms that outsource production rather than build captive plants, while quick-service restaurant chains across Southeast Asia expand processed cheese procurement for burger and pizza applications.
Growth Catalysts
- QSR Expansion:Quick-service restaurant chains across Southeast Asia are expanding processed cheese procurement for burger and pizza applications as western-style fast food penetration deepens in Indonesia and Vietnam.
- EU Green Deal:Dairy processing emissions targets and sustainable packaging mandates are accelerating facility modernization investments across European production facilities.
- Slice Format Convenience:Retail channel revenue concentration in slice formats is pulling manufacturing capacity toward sandwich-ready products with extended shelf stability.
Market Restraints
- Milk Powder Price Volatility:Backward integration into New Zealand milk powder supply anchors cost structures for integrated players, but spot market exposure punishes non-integrated processors.
- FDA Identity Standards:Updated Standards of Identity for cheese products in the United States is tightening ingredient disclosure requirements and constraining formulation flexibility.
- Natural Cheese Substitution:Artisan and specialty natural cheese categories are capturing premium-positioned food service accounts seeking menu differentiation.
Strategic Opportunities
- Spreadable Breakfast Expansion:Spreadable varieties represent underpenetrated white space as breakfast and snacking occasions expand beyond traditional sandwich applications.
- BIS Certification Pathway:India's BIS certification requirements and FSSAI quality standards create import substitution incentives for local formulation adaptations targeting tropical climate stability.
- Industrial Bulk Contracts:Bulk packaging for industrial end users captures concentrated margin pools where long-term supply contracts reduce price volatility for food manufacturers.
Industry Challenges
- Emissions Accounting Expertise:Carbon accounting rules under EU Green Deal frameworks are reshaping sourcing decisions, creating skill gaps in lifecycle assessment and Scope 3 data collection.
- Front-of-Pack Labeling Compliance:Evolving front-of-pack labeling regulations across multiple jurisdictions are forcing simultaneous reformulation priorities with conflicting nutritional claim requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Cheese Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $89.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slice, Spread, Shred, Block Grade: Cheddar, Mozzarella, American, Gouda Packaging Type: Flexible, Rigid, Tetra Pak, Bulk End User: Food Service, Retail, Residential, Industrial |
| Companies Covered | Saputo Inc., Fonterra Co-operative Group, Kraft Heinz, Savencia SA, FrieslandCampina, Bel Group, Arla Foods, Dairy Farmers of America, Lactalis Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Cheese Market Emerging Trajectories
Clean-label emulsification systems and precision fermentation-derived dairy proteins are actively reshaping formulation strategies, while regulatory pressure on sodium content and processing transparency accelerates ingredient list simplification.
High-pressure processing technology for extended shelf stability without chemical preservatives is migrating from premium organic lines to mainstream retail blocks. Mid-tier private label manufacturers in Germany and the Netherlands are adopting HPP equipment at accelerating capex cycles. This technology is compressing the traditional trade-off between clean-label positioning and distribution reach.
REACH chemical restrictions and EU Green Deal packaging mandates are forcing substitution of phosphate-based emulsifiers with citrate and sodium citrate alternatives. Reformulation costs are concentrating among small-to-mid processors lacking in-house R&D scale. Spreadable and sauce-grade cheese products face the steepest technical adaptation curves due to texture stability requirements.
Buyer concentration among quick-service restaurant procurement consortia is compressing supplier negotiation cycles and unbundling technical service from base product supply. Food service distributors in Indonesia and Vietnam are consolidating purchase volumes through regional buying cooperatives. This pattern is most visible in the Ho Chi Minh City and Jakarta metropolitan clusters where western fast food expansion is densest.
Processed Cheese Market Segmentation
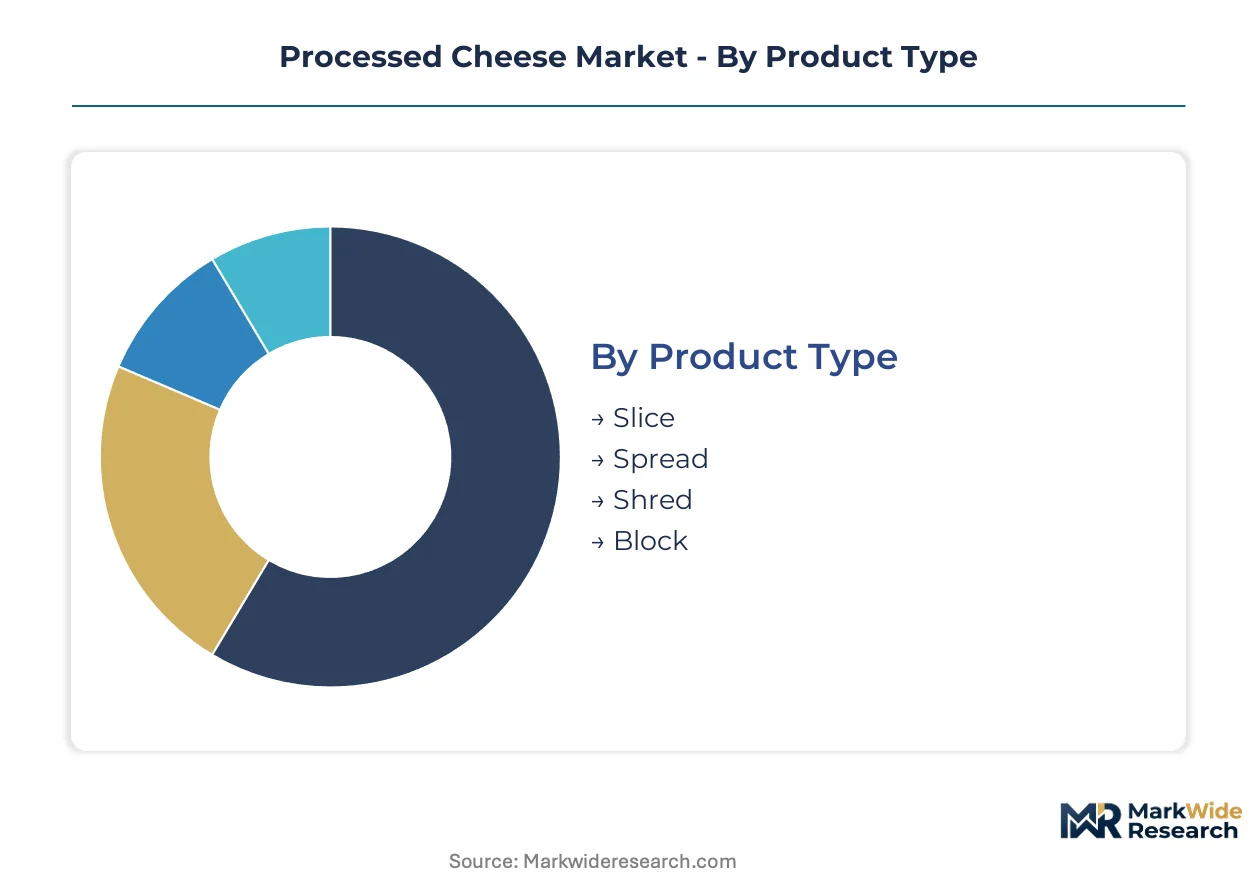
Processed cheese manufacturers configure production lines around format-specific melting profiles and shelf stability requirements. Each segment carries distinct margin structures, regulatory exposure, and capital intensity that shape portfolio allocation decisions.
Product Type:
Format selection determines emulsifier load, moisture targets, and distribution channel compatibility.
- Slice:Individually wrapped portions with 40-50% controlled moisture content deliver uniform melt for sandwich applications. Quick-service restaurant procurement in Indonesia and Vietnam concentrates demand here as burger chain expansion accelerates.
- Spread:Pumpable consistency with higher moisture ceiling targets breakfast and snacking occasions outside traditional sandwich use. Reformulation pressure from EU Green Deal packaging mandates is compressing margin for smaller processors lacking R&D scale.
- Shred:Anti-caking coated strands for pizza and baked dish applications.
- Block:Bulk formats for deli slicing and food service portion control.
Slice holds installed capacity. Spread is rotating up the share rankings.
Grade:
Base cheese selection anchors flavor intensity, color specification, and regional preference patterns.
- Cheddar:Sharp to mild flavor gradients achieved through controlled aging of natural cheese inputs. North American retail channels and QSR burger applications concentrate procurement here.
- Mozzarella:Low moisture part-skim specifications with stretch-optimized protein matrices. Pizza chain procurement across Southeast Asia drives volume concentration.
- American:Mild, uniform melt profile standardized for sandwich and burger applications.
- Gouda:Smoked and unsmoked variants for premium positioning in European retail.
Cheddar dominates North American production. Mozzarella is climbing the fastest in Southeast Asian procurement.
Packaging Type:
Barrier properties and shelf-life extension technologies segment cost structures and sustainability exposure.
- Flexible:Multi-layer films with oxygen scavengers for retail sliced formats. FDA identity standards tightening on ingredient disclosure is forcing label redesign cycles.
- Rigid:Thermoformed trays and injection-molded tubs for spread and block formats.
- Tetra Pak:Aseptic carton systems for ambient distribution in tropical climates.
- Bulk:Food service totes and industrial drums capturing long-term contract volumes with reduced price volatility.
Flexible commands retail shelf presence. Bulk is gaining share in industrial procurement consolidation.
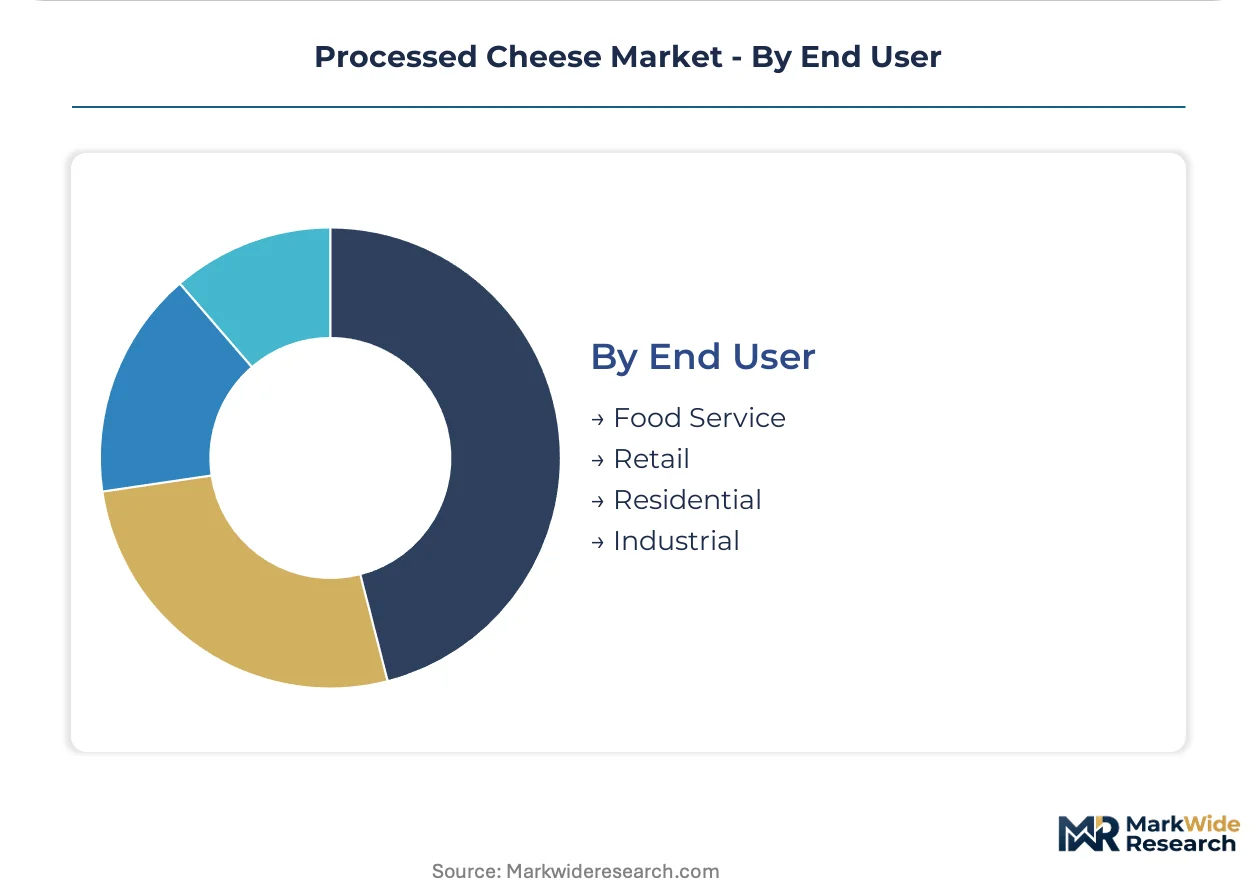
End User:
Customer type dictates formulation flexibility, technical service intensity, and contract structure.
- Food Service:Quick-service restaurant chains and institutional cafeterias requiring melt consistency across equipment variations. Procurement consortia in Ho Chi Minh City and Jakarta metropolitan clusters are compressing supplier negotiation cycles.
- Retail:Supermarket and convenience store channels with front-of-pack labeling compliance burdens across multiple jurisdictions.
- Residential:Direct-to-consumer e-commerce and specialty store volumes.
- Industrial:Food manufacturers incorporating processed cheese as ingredient input for frozen meals and prepared foods.
Food Service holds contract volume concentration. Industrial is expanding most quickly in long-term supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented processors in New Zealand and the Netherlands supply dairy solids to formulation facilities across Southeast Asia, while import-dependent markets in Indonesia and Vietnam expand cold-chain infrastructure to handle growing processed cheese volumes.
United States
Quick-service restaurant chains and retail deli channels absorb the majority of domestic production. FDA updated Standards of Identity tighten ingredient disclosure requirements and constrain formulation flexibility for manufacturers. Chicago and Dallas metropolitan clusters concentrate industrial food service procurement for burger and sandwich applications.
Germany
Private label manufacturers and mid-tier processors drive flexible packaging adoption for retail sliced formats. EU Green Deal emissions targets and sustainable packaging mandates accelerate facility modernization investments. The Rhine-Ruhr industrial corridor hosts HPP equipment installations that compress clean-label trade-offs.
Indonesia
Burger chain expansion and pizza penetration deepen western fast food adoption in Jakarta and Surabaya. BIS certification requirements and FSSAI quality standards constrain import access and shape local formulation adaptations. The Jakarta metropolitan cluster concentrates procurement consortia activity as distributor consolidation accelerates.
Vietnam
Ho Chi Minh City anchors demand concentration for mozzarella specifications in pizza applications. Dairy processing infrastructure modernization expands cold-chain capacity for tropical climate stability. Regional buying cooperatives in the southern economic zone compress supplier negotiation cycles for food service distributors.
India
Spreadable breakfast applications and snacking occasions expand beyond traditional sandwich use in urban centers. FSSAI quality standards and BIS certification create import substitution incentives for domestic processors. Maharashtra and Gujarat industrial corridors attract contract manufacturing investments targeting tropical formulation requirements.
Processed Cheese Market Vendor Landscape
On the supply side, the industry is consolidating around cooperative ownership structures and backward-integrated dairy solids suppliers. Kraft Heinz leverages North American brand equity and retail shelf presence to sustain volume leadership in sliced and block formats. Fonterra Co-operative Group anchors its position through upstream control over New Zealand milk powder supply, securing cost advantages on dairy solids. Arla Foods competes via cooperative ownership structures that stabilize farmer milk pricing and buffer margin volatility. The dominant competitive moves are asset-light contract manufacturing agreements and third-party dairy processing partnerships that tilt dynamics toward outsourcing rather than captive plant construction.
Within the cooperative-anchored tier, Fonterra Co-operative Group and Arla Foods exemplify ownership models that stabilize input costs through farmer-member structures. Kraft Heinz occupies a position representing brand-equity-driven retail presence in North American channels. These three entities sit within distinct strategic archetypes: upstream-integrated dairy solids suppliers, cooperative-owned processors with margin-buffering governance, and brand-dominant consumer goods conglomerates with shelf-space leverage.
| Leading Market Players |
|---|
| Saputo Inc. |
| Fonterra Co-operative Group |
| Kraft Heinz |
| Savencia SA |
| FrieslandCampina |
| Bel Group |
| Arla Foods |
| Dairy Farmers of America |
| Lactalis Group |
| Others |
Supply Flow & Price Mechanics
New Zealand's milk powder processing clusters anchor global dairy solids supply, concentrating upstream pricing power among cooperative-owned processors while downstream food service buyers in Jakarta and Ho Chi Minh City negotiate compressed payment cycles through regional procurement consortia.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across bulk and food service tiers. Price differentiation separates premium clean-label formulations carrying EU Green Deal compliance costs from standard phosphate-emulsified grades and economy private-label retail blocks. Pricing pressure stems from milk powder spot market volatility punishing non-integrated processors without backward integration into New Zealand supply. Quick-service restaurant procurement consortia in Southeast Asia exhibit highest price sensitivity, while pharmaceutical and infant nutrition ingredient buyers tolerate premium positioning for certification-grade dairy solids.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities concentrate working capital burdens on mid-tier processors lacking cooperative ownership structures. New Zealand, the Netherlands, and Germany anchor geographic supply concentration for dairy solids and emulsifier inputs. Raw material dependencies rest on milk powder, citrate-based emulsifiers, and flexible packaging films. Single-source vulnerability runs through New Zealand milk powder supply disruptions from climate or regulatory shocks. Distribution feeds from formulation facilities through cold-chain logistics into regional food service hubs and retail distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Processed cheese procurement is consolidating around platform-economics dynamics where regional buying cooperatives in Southeast Asia unbundle technical service from base supply, creating interoperability pressures between supplier technical capabilities and buyer procurement systems.
For Market Incumbents: Entrench cooperative ownership structures that stabilize farmer milk pricing against Fonterra's upstream control, while accelerating clean-label emulsification R&D to preempt EU Green Deal reformulation mandates. Defend position by locking long-term bulk contracts with industrial food manufacturers before spot market volatility widens margin gaps between integrated and non-integrated processors. For New Entrants and Emerging Players: Build out spreadable breakfast applications and tropical-climate-stable formulations for India's Maharashtra and Gujarat corridors where BIS certification creates import substitution incentives. Target contract manufacturing agreements with asset-light third-party processors in Indonesia and Vietnam rather than captive plant construction, leveraging existing dairy processing infrastructure modernization. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with installed high-pressure processing equipment and clean-label formulation capabilities over legacy phosphate-dependent facilities. Acquisition target archetype: mid-tier European private label manufacturers with HPP capex cycles underway but lacking brand equity for retail channel expansion. Signal to watch: front-of-pack labeling regulation harmonization across EU, India, and Southeast Asian jurisdictions forcing simultaneous reformulation investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Solids | Cooperative ownership structures in New Zealand and Europe stabilize input cost volatility against spot market exposure. |
| Clean-Label Emulsification R&D | Citrate and sodium citrate alternatives to phosphate emulsifiers address REACH restrictions and EU Green Deal mandates. |
| High-Pressure Processing Equipment Deployment | HPP technology migration from premium organic lines to mainstream retail blocks compresses shelf-life trade-offs. |
| Regional Procurement Consortium Participation | Food service distributor consolidation in Jakarta and Ho Chi Minh City clusters compresses supplier negotiation cycles. |
| Tropical Climate Formulation Adaptation | BIS certification and FSSAI quality standards in India create localized production incentives for spreadable grades. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dairy processing plant managers, quick-service restaurant procurement directors, cooperative governance officers, and flexible packaging technical specialists. Secondary validation drew from FDA Standards of Identity filings, EFSA dairy processing emissions guidance, EU Green Deal packaging mandate documentation, BIS certification registries, and FSSAI quality standard notifications. Bottom-up volume modeling across slice, spread, shred, and block formats triangulated against top-down value assessments anchored in milk powder input cost structures.
Calibration against historical capacity utilization rates and emulsifier substitution cost curves shaped projections across the analysis window. Segmentation dimensions modeled include product format, base cheese grade, packaging barrier technology, and end-user channel concentration. CAGRs were derived from elasticity-adjusted demand functions incorporating QSR expansion rates in Southeast Asia and clean-label premium capture assumptions. Forecast inputs included milk powder spot price volatility indices and regulatory compliance cost trajectories for phosphate-to-citrate reformulation cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation-derived dairy protein entrants or rapid harmonization of front-of-pack labeling rules would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
South America Dairy Protein Market
Dairy Products
Oman Dairy Products and Juice Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Europe Milk Protein Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Organic Cheese Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Global Specialty Cheese Market
Dairy Products
Dairy Spreads Market
Dairy Products
Plain Yogurt Market
Dairy Products
Dairy Based Dressings Market
Dairy Products
Global Milk Protein Market
Dairy Products
UHT Whipping Cream Market
Dairy Products
North America Cheese Market
Dairy Products
Lactose-Free Cheese Market
Dairy Products
Global Quark and Fromage Frais Market