
 Australia Nutraceuticals Market | 2026-2036
Australia Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Nutraceuticals Market Outlook
Asset-light contract manufacturing and third-party logistics leasing is rewriting capital requirements for new entrants in Australian nutraceuticals. Blackmores Limited leverages its vertically integrated TGA-licensed facilities to sustain quality premiums across pharmacy channels. Swisse Wellness Pty Ltd anchors its position through aggressive sports-nutrition positioning and celebrity-endorsed branding. Herbalife Nutrition competes via direct-selling networks that bypass traditional retail markups entirely.
Nutraceuticals encompass bioactive compounds, vitamins, minerals, herbal extracts, and probiotics formulated into capsules, powders, liquids, or gummies for physiological benefit beyond basic nutrition. Manufacturing demands TGA-listed Good Manufacturing Practice compliance with stability testing for active ingredient potency through shelf life. Vitamins and probiotics currently dominate pharmacy shelf space, though gummies and liquid formats targeting pediatric and senior palatability are capturing faster growth. Online retail channels are eroding supermarket dominance as subscription models and telehealth referrals redirect purchase behavior toward direct-to-consumer platforms.
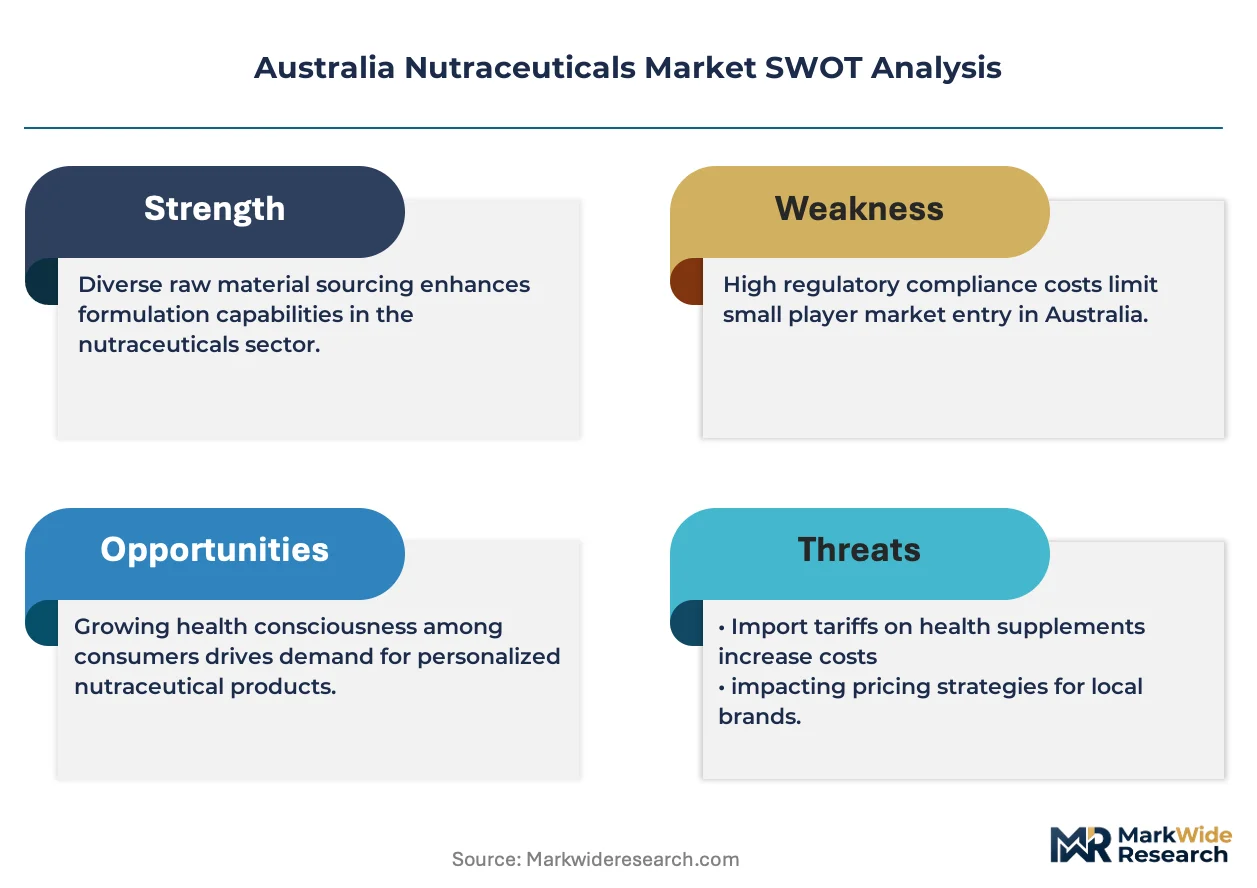
TGA's listed medicine framework and the Therapeutic Goods Advertising Code govern label claims, while Food Standards Australia New Zealand regulates products positioned as functional foods rather than supplements. These overlapping regimes create compliance complexity that favors established players with dedicated regulatory affairs teams. Stakeholders must monitor TGA's pending reforms on permissible indications and the convergence of food-drug boundaries as personalized nutrition platforms gain traction.
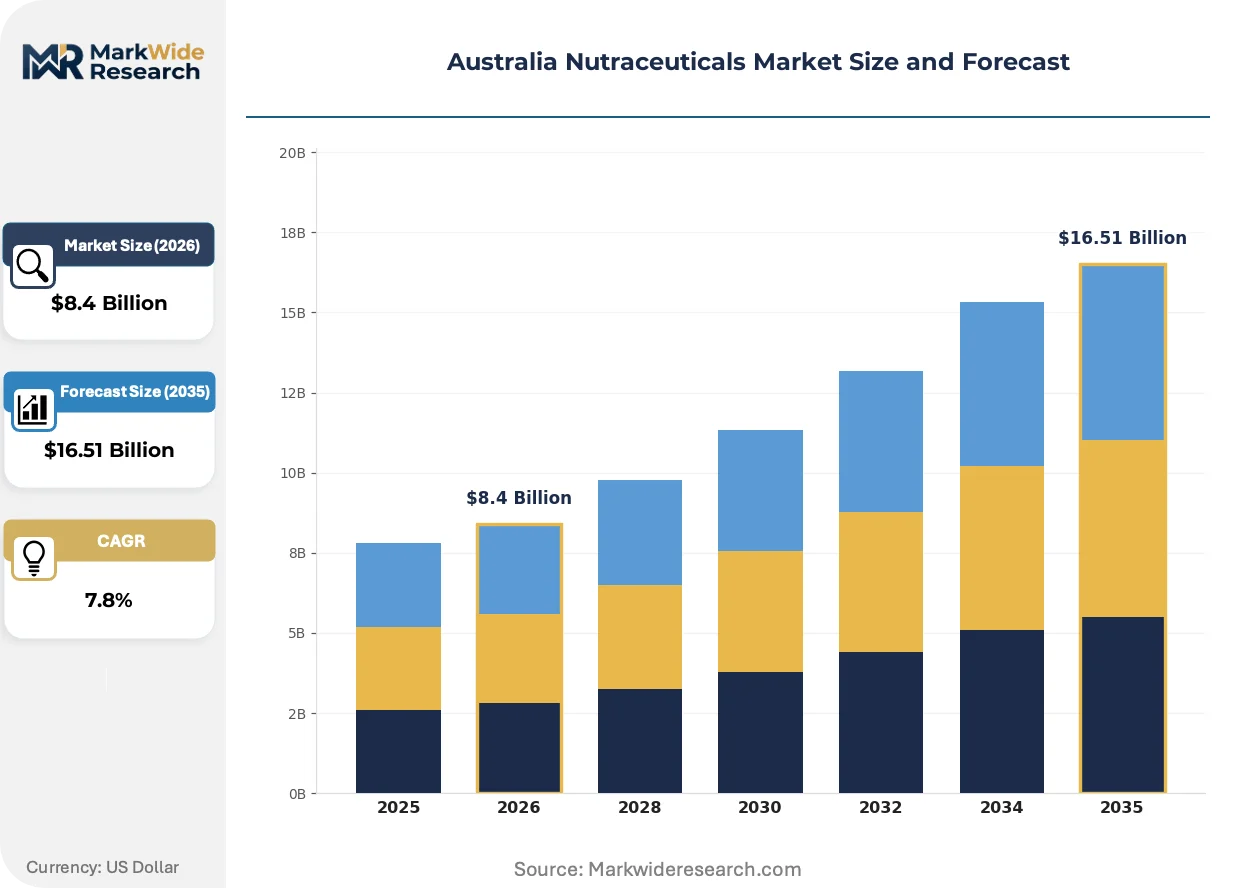
Market Dynamics
TGA's listed medicine framework reforms are compressing formulation-to-shelf timelines while elevating compliance costs, forcing mid-tier manufacturers toward contract manufacturing partnerships or exit.
Growth Catalysts
- Sports nutrition adoption:Amateur athlete participation across triathlon, CrossFit, and endurance cycling is expanding addressable demand beyond traditional bodybuilding segments.
- TGA's evolving complementary medicine framework:Tightening label claims verification is weeding out low-efficacy products, concentrating volume toward clinically substantiated formulations.
- Functional food clustering:Sydney's concentrated R&D infrastructure in New South Wales accelerates co-development between ingredient suppliers and finished goods manufacturers.
Market Restraints
- Active ingredient import dependency:Over 70 percent of probiotic strains and specialized herbal extracts enter through concentrated Asian supply corridors, exposing margins to shipping volatility.
- Stability testing capex:TGA-mandated shelf-life potency verification requires climate-controlled stability chambers that smaller entrants cannot amortize across limited SKU counts.
- Functional food substitution:Fortified beverages and medical foods positioned under Food Standards Australia New Zealand are capturing consumers seeking convenience over capsule regimens.
Strategic Opportunities
- Direct-to-consumer subscription platforms:Telehealth referral networks and algorithm-driven personalization engines are bypassing pharmacy markups entirely.
- Pediatric and senior palatability formats:Gummies and liquid delivery systems remain underdeveloped relative to adult capsule dominance, offering first-mover positioning.
- Regulatory convergence preparation:TGA's pending food-drug boundary reforms will reward early investments in dual-framework compliance infrastructure.
Industry Challenges
- Regulatory affairs talent scarcity:Dual expertise in TGA listed medicines and Food Standards Australia New Zealand functional food regulations commands premium salaries that strain mid-cap payrolls.
- Legacy ERP integration:Batch record digitization for TGA audit trails requires reconfiguring manufacturing execution systems without disrupting continuous production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Nutraceuticals Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Supplements, Probiotics Distribution Channel: Health Stores, Online Retail, Pharmacies, Supermarkets End User: Adults, Seniors, Athletes, Pregnant Women Form: Capsules, Powders, Liquids, Gummies |
| Companies Covered | General Mills, Blackmores Limited, Herbalife Nutrition, Bayer, Swisse Wellness Pty Ltd, Nestlé, Kellanov, GlaxoSmithKline, PepsiCo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Nutraceuticals Market Strategic Shifts
Format innovation and channel disintermediation are compressing traditional go-to-market economics while microbiome science opens new indication territories previously reserved for pharmaceuticals.
Precision fermentation for bioactive peptide production is hybridizing pharmaceutical-grade manufacturing with nutraceutical scale economics. Contract manufacturers in Melbourne and Brisbane are retrofitting antibiotic-era fermentation tanks for lactoferrin and colostrum peptide output. This capability migration is collapsing the historical purity-premium gap between pharmacy-grade and mass-market positioning.
TGA's pending permissible indications reform is narrowing the evidentiary gap between listed medicines and registered therapeutic goods. Manufacturers must now commission randomized controlled trials for digestive health and immune function claims previously supported by traditional use evidence. Early movers with existing clinical trial infrastructure are securing exclusivity windows on reformulated legacy SKUs.
Subscription-based replenishment models are displacing supermarket impulse purchasing as the dominant customer acquisition channel. Melbourne-based telehealth platforms integrate diagnostic biomarker testing with automated supplement curation, locking in twelve-month commitments. This shift concentrates customer lifetime value calculations in Victoria and New South Wales metro corridors where digital health infrastructure is densest.
Australia Nutraceuticals Market Segmentation
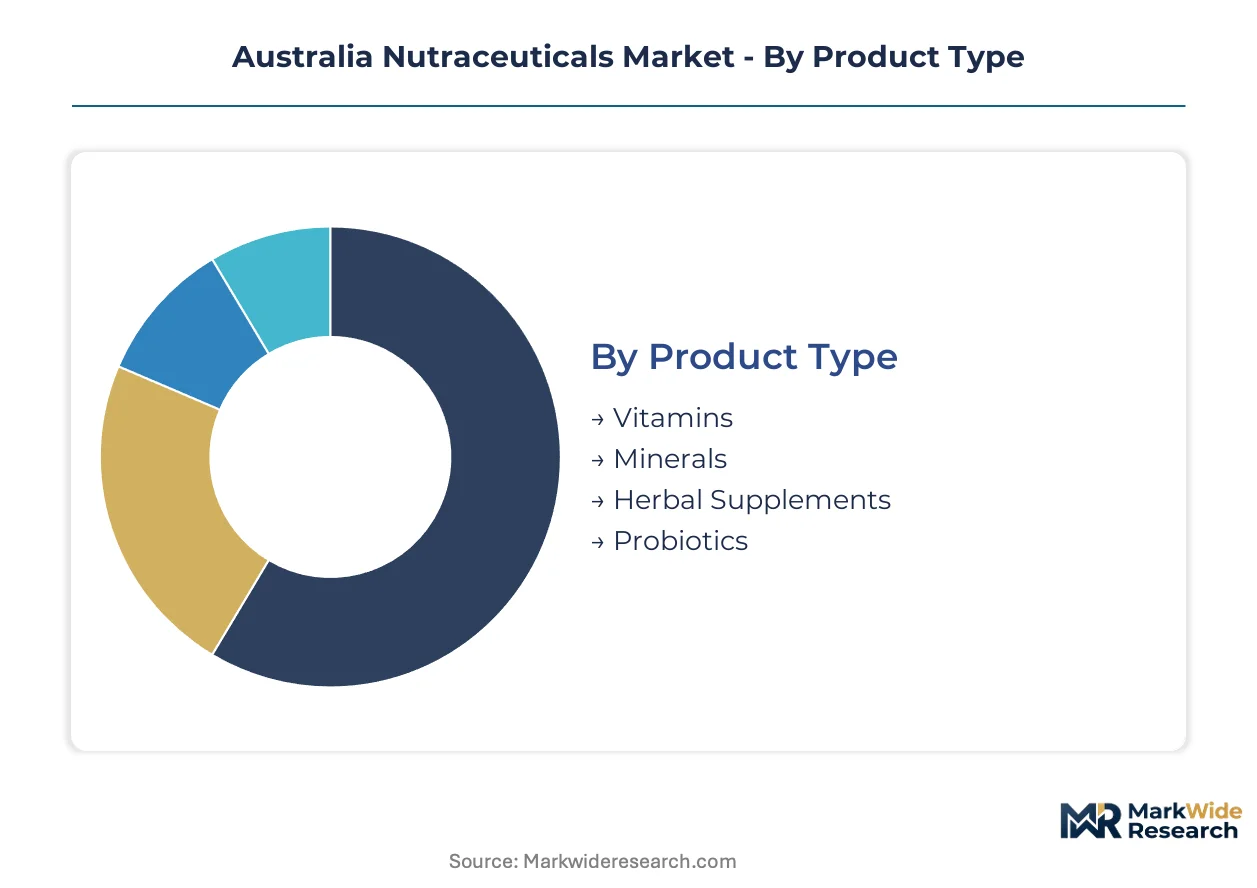
Segmentation in Australian nutraceuticals reveals divergent margin profiles and inventory velocities across product formats and channel mixes. TGA compliance requirements create tiered barriers that concentrate premium positioning in specific delivery systems and verified therapeutic categories.
Product Type:
Vitamins and probiotics turn inventory fastest through pharmacy repeat-purchase programs, while herbal supplements cycle slower due to seasonal demand spikes and traditional-use evidentiary debates.
- Vitamins:Synthetic and natural isolates formulated for deficiency correction and optimization protocols dominate pharmacy shelf space. Demand concentrates in New South Wales metro corridors where preventive health screening rates drive multivitamin adherence. TGA's tightening label claims verification is compressing SKU counts toward clinically substantiated formulations.
- Probiotics:Live microbial strains with defined CFU counts through shelf-life require climate-controlled supply chains and stability chamber verification. Sydney's functional food cluster anchors domestic formulation R&D, though over 70 percent of specialized strains enter via Asian import corridors. Refrigerated logistics capabilities separate pharmacy-grade from mass-market positioning.
- Minerals:Chelated and inorganic forms target deficiency states with slower repurchase cycles than daily multivitamin regimens.
- Herbal Supplements:Traditional use evidence faces TGA reform pressures toward randomized trial standards, elongating new product development timelines.
Vitamins anchor the volume base while probiotics gains share at the steepest rate.
Distribution Channel:
Channel economics stratify by markup capture and customer acquisition cost, with digital platforms collapsing traditional retail margin structures through subscription lock-in.
- Pharmacies:TGA-listed medicine dispensing with trained staff consultation commands premium pricing and repeat loyalty. New South Wales pharmacy density concentrates volume in Sydney's eastern suburbs and North Shore corridors where disposable income supports practitioner-grade recommendations.
- Online Retail:Direct-to-consumer platforms with telehealth integration and algorithm-driven curation bypass wholesale markups entirely. Melbourne-based diagnostic biomarker services anchor subscription replenishment models with twelve-month commitment structures.
- Health Stores:Specialty retailers with trained naturopathic staff serve enthusiast segments seeking practitioner-exclusive lines.
- Supermarkets:Impulse-driven mass-market SKUs face erosion from digital subscription displacement and private label compression.
Pharmacies retain the highest margin per transaction while online retail expands its customer base most aggressively.
End User:
User segments diverge by purchase frequency, price sensitivity, and evidence requirements for efficacy claims.
- Adults:Working-age preventive health seekers drive the largest absolute volume through multivitamin and stress-adaptogen categories. Victoria's white-collar employment corridors show elevated subscription platform penetration.
- Athletes:Amateur triathlon, CrossFit, and endurance cycling participation is expanding addressable demand beyond traditional bodybuilding. Sports nutrition SKUs command formulation premiums for banned-substance testing certification.
- Seniors:Bone health, cognitive function, and mobility formulations target Australia's aging demographic with palatability-format preferences shifting toward liquids and gummies.
- Pregnant Women:Pre-natal vitamin and DHA categories operate under stricter TGA pregnancy claim restrictions with longer purchase cycles per gestational period.
Adults generate the largest revenue pool while athletes deliver the highest growth trajectory in per-capita spending.
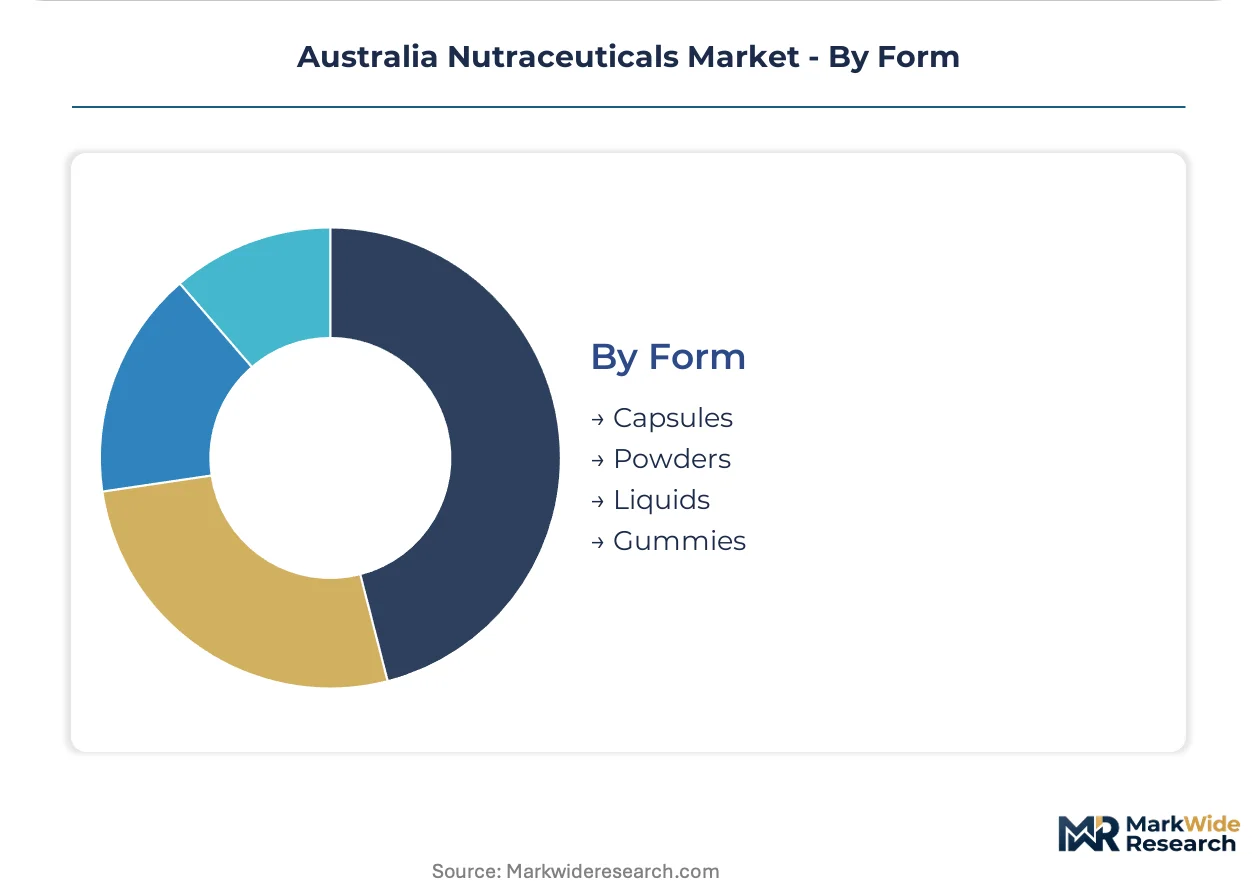
Form:
Manufacturing capital intensity and stability testing requirements create tiered entry barriers across delivery systems.
- Capsules:Hard-shell and soft-gel formats dominate pharmacy-grade positioning with established TGA manufacturing guidelines and shelf-life verification protocols. Powder-in-capsule flexibility supports complex multi-ingredient formulations.
- Gummies:Palatability-driven pediatric and senior segments are capturing faster growth despite higher per-unit manufacturing complexity and moisture-stability challenges. Sugar-free and clean-label variants command manufacturing premiums.
- Powders:Sports nutrition bulk formats with flavor masking systems serve high-dose protein and amino acid categories.
- Liquids:Pediatric, geriatric, and dysphagia applications require preservative systems and bottle stability testing that elevates regulatory compliance costs.
Capsules retain manufacturing volume dominance while gummies climb the fastest in new product launch activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Preventive health seekers and amateur athlete communities concentrate demand across Australia's eastern seaboard metropolitan corridors. State-level regulatory enforcement and R&D infrastructure clustering determine competitive positioning.
New South Wales
Sydney's functional food cluster anchors domestic formulation R&D with concentrated ingredient supplier co-development. TGA's listed medicine framework enforcement tightens fastest in this jurisdiction, elevating compliance costs for entrants lacking dedicated regulatory affairs teams. Eastern suburbs and North Shore pharmacy density supports practitioner-grade multivitamin adherence among high-disposable-income households.
Victoria
Melbourne-based telehealth platforms integrate diagnostic biomarker testing with automated supplement curation, locking in subscription replenishment commitments. White-collar employment corridors show elevated direct-to-consumer platform penetration for stress-adaptogen and nootropic categories. The state's manufacturing execution systems sector supplies batch record digitization capabilities for TGA audit trail compliance.
Queensland
Amateur triathlon and endurance cycling participation drives sports nutrition SKU expansion beyond traditional bodybuilding segments. Gold Coast and Brisbane health store networks serve enthusiast segments seeking practitioner-exclusive herbal lines. Climate-controlled logistics infrastructure separates pharmacy-grade probiotic distribution from mass-market shelf-stable alternatives.
Western Australia
Mining sector fly-in-fly-out workforces generate concentrated demand for immune function and fatigue-management formulations through pharmacy repeat-purchase programs. Perth's geographic isolation elevates shipping cost exposure for active ingredient imports through Asian supply corridors. Local contract manufacturing capacity remains limited relative to eastern state concentration.
Australia Nutraceuticals Market Competitive Environment
Channel-controlling players compete with product-specialist players across pharmacy, direct-selling, and digital subscription vectors. Market structure tilts toward established incumbents with amortized TGA compliance infrastructure and captive pharmacy distribution relationships. Three archetypes dominate: vertically integrated domestic manufacturers with licensed facilities, global CPG conglomerates with portfolio diversification strategies, and direct-selling networks bypassing retail markups entirely. Competitive moves concentrate on M&A for clinical trial capabilities and strategic partnerships for precision fermentation capacity.
Within the vertically integrated domestic tier, Blackmores Limited and Swisse Wellness Pty Ltd exemplify archetypes leveraging TGA-licensed facilities and aggressive sports-nutrition positioning respectively. Herbalife Nutrition occupies a distinct channel position through direct-selling network architecture that bypasses traditional retail economics entirely. These three anchors represent divergent capital deployment strategies: captive manufacturing quality premiums, celebrity-endorsed brand equity accumulation, and disintermediated margin capture.
| Leading Market Players |
|---|
| General Mills |
| Blackmores Limited |
| Herbalife Nutrition |
| Bayer |
| Swisse Wellness Pty Ltd |
| Nestlé |
| Kellanov |
| GlaxoSmithKline |
| PepsiCo |
| Others |
Value Chain & Pricing Dynamics
Sydney's functional food cluster concentrates TGA-licensed manufacturing capacity, translating compliance infrastructure scarcity into pricing power for domestic formulators serving pharmacy-grade channels.
Pricing Analysis
Certification level (TGA-listed versus registered therapeutic goods) creates the primary spread between pharmacy-grade premiums and mass-market positioning. Three-tier pricing structure across practitioner-exclusive, retail pharmacy, and supermarket private-label tiers reflects stability testing investment amortization. Cost compression in mass-market SKUs is intensifying because private-label substitution erodes brand premiums. Supermarket impulse buyers exhibit highest price sensitivity while telehealth-integrated subscription customers show lowest elasticity.
Supply Chain Analysis
Tariff exposure between Australia and concentrated Asian supply corridors dominates margin volatility for probiotic strains and specialized herbal extracts. Manufacturing inputs draw from China, India, and South Korea for active pharmaceutical-grade compounds. Single-source vulnerability concentrates in refrigerated logistics for live microbial strains. Distribution runs through pharmacy wholesale networks with direct-to-consumer platforms bypassing traditional tiered markups entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual-framework regulatory expertise commands salary premiums that strain mid-cap payrolls, creating acquisition opportunities for players with pre-built TGA and Food Standards Australia New Zealand compliance teams.
For Market Incumbents: Pre-empt subscription platform displacement by acquiring Melbourne-based telehealth infrastructure with biomarker integration capabilities. Defend pharmacy channel positioning through exclusive practitioner-line extensions that supermarket private labels cannot replicate. Lock in precision fermentation capacity via contract manufacturing partnerships before fermentation tank retrofitting costs escalate. For New Entrants and Emerging Players: Establish a beachhead in pediatric gummy formats where manufacturing complexity has delayed incumbent response. Target Queensland's amateur athlete communities with banned-substance-certified sports nutrition SKUs underserved by mass-market positioning. Launch through direct-to-consumer subscription models to bypass pharmacy wholesale margin capture entirely. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telehealth-integrated subscription platforms with twelve-month commitment structures. Five-to-ten-year viability favors targets with amortized TGA stability chamber infrastructure and existing clinical trial relationships for permissible indications reform. Watch TGA's permissible indications implementation timeline as the inflection signal for SKU rationalization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Partnership | Retrofitting antibiotic-era tanks for lactoferrin production collapses purity-premium gaps. |
| Telehealth Platform Integration | Melbourne-based biomarker services lock twelve-month subscription commitments through algorithmic curation. |
| Dual-Framework Compliance Investment | Early TGA and Food Standards Australia New Zealand infrastructure readiness captures reform windows. |
| Pediatric Format Manufacturing Scale-Up | Gummy and liquid production lines address senior and pediatric palatability gaps faster than incumbents. |
| Clinical Trial Infrastructure Acquisition | Randomized controlled trial capability secures exclusivity on reformulated legacy SKUs under tightened evidentiary standards. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with TGA regulatory affairs leads, pharmacy procurement managers, contract manufacturing executives, and telehealth platform operators; and secondary validation against TGA listed medicine registers, Food Standards Australia New Zealand code amendments, pharmacy wholesale transaction data, and subscription platform customer commitment disclosures. Bottom-up SKU-level volume builds were triangulated against top-down category expenditure estimates from preventive health screening correlation analysis.
Forecast inputs span product type, distribution channel, end-user demographic, and delivery form dimensions across the analysis window. CAGRs derive from segment-level growth rate differentials applied to base-year market sizing. TGA reform implementation pace and precision fermentation capacity expansion curves serve as scenario-weighting variables.
Sensitivities concentrate around TGA permissible indications reform timing and Asian supply corridor shipping volatility. Forecasts reflect documented assumptions on subscription platform penetration curves and stability testing cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
Calcium HMB Market
Nutritional Supplements
Energy Supplements Market
Nutritional Supplements
Nutritional Drink Market
Nutritional Supplements
Native Whey Protein Market
Nutritional Supplements
Whey Hydrolysates Market
Nutritional Supplements
Energy Gums Market
Nutritional Supplements
North America Whey Protein Market
Nutritional Supplements
Chewable Energy Tablet Market
Nutritional Supplements
Hydroxymethylbutyrate (HMB) Market
Nutritional Supplements
Europe Nutrition and Supplements Market
Nutritional Supplements
Global Antioxidant Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Hair Growth Supplements Market
Nutritional Supplements
South America Botanical Supplements Market
Nutritional Supplements
US Nutraceuticals Market