
 Elderberry Supplements Market | 2026-2036
Elderberry Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Elderberry Supplements Market Foresight
Multi-source botanical sourcing is restructuring supply security across the elderberry supplements industry. Nature's Way Products leverages vertically integrated herb procurement to secure raw material consistency. Gaia Herbs sustains competitive differentiation through certified organic cultivation partnerships in Eastern Europe. NOW Health Group anchors manufacturing scale with in-house encapsulation and liquid extraction capabilities.
Elderberry supplements deliver standardized anthocyanin extracts from Sambucus nigra fruit, typically processed through cold-pressing or ethanol extraction to preserve flavonoid integrity for immune modulation applications. Liquid extracts and gummies capture disproportionate growth momentum as consumers prioritize palatability and rapid absorption over traditional capsule formats. Organic and non-GMO formulation segments command premium positioning, while sugar-free variants expand addressable reach among diabetic and ketogenic diet adherents.
The FDA enforces Current Good Manufacturing Practice regulations for dietary supplements, mandating identity testing and contamination screening that elevates compliance costs for new entrants. EFSA novel food assessments govern European market access for concentrated elderberry extracts. Third-party certifications from NSF International and USP verify potency claims, creating a dual-layer quality barrier that stakeholders must navigate to sustain channel placement.
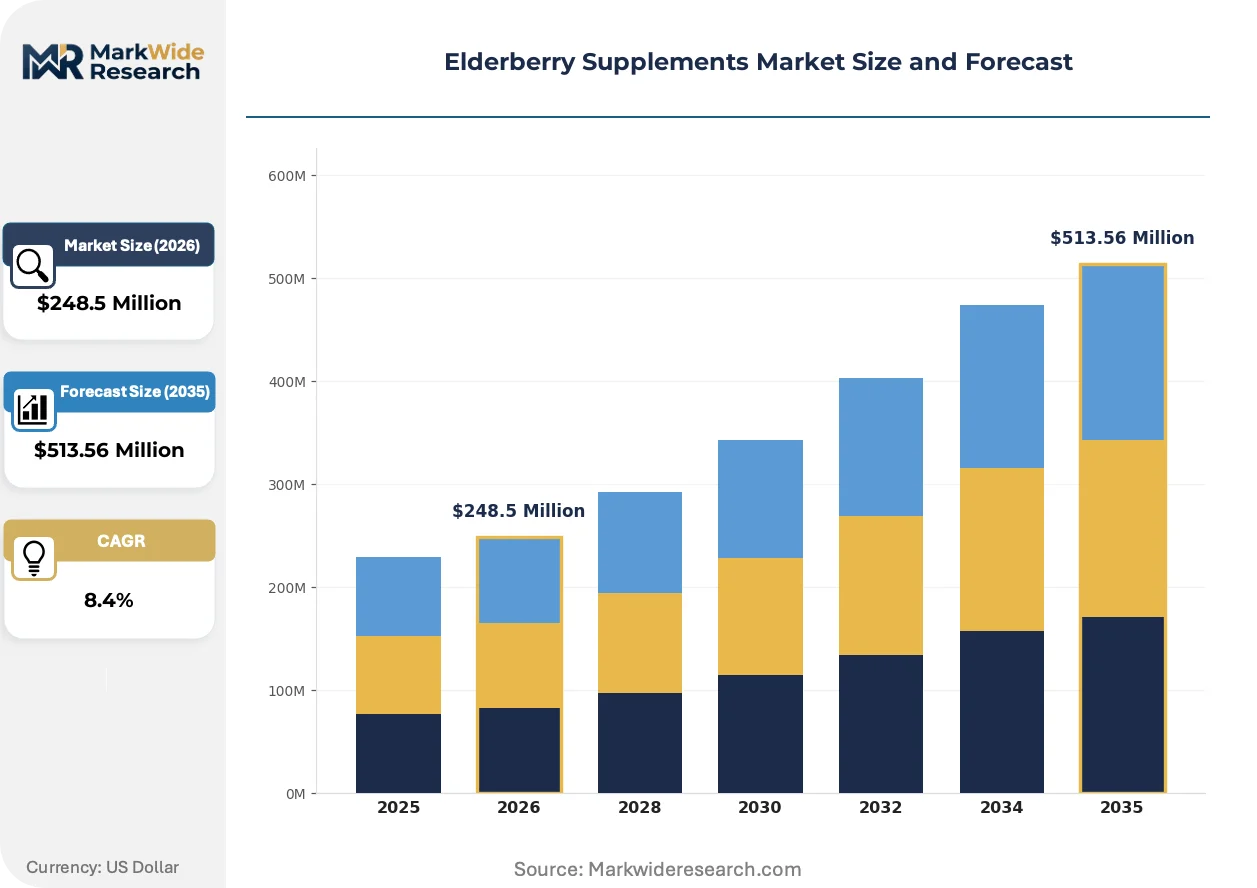
Market Dynamics
The elderberry supplements market is being fundamentally restructured by the FDA's Current Good Manufacturing Practice enforcement, which mandates identity testing and contamination screening that elevates compliance costs and consolidates competitive position among scaled manufacturers capable of absorbing regulatory overhead.
Growth Catalysts
- DSHEA Label Framework:The FDA's Dietary Supplement Health and Education Act provides a structured pathway for immune-support claims, enabling direct-to-consumer wellness brands to market elderberry anthocyanin extracts with validated positioning.
- Ketogenic Diet Expansion:Sugar-free gummy and liquid extract formats are capturing diabetic and ketogenic diet adherents, broadening addressable consumer segments beyond traditional capsule users.
- Organic Cultivation Partnerships:Certified organic Sambucus nigra sourcing from Eastern European growing regions is securing supply consistency for premium-positioned extractors seeking non-GMO verification.
Market Restraints
- Raw Material Volatility:European elderberry harvest fluctuations and climate-dependent yield variability in primary growing regions create input cost instability for extract processors.
- EFSA Novel Food Assessments:European market access for concentrated elderberry extracts faces extended safety evaluation timelines that delay product launches and tie up regulatory capital.
- Standardization Complexity:Anthocyanin potency variation between Sambucus nigra cultivars and extraction methods complicates batch consistency for manufacturers seeking USP verification.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Immune-conscious adult consumers in the United States are migrating toward recurring delivery formats that lock in lifetime value and reduce customer acquisition costs.
- Third-Party Certification Premiumization:NSF International and USP verification programs create dual-layer quality barriers that allow certified manufacturers to command shelf-space advantages in premium retail channels.
- Liquid Extract Palatability Innovation:Rapid-absorption delivery formats are displacing traditional capsules among pediatric and geriatric segments seeking ease of administration.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Flavonoid quantification and HPLC-based anthocyanin profiling require specialized laboratory personnel that mid-scale manufacturers struggle to recruit and retain.
- Cold-Chain Integration Complexity:Ethanol extraction and cold-pressing preservation methods demand temperature-controlled logistics that fragment distribution economics for national rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elderberry Supplements Market |
| Market Size in 2026 | $248.5 Million |
| Market Size in 2035 | $513.56 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Liquid Extracts, Gummies, Powders Formulation: Organic, Non-GMO, Vegan, Sugar-Free Distribution Channel: Retail Stores, E-commerce, Health Food Shops, Pharmacies End User: Adults, Children, Seniors, Athletes |
| Companies Covered | Nature's Way Products, Nature's Sunshine Products, Sambucol USA, Herbalife International of America, NOW Health Group, Gaia Herbs, Nature's Answer, Nutraceutical Corporation, Quantum Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elderberry Supplements Market Shifts & Advancements
Processing technology and verification protocols are compressing production timelines while reshaping how elderberry extracts demonstrate bioactive integrity to immune-conscious consumers.
Supercritical CO2 extraction systems are automating flavonoid recovery from Sambucus nigra fruit at temperatures below ethanol-based methods, preserving heat-sensitive anthocyanin structures. Premium supplement manufacturers in the United States are retrofitting mid-scale facilities with these units to secure organic certification compliance. The technology is automating potency standardization that previously required manual batch adjustment, compressing quality control labor by half.
EFSA novel food safety assessments are extending evaluation timelines for concentrated elderberry extracts entering European commerce, forcing manufacturers to front-load toxicology documentation. The industrial consequence is a two-tier market where legacy extractors with grandfathered status hold shelf-positioning advantages over new entrants. German and French regulators are applying heightened scrutiny to immune-modulation claims, prompting reformulation toward structure-function language.
Subscription-based replenishment programs are displacing one-time retail purchases among United States direct-to-consumer wellness buyers, locking in predictable offtake for scaled manufacturers. Amazon and specialized health platforms are capturing channel share from brick-and-mortar pharmacy placements. This shift concentrates demand forecasting risk with fulfillment-integrated brands capable of managing inventory turns across monthly delivery cycles.
Elderberry Supplements Market Segmentation
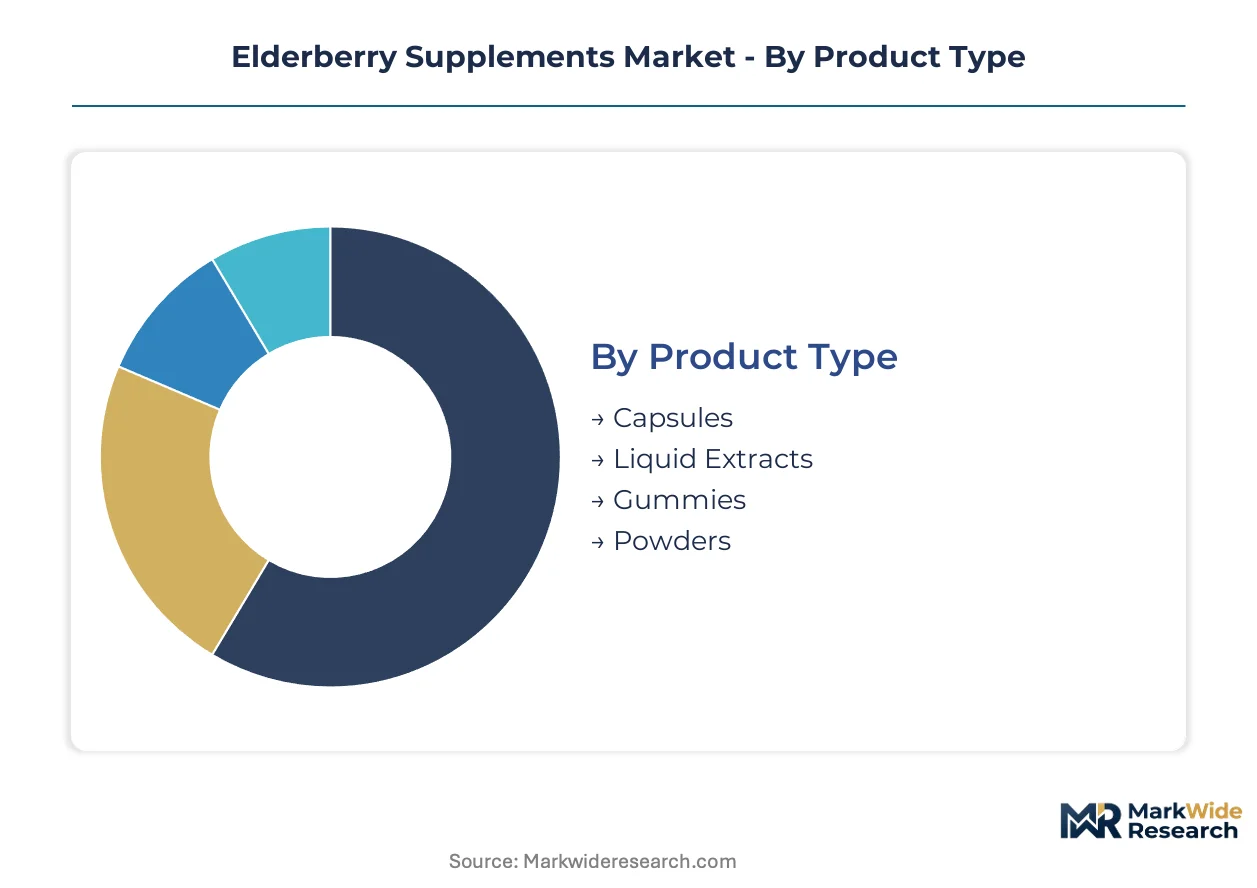
Elderberry supplement manufacturers configure production lines around format-specific extraction and encapsulation requirements. Each segment carries distinct capital commitments for equipment, certification, and cold-chain logistics that shape competitive entry barriers.
Product Type:
Capital intensity varies sharply across formats, with liquid extraction systems demanding the highest upfront equipment investment and gummy production requiring specialized molding and coating infrastructure.
- Liquid Extracts:Ethanol or glycerin-based solutions preserve anthocyanin bioactivity through cold-processing. Demand clusters among pediatric and geriatric users in the United States seeking rapid absorption without swallowing difficulty. Cold-chain distribution requirements elevate per-unit logistics costs.
- Gummies:Pectin or gelatin matrices incorporate standardized Sambucus nigra extract with palatability masking. Sugar-free variants capture diabetic and ketogenic diet adherents through alternative sweetener formulations. Manufacturing requires humidity-controlled coating tunnels.
- Capsules:Hard gelatin or vegetable cellulose shells deliver powdered extract with extended shelf stability. Lower production complexity supports private-label manufacturing at reduced capital thresholds.
- Powders:Bulk anthocyanin concentrate for beverage fortification and custom compounding. Minimal processing beyond spray-drying reduces equipment requirements.
Capsules absorb the bulk of installed capacity; gummies are expanding most quickly.
Formulation:
Certification tiering separates price positioning, with organic and non-GMO segments commanding premium shelf placement through verified supply chain documentation.
- Organic:Sambucus nigra sourced from certified cultivation partnerships in Eastern Europe requires third-party verification of pesticide-free growing practices. USDA Organic and EU organic seals unlock premium retail placement in natural food channels.
- Sugar-Free:Stevia, monk fruit, or allulose substitutions enable ketogenic and diabetic market access. Formulation complexity increases with taste-masking requirements.
- Non-GMO:Identity preservation protocols from seed to finished product satisfy verification programs. Project Non-GMO certification requires segregated handling infrastructure.
- Vegan:Plant-based capsule materials and exclusion of animal-derived processing aids. Growing demand among ethically motivated consumers in Germany and the United Kingdom.
Organic formulations absorb the bulk of installed capacity; sugar-free variants are climbing the fastest.
Distribution Channel:
Channel selection determines working capital intensity, with e-commerce requiring fulfillment infrastructure and retail demanding slotting fee commitments.
- E-commerce:Direct-to-consumer platforms and Amazon marketplace capture recurring subscription revenue. Inventory turnover pressure concentrates with fulfillment-integrated brands managing monthly delivery cycles.
- Pharmacies:Chain and independent drugstores stock elderberry alongside cough and cold remedies. Pharmacist recommendation drives trial among condition-specific buyers.
- Health Food Shops:Independent natural retailers and co-ops prioritize local and certified organic suppliers. Smaller order quantities elevate per-unit distribution economics.
- Retail Stores:Mass-market grocery and big-box placements reach immune-conscious mainstream consumers. Category management demands promotional spending and shelf-space negotiations.
Retail stores absorb the bulk of installed capacity; e-commerce is gaining share fastest.
End User:
Demographic targeting shapes dosage standardization and palatability engineering, with pediatric and senior segments requiring format adaptation.
- Adults:Working-age immune-conscious consumers drive baseline demand through seasonal supplementation patterns. Capsule and liquid preferences split by convenience versus absorption priorities.
- Seniors:Swallowing difficulty and polypharmacy concerns elevate liquid and gummy preference. Medicare-adjacent retail channels capture this segment.
- Children:Palatability-driven gummy formats dominate with reduced dosage concentrations. Parental purchasing decisions prioritize safety certification and clean label positioning.
- Athletes:Recovery and immune resilience positioning targets competitive and recreational sports participants. NSF Certified for Sport verification opens collegiate and professional team access.
Adults absorb the bulk of installed capacity; seniors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Balkan and Eastern European Sambucus nigra cultivation belts anchor raw material flows for the elderberry supplements industry, with harvest volumes from Bulgaria and Poland conditioning global extract availability.
United States
Immune-conscious adult consumers in the United States drive premium supplement uptake through direct-to-consumer wellness brands and pharmacy retail channels. The FDA's Dietary Supplement Health and Education Act structures permissible label claims for anthocyanin extracts, creating compliance thresholds that favor scaled manufacturers. Utah and Colorado host concentrated supplement manufacturing clusters where encapsulation and liquid extraction facilities cluster near distribution infrastructure.
Germany
German consumers demonstrate strong preference for certified organic elderberry formulations through pharmacy and health food retail networks. EFSA novel food assessments govern market access for concentrated extracts, extending evaluation timelines that protect incumbent suppliers. Bavaria and Baden-Württemberg house analytical testing laboratories that verify anthocyanin potency for brands seeking EU organic certification compliance.
United Kingdom
United Kingdom demand clusters around gummy and liquid formats targeting pediatric and geriatric immune support applications. The Food Standards Agency applies novel food consultation requirements to concentrated elderberry extracts not consumed pre-1997. Greater London and the Southeast concentrate direct-to-consumer brand headquarters managing subscription fulfillment across domestic and export markets.
France
French consumers prioritize structure-function positioning over immune-modulation claims following ANSM scrutiny of botanical supplement marketing. EU organic regulations and AB certification requirements shape sourcing decisions for premium-positioned extractors. The Provence-Alpes-Côte d'Azur region hosts traditional herbal medicine manufacturers integrating elderberry into multi-botanical immune formulations.
Canada
Canadian market access requires Natural Health Product Directorate licensing for elderberry extracts making therapeutic claims, creating regulatory capital requirements that filter new entrants. Health Canada monograph compliance permits specific dosage and use statements for Sambucus nigra preparations. Ontario and British Columbia concentrate natural health product distribution infrastructure serving both domestic demand and cross-border e-commerce fulfillment.
Elderberry Supplements Market Competitive Landscape
Third-party certification premiumization dominates the current landscape as manufacturers seek shelf-space advantages through NSF International and USP verification programs. The competitive structure stratifies across scaled integrated producers, certified organic specialists, and private-label contract manufacturers serving retail channel partners. Three archetypes occupy distinct positions: vertically integrated herb processors controlling cultivation through finished goods, certified organic extractors leveraging Eastern European partnerships, and fulfillment-integrated direct-to-consumer brands managing subscription economics. Competitive intensity concentrates around M&A activity targeting organic cultivation assets and strategic partnerships securing cold-chain distribution capacity.
Within the integrated processing tier, Nature's Way Products and NOW Health Group exemplify scaled manufacturers with in-house encapsulation and extraction capabilities. Gaia Herbs occupies a position among certified organic specialists sourcing from Eastern European cultivation partnerships. These three entities anchor the competitive landscape without exhaustively representing its full composition.
| Leading Market Players |
|---|
| Nature's Way Products |
| Nature's Sunshine Products |
| Sambucol USA |
| Herbalife International of America |
| NOW Health Group |
| Gaia Herbs |
| Nature's Answer |
| Nutraceutical Corporation |
| Quantum Health |
| Others |
Supply & Pricing Matrix
Anthocyanin standardization costs from Sambucus nigra fruit cascade through three distinct pricing tiers, with organic certification and USP verification separating premium extractors from commodity suppliers serving private-label contract manufacturers.
Pricing Analysis
Third-party certification bundling determines price positioning, with NSF International and USP verification included in premium tier quotes while standard tiers strip out laboratory testing costs. Price differentiation rests on organic cultivation documentation and cold-chain logistics capability, with verified Eastern European sourcing commanding shelf-space premiums. Cost compression in economy tiers is intensifying as raw material volatility from Bulgarian and Polish harvest fluctuations squeezes margin buffers. Private-label contract manufacturers exhibit highest price sensitivity, whereas direct-to-consumer wellness brands absorbing certification costs demonstrate lowest sensitivity due to subscription lock-in effects.
Supply Chain Analysis
Direct-to-consumer platforms and Amazon marketplace fulfillment centers handle recurring subscription demand from immune-conscious United States buyers, with cold-chain distribution networks fragmenting national rollout economics. Raw material supply concentrates in Bulgaria, Poland, and Romania, where Sambucus nigra cultivation belts anchor global anthocyanin extraction capacity. Finished production draws from ethanol extraction equipment and encapsulation infrastructure clustered in Utah and Colorado manufacturing hubs. Single-source vulnerability around Eastern European harvests creates input cost instability, with climate-dependent yield variability threatening batch consistency for scaled extract processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from FDA Current Good Manufacturing Practice enforcement is filtering mid-scale manufacturers unable to absorb identity testing and contamination screening overhead, compressing the vendor base toward integrated processors with captive laboratory capabilities.
For Market Incumbents: Deepen backward integration into certified organic Sambucus nigra cultivation partnerships across Eastern European growing regions to secure non-GMO verification and supply consistency. Expand in-house HPLC-based anthocyanin profiling capacity to reduce dependence on scarce analytical chemistry talent, defending against emerging entrants leveraging third-party testing shortcuts. For New Entrants and Emerging Players: DSHEA label framework compliance in the United States opens a window for structure-function positioning without therapeutic claim scrutiny, enabling white-space capture among ketogenic and diabetic segments through sugar-free gummy innovation. Target senior and pediatric end users with liquid extract palatability engineering, deploying direct-to-consumer subscription models to bypass slotting fee barriers in mass retail pharmacy channels. For Investors and Strategic Acquirers: M&A activity targeting organic cultivation assets is the leading indicator that supply security premiumization is accelerating competitive stratification. Five-to-ten-year viability favors vertically integrated extractors with cold-chain distribution partnerships over pure-play contract manufacturers. Watch for EFSA novel food assessment clearance timelines as the signal for European market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captive Sambucus nigra supply from Bulgarian partnerships secures non-GMO verification tier. |
| Third-Party Certification Investment | USP and NSF International verification unlocks premium pharmacy shelf-space positioning. |
| Cold-Chain Distribution Partnership | Temperature-controlled logistics capacity enables liquid extract national rollout economics. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models reduce customer acquisition costs among immune-conscious adults. |
| Sugar-Free Formulation Expansion | Stevia and monk fruit substitutions capture ketogenic and diabetic diet adherents. |
Research Methodology
Independent corroboration across supplement brand executives, FDA regulatory consultants, Eastern European cultivation cooperative managers, and pharmacy retail buyers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through FDA warning letter databases, USDA organic certification records, EFSA novel food assessment documentation, and customs trade flows for Sambucus nigra raw material shipments. Bottom-up segment sizing triangulated against top-down category expenditure estimates from health food retail audit data.
Comparable historical periods anchored volume and value projections across the analysis window, with segmentation modeling spanning product format, certification tier, distribution channel, and end-user demographic dimensions. CAGRs derived from fitted growth curves incorporating raw material harvest variability, regulatory assessment timeline distributions, and channel shift velocity parameters. Forecast inputs included organic cultivation partnership expansion rates and cold-chain logistics capacity buildout trajectories.
Caveats apply where EFSA novel food safety evaluation extensions or FDA enforcement intensity shifts could materially shift the outlook. Forecasts reflect assumptions around sustained immune-conscious consumer behavior and stable Eastern European agricultural output. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Raspberry Ketones Market
Nutritional Supplements
Energy Supplements Market
Nutritional Supplements
Vegan Protein Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Global Beta-Alanine Market
Nutritional Supplements
Chia-Based Protein Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
South America Botanical Supplements Market
Nutritional Supplements
Spirulina Purple Blend Market
Nutritional Supplements
Stress Relief Supplements Market
Nutritional Supplements
North America Insoluble Dietary Fibers Market
Nutritional Supplements
Asia-Pacific Dietary Supplement Market
Nutritional Supplements
Dietary Supplement Cultures Market
Nutritional Supplements
Bone Broth Protein Powder Market