
 Paneer Market | 2026-2036
Paneer Market Size, Share, and Industry Trends Forecast 2026-2036
Paneer Market Intelligence
Traditional dairy distribution through local milk cooperatives is fragmenting as organized retail and e-commerce platforms capture share from unbranded vendors. Amul leverages its Gujarat Cooperative Milk Marketing Federation infrastructure to dominate branded paneer across Indian states. Fonterra competes through specialized dairy protein technology and export-grade production systems. Parag Milk Foods anchors its position with dedicated paneer manufacturing facilities and direct-to-retailer supply contracts.
Paneer is a fresh acid-set cheese made by curdling heated milk with food-grade acids such as citric acid or vinegar, then pressing the coagulated curds into a firm block with typical moisture content of 50-55 percent and protein content around 18-20 percent. The product serves as a primary protein source in vegetarian diets and functions as a versatile ingredient across residential cooking, foodservice operations, and industrial food manufacturing. Fresh paneer leads volume but carries shorter shelf life and higher logistics costs, while processed paneer variants with extended shelf stability are capturing growth in supermarket and online retail channels where vacuum packs and modified atmosphere packaging reduce spoilage rates. The food processing industry segment demands standardized cube sizes and consistent texture for ready-meal applications, creating margin pools distinct from commodity fresh blocks sold through local dairy shops.
FSSAI standards govern microbial limits and labeling requirements for paneer sold across Indian states, while BIS certification marks indicate adherence to national quality benchmarks for dairy fat content and moisture parameters. The EU's EFSA dairy hygiene regulations and CE marking requirements shape export market access for Indian and New Zealand producers targeting European food manufacturers. Stakeholders must monitor evolving cold chain infrastructure investments and shifting certification requirements as retail channels expand beyond traditional wholesale markets.
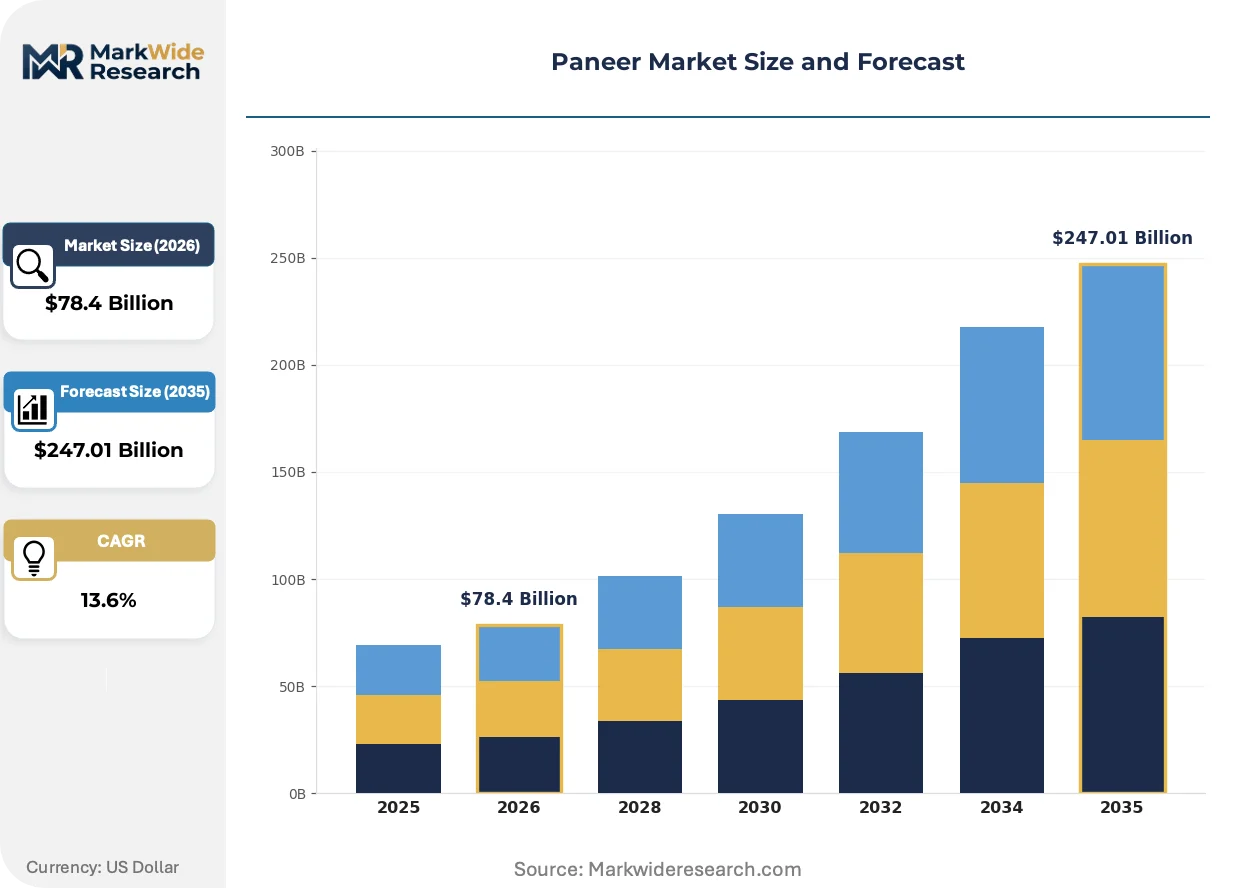
Market Dynamics
India's FSSAI microbial tightening for fresh dairy products is compressing shelf life tolerances and forcing cold chain infrastructure upgrades across Maharashtra and Gujarat distribution networks. Organized retail and e-commerce platforms capture share from unbranded local milk cooperatives, fragmenting traditional supply relationships.
Growth Catalysts
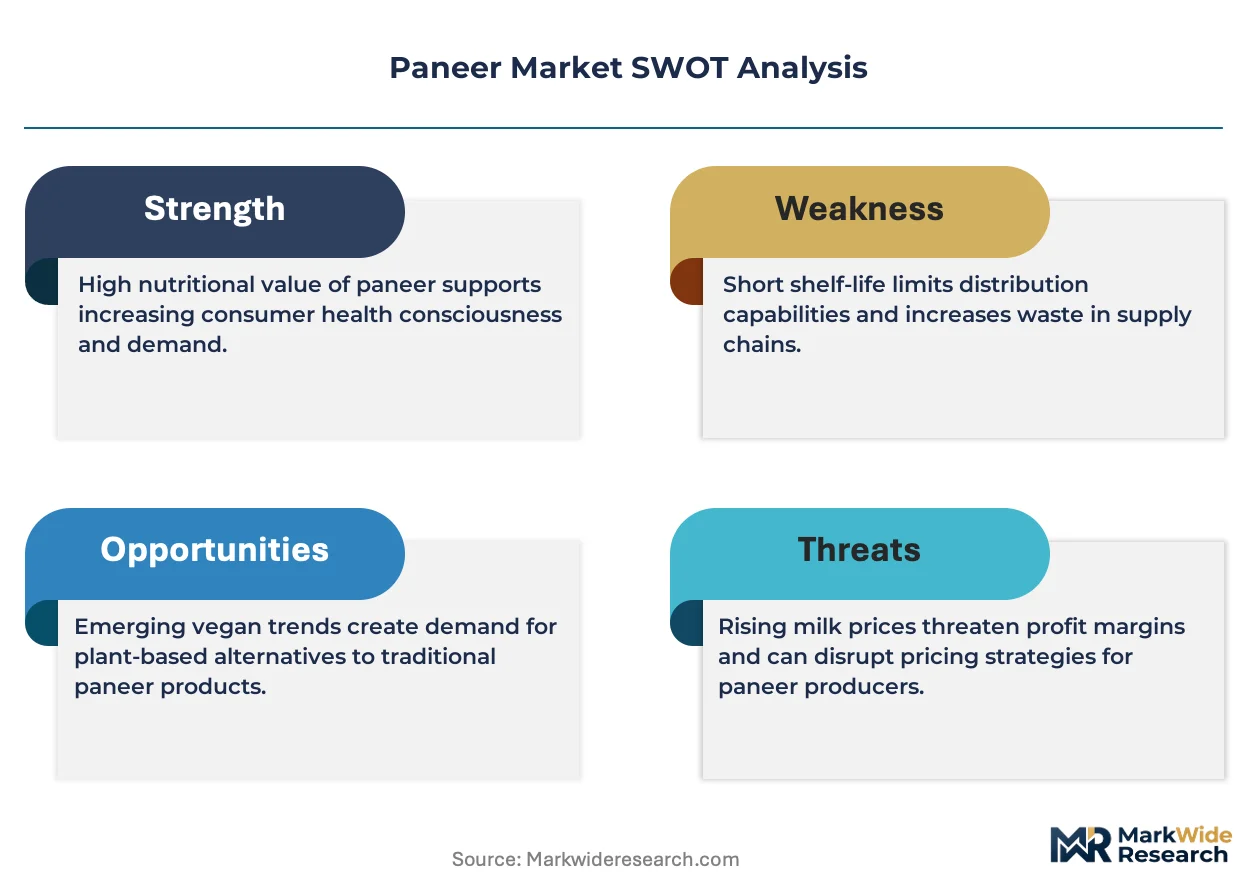
- Urban protein demand:Quick-service restaurant chains across South Asia expand paneer-based menu offerings, pulling standardized cube formats into foodservice procurement specifications.
- Modified atmosphere packaging:Vacuum-pack technology extends shelf stability for processed paneer variants, reducing spoilage rates in supermarket and online retail channels.
- FSSAI compliance infrastructure:Tightened standards create barrier-to-entry advantages for organized players with certified cold chain capabilities over unbranded vendors.
Market Restraints
- Fresh product logistics:Fresh paneer carries 50-55 percent moisture content and shorter shelf life, elevating refrigerated transport costs versus UHT milk substitutes.
- Input concentration:Milk supply volatility in Gujarat and Maharashtra cooperative networks creates margin pressure for processors without backward integration into dairy farming.
- Export certification friction:EU EFSA dairy hygiene regulations and CE marking requirements block Indian producers from European food manufacturing supply chains.
Strategic Opportunities
- Ready-meal industrial formats:Food processing demand for standardized cube sizes and consistent texture creates margin pools distinct from commodity fresh blocks.
- E-commerce direct channels:Online retail penetration in Indian tier-2 cities enables bypass of traditional wholesale market intermediaries.
- BIS certification differentiation:National quality benchmarks for dairy fat content and moisture parameters allow premium positioning against unmarked competitors.
Industry Challenges
- Cold chain capex intensity:Refrigerated warehousing and last-mile delivery infrastructure requires capital deployment that fragments returns across small-batch fresh production.
- Microbial testing timelines:FSSAI compliance documentation delays batch release, compressing effective shelf life for perishable inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paneer Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Paneer, Processed Paneer, Grated Paneer, Paneer Cubes Distribution Channel: Supermarkets, Online Retail, Wholesale Markets, Local Dairy Shops End User: Households, Restaurants, Caterers, Food Processing Industry Packaging Type: Bags, Boxes, Vacuum Packs, Tubs |
| Companies Covered | Saras (Rajasthan Cooperative Dairy Federation), Ananda Dairy, Amul (Gujarat Cooperative Milk Marketing Federation), Fonterra, Arla Foods, Parag Milk Foods, VRS Foods, Beijing Sanyuan, Mother Dairy Fruits & Vegetables, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paneer Market Strategic Shifts & Innovations
Processing technology and packaging formats are converging to extend paneer shelf stability while preserving texture characteristics valued in traditional cooking applications. Regulatory pressure on microbial standards accelerates capital deployment into controlled-environment manufacturing.
High-pressure processing technology is hybridizing thermal pasteurization with non-thermal microbial reduction, extending refrigerated shelf life without altering protein structure. Ready-meal manufacturers in Mumbai and Ahmedabad adopt these systems to secure consistent supply contracts with quick-service chains. The technology is hybridizing fresh and processed category boundaries, enabling single-facility production of multiple stability grades.
India's FSSAI tightened microbial limits for coliform and S. aureus in fresh dairy products, mandating HACCP documentation for facilities above defined throughput thresholds. Medium-scale processors in Pune and Surat face facility upgrade costs or volume caps that favor larger organized players. Fresh paneer sold through local dairy shops bears the highest compliance burden, accelerating shift toward packaged retail formats.
Foodservice procurement specifications now require lot-traceable certificates of analysis for every paneer delivery, displacing informal quality verification through taste and texture sampling. Quick-service restaurant chains in Bangalore and Hyderabad enforce supplier audit protocols that exclude uncertified local producers. This pattern concentrates supply contracts toward integrated dairy processors with in-house laboratory capabilities.
Paneer Market Segmentation
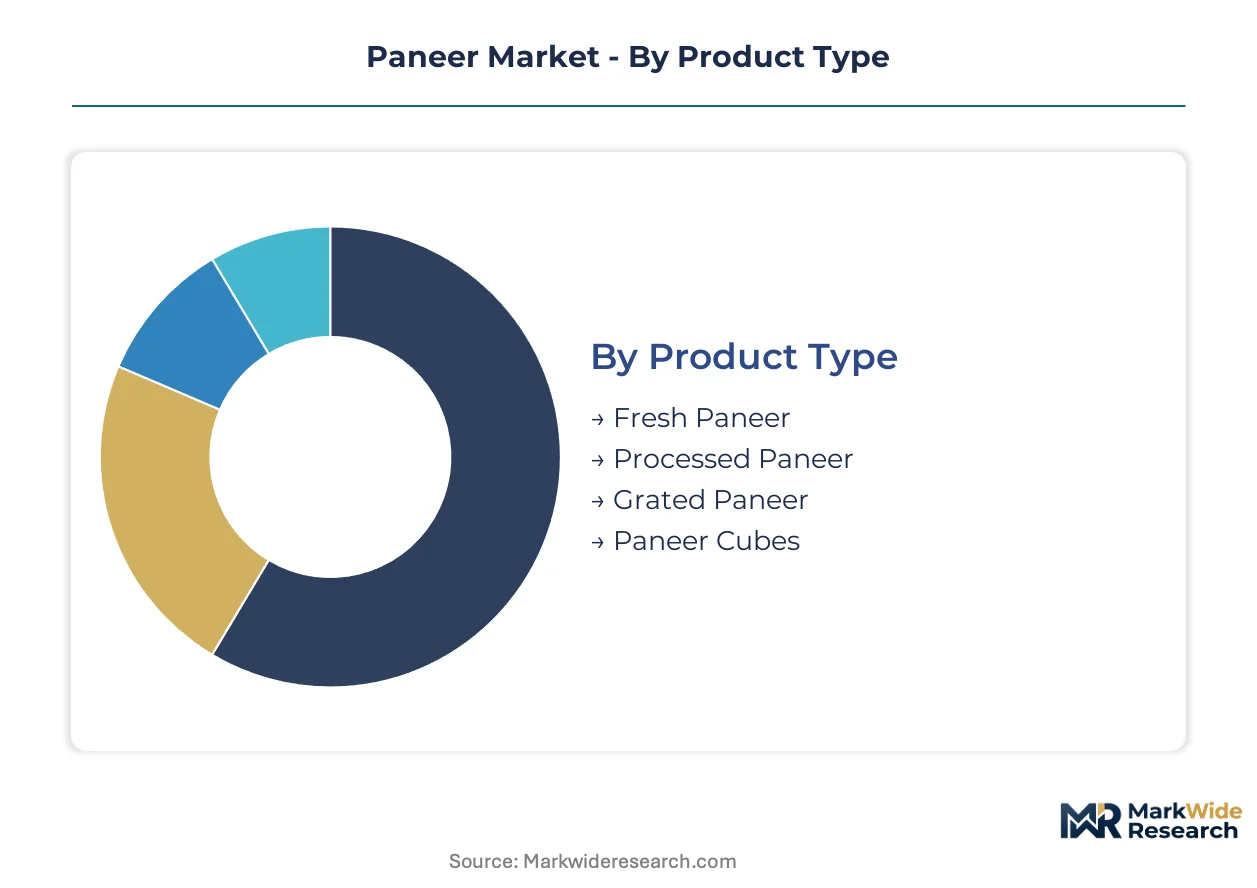
Paneer segmentation reveals divergent margin structures across freshness grades and channel formats. Organized players capture premium positioning through certified packaging and cold chain infrastructure while traditional vendors dominate volume in unbranded fresh blocks.
Product Type:
Mature formats face pressure from emerging processed variants that reduce spoilage and extend distribution reach.
- Fresh Paneer:Acid-set cheese with 50-55 percent moisture and 18-20 percent protein content, produced through direct curdling and pressing without aging. Maharashtra and Gujarat households drive demand for same-day production with texture suited to traditional cooking methods. Cold chain limitations restrict radius from production facilities.
- Processed Paneer:Thermally stabilized variants with extended shelf stability through controlled moisture reduction and modified atmosphere packaging. Quick-service restaurant chains in Bangalore and Hyderabad specify standardized cube formats for menu consistency. FSSAI microbial compliance creates entry barriers favoring organized processors with HACCP documentation.
- Grated Paneer:Pre-cut shreds for pizza and ready-meal applications, packaged in nitrogen-flushed bags.
- Paneer Cubes:Uniform 1-2 cm cuts for industrial food manufacturing and catering bulk procurement.
Fresh Paneer retains volume leadership; Processed Paneer holds the steepest expansion curve.
Distribution Channel:
Channel economics separate capital-intensive organized formats from relationship-dependent traditional trade.
- Supermarkets:Branded retail with BIS-certified shelf displays and refrigerated merchandising. Urban Maharashtra consumers shift toward vacuum-packed SKUs with visible fat content labeling. Modified atmosphere packaging reduces shrinkage rates versus open-counter sales.
- Online Retail:Direct-to-doorstep delivery with temperature-controlled logistics and subscription models. Tier-2 Indian cities bypass wholesale intermediaries through platform aggregators. Last-mile cold chain capex fragments returns across low-margin fresh categories.
- Wholesale Markets:Bulk procurement hub for caterers and restaurant chains with informal quality verification.
- Local Dairy Shops:Unbranded fresh blocks sold through milk cooperative networks with highest FSSAI compliance burden.
Local Dairy Shops retain volume leadership; Online Retail holds the steepest expansion curve.
End User:
User specifications diverge between taste-driven residential cooking and specification-driven foodservice procurement.
- Households:Residential consumers prioritizing freshness and traditional texture for daily meal preparation. Gujarat urban households display willingness to pay premiums for BIS-marked packaged variants. Price sensitivity remains acute in rural cooperative catchment areas.
- Restaurants:Foodservice operators requiring lot-traceable certificates of analysis for every delivery. Quick-service chains enforce supplier audit protocols that exclude uncertified local producers. Procurement specifications now mandate standardized cube sizes and consistent protein content.
- Caterers:Event-volume buyers with intermittent bulk demand and limited cold chain investment.
- Food Processing Industry:Ready-meal manufacturers requiring industrial-scale supply contracts with texture uniformity.
Households retain volume leadership; Restaurants hold the steepest expansion curve.
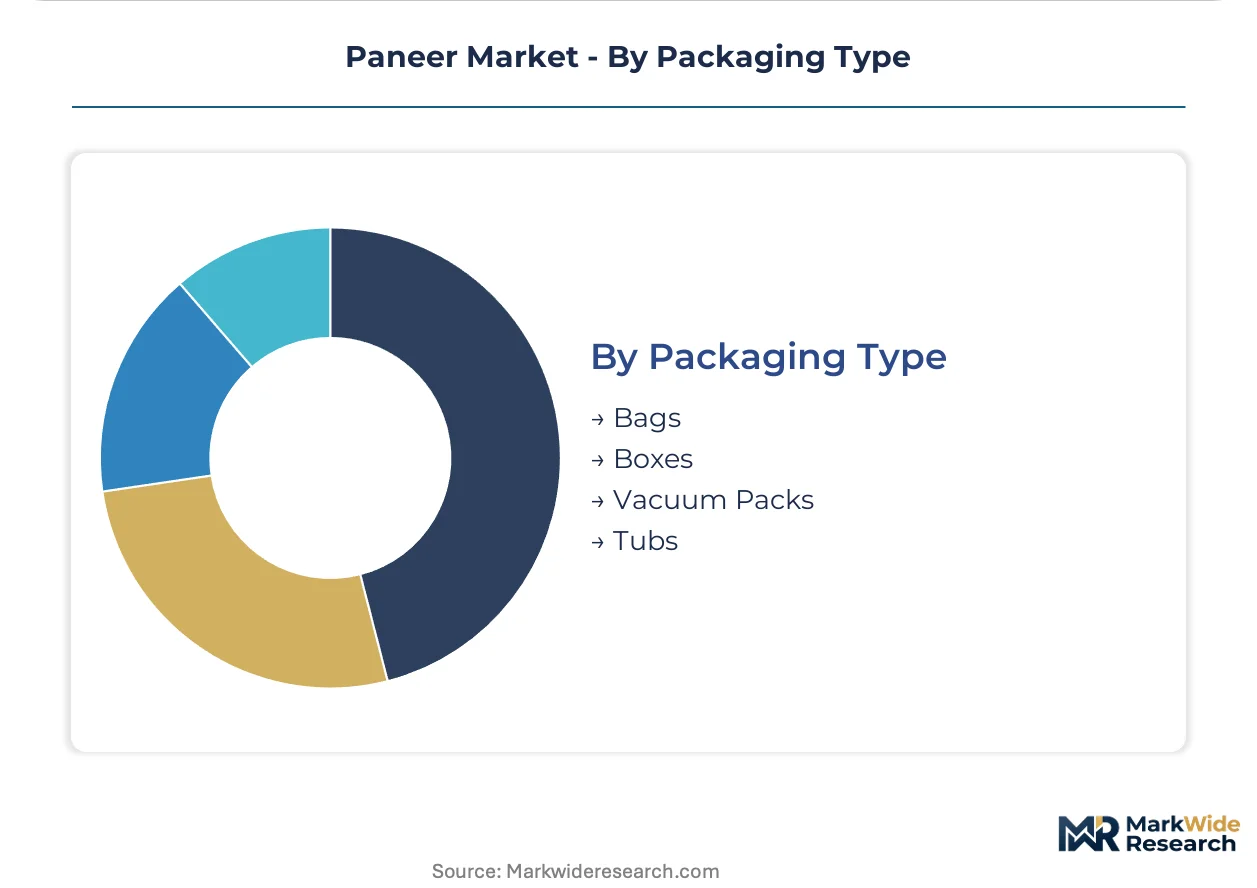
Packaging Type:
Packaging technology investments separate premium-positioned organized players from commodity fresh vendors.
- Vacuum Packs:Oxygen-excluded barrier films extending refrigerated shelf life without thermal alteration of protein structure. High-pressure processing technology hybridizes with vacuum sealing for Mumbai and Ahmedabad ready-meal manufacturers. Capital deployment favors larger processors over medium-scale Pune and Surat facilities.
- Tubs:Rigid containers with modified atmosphere headspace for premium supermarket placement. Branded positioning leverages visible product integrity and resealability for urban consumer convenience.
- Bags:Flexible pouches for grated and shredded formats with nitrogen flushing.
- Boxes:Corrugated secondary packaging for bulk foodservice and industrial shipments.
Tubs retain volume leadership; Vacuum Packs hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI regulations anchor the dominant Indian market, where organized dairy cooperatives and multinational processors compete across distinct state-level consumption patterns. Regional variations in cold chain maturity and certification infrastructure create divergent competitive environments.
India
Maharashtra and Gujarat households drive demand for fresh paneer with traditional texture specifications. FSSAI microbial limits for coliform and S. aureus mandate HACCP documentation for facilities above throughput thresholds. Mumbai and Ahmedabad processors deploy high-pressure processing technology to secure quick-service restaurant supply contracts.
China
Urban consumers in Beijing and Shanghai adopt paneer as a vegetarian protein alternative in quick-service formats. SAMR dairy hygiene standards and GB certification requirements shape manufacturing compliance costs. Beijing Sanyuan anchors production capacity in the northern dairy belt serving institutional foodservice procurement.
New Zealand
Fonterra leverages specialized dairy protein technology for export-grade paneer targeting Asian food manufacturers. EFSA dairy hygiene regulations and CE marking requirements block direct European market access, redirecting volume toward Southeast Asian industrial buyers. Canterbury processing clusters focus on standardized cube formats for ready-meal applications.
Denmark
Arla Foods competes through cooperative dairy infrastructure and extended-shelf-life packaging innovations. EU Green Deal sustainability reporting requirements and EFSA hygiene protocols govern production standards. Danish facilities supply European food manufacturers seeking lot-traceable certificates of analysis.
United States
South Asian diaspora communities in New Jersey and California sustain demand for traditional fresh paneer. FDA dairy plant inspection protocols and state-level milk safety regulations exceed FSSAI stringency, limiting Indian import penetration. Domestic processors in the Northeast dairy corridor target foodservice specifications for standardized formats.
Paneer Market Key Industry Players
Cooperative federations and multinational dairy corporations split the market between relationship-based local supply and technology-driven export positioning. The vendor base concentrates around three strategic archetypes: state-backed dairy cooperatives with captive milk sourcing, multinational processors with specialized protein technology, and regional private-label specialists with dedicated manufacturing facilities. Dominant competitive moves include backward integration into dairy farming and certification-driven capacity expansion.
Within the cooperative tier, Amul and Saras exemplify state-backed federations leveraging Gujarat and Rajasthan milk union infrastructure. Fonterra and Arla Foods occupy multinational positions shaped by export-grade production systems and European regulatory compliance. Parag Milk Foods anchors the private-label specialist archetype with dedicated paneer manufacturing and direct-to-retailer supply contracts.
| Leading Market Players |
|---|
| Saras (Rajasthan Cooperative Dairy Federation) |
| Ananda Dairy |
| Amul (Gujarat Cooperative Milk Marketing Federation) |
| Fonterra |
| Arla Foods |
| Parag Milk Foods |
| VRS Foods |
| Beijing Sanyuan |
| Mother Dairy Fruits & Vegetables |
| Others |
Cost & Logistics Intelligence
Gujarat and Maharashtra milk cooperative networks concentrate upstream supply, anchoring margin pools in cold chain-certified processing and branded retail packaging downstream. FSSAI microbial compliance creates tiered pricing separation between organized players with HACCP documentation and unbranded local vendors bearing spoilage risk.
Pricing Analysis
Maharashtra commands premium pricing over Rajasthan and Madhya Pradesh due to cold chain density and quick-service restaurant procurement concentration. Three-tier pricing structure across BIS-certified premium, packaged standard, and unbranded economy levels reflects certification grade and moisture standard adherence. Cost compression in fresh blocks intensifies as refrigerated logistics capex fragments returns across small-batch production. Households in rural cooperative catchments display highest price sensitivity; quick-service chains in Bangalore and Hyderabad accept premium pricing for lot-traceable supply.
Supply Chain Analysis
Extended payment terms from quick-service chains and supermarket consolidators strain working capital for medium-scale Pune and Surat processors. Supply draws from India, New Zealand, and Denmark, with Fonterra and Arla Foods anchoring export-grade production. Raw material dependencies center on buffalo and cow milk sourcing, food-grade acid curdling agents, and barrier film packaging. Single-source vulnerability concentrates in Gujarat cooperative milk unions during monsoon supply volatility. Distribution runs through supermarket refrigerated merchandising, platform-aggregator online retail, and traditional wholesale market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold chain logistics services and HACCP compliance certification represent faster-expanding recurring revenue layers than commodity paneer production. Subscription-based direct-to-consumer delivery models in tier-2 cities attach service revenue to perishable product flows.
For Market Incumbents: Pre-empt unbranded vendor displacement by deploying high-pressure processing technology for extended-shelf-life product lines. Anchor backward integration into captive dairy farming in Gujarat and Maharashtra to buffer milk supply volatility. Defend against emerging private-label specialists through BIS certification differentiation and direct-to-retailer supply contract exclusivity. For New Entrants and Emerging Players: Establish a beachhead in grated and pre-cubed industrial formats for ready-meal manufacturers in Mumbai and Ahmedabad. Target tier-2 online retail channels in Surat and Pune where platform aggregators bypass wholesale intermediaries. Pursue white-label supply contracts with quick-service chains requiring standardized cube specifications and lot-traceable certificates of analysis. For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional private-label specialists lacking cold chain certification infrastructure. Five-to-ten-year viability hinges on FSSAI compliance scalability and e-commerce channel penetration rates. Acquisition targets include medium-scale processors in Pune and Surat facing facility upgrade costs or volume caps. Watch high-pressure processing technology adoption curves as inflection indicator for margin expansion potential.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Expansion | FSSAI microbial compliance mandates HACCP-certified refrigerated warehousing and last-mile delivery capabilities. |
| High-Pressure Processing Technology Deployment | Mumbai and Ahmedabad ready-meal manufacturers adopt hybrid thermal pasteurization systems for extended shelf stability. |
| Direct-to-Retailer Supply Contracts | Parag Milk Foods and Amul bypass wholesale intermediaries through exclusive supermarket and e-commerce partnerships. |
| Backward Integration into Dairy Farming | Processors in Gujarat and Maharashtra secure captive milk supply to buffer cooperative network volatility. |
| BIS Certification Differentiation | National quality benchmarks for dairy fat content enable premium positioning against unmarked competitors in urban markets. |
Research Approach
Desk research of FSSAI regulatory filings, BIS certification databases, and dairy cooperative annual reports preceded structured interviews with plant managers at organized processors, procurement leads at quick-service restaurant chains, cold chain logistics operators, and supermarket category buyers. Secondary validation drew from customs trade data, food processing industry associations, and SEC filings of listed dairy corporations. Bottom-up volume modeling triangulated against top-down market sizing across product type, distribution channel, and end-user segments.
Assumptions held fixed include FSSAI microbial limit enforcement intensity, cold chain infrastructure investment rates in Maharashtra and Gujarat, and quick-service restaurant expansion trajectories across South Asia. Variables stress-tested included milk supply volatility in cooperative networks, e-commerce platform penetration in tier-2 cities, and high-pressure processing technology adoption curves. Segmentation dimensions modeled spanned freshness grades, packaging formats, channel formats, and regional regulatory clusters. CAGRs derived from historical trajectory analysis and demand driver elasticity assessment across the projection horizon.
Stress conditions across milk input pricing, refrigerated logistics cost inflation, and FSSAI compliance timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Macroeconomic contraction, regulatory enforcement discontinuity, or alternative protein substitution acceleration would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Table Butter Market
Dairy Products
Recombined Milk Market
Dairy Products
Asia-Pacific Flavored Milk Market
Dairy Products
Filled Cheese Market
Dairy Products
Butter Concentrate Market
Dairy Products
China Lactose-Free Dairy Market
Dairy Products
Dairy Spreads Market
Dairy Products
Dairy Blends Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Organic Milk Protein Market
Dairy Products
United Kingdom Whey Protein Market
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
Halloumi Cheese Market
Dairy Products
Cheese Shreds Market
Dairy Products
Europe Drinkable Yogurt Market
Dairy Products
Cheese Packaging Market