
 Hydrolyzed Casein Market | 2026-2036
Hydrolyzed Casein Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrolyzed Casein Market Foresight
Direct-to-brand ingredient supply is rewriting procurement patterns in the hydrolyzed casein industry. Arla Foods Ingredients leverages its Scandinavian dairy cooperative structure to sustain captive milk supply across Northern Europe. Fonterra Co-operative Group anchors oceania-origin casein output through its New Zealand farmer network. FrieslandCampina Ingredients differentiates via specialized protein fractionation technology at Dutch production sites.
Hydrolyzed casein comprises enzymatically cleaved casein phosphoproteins yielding bioactive peptides with molecular weights typically below 10 kDa, serving primarily as rapid-digesting protein fortification in clinical and sports nutrition. The hydrolyzed product type leads value generation due to premium positioning in medical nutrition and elite sports applications. Infant formula application segments command concentrated margin pools as pharmaceutical-grade peptide specifications tighten supply eligibility. Caseinate variants occupy mature volume positions in processed food manufacturing where cost efficiency dominates procurement criteria.
FDA GRAS notifications and USDA dairy plant inspections govern US market entry for hydrolyzed casein ingredients, while EFSA novel food assessments and EU MDR frameworks shape European clinical nutrition deployment. These regulatory layers elevate compliance costs for new entrants but protect incumbent suppliers with established certification infrastructure. Stakeholders must monitor evolving peptide-specific health claim authorization pathways as the primary uncertainty affecting premium segment expansion.
Market Dynamics
Precision fermentation is collapsing traditional enzymatic hydrolysis timelines, compressing peptide production from weeks to days while EFSA novel food assessments simultaneously extend commercialization pathways for bioactive ingredient suppliers.
Growth Catalysts
- Sports nutrition fortification:North American athletic supplement brands are expanding peptide procurement for rapid-absorption protein formulations targeting post-workout recovery windows.
- EU MDR clinical nutrition frameworks:Medical device regulations for enteral feeding are tightening peptide purity specifications, elevating demand for pharmaceutical-grade hydrolyzed casein.
- Enzymatic specificity advances:Targeted protease engineering is enabling selective peptide cleavage for bioactive sequences with documented physiological effects.
Market Restraints
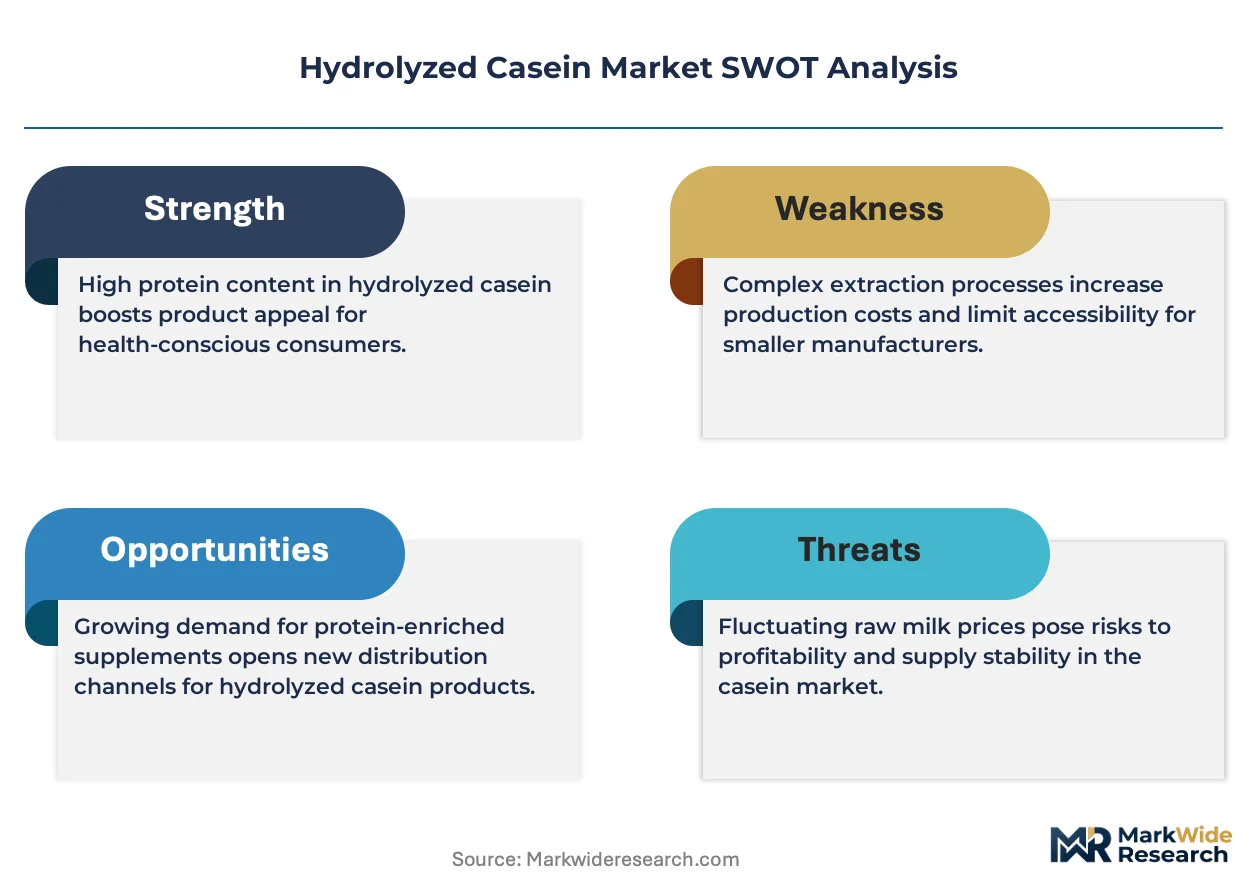
- Raw milk supply concentration:Oceania and Northern European dairy cooperative structures control upstream casein availability, limiting independent processor expansion.
- EFSA novel food assessment timelines:Extended safety evaluation periods for new peptide structures delay revenue realization by 18-36 months.
- Plant protein substitution:Pea and rice protein isolates are capturing cost-sensitive sports nutrition segments where rapid digestion is less critical.
Strategic Opportunities
- German precision fermentation capacity:Domestic peptide production investments are accelerating, reducing import dependency for clinical-grade hydrolyzed casein.
- Infant formula bioactive fortification:Oligopeptide-enriched formulations for hypoallergenic neonatal nutrition represent underexploited premium positioning.
- Direct-to-brand ingredient supply:Bypassing traditional distributor networks allows peptide suppliers to capture margin pools previously allocated to intermediaries.
Industry Challenges
- Peptide characterization expertise:Mass spectrometry and bioassay validation capabilities remain scarce among mid-scale ingredient processors.
- Multi-jurisdiction certification synchronization:Aligning FDA GRAS notifications with EFSA novel food dossiers demands specialized regulatory affairs infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrolyzed Casein Market |
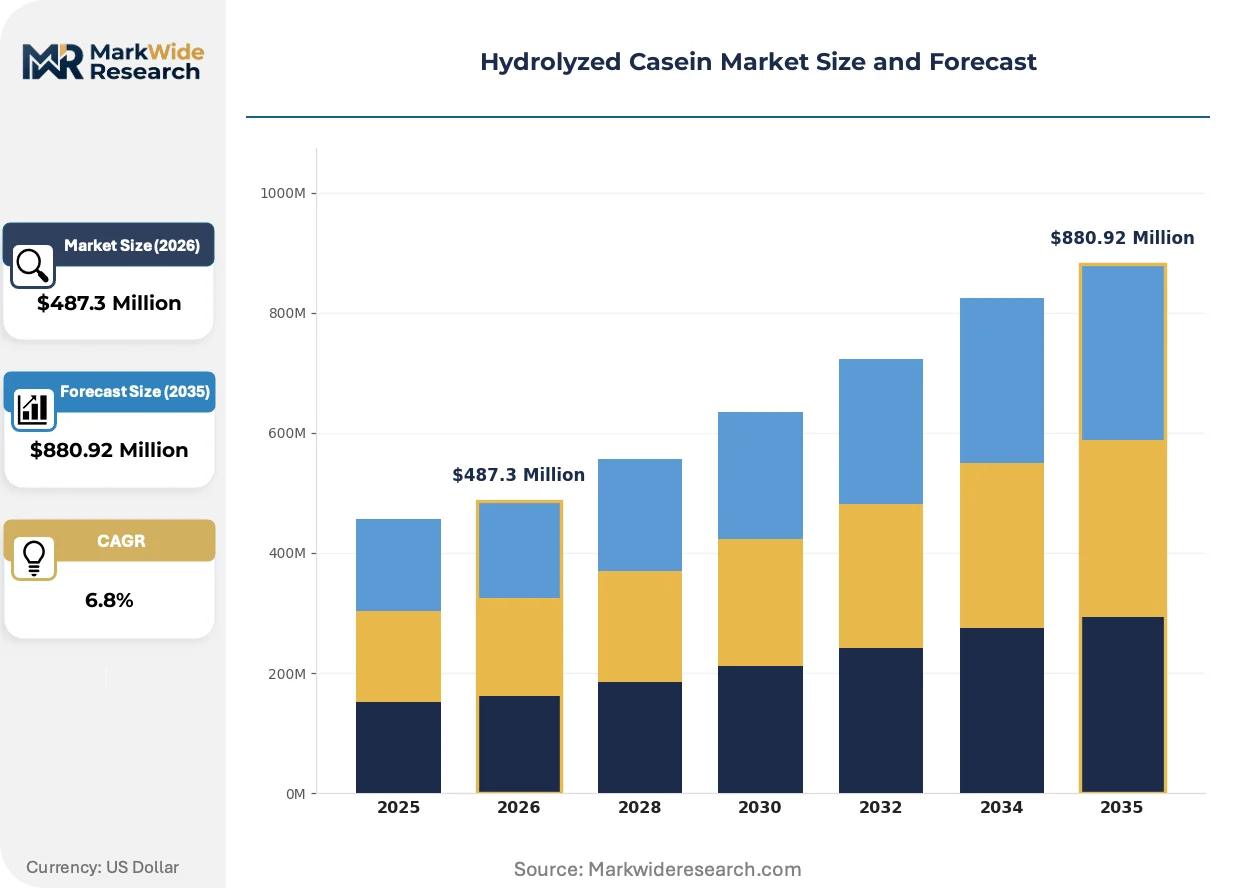
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed, Micellar Casein, Caseinates, Casein Protein Application: Nutrition Products, Dairy Industry, Food & Beverage, Infant Formula End User: Food Manufacturers, Dietary Supplement Companies, Healthcare Providers, Fitness Centers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Arla Foods Ingredients, Fonterra Co-operative Group, FrieslandCampina Ingredients, Milk Specialties Global, Ingredia SA, Armor Proteines, Glanbia Nutritionals, AMCO Proteins, Tatua Co-operative Dairy Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrolyzed Casein Market Shifts & Advancements
Bioprocessing advances and regulatory recalibration are simultaneously compressing production economics and extending commercialization pathways for hydrolyzed casein suppliers.
Continuous enzymatic membrane reactors are collapsing batch-to-batch variability in peptide molecular weight distribution. Sports nutrition contract manufacturers in Germany and the Netherlands are adopting these systems to reduce purification overhead. The technology is collapsing quality control costs while enabling real-time process analytical technology integration.
EFSA updated guidance on bioactive peptide health claims is tightening evidentiary requirements for immunomodulatory and antihypertensive positioning statements. Clinical nutrition brands must now commission human intervention trials rather than relying on in vitro mechanistic data. Infant formula specialists are responding by concentrating R&D spending on well-documented ACE-inhibitory and antioxidant peptide sequences with existing positive opinions.
Ingredient procurement is consolidating around direct supply relationships with demonstrated traceability from milk source to hydrolysis facility. North American sports nutrition brands are displacing spot-market purchasing with multi-year offtake agreements specifying peptide profile consistency. This pattern is most visible in California and Texas, where vertically integrated dairy-protein processors are capturing volume commitments previously held by European traders.
Hydrolyzed Casein Market Segmentation
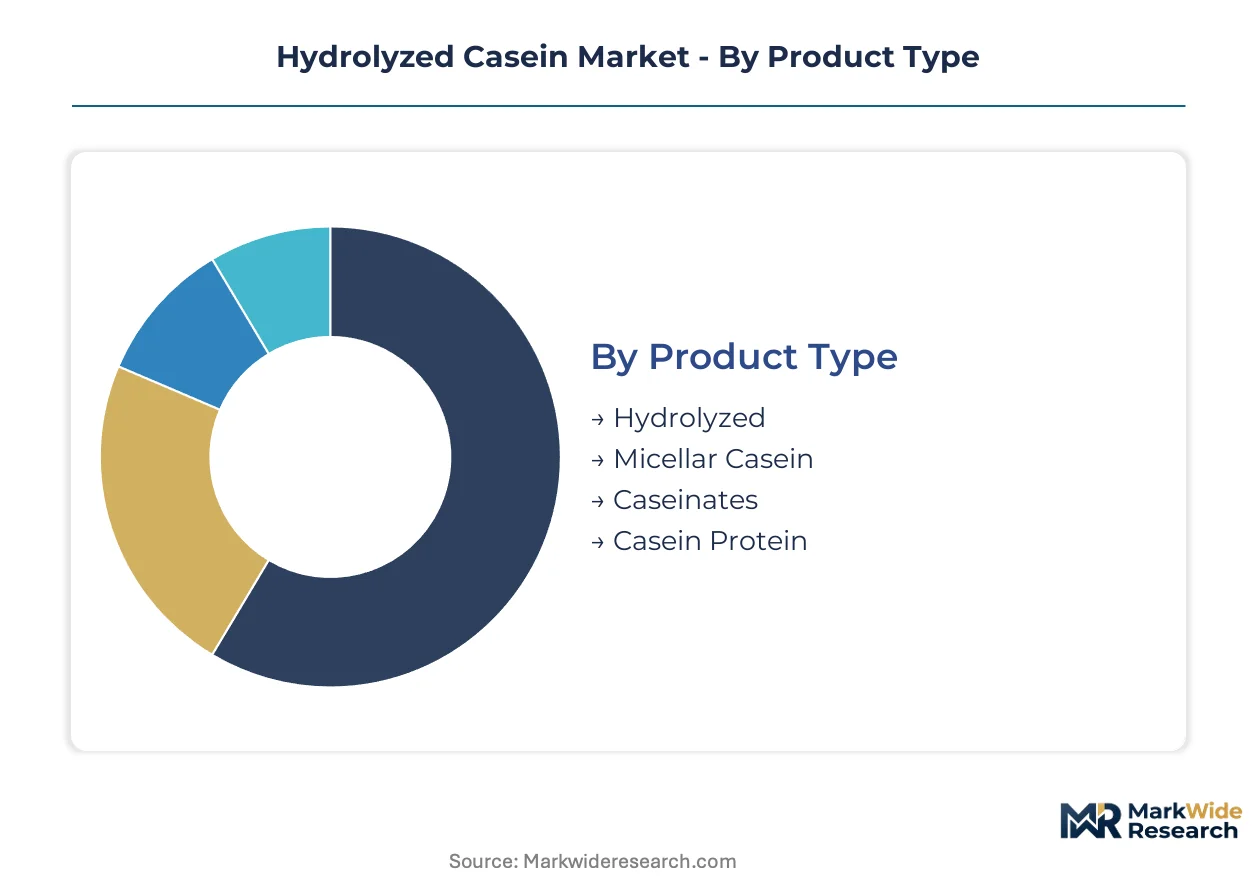
Segmentation in hydrolyzed casein markets reveals divergent margin structures across peptide purity grades and end-use certification requirements. Procurement patterns split sharply between pharmaceutical-grade specifications demanding mass spectrometry validation and commodity-grade volumes serving processed food manufacturing.
Product Type:
After-sales technical support intensity escalates dramatically with peptide complexity, as clinical-grade hydrolyzed casein requires ongoing batch certification and regulatory dossier maintenance.
- Hydrolyzed:Enzymatically cleaved casein phosphoproteins yielding bioactive peptides below 10 kDa molecular weight. Demand concentrates in German precision fermentation facilities and North American sports nutrition contract manufacturing, where rapid-absorption positioning commands formulation premiums.
- Micellar Casein:Native protein structure preserved through gentle membrane separation, delivering sustained amino acid release profiles. Athletic supplement brands in California and Texas are expanding procurement for overnight recovery formulations, displacing slower-digesting alternatives in premium positioning.
- Caseinates:Alkali-treated casein salts dominating processed food manufacturing where emulsification and water-binding functionality outweigh peptide bioactivity requirements.
- Casein Protein:Unhydrolyzed native protein serving cost-sensitive fortification applications with minimal enzymatic processing overhead.
By volume, Caseinates leads. By growth pace, Hydrolyzed is expanding most quickly.
Application:
Cost tier stratification separates pharmaceutical-grade peptide specifications from commodity food-grade volumes, with certification infrastructure acting as the primary pricing determinant.
- Nutrition Products:Medical nutrition and sports supplement formulations requiring documented peptide bioactivity. EU MDR enteral feeding regulations are tightening purity specifications, elevating demand for mass spectrometry-validated hydrolyzed casein in German and Dutch clinical nutrition manufacturing.
- Infant Formula:Hypoallergenic neonatal nutrition with oligopeptide-enriched formulations commanding concentrated margin pools. EFSA novel food assessments for bioactive peptide health claims are extending commercialization timelines while protecting incumbent suppliers with established dossier infrastructure.
- Dairy Industry:Functional ingredient applications leveraging casein emulsification and texture modification in processed cheese and yogurt systems.
- Food & Beverage:General fortification applications where cost efficiency dominates procurement criteria and plant protein substitution pressures intensify.
Infant Formula captures the steepest margin expansion. Nutrition Products shows the strongest volume acceleration.
End User:
Customer type fragmentation reflects divergent technical capabilities, with pharmaceutical-grade buyers maintaining in-house peptide characterization labs while commodity processors rely on supplier certificates.
- Dietary Supplement Companies:Sports nutrition brands driving rapid-absorption peptide procurement through direct-to-brand supply relationships. North American athletic supplement manufacturers are displacing spot-market purchasing with multi-year offtake agreements specifying molecular weight distribution consistency.
- Healthcare Providers:Clinical nutrition departments sourcing pharmaceutical-grade hydrolyzed casein for enteral feeding and medical food applications. FDA GRAS notifications and EFSA novel food frameworks govern procurement eligibility, favoring suppliers with synchronized multi-jurisdiction certification.
- Food Manufacturers:Processed food producers prioritizing cost efficiency and supply security over peptide bioactivity documentation.
- Fitness Centers:Direct retail channels for ready-to-drink protein beverages with simplified formulation requirements.
Healthcare Providers maintains the most stringent specification barriers. Dietary Supplement Companies are gaining share fastest in absolute procurement volume.
Distribution Channel:
Supply concentration in Northern European dairy cooperatives shapes channel economics, with direct procurement relationships displacing traditional trader intermediaries.
- Wholesale:Bulk ingredient supply to contract manufacturers and large-scale food processors. Arla Foods Ingredients and FrieslandCampina leverage cooperative structures to sustain captive milk supply through direct wholesale relationships bypassing distributor markups.
- Online Retail:Direct-to-brand ingredient platforms enabling small-batch peptide procurement with documented traceability. Specialty hydrolyzed casein suppliers are capturing margin pools previously allocated to European trading houses through digital procurement interfaces.
- Specialty Stores:Niche channels serving artisan food producers and boutique supplement manufacturers.
- Supermarkets:Consumer-packaged goods retail with minimal hydrolyzed casein penetration due to ingredient-grade positioning.
Wholesale dominates current volume flows. Online Retail demonstrates the sharpest trajectory shift in procurement pattern adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp port complex underwrites European peptide ingredient flows, while Union Pacific rail corridors anchor North American dairy protein distribution to coastal formulation centers.
Germany
Precision fermentation investments in Saxony-Anhalt and Bavaria are accelerating domestic peptide production capacity for clinical-grade hydrolyzed casein. EFSA novel food assessments govern bioactive peptide commercialization timelines, extending safety evaluation periods. The Leipzig-Halle chemical cluster hosts emerging bioprocessing facilities reducing import dependency for pharmaceutical-grade ingredients.
United States
California and Texas sports nutrition brands are displacing spot-market purchasing with multi-year offtake agreements specifying molecular weight distribution consistency. FDA GRAS notifications and USDA dairy plant inspections govern market entry for hydrolyzed casein ingredients. Vertically integrated dairy-protein processors in the Central Valley and Dallas-Fort Worth corridor capture volume commitments previously held by European traders.
Netherlands
FrieslandCampina's specialized protein fractionation technology at Dutch production sites sustains Northern European supply concentration. REACH compliance frameworks and EFSA novel food assessments shape clinical nutrition deployment pathways. The Wageningen food valley cluster anchors enzymatic specificity research for selective peptide cleavage applications.
New Zealand
Fonterra Co-operative Group anchors oceania-origin casein output through its farmer network, controlling upstream availability for Asia-Pacific formulation markets. The country's national dairy regulator oversees export certification infrastructure protecting incumbent supplier positions. Canterbury dairy processing clusters concentrate micellar casein output for sustained-release athletic supplement applications.
France
Armor Proteines exemplifies cooperative-structured dairy ingredient supply sustaining captive milk access across Northwestern France. ANSM pharmaceutical regulations and EFSA health claim frameworks tighten peptide-specific authorization pathways. The Brittany dairy basin maintains emulsification-grade caseinate production for processed food manufacturing cost efficiency.
Hydrolyzed Casein Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in peptide characterization and regulatory dossier infrastructure. The vendor base concentrates around dairy cooperative structures controlling raw milk supply, with independent processors facing upstream availability constraints. Two strategic archetypes dominate: cooperative-anchored integrated processors with captive supply chains, and specialized fractionation technology holders with pharmaceutical-grade certification infrastructure. Competitive moves center on multi-jurisdiction certification synchronization and direct-to-brand procurement relationship displacement of traditional distributor networks.
Within the cooperative-anchored tier, Arla Foods Ingredients leverages its Scandinavian dairy cooperative structure to sustain captive milk supply across Northern Europe, exemplifying upstream integration archetypes. Fonterra Co-operative Group anchors oceania-origin output through New Zealand farmer network structures, representing scale-driven supply concentration. FrieslandCampina Ingredients occupies a position as specialized fractionation technology holder at Dutch production sites, illustrating premium-tier peptide processing capabilities.
| Leading Market Players |
|---|
| Arla Foods Ingredients |
| Fonterra Co-operative Group |
| FrieslandCampina Ingredients |
| Milk Specialties Global |
| Ingredia SA |
| Armor Proteines |
| Glanbia Nutritionals |
| AMCO Proteins |
| Tatua Co-operative Dairy Company |
| Others |
Supply & Pricing Matrix
The Leipzig-Halle chemical cluster's precision fermentation capacity expansion is compressing domestic peptide production costs while simultaneously elevating pricing power for pharmaceutical-grade hydrolyzed casein suppliers serving German clinical nutrition manufacturers. This geographic concentration of bioprocessing infrastructure enables incumbent dairy cooperatives to enforce volume-commitment contracts that lock in margin pools previously captured by European trading intermediaries.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with pharmaceutical-grade peptide specifications commanding three-tier pricing stratification across premium, standard, and economy certification levels. Price differentiation rests on mass spectrometry validation depth and synchronized FDA-EFSA multi-jurisdiction dossier completion, with clinical nutrition buyers exhibiting minimal price sensitivity compared to processed food manufacturers facing intensifying plant protein substitution. Pricing pressure stems from precision fermentation technology diffusion eroding traditional enzymatic hydrolysis cost premiums in German and Dutch production facilities.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Northern European dairy cooperatives are locking independent processors out of upstream milk procurement, with Arla Foods Ingredients and FrieslandCampina leveraging captive farmer networks across Denmark, the Netherlands, and Germany. Raw material dependencies center on high-protein milk solids, specialized protease enzymes, and pharmaceutical-grade filtration membranes. Single-source vulnerability concentrates in Oceania-origin casein controlled by Fonterra's New Zealand farmer cooperative structure. Distribution runs through direct-to-brand ingredient platforms displacing traditional wholesale trader networks in North American sports nutrition procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass spectrometry and bioassay validation capabilities remain scarce among mid-scale peptide processors, creating persistent bottlenecks for clinical-grade hydrolyzed casein commercialization. This technical asset gap constrains supply elasticity and protects incumbent positions for suppliers with established analytical infrastructure.
For Market Incumbents: Entrench multi-jurisdiction certification synchronization as a defensive moat against emerging precision fermentation specialists by accelerating EFSA novel food dossier maintenance and FDA GRAS notification updates. Prioritize backward integration into captive milk supply through cooperative structure expansion in Saxony-Anhalt and Bavaria production corridors. Lock in multi-year offtake agreements with North American sports nutrition brands specifying molecular weight distribution consistency to displace spot-market competitor access. For New Entrants and Emerging Players: German precision fermentation facility partnerships represent the most penetrable entry point for clinical-grade hydrolyzed casein production, bypassing raw milk supply concentration controlled by established dairy cooperatives. Online retail ingredient platforms serving small-batch sports nutrition contract manufacturers in California and Texas offer secondary white-space access with lower certification barrier requirements. Pursue direct-to-brand digital procurement relationships as the primary go-to-market angle to capture margin pools previously allocated to European trading intermediaries. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory infrastructure play because EFSA novel food assessment timelines and synchronized FDA-EFSA certification requirements create durable competitive moats protecting incumbent supplier valuations. Target acquisition profiles emphasizing specialized peptide fractionation technology holders with established pharmaceutical-grade dossier infrastructure rather than commodity caseinate processors. Monitor precision fermentation cost parity achievement against traditional enzymatic hydrolysis as the critical inflection signal for margin compression timing in clinical nutrition segments.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Saxony-Anhalt and Bavaria facilities reduce German import dependency for clinical-grade peptide production. |
| Multi-Jurisdiction Certification Synchronization | Aligned FDA GRAS notifications with EFSA novel food dossiers protect premium segment market access. |
| Direct-to-Brand Ingredient Supply Relationships | Bypassing distributor networks captures margin pools in North American sports nutrition procurement. |
| Specialized Protease Engineering Investment | Wageningen cluster research enables selective peptide cleavage for documented bioactive sequences. |
| Long-Term Offtake Agreement Structuring | California and Texas brands lock in molecular weight distribution consistency displacing spot-market purchasing. |
Research Methodology
Cross-validation between primary interviews with dairy cooperative procurement directors, sports nutrition brand formulation scientists, clinical nutrition regulatory affairs specialists, and precision fermentation facility operations managers anchors the qualitative findings. Secondary validation draws from EFSA novel food assessment databases, FDA GRAS notification filings, USDA dairy plant inspection records, and EU MDR enteral feeding regulatory frameworks. Bottom-up volume triangulation across hydrolyzed casein production facilities integrates with top-down demand modeling from infant formula and sports nutrition end-use segments.
Calibration against historical peptide production capacity utilization and documented commercialization timeline data from precision fermentation technology deployments shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include peptide purity grade tiers, application-specific certification requirements, end-user technical capability profiles, and regional regulatory cluster classifications. CAGRs derive from elasticity-adjusted demand projections incorporating enzymatic specificity advance rates and plant protein substitution threat parameters in cost-sensitive segments.
Practitioners should monitor EFSA bioactive peptide health claim authorization pathway evolution and precision fermentation cost parity achievement against traditional enzymatic hydrolysis for early signals of segment margin restructuring. Forecasts reflect assumptions regarding sustained dairy cooperative upstream supply control and regulatory assessment timeline stability. Macroeconomic dairy commodity volatility, novel food safety evaluation period extension, or breakthrough plant protein rapid-digestion technology emergence would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
High Protein Yogurt Market
Dairy Products
Mascarpone Cheese Market
Dairy Products
Latin America Cheese Market
Dairy Products
Japan Casein Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
Europe Milk Protein Market
Dairy Products
Whipping Cream Market
Dairy Products
Cheese Packaging Market
Dairy Products
Lactic Butter Market
Dairy Products
Canada Milk Protein Market
Dairy Products
India Milk Protein Market
Dairy Products
Dairy Based Dressings Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Milk Protein Hydrolysate Market
Dairy Products
Soluble Milk Protein Market
Dairy Products
Middle East and Africa Whey Protein Market