
 Glycerol Carbonate Market | 2026-2036
Glycerol Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Glycerol Carbonate Market Intelligence
REACH chemical registration requirements is realigning capital deployment across European glycerol carbonate production. Solvay SA leverages its integrated chlor-alkali and epichlorohydrin assets to control feedstock quality for pharmaceutical-grade output. Mitsubishi Chemical Group anchors its position through proprietary catalytic carbonation technology that reduces energy intensity in carbonate synthesis. BASF SE competes via backward integration into bio-based glycerol streams sourced from European biodiesel refineries.
Glycerol carbonate is a cyclic carbonate ester formed from glycerol and carbon dioxide or phosgene derivatives, typically exhibiting high polarity, low volatility, and a boiling point near 354 degrees Celsius that suits high-temperature solvent applications. Its primary commercial purpose centers on replacing petroleum-derived solvents in coatings, electrolyte formulations, and surfactant systems where biodegradability and low toxicity carry regulatory weight. Industrial grade glycerol carbonate dominates volume flows into paint and coatings applications, while pharmaceutical and cosmetic grades command premium positioning due to stringent purity certification requirements. Enzymatic conversion and biocatalysis technologies are gaining traction as manufacturers seek to reduce phosgene dependency and align with EU chemical sustainability directives.
The European Chemicals Agency enforces REACH substance evaluation protocols that elevate compliance costs for importers of non-registered glycerol carbonate volumes. The EPA's Toxic Substances Control Act governs new chemical notifications for carbonate derivatives entering US commerce, while China's Ministry of Ecology and Environment implements GB standards on industrial chemical emissions that affect export-oriented producers. Stakeholders must monitor tightening cross-border chemical registration reciprocity agreements that could fragment supply access between major manufacturing jurisdictions.
Market Dynamics
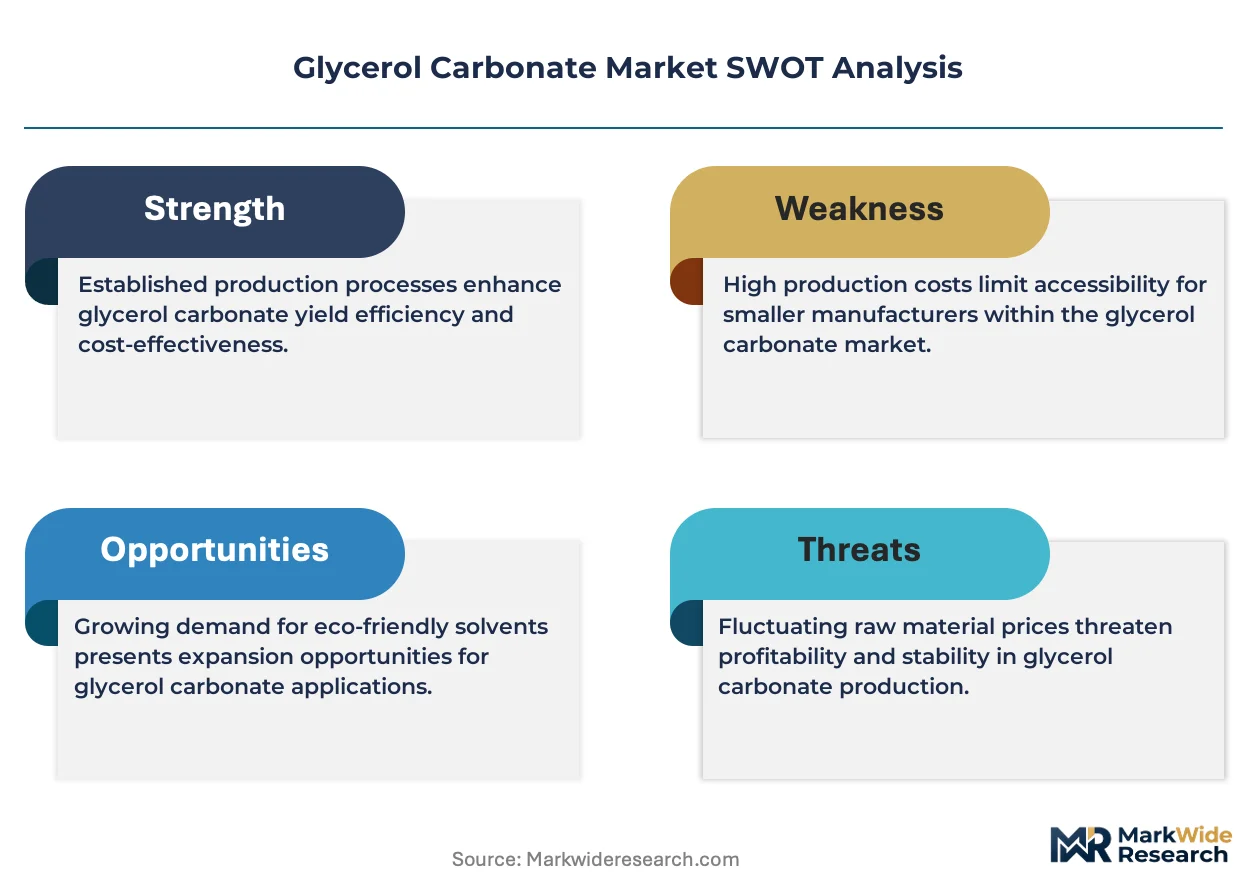
REACH chemical registration protocols are restructuring capital allocation across glycerol carbonate production, forcing manufacturers to consolidate registration assets or exit European supply chains entirely. Specialty solvent producers now face binary choices between phosgene-based legacy routes and enzymatic carbonation investments.
Growth Catalysts
- EU Green Deal solvent mandates:Volatile organic compound limits in automotive coatings are accelerating glycerol carbonate substitution for petroleum-derived solvents across German and French manufacturing clusters.
- Biodiesel refinery integration:Crude glycerol streams from European biofuel plants provide captive feedstock for carbonate synthesis, reducing raw material cost volatility.
- High-temperature electrolyte demand:Lithium-ion battery manufacturers are adopting glycerol carbonate for thermal stability in electrolyte formulations serving electric vehicle supply chains.
Market Restraints
- Epichlorohydrin price volatility:Chlor-alkali energy intensity and propylene feedstock costs create margin compression for conventional carbonate synthesis routes.
- Chinese supply concentration:Export-oriented producers in Shandong and Jiangsu provinces control bulk industrial-grade volumes, creating import dependency risks for European formulators.
- Phosgene handling restrictions:OSHA and EU Seveso III directives impose capital-intensive safety infrastructure requirements on legacy production facilities.
Strategic Opportunities
- Pharmaceutical-grade certification gap:USP and EP monograph compliance for injectable-grade glycerol carbonate remains underdeveloped outside Solvay's Belgian and Japanese facilities.
- Biocatalytic carbonation scale-up:Immobilized enzyme reactors and supercritical CO2 processing are converging to eliminate phosgene entirely from pharmaceutical-grade production.
- Cosmetic surfactant channels:Direct-to-formulator e-commerce platforms are bypassing traditional distributor markups for mid-volume personal care manufacturers.
Industry Challenges
- REACH data gap bridging:Small and mid-scale producers lack toxicology study resources to complete substance evaluation dossiers for 2027 registration deadlines.
- Multi-grade inventory complexity:Simultaneous production of industrial, pharmaceutical, and cosmetic grades requires segregated processing trains and extended cleaning validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycerol Carbonate Market |
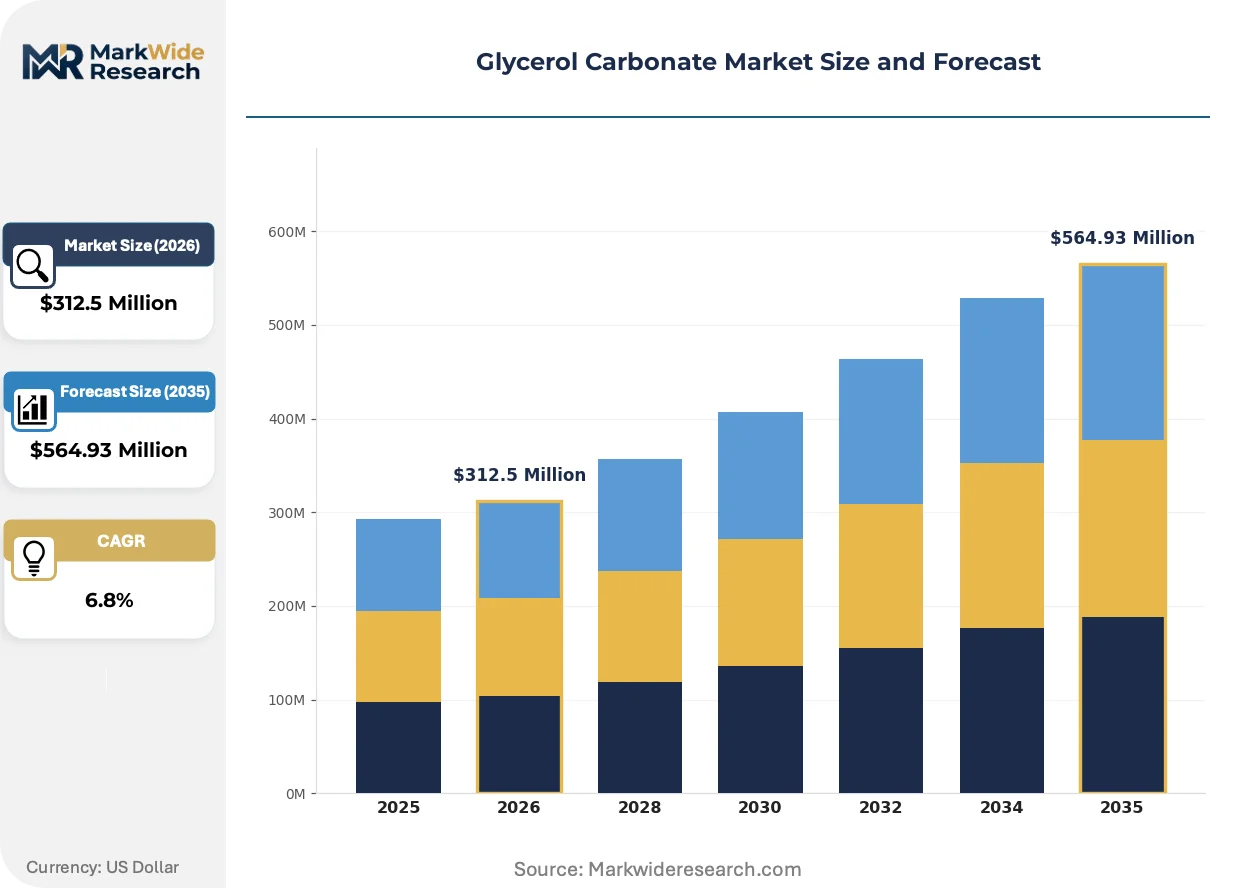
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Food Grade, Cosmetic Grade, Agricultural Grade Technology: Chemical Synthesis, Enzymatic Conversion, Electrochemical Process, Catalytic Carbonation, Biocatalysis Application: Solvents, Electrolytes, Surfactants, Coatings, Adhesives, Plasticizers End User Industry: Paint & Coatings Manufacturers, Detergent Producers, Personal Care Brands, Agrochemical Firms, Polymer Manufacturers |
| Companies Covered | Solvay SA, Mitsubishi Chemical Group, BASF SE, Cargill, Incorporated, Merck KGaA, Huntsman Corporation, Evonik Industries AG, Perstorp Holding AB, UBE Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycerol Carbonate Market Strategic Shifts & Innovations
Enzymatic conversion technologies are disrupting conventional phosgene-dependent carbonate synthesis, creating divergence between legacy chlor-alkali producers and biocatalytic entrants. This technological schism is fragmenting competitive positioning across purity grades and end-use certifications.
Supercritical carbon dioxide carbonation is electrifying glycerol processing economics. Pharmaceutical manufacturers in Switzerland and Germany are adopting this route for API-grade output. The technology is compressing energy intensity differentials between European and Asian production bases.
REACH substance evaluation protocols are tightening impurity disclosure requirements for cyclic carbonate imports. The European Chemicals Agency's 2024-2027 work program prioritizes glycerol derivative assessments. Coatings formulators in Italy and Spain are accelerating qualification of pre-registered supply sources.
Certification-driven procurement is consolidating supplier relationships around dual-registered producers. Tier-one automotive coaters in Stuttgart and Wolfsburg are reducing qualified vendor lists from twelve to four. This concentration is visible across German automotive chemical supply chains.
Glycerol Carbonate Market Segmentation
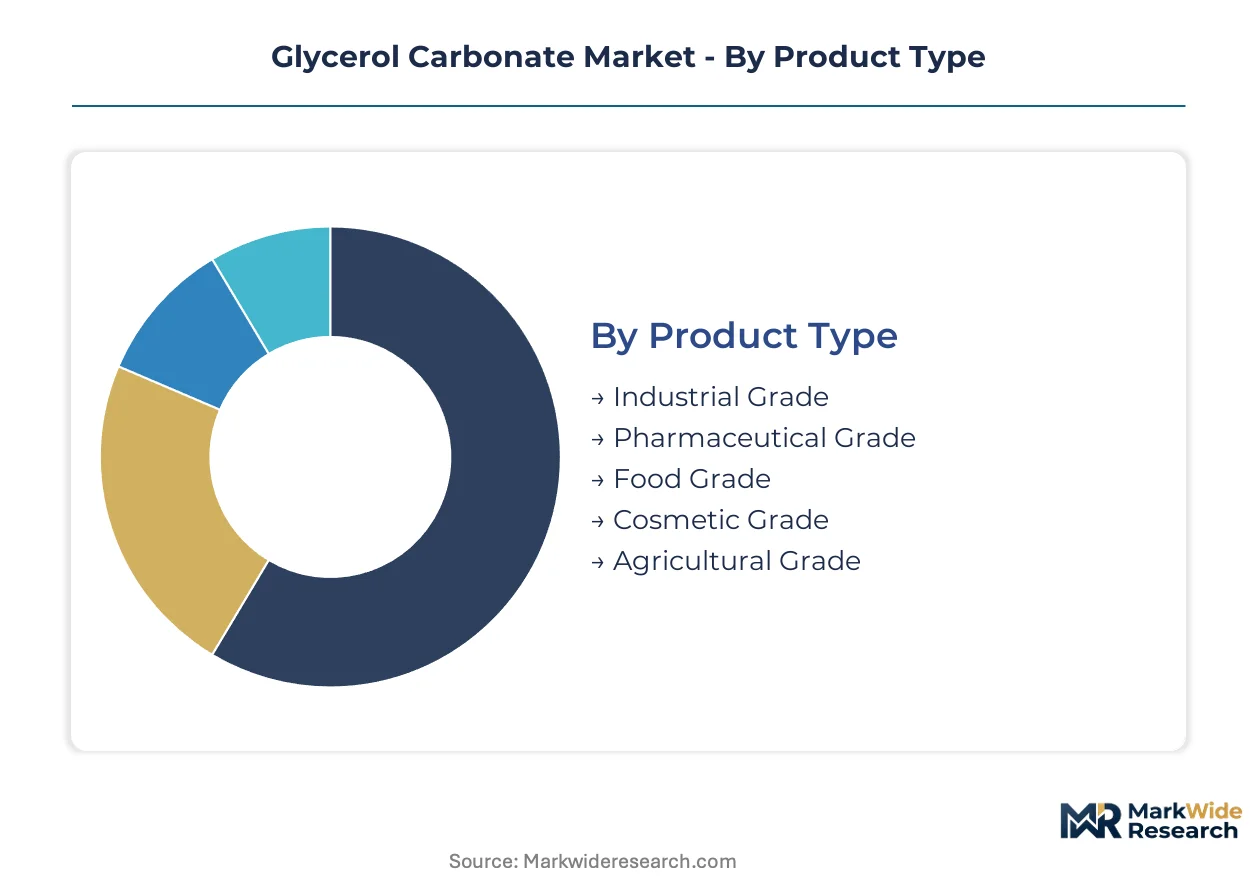
Glycerol carbonate producers face divergent capital requirements across purity tiers, with pharmaceutical-grade infrastructure demanding tenfold higher investment than industrial-grade lines. Segmentation discipline separates margin-accretive specialty positions from volume-driven commodity plays.
Product Type:
Capital intensity escalates sharply with purity certification, separating phosgene-handling industrial assets from biocatalytic pharmaceutical facilities.
- Industrial Grade:Produced via conventional chlor-alkali routes with epichlorohydrin feedstock, this segment serves high-volume coatings and adhesive applications where cost minimization dominates procurement. German automotive coaters in Stuttgart and Wolfsburg absorb the majority of European industrial-grade flows as REACH VOC limits tighten.
- Pharmaceutical Grade:USP and EP monograph compliance requires segregated enzymatic processing trains, supercritical CO2 carbonation, and extended cleaning validation cycles. Swiss and Belgian facilities anchor supply for injectable drug formulations where impurity thresholds are measured in parts per billion.
- Food Grade:FSSAI and FDA food additive clearances govern this segment's regulatory burden, with applications concentrated in flavor carrier and food processing aid formulations.
- Cosmetic Grade:REACH cosmetic regulation compliance and ECOCERT organic certification requirements shape formulation specifications for surfactant and emollient applications.
- Agricultural Grade:Serves as a solvent and carrier in agrochemical formulations, with demand linked to pesticide and herbicide production cycles.
Industrial grade absorbs the bulk of installed capacity; pharmaceutical grade is expanding most quickly.
Technology:
Process selection determines energy intensity, phosgene exposure liability, and alignment with EU chemical sustainability directives.
- Chemical Synthesis:Legacy phosgene-dependent routes dominate current industrial-grade output but face escalating Seveso III compliance costs and carbon border adjustment exposure.
- Enzymatic Conversion:Immobilized lipase reactors operating at ambient pressure eliminate toxic reagent handling while delivering pharmaceutical-grade purity. German and Swiss producers are scaling this technology for API-grade carbonate output.
- Electrochemical Process:Direct glycerol oxidation in membrane cell configurations offers modular capacity expansion with reduced carbon footprint versus thermal routes.
- Catalytic Carbonation:Proprietary heterogeneous catalyst systems enable continuous CO2 fixation, with Mitsubishi Chemical Group's technology reducing energy intensity in carbonate synthesis.
- Biocatalysis:Whole-cell fermentation approaches using engineered yeast strains are advancing through pilot stages, targeting fully bio-based production from crude glycerol feedstock.
Chemical synthesis retains the dominant share of operating capacity; enzymatic conversion is climbing the fastest.
Application:
End-use performance requirements dictate grade selection, with thermal stability and polarity specifications varying across formulation contexts.
- Solvents:High boiling point and low vapor pressure suit glycerol carbonate for high-temperature coating applications where VOC emissions are restricted.
- Electrolytes:Lithium-ion battery manufacturers specify carbonate purity for thermal stability in electric vehicle electrolyte formulations, with demand concentrating in German and South Korean cell production clusters.
- Surfactants:Personal care and detergent formulators leverage biodegradability and low aquatic toxicity profiles in EU Ecolabel-compliant products.
- Coatings:Automotive and industrial paint producers substitute petroleum-derived solvents under EU Green Deal mandates, with Italian and Spanish formulators accelerating qualification.
- Adhesives:Reactive diluent applications in epoxy and polyurethane systems benefit from carbonate polarity and low shrinkage characteristics.
- Plasticizers:Polymer compatibility and migration resistance support use in flexible PVC and biopolymer compounds.
Solvent applications command the largest volume commitment; electrolyte demand is gaining share fastest.
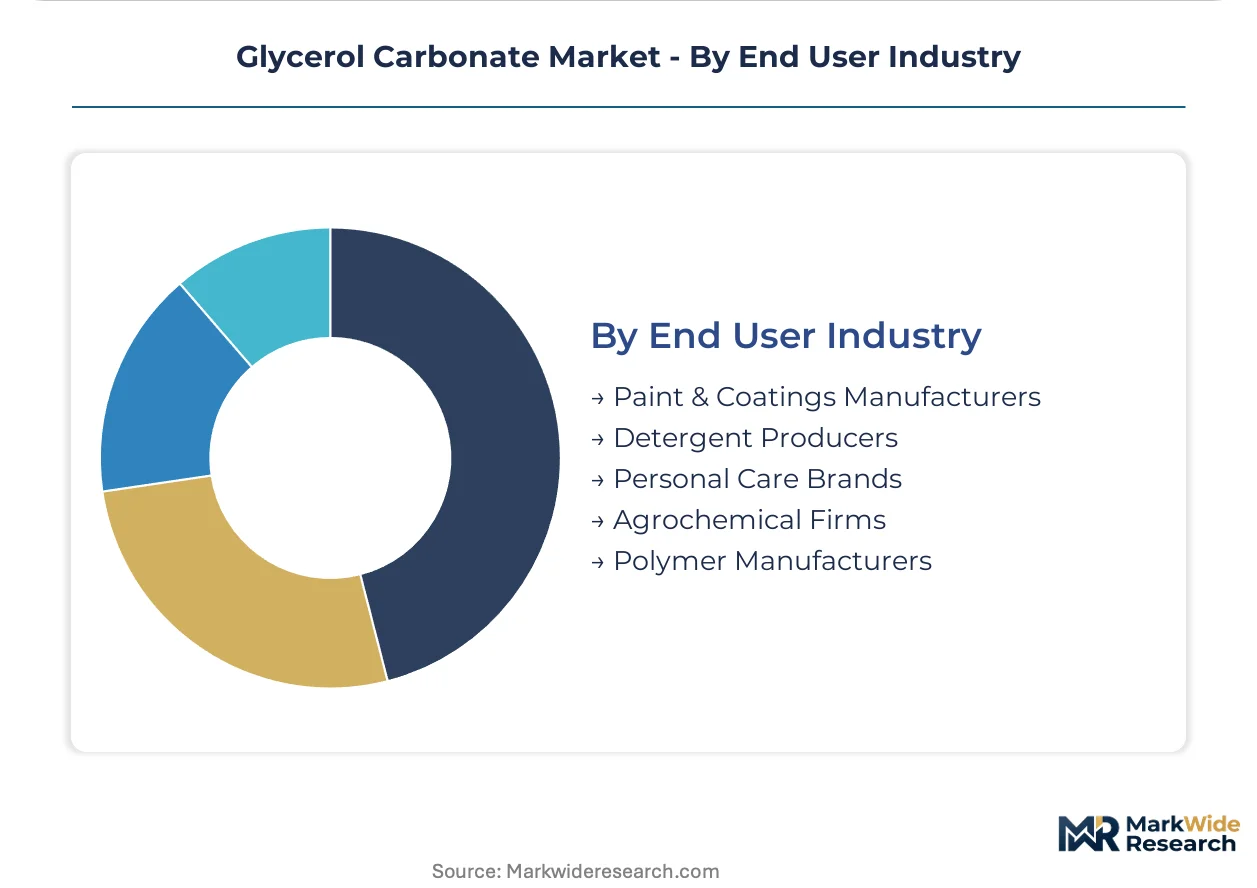
End User Industry:
Customer concentration and procurement power vary sharply, with automotive coaters consolidating vendor lists while agrochemical buyers fragment across regional formulators.
- Paint & Coatings Manufacturers:Tier-one automotive coaters in Germany's industrial corridor are reducing qualified glycerol carbonate suppliers from twelve to four, concentrating volume with dual-registered producers.
- Detergent Producers:Large-scale surfactant manufacturers specify industrial-grade carbonate for EU Ecolabel and Nordic Swan compliance in household cleaning formulations.
- Personal Care Brands:Mid-volume cosmetic manufacturers are bypassing traditional distributors through direct-to-formulator e-commerce platforms, reshaping channel economics.
- Agrochemical Firms:Pesticide and herbicide formulators in France and Germany specify agricultural-grade carbonate as a solvent and carrier, with demand cyclicality tied to planting seasons.
- Polymer Manufacturers:Biopolymer and specialty resin producers incorporate carbonate plasticizers for flexibility and processing aid functions.
Paint and coatings manufacturers absorb the dominant share of industrial-grade output; personal care brands are expanding procurement most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Industrial Chemical Corridor operates as the primary tax-advantaged zone for glycerol carbonate concentration, with Belgium's Antwerp-Rotterdam port complex and Japan's Kansai chemical belt forming secondary poles of specialized capacity.
Germany
Automotive coating supply chains in Stuttgart and Wolfsburg absorb industrial-grade volumes as REACH VOC limits tighten. The EU Green Deal mandates accelerate solvent substitution in manufacturing clusters along the Rhine. Specialty producers in North Rhine-Westphalia consolidate registration assets to meet ECHA substance evaluation deadlines.
Belgium
Pharmaceutical-grade output concentrates near Antwerp's chlor-alkali infrastructure, serving injectable drug formulators across the Benelux. REACH registration protocols elevate compliance costs for import-dependent processors. Integrated producers in the port region leverage captive epichlorohydrin feedstock for purity-controlled carbonate synthesis.
Japan
Mitsubishi Chemical Group anchors Kansai-region carbonate production through proprietary catalytic carbonation systems. METI chemical safety frameworks govern phosgene handling protocols at legacy facilities. Osaka-based manufacturers supply high-purity grades to domestic lithium-ion battery electrolyte formulators.
China
Shandong and Jiangsu provinces control bulk industrial-grade export volumes, creating supply concentration risks for European formulators. MEE GB standards on industrial chemical emissions shape production economics at coastal export facilities. Qingdao chemical parks house integrated glycerol-to-carbonate processing trains serving coatings manufacturers.
United States
EPA Toxic Substances Control Act notifications govern carbonate derivative commerce, with demand concentrating in Texas and Louisiana chemical corridors. OSHA process safety management rules impose capital requirements on phosgene-handling infrastructure. Gulf Coast biodiesel refineries provide crude glycerol feedstock for regional carbonate synthesis.
Glycerol Carbonate Market Key Industry Players
Belgian and German producers anchor the premium-grade tier; Chinese fabricators hold volume-driven industrial positions. The vendor base separates into three strata: integrated chlor-alkali operators, biodiesel-integrated biocatalytic specialists, and import-dependent formulation distributors. Strategic moves concentrate on REACH registration consolidation and enzymatic carbonation licensing.
Within the integrated chemical conglomerate tier, Solvay SA and BASF SE exemplify divergent feedstock strategies—Solvay leveraging chlor-alkali integration while BASF SE anchors bio-based glycerol sourcing. Mitsubishi Chemical Group occupies a distinct position through catalytic technology specialization. These three entities represent the dominant competitive archetypes: legacy chemical integration, renewable feedstock backward integration, and proprietary process technology licensing.
| Leading Market Players |
|---|
| Solvay SA |
| Mitsubishi Chemical Group |
| BASF SE |
| Cargill, Incorporated |
| Merck KGaA |
| Huntsman Corporation |
| Evonik Industries AG |
| Perstorp Holding AB |
| UBE Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Epichlorohydrin spot indices and propylene feedstock benchmarks cascade through glycerol carbonate supply chains, compressing margins for chlor-alkali producers while enzymatic carbonation specialists capture premium pricing through phosgene-free certification tiers.
Pricing Analysis
Short lead-time premiums distinguish pharmaceutical-grade procurement, with Swiss and Belgian facilities commanding 15-20% markups over spot industrial volumes for USP-compliant injectable output. Three-tier pricing structure across pharmaceutical, industrial, and cosmetic grades reflects certification burden and purity validation cycles. Cost compression in industrial-grade segments intensifies as Shandong export volumes pressure European formulators. Detergent producers and coatings manufacturers exhibit highest price sensitivity, while lithium-ion battery electrolyte specialists prioritize thermal stability specifications over unit economics.
Supply Chain Analysis
Regional distribution centers in Antwerp-Rotterdam and Hamburg-Rotterdam corridors buffer European formulators against Chinese supply concentration, with hub-and-spoke patterns radiating into Stuttgart and Wolfsburg automotive clusters. Manufacturing gravity centers on China, Belgium, and Germany, with Shandong province controlling bulk industrial-grade export volumes. Feedstock dependencies span crude glycerol from European biodiesel refineries, propylene derivatives from chlor-alkali complexes, and immobilized enzyme preparations from Swiss biocatalysis specialists. Single-source vulnerability pervades pharmaceutical-grade supply, where Solvay's Belgian and Japanese facilities dominate USP-monograph output. Distribution runs through specialty chemical distributors for mid-volume personal care manufacturers, while tier-one automotive coaters negotiate direct long-term offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade capacity scarcity props pricing across all purity tiers, with enzymatic carbonation bottlenecks constraining qualified supply expansion.
For Market Incumbents: Hedge phosgene-exposure liability through biocatalytic carbonation licensing or joint ventures with German enzyme technology specialists. Consolidate REACH registration assets ahead of ECHA substance evaluation deadlines to defend vendor list positions at Stuttgart automotive coaters. Prioritize backward integration into biodiesel refinery glycerol streams to neutralize propylene feedstock volatility. For New Entrants and Emerging Players: Launch via direct-to-formulator e-commerce platforms targeting mid-volume cosmetic manufacturers in Southern Europe, bypassing traditional distributor markups. Cosmetic-grade surfactant channels offer lowest certification barriers and fastest qualification cycles. White-space concentrates in agricultural-grade formulations for French and German agrochemical formulators, where REACH compliance requirements remain less stringent than pharmaceutical tiers. For Investors and Strategic Acquirers: Distressed-cycle entries favor biodiesel-integrated biocatalytic specialists in Germany's North Rhine-Westphalia corridor, where crude glycerol captive supply meets enzymatic carbonation scale-up potential. Five-to-ten-year viability hinges on phosgene-elimination technology maturation and EU carbon border adjustment alignment. Monitor ECHA registration completion rates as inflection indicator for supply consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Carbonation Scale-Up | Eliminates phosgene handling liability while securing pharmaceutical-grade certification premiums. |
| Backward Integration into Biodiesel Refineries | Captures crude glycerol feedstock cost advantage and aligns with EU Green Deal bio-based mandates. |
| REACH Registration Consolidation | Preserves European market access as ECHA substance evaluation protocols tighten import requirements. |
| Direct-to-Formulator E-Commerce Launch | Bypasses distributor markups for mid-volume personal care manufacturers seeking cosmetic-grade supply. |
| Long-Term Automotive Coater Offtake Agreements | Locks in industrial-grade volume commitments as German tier-one suppliers reduce qualified vendor lists. |
Research Approach
Trade databases, ECHA registration filings, and SEC chemical segment disclosures formed the secondary backbone, cross-referenced with primary interviews spanning plant managers at chlor-alkali facilities, procurement leads at Stuttgart automotive coaters, technical R&D directors at specialty solvent producers, and distribution channel partners in the Antwerp-Rotterdam corridor. Bottom-up capacity modeling and top-down demand segmentation were triangulated against customs flow data and biodiesel refinery output statistics.
Historical trendline analysis anchored the projection framework, with growth rates derived from segment-specific demand elasticity modeling across pharmaceutical, industrial, and cosmetic grade tiers. Segmentation dimensions spanned purity certification level, synthesis technology route, end-use application, and regional production hub concentration. Forecast inputs incorporated REACH compliance cost trajectories, enzymatic carbonation scale-up curves, and lithium-ion battery electrolyte formulation adoption patterns across German and South Korean cell manufacturing clusters.
Feedstock price volatility, regulatory registration timeline slippage, and biocatalytic technology scale-up failures are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding ECHA enforcement intensity and carbon border adjustment implementation scope. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
White Phosphorus Market
Chemicals
Aromatic Polyamine Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Phenylethyl Market
Chemicals
Scouring Agents Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
Etidronic Acid Market
Chemicals
Chemical Distribution Market
Chemicals
Naturally Derived Fatty Alcohol Market
Chemicals
Southeast Asia Construction Chemicals Market
Chemicals
Peroxyacetic Acid Market
Chemicals
Coal Tar Market
Chemicals
Integrated Chemistry Systems Market
Chemicals
Valeronitrile Market
Chemicals
Calcium Methoxide Market
Chemicals
Fluoroboric Acid Market