
 Fipronil Market | 2026-2036
Fipronil Market Size, Share, and Industry Trends Forecast 2026-2036
Fipronil Market Analysis
Agronomic expertise in integrated pest management is collapsing across major cotton-growing belts, forcing growers toward simpler chemical protocols. BASF SE leverages its phenylpyrazole patent estate to sustain premium positioning in seed treatment formulations. Bayer AG anchors its position through veterinary product lines that extend into companion animal parasiticides. Sumitomo Chemical Company Limited dominates Asian manufacturing scale for technical-grade fipronil.
Fipronil is a broad-spectrum phenylpyrazole insecticide that acts as a GABA-gated chloride channel antagonist, typically formulated as suspension concentrate or emulsifiable concentrate for foliar and soil applications. Its primary commercial purpose centers on controlling chewing and sucking insect pests across row crops, turf, and companion animals. Agricultural Chemicals command the largest product type share, reflecting sustained procurement from cotton and rice value chains. Animal Health applications generate disproportionate margin pools due to regulatory barriers and brand loyalty among veterinary prescribers. Powder formulations lag in growth velocity as farmers migrate toward liquid delivery systems that reduce handler exposure.
EPA tolerance assessments and EU REACH compliance obligations shape residue limits and import acceptance criteria for fipronil-treated commodities. India's Central Insecticides Board registration requirements create additional market access filters for imported technical material. Brazil's ANVISA and China's MEE both enforce environmental fate testing that extends product development timelines. Stakeholders must monitor evolving pollinator risk assessments that could trigger formulation restrictions or buffer zone mandates without advance notice.
Market Dynamics
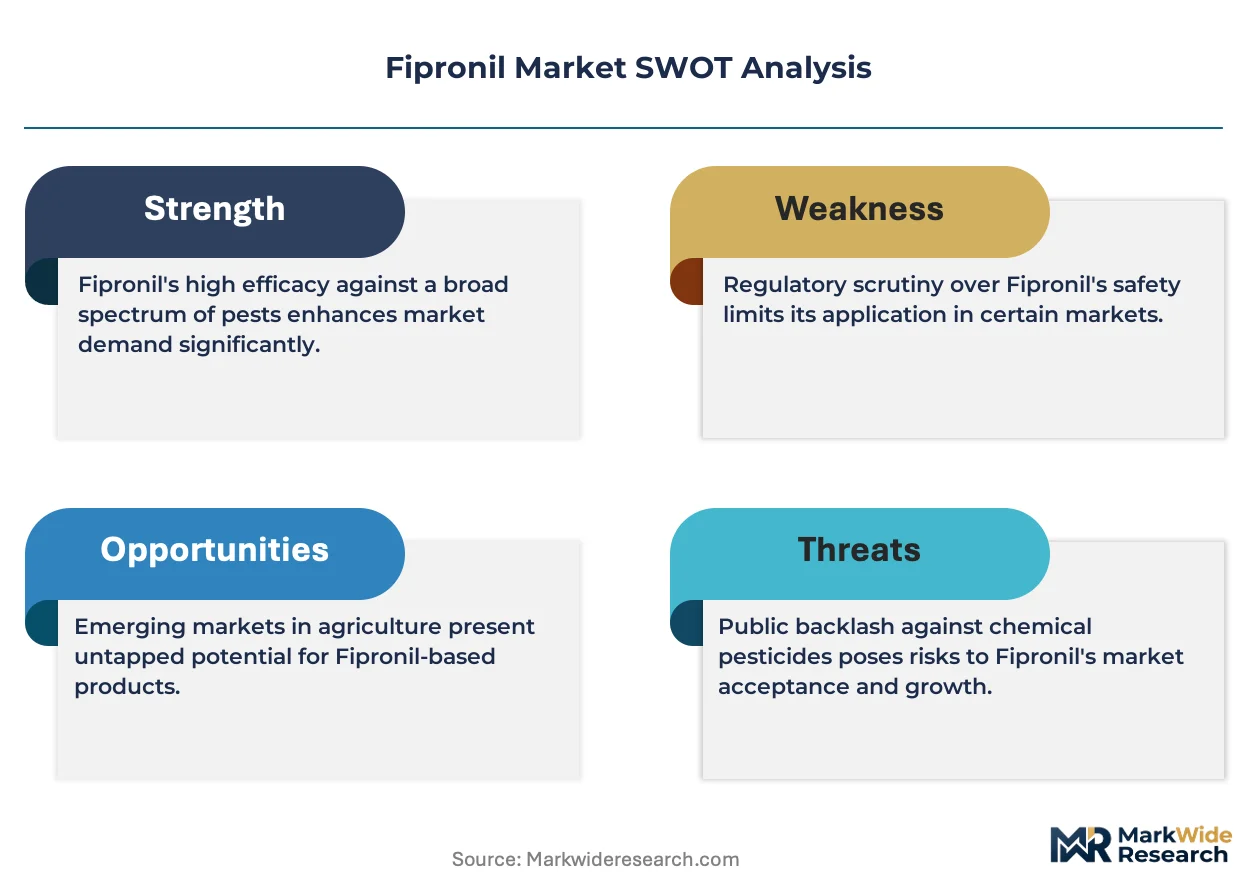
Neonicotinoid phase-outs across the European Union are redirecting farmer preference toward phenylpyrazole alternatives, compressing the window for technical-grade supply expansion and forcing reformulation investments from incumbent producers.
Growth Catalysts
- EU Green Deal pesticide reduction targets:Member states are accelerating neonicotinoid withdrawals under the Farm to Fork Strategy, creating immediate substitution demand for fipronil-based seed treatments in sugar beet and maize rotations.
- Cotton bollworm pressure in Maharashtra and Gujarat:Resistance to pyrethroids and organophosphates is driving procurement of phenylpyrazole alternatives for foliar spray programs during peak infestation windows.
- Seed treatment technology migration:Film-coating equipment upgrades across Brazilian soybean cooperatives are enabling precision application of fipronil-based protectants at sub-lethal dose rates.
Market Restraints
- Technical-grade concentration in Asian manufacturing:Over three-quarters of active pharmaceutical ingredient and technical insecticide synthesis clusters in eastern China, creating single-source vulnerability for formulated product supply chains.
- EPA pollinator risk assessments:Ongoing re-evaluations of phenylpyrazole toxicity to honey bees and wild pollinators are extending registration review timelines and triggering precautionary buffer zone mandates in California almond districts.
- Biological insecticide substitution:Bacillus thuringiensis formulations and pheromone mating disruption systems are capturing share in integrated pest management protocols across European vegetable greenhouse operations.
Strategic Opportunities
- Companion animal parasiticide expansion in Southeast Asia:Pet ownership growth in Bangkok, Jakarta, and Ho Chi Minh City is outpacing veterinary clinic density, creating channel space for over-the-counter fipronil spot-on products.
- India PLI scheme for agrochemical intermediates:Production-linked incentive allocations for technical-grade manufacturing are attracting capital toward domestic phenylpyrazole synthesis capacity in Gujarat and Andhra Pradesh.
- Drone-based precision application:Ultra-low volume spraying systems are enabling targeted fipronil deployment in rice paddy environments previously inaccessible to ground-based equipment, reducing water contamination risk.
Industry Challenges
- Residue analytical laboratory capacity:Brazil's ANVISA and India's FSSAI are expanding maximum residue limit testing protocols faster than certified testing facilities can achieve ISO 17025 accreditation, delaying export clearances.
- Formulation patent cliff navigation:Expiring phenypyrazole composition patents in major jurisdictions are fragmenting technical supply into generic channels, compressing margin pools for proprietary suspension concentrate formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fipronil Market |
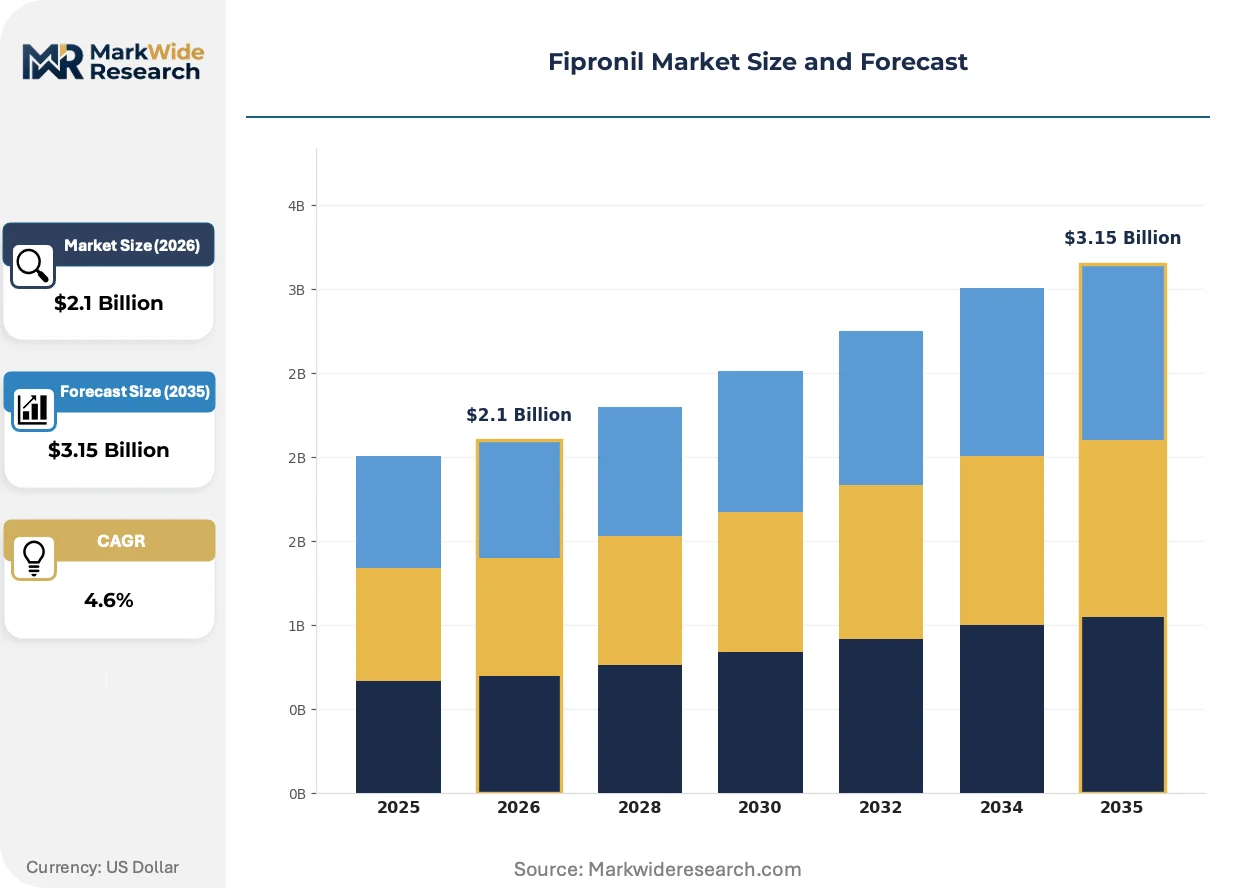
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agricultural Chemicals, Insecticides, Veterinary Products, Lawn Treatments Application: Crop Protection, Pest Control, Animal Health, Household Use End User: Agriculture, Pet Owners, Commercial Farmers, Homeowners Formulation: Suspension Concentrate, Emulsifiable Concentrate, Granules, Powder |
| Companies Covered | Sumitomo Chemical Company Limited, Jiangsu Tuoqiu Agrochemicals Co., Ltd., BASF SE, Albaugh LLC, GSP Crop Science Private Limited, Bayer AG, Parijat Industries (India) Pvt. Ltd., HPM Chemicals, Gharda Chemicals Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fipronil Market Emerging Trajectories
Formulation chemistry and application hardware are converging to reduce environmental load while maintaining insecticidal efficacy, reshaping how phenylpyrazole products reach end-use fields and veterinary clinics.
Microencapsulation technology is miniaturizing active ingredient particle size to sub-micron scales, enabling controlled release kinetics that extend residual efficacy in soil applications. Brazilian sugarcane growers are adopting these formulations for termite control at scale. The technology is compressing re-application frequency requirements and reducing total chemical load per hectare.
REACH authorization requirements for hazardous substance categories are tightening downstream user notification obligations across EU member states. Formulators must now document safe-use scenarios for professional applicators in arable crop sectors. Specialty seed treatment houses in France and Germany are responding by consolidating technical material sourcing through pre-registered supply agreements.
Veterinary prescribers in companion animal practice are unbundling parasiticide dispensing from consultation fees, exposing fipronil spot-on products to direct price comparison in online pharmacy channels. This pattern is most visible in UK and Australian markets where pet insurance penetration drives reimbursement-seeking behavior. Clinic-based loyalty programs are losing share to subscription auto-delivery platforms.
Fipronil Market Segmentation
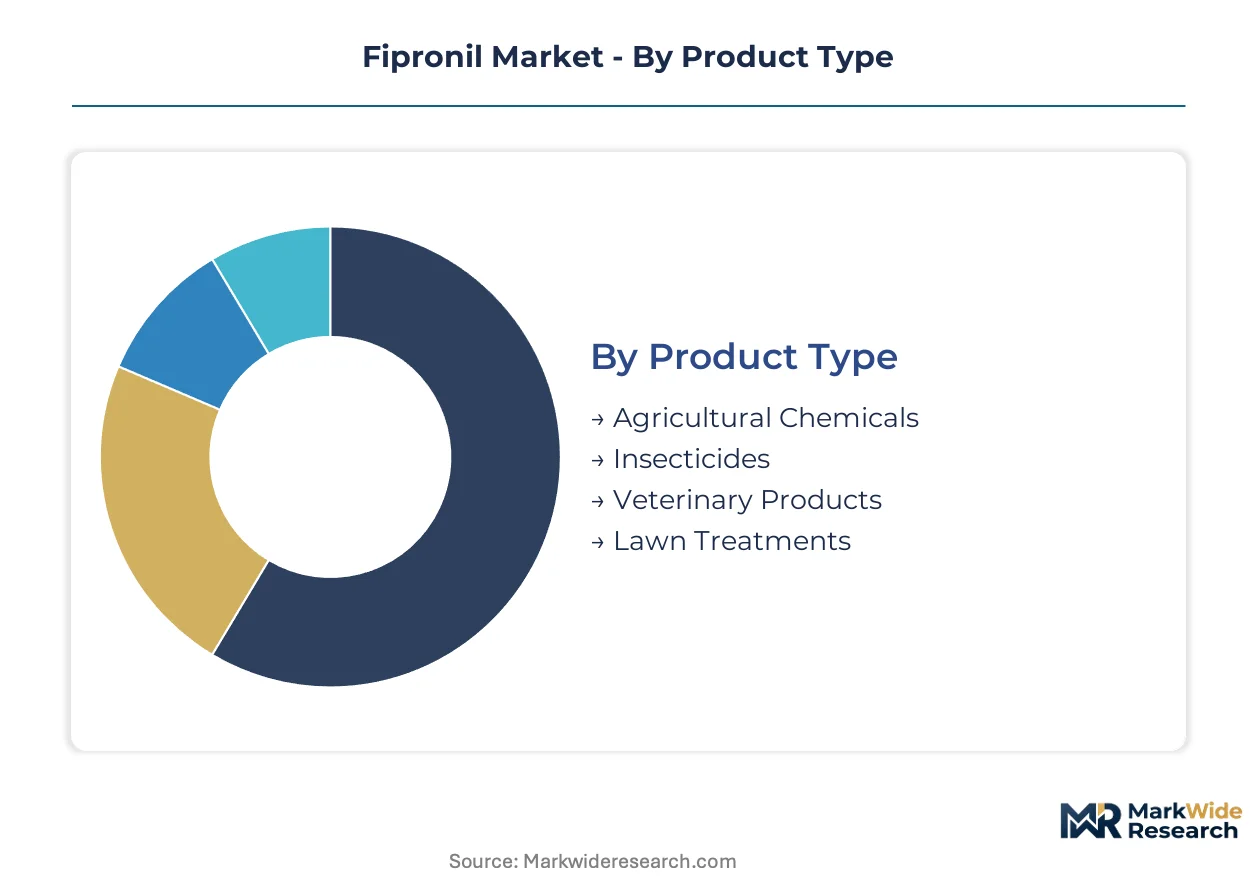
Fipronil procurement patterns diverge sharply between export-oriented agricultural chemical channels and domestically consumed veterinary formulations. Understanding these segment boundaries clarifies where formulation investments yield margin protection versus volume capture.
Product Type:
Agricultural Chemicals and Insecticides dominate cross-border trade flows, while Veterinary Products and Lawn Treatments serve largely captive domestic markets.
- Agricultural Chemicals:Technical-grade material formulated as suspension concentrates for seed treatment and foliar application. Demand concentrates in Indian cotton belts and Brazilian soybean cooperatives where phenylpyrazole alternatives replace phased-out neonicotinoids under EU Green Deal directives.
- Insecticides:Broad-spectrum phenylpyrazole compounds targeting chewing and sucking pests across row crops. Procurement runs heaviest through Maharashtra and Gujarat state procurement channels during peak bollworm infestation windows.
- Veterinary Products:Companion animal parasiticides including spot-on formulations for flea and tick control.
- Lawn Treatments:Turf and ornamental applications for termite and ant control in residential and golf course settings.
Agricultural Chemicals commands the established base. The steepest expansion runs through Veterinary Products.
Application:
Cost-tier stratification separates high-volume crop protection from premium-priced animal health and household channels.
- Crop Protection:Field-scale deployment across cotton, rice, maize, and sugar beet rotations. Film-coating equipment upgrades in Brazilian cooperatives enable precision application at sub-lethal dose rates, compressing re-application frequency.
- Pest Control:Professional and residential termite management programs. Microencapsulation technology adoption in Brazilian sugarcane regions extends residual efficacy against subterranean termite pressure.
- Animal Health:Veterinary prescription and over-the-counter parasiticide channels. Pet ownership growth in Bangkok, Jakarta, and Ho Chi Minh City outpaces clinic density, opening channel space for subscription auto-delivery platforms.
- Household Use:Consumer-facing ant and roach control products in retail home improvement channels.
Crop Protection anchors volume throughput. Animal Health delivers the widest margin spreads.
End User:
Customer-type fragmentation creates distinct procurement rhythms between institutional agriculture and fragmented pet owner segments.
- Agriculture:State-level procurement authorities and cooperative buying groups across Indian cotton belts. Integrated pest management collapse forces simpler chemical protocols on growers with depleted agronomic expertise.
- Commercial Farmers:Large-scale row crop operations in Brazil and the US Midwest. Drone-based ultra-low volume spraying systems enable targeted deployment in rice paddy environments previously inaccessible to ground equipment.
- Pet Owners:Individual consumers purchasing through veterinary clinics, retail pharmacies, and online subscription platforms. UK and Australian markets show pronounced shift toward reimbursement-seeking behavior through pet insurance channels.
- Homeowners:Residential lawn and perimeter pest control purchasers.
Commercial Farmers drive technical-grade volume. Pet Owners are expanding most quickly.
Formulation:
Supply concentration in Asian manufacturing clusters shapes which formulation types reach export markets versus domestic channels.
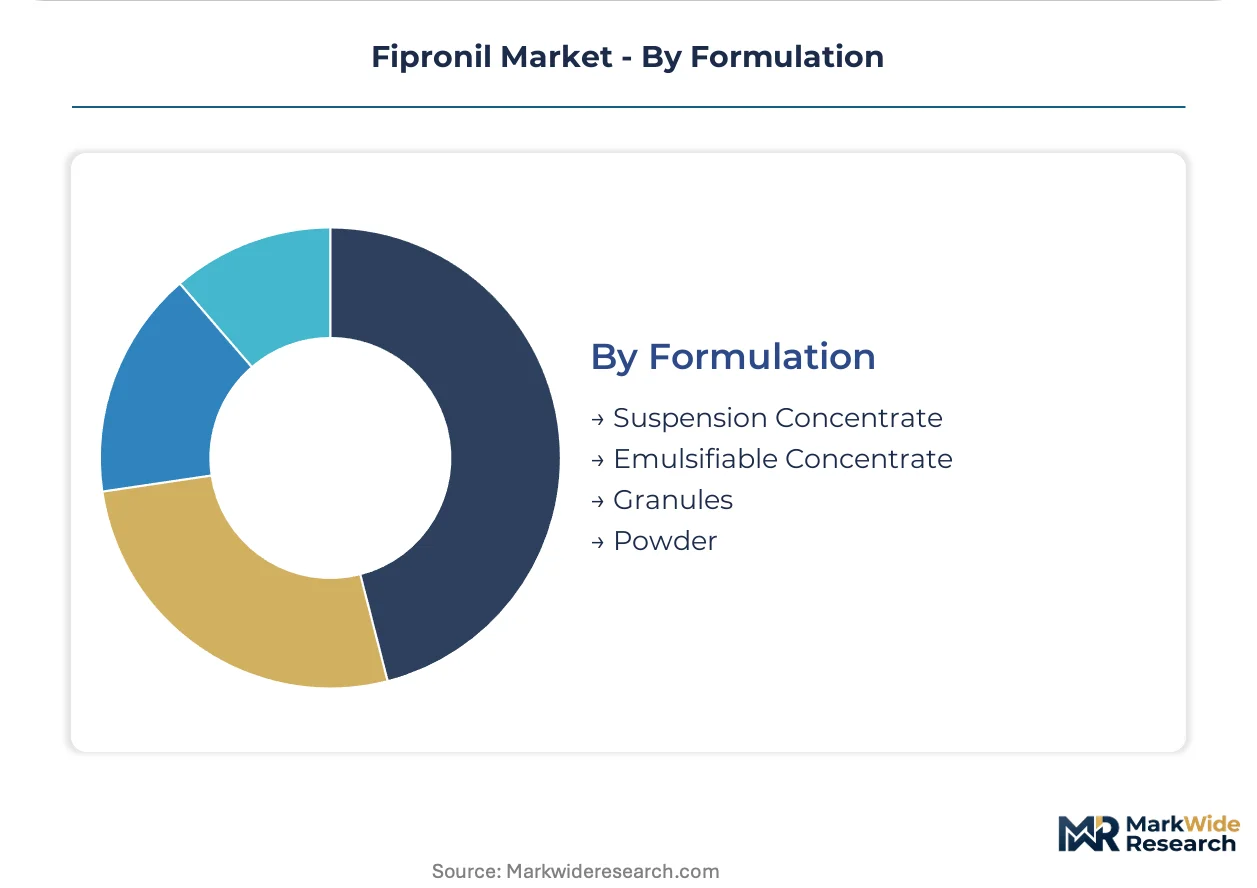
- Suspension Concentrate:Aqueous dispersions of technical-grade fipronil enabling uniform foliar coverage. Preferred in EU sugar beet and maize rotations where seed treatment substitution demand accelerates under Farm to Fork pesticide reduction targets.
- Emulsifiable Concentrate:Oil-based formulations for soil injection and perimeter barrier applications. Dominates professional pest control channels in US termite management programs.
- Granules:Slow-release matrices for soil incorporation in turf and ornamental settings.
- Powder:Dry formulations for dusting applications. Growth velocity lags as handlers migrate toward liquid delivery systems reducing exposure risk.
Suspension Concentrate holds the dominant share. Emulsifiable Concentrate shows the steepest climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Central Insecticides Board anchors regulatory demand for fipronil formulations, with cotton and rice procurement channels sustaining heavy insecticide application across Maharashtra and Gujarat state authorities.
India
Cotton bollworm pressure in Maharashtra and Gujarat drives phenylpyrazole procurement through state-level channels during peak infestation windows. The PLI scheme for agrochemical intermediates attracts capital toward domestic technical-grade synthesis capacity in Gujarat and Andhra Pradesh. Drone-based ultra-low volume spraying systems enable targeted deployment in rice paddy environments previously inaccessible to ground equipment.
Brazil
ANVISA environmental fate testing extends product development timelines for imported technical material. Film-coating equipment upgrades across soybean cooperatives enable precision application of seed treatment formulations at sub-lethal dose rates. Microencapsulation technology adoption in sugarcane regions extends residual efficacy against subterranean termite pressure.
United States
EPA pollinator risk assessments trigger precautionary buffer zone mandates in California almond districts. Emulsifiable concentrate formulations dominate professional pest control channels for soil injection and perimeter barrier applications. The EPA tolerance assessment framework shapes residue limits for treated commodity exports.
Germany
EU Green Deal pesticide reduction targets accelerate neonicotinoid withdrawals under the Farm to Fork Strategy, creating substitution demand for seed treatments in sugar beet and maize rotations. REACH authorization requirements tighten downstream user notification obligations across member states. Specialty seed treatment houses in France and Germany consolidate technical material sourcing through pre-registered supply agreements.
China
MEE environmental fate testing protocols govern technical-grade manufacturing clusters in eastern provinces. Over three-quarters of active pharmaceutical ingredient and technical insecticide synthesis concentrates in eastern China, creating single-source vulnerability for formulated product supply chains. NMPA registration requirements filter market access for domestic and imported formulations alike.
Fipronil Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with patent estate holders commanding premium positioning in seed treatment formulations while generic technical suppliers compete on manufacturing scale. The market structure separates proprietary suspension concentrate formulators from commodity technical-grade producers. Three archetypes dominate: integrated agrochemical conglomerates with phenylpyrazole patent estates, Asian technical-grade manufacturers serving export formulation channels, and regional formulators capturing domestic procurement contracts. Capacity expansion in Indian technical synthesis and strategic partnerships for drone-based application systems represent the dominant competitive moves.
Among Japanese and German integrated conglomerates, Sumitomo Chemical Company Limited and BASF SE exemplify the patent-holding tier with established positions in phenylpyrazole chemistry, while Bayer AG occupies a position spanning agricultural and veterinary application channels. These three entities represent the concentration of proprietary formulation expertise against a backdrop of fragmenting technical supply.
| Leading Market Players |
|---|
| Sumitomo Chemical Company Limited |
| Jiangsu Tuoqiu Agrochemicals Co., Ltd. |
| BASF SE |
| Albaugh LLC |
| GSP Crop Science Private Limited |
| Bayer AG |
| Parijat Industries (India) Pvt. Ltd. |
| HPM Chemicals |
| Gharda Chemicals Limited |
| Others |
Supply Flow & Price Mechanics
Neonicotinoid substitution toward phenylpyrazole alternatives in EU sugar beet and maize rotations is compressing technical-grade supply windows while simultaneously elevating procurement premiums for Indian cotton cooperatives and Brazilian soybean growers.
Pricing Analysis
Price spreads between technical-grade material sourced from eastern Chinese manufacturing clusters and formulated product delivered to EU seed treatment houses run wide due to REACH authorization compliance costs. Three-tier pricing structure across proprietary suspension concentrates, licensed formulations, and generic technical separates BASF and Sumitomo patent-holders from Indian domestic producers. Cost compression in standard-grade channels is intensifying because of expiring composition patents fragmenting supply into generic pools. State procurement authorities in Maharashtra and Gujarat exhibit highest price sensitivity, while veterinary prescribers in Bangkok and Jakarta show lowest sensitivity due to brand loyalty and reimbursement-seeking behavior.
Supply Chain Analysis
Inventory lead times for technical-grade fipronil stretch longer than formulated product cycles due to ANVISA and MEE environmental fate testing protocols. Supply concentrates in eastern China, India, and Germany, with over three-quarters of active pharmaceutical ingredient and technical insecticide synthesis anchored in Chinese coastal provinces. Raw material dependencies include 4-trifluoromethylphenylhydrazine, trifluoromethylsulfinyl chloride, and pyrazole ring precursors. Single-source vulnerability in eastern Chinese manufacturing clusters creates systemic risk for formulated product supply chains. Distribution runs through pre-registered supply agreements between specialty seed treatment houses and technical-grade manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise and REACH compliance capabilities are scarce assets concentrated among patent-holding conglomerates, leaving generic technical suppliers exposed to margin compression and regulatory exclusion.
For Market Incumbents: Shield proprietary margin pools by deepening backward integration into technical-grade synthesis capacity in Gujarat and Andhra Pradesh under India's PLI scheme. Accelerate microencapsulation patent filings to extend residual efficacy claims before generic competitors replicate controlled-release kinetics. The priority lever sits with pre-registered REACH supply agreements that lock EU seed treatment houses into exclusive technical material channels. For New Entrants and Emerging Players: Anchor in drone-based precision application services for rice paddy environments in Vietnam and Indonesia, where ground equipment access remains limited and ultra-low volume spraying commands premium deployment fees. Target over-the-counter veterinary channels in Ho Chi Minh City and Jakarta, where pet ownership growth outpaces clinic density and subscription auto-delivery platforms are capturing share from traditional veterinary dispensing. The penetrable entry point runs through film-coating equipment upgrade partnerships with Brazilian soybean cooperatives. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian agrochemical intermediates producers holding PLI scheme allocations but lacking formulation expertise to reach export markets. Long-term viability hinges on regulatory navigation capabilities across EPA, REACH, and ANVISA frameworks rather than pure manufacturing scale. The acquisition target archetype combines domestic technical synthesis capacity with dormant patent estates for controlled-release delivery systems. Watch for EPA pollinator risk assessment outcomes as the inflection signal that could trigger buffer zone mandates and reformulation investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical Synthesis | PLI scheme allocations in Gujarat reduce import dependence for Indian formulators serving cotton procurement channels. |
| Microencapsulation Patent Expansion | Sub-micron particle size claims extend residual efficacy in Brazilian sugarcane termite control applications. |
| Pre-registered REACH Supply Agreements | Downstream user notification obligations in France and Germany favor consolidated technical sourcing relationships. |
| Drone Application System Partnerships | Ultra-low volume spraying in Vietnamese rice paddies opens previously inaccessible acreage to phenylpyrazole deployment. |
| Veterinary Channel Subscription Platforms | Auto-delivery models in Bangkok and Jakarta bypass clinic-based dispensing to capture pet owner reimbursement behavior. |
Methodological Framework
Initial hypotheses were tested against primary input from agrochemical procurement managers at Indian state authorities, technical R&D directors at phenylpyrazole patent holders, veterinary clinic operators in Southeast Asian metropolitan markets, and seed treatment formulators in EU member states, then refined through customs trade data, Central Insecticides Board registration filings, EPA tolerance assessment documents, and SEC 10-K disclosures from listed agrochemical conglomerates. Bottom-up volume estimates from crop-acreage application rates were triangulated against top-down technical-grade production capacity assessments.
Variance decomposition across the projection horizon isolates volume drivers by product type, application channel, formulation technology, and regional regulatory cluster. Segmentation modeling incorporated grade tier distinctions between technical and formulated material, end-use splits across crop protection and animal health, packaging format differences for liquid versus dry delivery, and regional production hub classifications. CAGRs were derived from regression analysis of historical procurement patterns against acreage expansion and substitution elasticity parameters, with specific inputs including neonicotinoid phase-out schedules and cotton bollworm resistance monitoring data from Maharashtra agricultural extension services.
Decision-makers should treat outputs as directional under assumptions of stable EU Green Deal implementation timelines and continued pyrethroid resistance progression in Indian cotton belts; material deviation in pollinator risk assessment outcomes or PLI scheme allocation shifts would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
Montelukast API Market
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Grade Hyaluronic Acid Market
Pharmaceutical Ingredients
Global Penicillin Drug Market
Pharmaceutical Ingredients
Duloxetine API Market
Pharmaceutical Ingredients
Global Aspirin Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
Global Sugar-Based Excipients Market
Pharmaceutical Ingredients
Acetaminophen API Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
Pharmaceutical Hot Melt Extrusion Market