
 China Active Pharmaceutical Ingredients (API) Market | 2026-2036
China Active Pharmaceutical Ingredients (API) Market Size, Share, and Industry Trends Forecast 2026-2036
China Active Pharmaceutical Ingredients (API) Market Outlook
Project finance through government-backed industrial bonds is fragmenting capital access across China's API sector, allowing mid-scale fermentation houses to challenge legacy state-owned producers. WuXi AppTec leverages its integrated CDMO platform to anchor high-value biotech API contracts. Zhejiang Huahai Pharmaceutical specializes in cardiovascular and anti-viral chemical synthesis, sustaining FDA-inspected export volumes. CSPC Pharmaceutical Group dominates cephalosporin and antibiotic bulk manufacturing through captive raw-material supply.
Active Pharmaceutical Ingredients are pharmacologically active substances—typically organic molecules, peptides, or recombinant proteins—manufactured through chemical synthesis, fermentation, or biotechnological expression, with purity thresholds and impurity profiles governed by pharmacopeial monographs for incorporation into finished dosage forms. Chemical API retains the largest revenue footprint due to mature generic demand, yet biotech API captures expanding margin pools as monoclonal antibody and cell-therapy pipelines multiply. Contract Research Organizations represent the fastest-growing end-user channel, reflecting pharmaceutical manufacturers' outsourcing of early-phase API development and process validation to reduce fixed-asset intensity.
NMPA's alignment with ICH Q7 guidelines and China's GB standards for pharmaceutical manufacturing reshape facility compliance costs and inspection readiness across domestic API sites. The country's dual carbon goals from MEE enforce energy-efficiency benchmarks that favor continuous-flow chemistry over batch processes in high-volume synthesis. Stakeholders must monitor how evolving green-chemistry mandates and pharmacovigilance data requirements will redraw the cost structure of domestic versus export-oriented API production.
Market Dynamics
NMPA's alignment with ICH Q7 guidelines is compressing compliance timelines for domestic fermentation houses while elevating capital barriers for batch-process incumbents. This regulatory convergence is redrawing competitive positioning between coastal chemical parks and inland legacy sites.
Growth Catalysts
- Dual carbon enforcement:MEE energy-efficiency benchmarks favor continuous-flow chemistry investments, accelerating process upgrades among Zhejiang-based synthesis operators.
- CDMO channel expansion:Contract Research Organizations are consolidating early-phase API development outsourcing, reducing fixed-asset intensity for originator pharmaceutical manufacturers.
- Biotech pipeline proliferation:Monoclonal antibody and cell-therapy candidates multiply investigational new drug filings, pulling demand toward recombinant protein expression capacity.
Market Restraints
- Input cost volatility:Solvent and specialty chemical feedstock prices fluctuate with crude oil derivatives, compressing margin predictability for high-volume antibiotic synthesis.
- Single-region concentration risk:Fermentation capacity clusters disproportionately in Zhejiang province coastal zones, exposing output continuity to localized environmental enforcement actions.
- Regulatory friction:GB standards for pharmaceutical manufacturing impose documentation burdens that extend inspection readiness cycles for export-oriented sites.
Strategic Opportunities
- Jiangsu province expansion:Underpenetrated northern chemical parks offer greenfield fermentation infrastructure with lower land costs than saturated Zhejiang zones.
- Continuous manufacturing adoption:Flow chemistry integration with real-time release testing converges process analytical technology with reduced batch failure rates.
- Pharmacovigilance data mandates:NMPA post-market surveillance requirements create service revenue streams for domestic API houses with integrated quality systems.
Industry Challenges
- Process analytical talent scarcity:Continuous-flow chemistry operations require specialized engineers with hybrid chemical engineering and data science competencies that domestic programs underproduce.
- Legacy system integration friction:Electronic batch record implementation at state-owned fermentation sites encounters technical debt from decades-old distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Active Pharmaceutical Ingredients (API) Market |
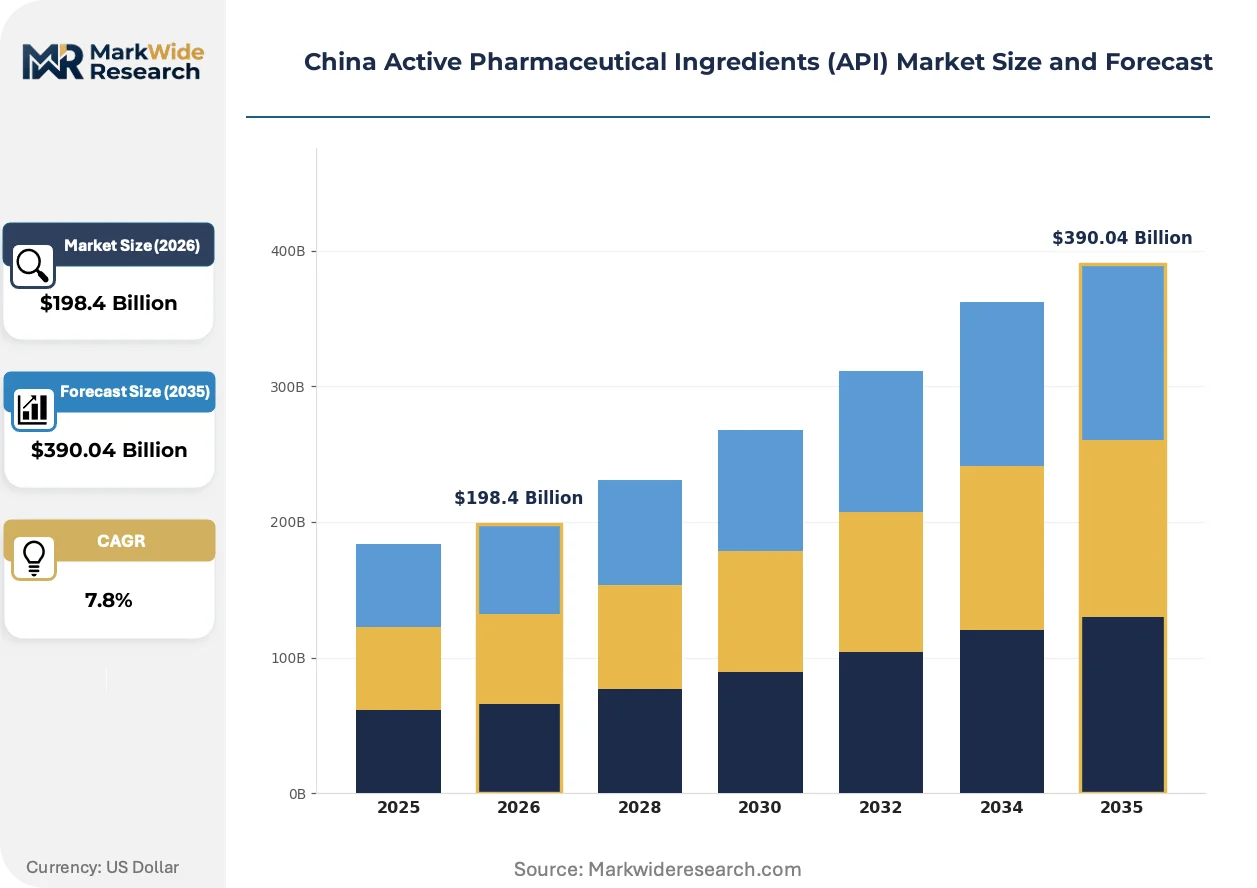
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $390.04 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical API, Biotech API, Organic API, Synthetic API End User: Pharmaceutical Manufacturers, Contract Research Organizations, Hospitals, Distribution Centers Therapy Area: Cardiovascular, Oncology, Neurology, Infectious Diseases Form: Solid, Liquid, Semi-Solid, Powder |
| Companies Covered | STA Pharmaceutical Co., Ltd., WuXi AppTec, Apeloa Pharmaceutical Co., Ltd., Guobang Pharmaceutical Group, ShanDong Xinhua Pharmaceutical, CSPC Pharmaceutical Group, North China Pharmaceutical Group, Zhejiang Huahai Pharmaceutical, Zhejiang Medicine Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Active Pharmaceutical Ingredients (API) Market Strategic Shifts
Process intensification and regulatory data harmonization are compressing development timelines while elevating technical barriers for API manufacturers serving both domestic and export markets.
Continuous-flow reactor technology is migrating from pilot-scale demonstration to commercial antibiotic and intermediate production. Zhejiang-based fermentation houses are retrofitting existing batch infrastructure with modular flow chemistry skids to reduce solvent consumption and thermal hazard exposure. This technology transition is enabling smaller footprint facilities with faster product changeover capabilities, compressing capital recovery periods for multi-product synthesis sites.
NMPA's adoption of ICH Q7 guidelines is mandating quality management system upgrades across domestic API manufacturing. The regulation requires documented process validation and supplier qualification protocols that mirror FDA inspection standards. Export-oriented chemical synthesis operators in Taizhou and Shaoxing chemical parks are responding by consolidating quality functions and investing in dedicated regulatory affairs capabilities to maintain dual-market access.
CDMO procurement patterns are consolidating toward integrated platform providers capable of spanning cell-line development through commercial API supply. Originators are reducing vendor panels and extending contract durations to lock in capacity for biotech pipeline candidates. This buyer concentration is most visible among Shanghai and Suzhou-based biopharmaceutical developers with multiple monoclonal antibody assets advancing to Phase III.
China Active Pharmaceutical Ingredients (API) Market Segmentation
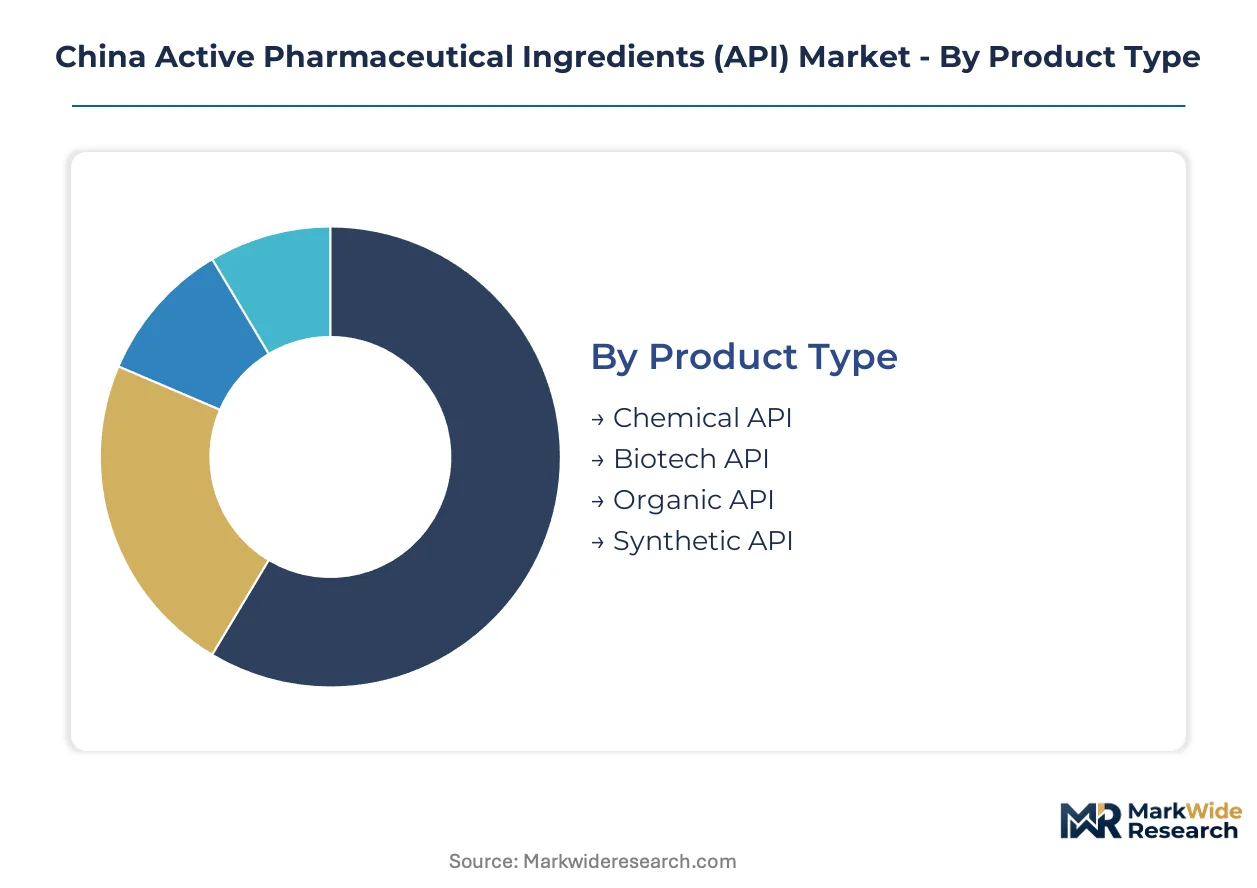
API segmentation in China reveals distinct manufacturing footprints, regulatory pathways, and customer procurement patterns. Each dimension shapes facility investment decisions and margin structures differently across the value chain.
Product Type:
After-sales service intensity varies sharply across production modalities, with fermentation-based categories demanding specialized technical support for bioreactor maintenance and contamination control.
- Chemical API:Manufactured through organic synthesis routes with established impurity profiling under pharmacopeial monographs. Demand concentrates among generic pharmaceutical manufacturers in Taizhou chemical parks, where NMPA's ICH Q7 alignment has compressed compliance timelines for batch-process operators.
- Biotech API:Encompasses recombinant proteins and monoclonal antibodies produced via mammalian or microbial expression systems. CDMO procurement in Suzhou and Shanghai biotech clusters is pulling capacity expansion toward single-use bioreactor platforms with integrated downstream purification.
- Organic API:Natural product derivatives extracted or semi-synthesized from plant or fermentation sources. Zhejiang fermentation houses dominate capacity for steroid and alkaloid intermediates.
- Synthetic API:Petrochemical-derived building blocks assembled through multi-step catalytic transformations. Continuous-flow chemistry adoption is displacing legacy batch infrastructure in high-volume antibiotic synthesis.
Chemical API holds the largest share; momentum sits with biotech API as monoclonal antibody pipelines multiply.
End User:
Customer procurement scale determines contract structure, with large-volume buyers commanding dedicated capacity allocations and extended payment terms.
- Pharmaceutical Manufacturers:Integrated drug developers sourcing API for captive formulation operations. State-owned enterprises in Hebei and Shandong maintain backward integration into cephalosporin and penicillin bulk production.
- Contract Research Organizations:Outsourcing intermediaries consolidating early-phase development and process validation. CDMO channel expansion is accelerating among WuXi AppTec and domestic competitors with platform capabilities spanning cell-line development through commercial supply.
- Hospitals:Direct procurement of compounded pharmacy ingredients for specialized formulations. Concentrated in tertiary medical centers with in-house sterile compounding facilities.
- Distribution Centers:Wholesale intermediaries managing inventory aggregation for fragmented regional demand. Logistics networks in Chengdu and Wuhan serve inland provinces with limited coastal API access.
Pharmaceutical manufacturers retain dominant procurement volume; CROs are expanding most quickly as outsourcing penetration deepens.
Therapy Area:
Margin profiles diverge across therapeutic categories based on regulatory complexity, synthesis difficulty, and competitive intensity in finished dosage forms.
- Cardiovascular:Statins, ACE inhibitors, and beta-blockers with mature generic competition. Zhejiang Huahai Pharmaceutical sustains FDA-inspected export volumes for sartan APIs from Taizhou facilities.
- Oncology:Cytotoxic agents and targeted small molecules with high potency handling requirements. Isolated production suites with containment infrastructure elevate capital barriers for new entrants.
- Neurology:CNS-active compounds with narrow therapeutic indices demanding tight impurity control. CSPC Pharmaceutical Group dominates bulk manufacturing for antiepileptic APIs.
- Infectious Diseases:Antibiotic and antiviral APIs with cyclical demand tied to epidemiological patterns. Cephalosporin synthesis clusters in Shijiazhuang face margin pressure from feedstock volatility.
Cardiovascular commands the largest revenue footprint; oncology shows the steepest expansion trajectory driven by pipeline proliferation.
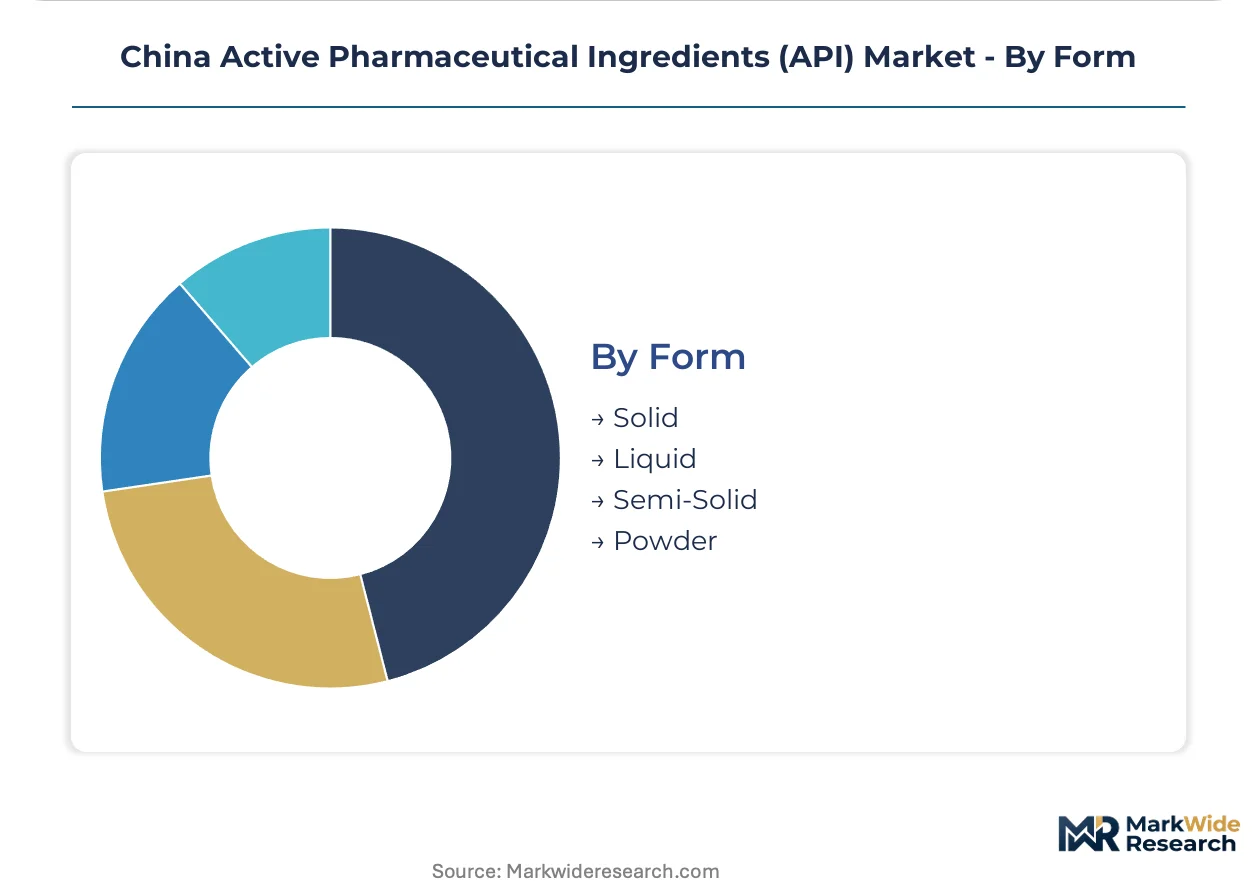
Form:
Physical state dictates packaging, stability testing protocols, and transportation logistics across domestic and export channels.
- Solid:Crystalline powders and granules with defined polymorphism specifications. Dominates oral dosage form feedstock with established handling infrastructure.
- Liquid:Solutions and suspensions for parenteral or ophthalmic applications. Requires aseptic processing capabilities with real-time release testing integration.
- Semi-Solid:Creams, ointments, and gels for topical dermatological formulations. Limited API demand relative to excipient concentration in finished products.
- Powder:Micronized or spray-dried materials for inhalation or rapid-dissolution applications. Particle size distribution specifications drive specialized milling investments.
Solid forms generate the highest shipment volumes; liquid forms are gaining share fastest with parenteral biotech API expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Zhejiang's coastal chemical parks while inland provinces absorb margin compression from feedstock logistics. This asymmetry shapes facility investment patterns across domestic API production zones.
Zhejiang Province
Taizhou and Shaoxing fermentation clusters anchor high-volume antibiotic and cardiovascular API synthesis. NMPA's ICH Q7 alignment has compressed compliance timelines for batch-process operators in these coastal zones. Taizhou chemical parks sustain FDA-inspected export volumes through dedicated regulatory affairs capabilities.
Jiangsu Province
Suzhou and Shanghai biotech clusters pull capacity expansion toward single-use bioreactor platforms for monoclonal antibody expression. The province's northern chemical parks offer greenfield fermentation infrastructure with lower land costs than saturated Zhejiang zones. Nantong and Changzhou house expanding CDMO operations serving originators with Phase III pipeline candidates.
Hebei Province
Shijiazhuang cephalosporin synthesis clusters face margin pressure from solvent feedstock volatility and cyclical antibiotic demand. State-owned enterprises maintain backward integration into penicillin bulk production under GB standards compliance mandates. The province's legacy fermentation sites encounter technical debt from decades-old distributed control architectures.
Shandong Province
Jinan and Weifang chemical parks specialize in synthetic intermediates and steroid API derivatives. MEE dual carbon enforcement accelerates continuous-flow chemistry retrofits among high-volume synthesis operators. The province's coastal access supports export-oriented organic API production with integrated downstream purification.
Sichuan-Chongqing
Chengdu distribution centers manage inventory aggregation for fragmented inland provincial demand with limited coastal API access. The region's underpenetrated fermentation capacity attracts greenfield investment from operators seeking geographic diversification beyond Zhejiang concentration risk. Chongqing's pharmaceutical manufacturing base expands captive API supply for regional formulation operations.
China Active Pharmaceutical Ingredients (API) Market Competitive Environment
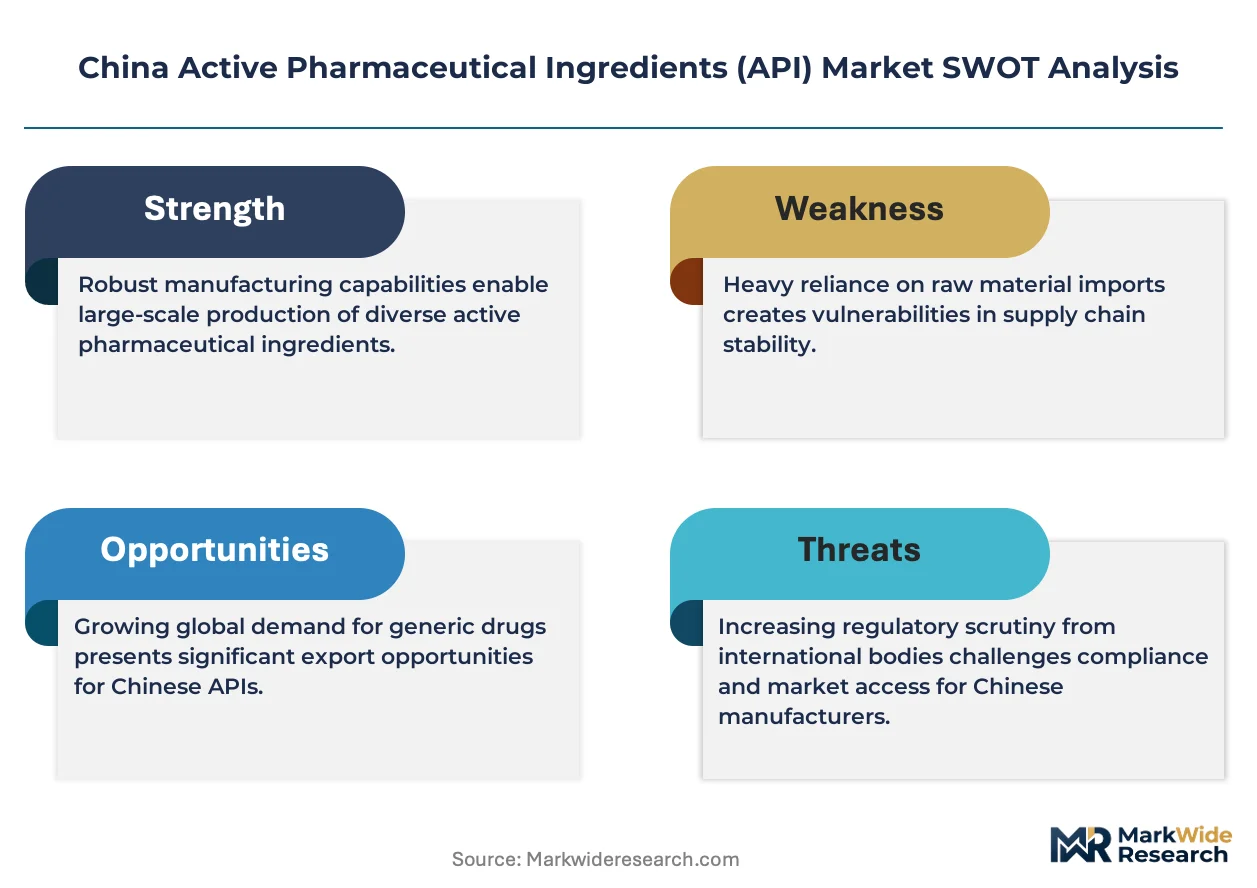
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper process expertise. The China API sector exhibits tiered consolidation where integrated CDMO platforms anchor high-value biotech contracts while mid-scale fermentation houses challenge legacy state-owned producers on generic chemical synthesis. Three archetypes dominate: integrated platform providers spanning cell-line development through commercial supply, specialized chemical synthesis operators with FDA-inspected export capabilities, and state-backed bulk antibiotic manufacturers with captive raw-material control. Competitive moves concentrate on continuous-flow chemistry investments and strategic partnerships with Contract Research Organizations.
Within the integrated platform tier, WuXi AppTec anchors high-value biotech API contracts through its CDMO capabilities. Zhejiang Huahai Pharmaceutical occupies a position exemplifying specialized chemical synthesis operators with sustained FDA-inspected export volumes. CSPC Pharmaceutical Group represents the state-backed bulk manufacturing archetype with cephalosporin and antibiotic focus. These three entities collectively illustrate the competitive stratification between platform breadth, regulatory certification depth, and captive supply integration that defines current market positioning.
| Leading Market Players |
|---|
| STA Pharmaceutical Co., Ltd. |
| WuXi AppTec |
| Apeloa Pharmaceutical Co., Ltd. |
| Guobang Pharmaceutical Group |
| ShanDong Xinhua Pharmaceutical |
| CSPC Pharmaceutical Group |
| North China Pharmaceutical Group |
| Zhejiang Huahai Pharmaceutical |
| Zhejiang Medicine Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Zhejiang province's coastal chemical parks concentrate fermentation and synthesis capacity, anchoring margin pools downstream with pharmaceutical manufacturers and CDMOs who command volume-based price premiums. Solvent feedstock volatility and NMPA compliance costs compress margins for batch-process operators while continuous-flow chemistry investments elevate pricing power for technology-advanced facilities.
Pricing Analysis
The customization-premium spread separates FDA-inspected export-grade API from domestic-standard chemical synthesis, with certification tier and volume scale as primary price differentiation drivers. Contract Research Organizations with multi-year offtake agreements secure preferential pricing through dedicated capacity allocations. Pricing pressure intensifies in antibiotic bulk manufacturing due to cyclical demand and feedstock cost swings. State-owned pharmaceutical manufacturers exhibit highest price sensitivity, while biotech originators prioritize quality assurance over unit cost.
Supply Chain Analysis
Supplier-financing facilities from state-backed industrial bond programs extend payment terms for mid-scale fermentation houses challenging legacy producers. Raw material dependencies center on petrochemical-derived solvents, specialty fermentation media, and catalytic reagents sourced from domestic refiners. Single-region concentration risk in Zhejiang coastal zones exposes output continuity to localized environmental enforcement actions. Distribution runs through Shanghai and Tianjin port infrastructure for export-oriented chemical synthesis, with Chengdu and Wuhan hubs serving inland provincial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated CDMO platforms consolidating vendor panels for biotech pipeline candidates, fragmenting pricing leverage for standalone API houses.
For Market Incumbents: Build regulatory certification moats through simultaneous FDA and NMPA inspection readiness to defend against emerging mid-scale fermentation competitors. Deepen backward integration into captive solvent recovery systems to offset feedstock volatility. Anchor high-value biotech contracts through single-use bioreactor capacity additions in Jiangsu province. For New Entrants and Emerging Players: Build out greenfield continuous-flow chemistry infrastructure in underpenetrated Jiangsu northern chemical parks to capture price premiums from technology differentiation. Target cardiovascular and antiviral API segments where FDA-inspected capacity scarcity sustains margin pools. Pursue strategic partnerships with Suzhou-based Contract Research Organizations for early-phase process validation contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed CDMO platforms holding Phase III biotech pipeline capacity commitments. Long-term viability over the next decade hinges on regulatory data harmonization capabilities and continuous manufacturing adoption rates. Monitor NMPA pharmacovigilance mandate implementation as inflection signal for quality-integrated API houses with service revenue potential.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Flow chemistry retrofits reduce solvent consumption and thermal hazard exposure for Zhejiang-based synthesis operators. |
| Regulatory Certification Investment | Dual FDA-NMPA inspection readiness sustains export market access for Taizhou and Shaoxing chemical park facilities. |
| CDMO Platform Integration | Cell-line development through commercial supply capabilities anchor multi-year contracts with Shanghai biotech originators. |
| Greenfield Capacity Expansion | Jiangsu northern chemical parks offer lower land costs than saturated Zhejiang zones for fermentation infrastructure. |
| Pharmacovigilance Service Development | NMPA post-market surveillance requirements create recurring revenue streams for API houses with integrated quality systems. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of NMPA filings, FDA inspection databases, chemical park development records, and customs trade data. Interviews with regulatory affairs directors, fermentation plant managers, CDMO procurement leads, and pharmaceutical formulation executives informed demand-side validation. Bottom-up capacity assessments across Zhejiang, Jiangsu, Hebei, and Shandong production zones triangulated against top-down market sizing.
Forecast inputs include modeled segmentation across chemical synthesis versus biotech expression modalities, captive versus merchant supply structures, and domestic versus export regulatory pathways. Treatment area demand trajectories, patient population demographics, and pipeline advancement rates informed volume projections. CAGRs derive from regression analysis of historical capacity utilization, pricing trend patterns, and regulatory compliance cost evolution.
Practitioners should monitor NMPA enforcement intensity, dual carbon mandate implementation pace, and biotech pipeline failure rates for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Pemetrexed Market
Pharmaceutical Ingredients
Pharmaceutical Suspension Market
Pharmaceutical Ingredients
Global Cephalosporin Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Grade Sodium Carbonate Market
Pharmaceutical Ingredients
Montelukast API Market
Pharmaceutical Ingredients
Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Anti-Allergic Agent Ingredients Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Global Tizanidine Market
Pharmaceutical Ingredients
Tranexamic Acid API Market
Pharmaceutical Ingredients
Pharmaceutical Lactose Market