
 Epcam Antagonists Market | 2026-2036
Epcam Antagonists Market Size, Share, and Industry Trends Forecast 2026-2036
Epcam Antagonists Market Foresight
Bispecific antibody engineering is rewriting the development paradigm for EpCAM-targeted therapeutics, enabling simultaneous tumor cell engagement and immune effector recruitment. Merck KGaA leverages its integrated bioprocessing infrastructure to anchor large-scale manufacturing of complex antibody formats. Roche sustains competitive pressure through deep clinical trial networks spanning multiple solid tumor indications. Sanofi differentiates via platform investments in T-cell engager architectures that expand addressable patient populations beyond conventional monoclonal constructs.
EpCAM antagonists comprise biologic and small-molecule modalities engineered to bind epithelial cell adhesion molecule, a transmembrane glycoprotein overexpressed in carcinomas of the lung, colorectum, and breast, thereby blocking tumor proliferation signaling or directing immune-mediated cytotoxicity. Monoclonal antibodies occupy the dominant revenue position due to established manufacturing know-how and favorable pharmacokinetic profiles in oncology settings. The immunotherapy segment within therapy areas commands accelerating pipeline investment as checkpoint combination strategies demonstrate improved objective response rates in early-stage trials.
FDA accelerated approval designations and EMA conditional marketing authorizations shape competitive timelines by rewarding surrogate endpoint data in refractory cancer populations. The EU MDR and FDA's updated guidance on bispecific T-cell engagers impose escalating purity and potency standards that filter development-stage candidates. Stakeholders must monitor evolving CMC requirements from FDA and EMA as these agencies tighten specifications for multi-specific antibody aggregates and host cell protein clearance.
Market Dynamics
Bispecific antibody engineering is collapsing traditional development timelines for EpCAM-directed therapeutics, compressing preclinical-to-clinic transitions while FDA and EMA accelerate review pathways for novel formats.
Growth Catalysts
- Accelerated approval frameworks:FDA's breakthrough therapy designation and EMA's priority medicines scheme compress regulatory timelines for EpCAM-targeted biologics in refractory solid tumors.
- Checkpoint combination strategies:Immunotherapy segments demonstrate improved objective response rates when EpCAM antagonists pair with PD-1/PD-L1 inhibitors in early-stage oncology trials.
- China's trial infrastructure:Hospital-based infusion centers in Shanghai and Beijing host expanding Phase II and Phase III footprints for epithelial cell adhesion molecule inhibitors.
Market Restraints
- Host cell protein clearance costs:Multi-specific antibody aggregates require escalating downstream purification expenditure that burdens development-stage balance sheets.
- CDMO concentration in Switzerland and Germany:Contract manufacturing for complex antibody formats depends on limited GMP bioprocessing capacity in Alpine and Rhine corridor clusters.
- Epitope masking in stromal microenvironments:Tumor-associated fibroblast density limits antigen accessibility in desmoplastic carcinoma subtypes.
Strategic Opportunities
- Perioperative adjuvant settings:Colorectal and non-small cell lung cancer resection protocols represent underpenetrated indications beyond metastatic disease.
- Japan's regenerative medicine framework:PMDA's conditional approval pathways for tissue-engineered products create regulatory tailwinds for EpCAM-directed cell therapies.
- Site-of-care infusion networks:Community oncology clinics are displacing hospital-based administration for stable biologic regimens in the United States.
Industry Challenges
- Bispecific CMC talent scarcity:Analytical development for T-cell engager architectures requires rare expertise in multi-specific aggregate characterization and potency assay design.
- Legacy monoclonal manufacturing retooling:Stainless steel bioreactor infrastructure at established antibody facilities demands capital-intensive adaptation for flexible, small-batch complex format production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epcam Antagonists Market |
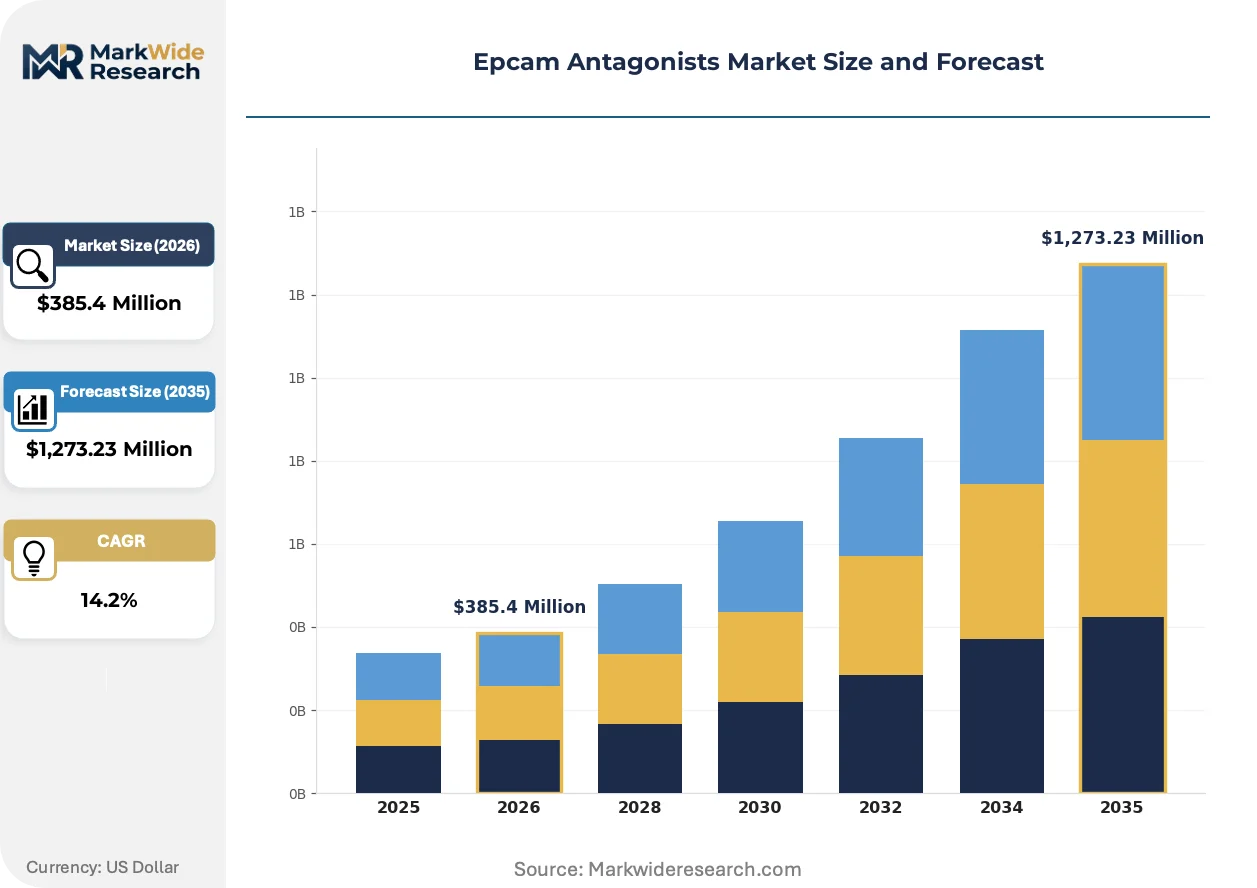
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,273.23 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Peptide Drugs, Small Molecules, Biosimilars Therapy Area: Oncology, Immunotherapy, Autoimmune Disorders, Infectious Diseases Delivery Mode: Injectable, Oral, Intravenous, Topical End User: Hospitals, Research Institutions, Clinics, Homecare |
| Companies Covered | Merck KGaA, Roche, Sanofi, GSK, AbCellera Biologics, Sino Biological, Sesen Bio, Zymeworks, Mersana Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epcam Antagonists Market Shifts & Advancements
Antibody engineering modalities are actively compressing the competitive set for EpCAM-targeted therapeutics, with platform investments determining which developers capture priority positioning in solid tumor pipelines.
Dual-targeting T-cell engagers are collapsing the historical separation between tumor antigen binding and immune effector recruitment into single molecular constructs. Academic medical centers in the United States and Germany are adopting these formats for investigator-initiated trials at accelerating velocity. The structural consequence is collapsing development timelines that previously required sequential monoclonal optimization.
EMA's updated guidance on bispecific T-cell engagers is imposing escalating purity specifications that filter mid-tier development candidates from European market entry. Manufacturers must demonstrate sub-ppm aggregate levels and defined glycosylation patterns to secure conditional marketing authorization. Oncology-focused biotechs with integrated CMC capabilities are capturing competitive advantage by pre-empting these standards in Phase I manufacturing.
Site-of-care economics are driving purchasing consolidation among United States hospital systems negotiating bundled payment contracts for infusion therapeutics. Integrated delivery networks in Texas and Florida are displacing independent oncology practices through captive specialty pharmacy arrangements. This concentration is most visible in Medicare Advantage populations where risk-bearing entities prioritize formulary control over physician preference.
Epcam Antagonists Market Segmentation
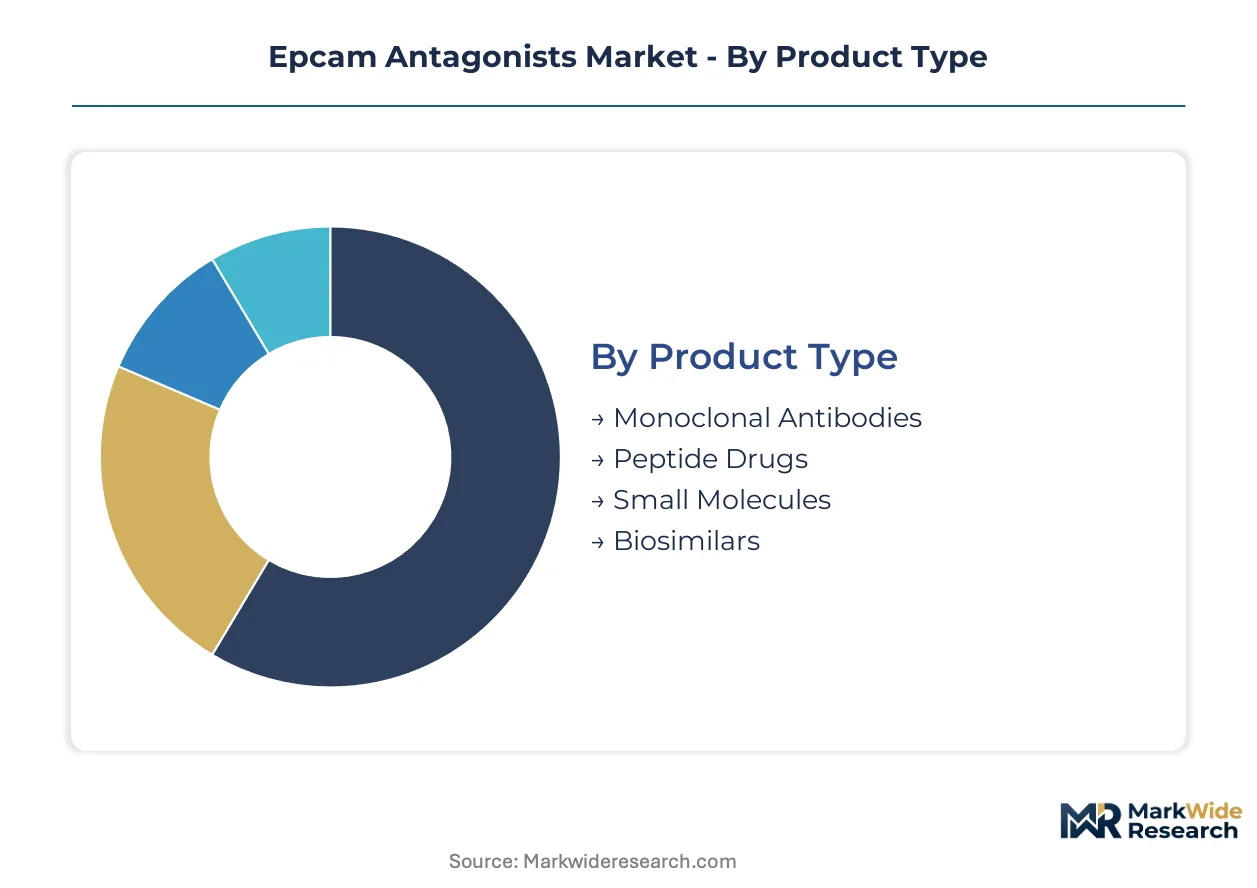
EpCAM antagonist development fractures across multiple technical and commercial dimensions, with modality format and therapeutic application determining manufacturing complexity, regulatory pathway, and reimbursement trajectory. Understanding these segment boundaries clarifies where capital deployment concentrates and which patient populations remain addressable.
Product Type:
Cost tier stratification across molecular formats governs development risk, manufacturing scale-up economics, and competitive moat durability for EpCAM-directed therapeutics.
- Monoclonal Antibodies:Full-length IgG constructs with established Fc-effector functions dominate current clinical pipelines due to mature CMC platforms and predictable pharmacokinetics. Hospital-based infusion centers in the United States and Germany concentrate demand for these formats as they integrate into standard-of-care protocols for refractory carcinomas.
- Peptide Drugs:Synthetic amino acid sequences engineered for high-affinity EpCAM binding offer reduced immunogenicity risk and simplified regulatory pathways compared to biologics. Manufacturing gravitates toward contract synthesis providers in Switzerland and China as developers seek to bypass the capital intensity of mammalian cell culture infrastructure.
- Small Molecules:Oral bioavailability and blood-brain barrier penetration expand addressable indications beyond solid tumors.
- Biosimilars:Follow-on biologics reference established monoclonal antibodies with expiring composition-of-matter patents.
Monoclonal antibodies command the established base. The steepest expansion runs through peptide drugs.
Therapy Area:
Application focus determines trial design complexity, endpoint selection, and the regulatory precedents that shape competitive entry barriers.
- Oncology:Solid tumor indications leverage EpCAM overexpression in carcinomas of the lung, colorectum, and breast to drive tumor-directed cytotoxicity. FDA breakthrough therapy designations for refractory populations accelerate review timelines for candidates demonstrating durable responses in Phase II settings.
- Immunotherapy:Checkpoint combination strategies pair EpCAM antagonists with PD-1/PD-L1 inhibitors to amplify objective response rates in desmoplastic tumor microenvironments. Academic medical centers in the United States and Germany are adopting these formats for investigator-initiated trials at accelerating velocity.
- Autoimmune Disorders:EpCAM modulation targets epithelial barrier dysfunction in inflammatory conditions.
- Infectious Diseases:Antigen presentation enhancement applications remain exploratory.
Oncology retains the revenue concentration. Immunotherapy is climbing the fastest.
Delivery Mode:
Administration route shapes site-of-care economics, patient compliance profiles, and the competitive dynamics between hospital and outpatient settings.
- Injectable:Subcutaneous formulations enable community oncology clinic administration, displacing hospital-based infusion for stable biologic regimens in United States Medicare Advantage populations. Integrated delivery networks in Texas and Florida negotiate bundled payment contracts that prioritize formulary control over physician preference.
- Intravenous:Large-molecule biologics require infusion center infrastructure with cold-chain logistics and nursing supervision.
- Oral:Small-molecule candidates target patient convenience and reduced healthcare utilization costs.
- Topical:Localized delivery for superficial epithelial lesions remains preclinical.
Intravenous administration anchors current revenue. Injectable formats are gaining share fastest.
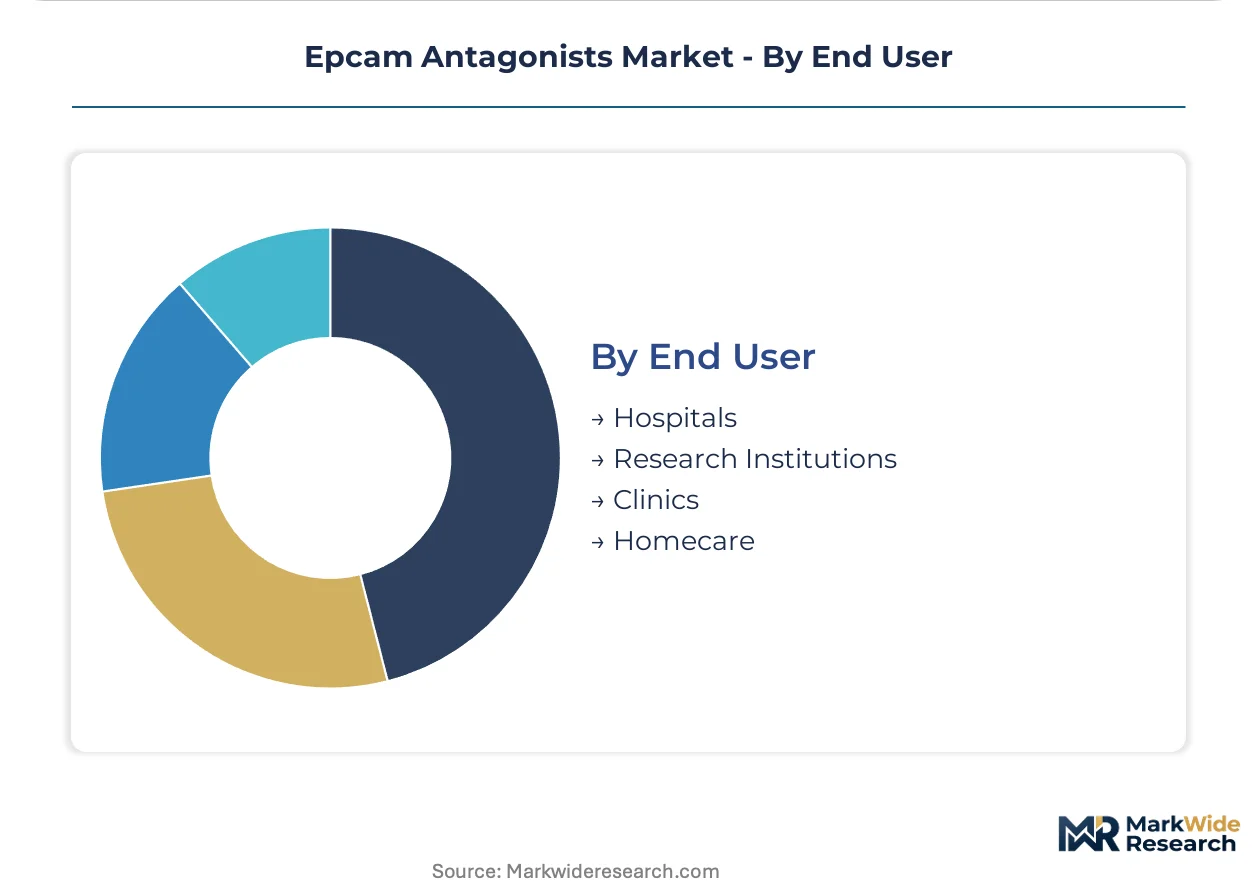
End User:
Customer type concentration reflects reimbursement structure, purchasing consolidation, and the shift from inpatient to ambulatory care settings.
- Hospitals:Academic medical centers anchor Phase II and Phase III trial footprints for epithelial cell adhesion molecule inhibitors, with Shanghai and Beijing hospital systems expanding patient recruitment capacity. EMA conditional marketing authorizations reward surrogate endpoint data generated in these settings for refractory cancer populations.
- Clinics:Community oncology practices are consolidating into integrated delivery networks that displace independent physician groups through captive specialty pharmacy arrangements.
- Research Institutions:Investigator-initiated trials at United States and German academic centers drive early-stage pipeline expansion.
- Homecare:Subcutaneous self-administration models remain underdeveloped for EpCAM-directed therapies.
Hospitals command the established base. Clinics represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital-based infusion centers in the United States, Germany, and China concentrate procurement authority for EpCAM-directed therapeutics, with academic medical centers anchoring Phase II and Phase III trial recruitment across these markets.
United States
FDA breakthrough therapy designations compress review timelines for refractory solid tumor candidates, accelerating commercial entry for developers demonstrating durable responses. The IRA's Medicare price negotiation provisions reshape reimbursement forecasting for biologics nearing approval. Integrated delivery networks in Texas and Florida consolidate purchasing through captive specialty pharmacy arrangements that displace independent oncology practices.
Germany
EMA conditional marketing authorizations reward surrogate endpoint data generated at academic medical centers in Heidelberg and Munich. The EU MDR imposes escalating purity standards for multi-specific antibody aggregates that filter mid-tier candidates from European market entry. Rhine corridor CDMO clusters anchor contract manufacturing capacity for complex T-cell engager formats.
China
NMPA accelerated approval pathways for innovative biologics compress development timelines for domestic developers. Hospital-based infusion centers in Shanghai and Beijing expand patient recruitment capacity for epithelial cell adhesion molecule inhibitor trials. Yangtze River Delta biotech clusters concentrate CMC talent for bispecific antibody characterization and potency assay design.
Switzerland
Swissmedic's alignment with EMA standards streamlines parallel submission strategies for developers targeting European market entry. Alpine CDMO infrastructure supports GMP bioprocessing for complex antibody formats with limited global capacity. Basel-Zurich corridor clusters host specialized analytical development expertise for multi-specific aggregate clearance.
Japan
PMDA's conditional approval pathways for regenerative medicine products create regulatory tailwinds for EpCAM-directed cell therapy modalities. METI funding programs for advanced biomanufacturing support domestic capacity expansion for flexible, small-batch production. Kanto region academic medical centers adopt T-cell engager formats for investigator-initiated trials at accelerating velocity.
Epcam Antagonists Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the EpCAM antagonists landscape, with consolidated purchasing power among integrated delivery networks favoring developers with established hospital formulary relationships. The vendor base stratifies across three tiers: integrated pharmaceutical conglomerates with bioprocessing infrastructure, platform-focused biotechs with novel antibody engineering capabilities, and specialized CDMOs supplying manufacturing capacity. Dominant competitive moves include strategic partnerships for CMC capability access and geographic expansion into China's trial infrastructure.
Within the integrated pharmaceutical tier, Merck KGaA, Roche, and Sanofi occupy positions as anchor developers with established clinical trial networks spanning multiple solid tumor indications. Merck KGaA exemplifies the infrastructure-heavy archetype through its integrated bioprocessing capabilities. Roche represents the deep clinical footprint model across refractory carcinoma settings. Sanofi sits within the platform-investment category for T-cell engager architectures that expand beyond conventional monoclonal constructs.
| Leading Market Players |
|---|
| Merck KGaA |
| Roche |
| Sanofi |
| GSK |
| AbCellera Biologics |
| Sino Biological |
| Sesen Bio |
| Zymeworks |
| Mersana Therapeutics |
| Others |
Supply & Pricing Matrix
Rhine corridor freight corridors connecting Basel to Frankfurt carry cold-chain biologics at elevated cost structures that concentrate supply-side leverage among Swiss and German CDMO clusters while forcing three-tier pricing stratification across premium GMP-certified, standard clinical-grade, and economy research-use formats.
Pricing Analysis
Cost-plus contracts indexed to CHF/EUR exchange rates dominate bioprocessing service agreements between developers and Alpine manufacturing partners. Price differentiation hinges on FDA tier certification and batch scale, with multi-specific antibody formats commanding premium positioning over legacy monoclonals. Pricing pressure stems from escalating downstream purification expenditure for aggregate clearance. Hospital systems demonstrate lowest price sensitivity due to bundled reimbursement, while academic research institutions exhibit highest elasticity.
Supply Chain Analysis
Upstream cell culture media and proprietary transfection reagents draw from Switzerland, Germany, and United States manufacturing bases. Chinese suppliers dominate synthetic peptide precursors and contract synthesis capacity. Single-source vulnerability concentrates in GMP bioreactor engineering talent pools. Distribution runs through hospital-based infusion centers and consolidating integrated delivery networks in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EpCAM antagonists market functions as a service-attach opportunity where companion diagnostic development and patient monitoring protocols expand faster than core therapeutic revenue streams.
For Market Incumbents: Insulate manufacturing margins by securing captive bioreactor capacity in Rhine corridor clusters before CDMO bottlenecks intensify. Deepen analytical development capabilities for multi-specific aggregate characterization to preempt EMA purity standard escalations. The priority defensive lever rests on backward integration into cell line development rather than reliance on external licensor platforms.
For New Entrants and Emerging Players: Establish a beachhead in peptide drug modalities where synthetic manufacturing bypasses mammalian cell culture capital intensity. Japan's PMDA conditional approval pathways for regenerative medicine products represent the most penetrable regulatory entry point. The go-to-market angle centers on investigator-initiated trial partnerships at Heidelberg and Munich academic centers.
For Investors and Strategic Acquirers: Platform-focused biotechs with integrated CMC capabilities and Phase I manufacturing readiness represent the priority acquisition archetype. Long-term viability over the coming decade hinges on bispecific antibody engineering talent retention and regulatory pre-positioning. The inflection signal to monitor is FDA breakthrough therapy designation velocity for T-cell engager formats in solid tumor indications.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II expansion in Shanghai and Beijing hospital systems accelerates patient recruitment timelines. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses review timelines for refractory carcinoma candidates. |
| Manufacturing Scale-Up | Flexible bioreactor adaptation enables small-batch production of complex T-cell engager formats. |
| Pipeline Diversification | Perioperative adjuvant settings in colorectal resection protocols expand addressable indications. |
| Strategic Partnership | CDMO alliances in Swissmedic-aligned jurisdictions streamline parallel EMA submission strategies. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions that shaped this analysis. Primary interview intelligence combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up patient population modeling and top-down revenue triangulation anchored the quantitative framework.
Demand-supply balance dynamics across antibody format manufacturing capacity and clinical trial enrollment velocity informed the analytical framework over the projection horizon. Segmentation dimensions included molecular format, therapy area, administration route, and regional regulatory cluster. CAGRs derived from compound growth trajectory analysis incorporating pipeline advancement rates and conditional approval probability weights.
Stress conditions across host cell protein clearance cost escalation, CDMO capacity constraints, and epitope masking in desmoplastic microenvironments were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway acceleration and reimbursement structure evolution. Cross-checking against external clinical pipeline benchmarks and hospital procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Global Penicillin Drug Market
Pharmaceutical Ingredients
Antipyretic Analgesic Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Sulphonamides Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Global Fibrate Drugs Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Pharmaceutical Grade Hyaluronic Acid Market
Pharmaceutical Ingredients
Oral Transmucosal Drugs Market