
 Global Tizanidine Market | 2026-2036
Global Tizanidine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tizanidine Market Foresight
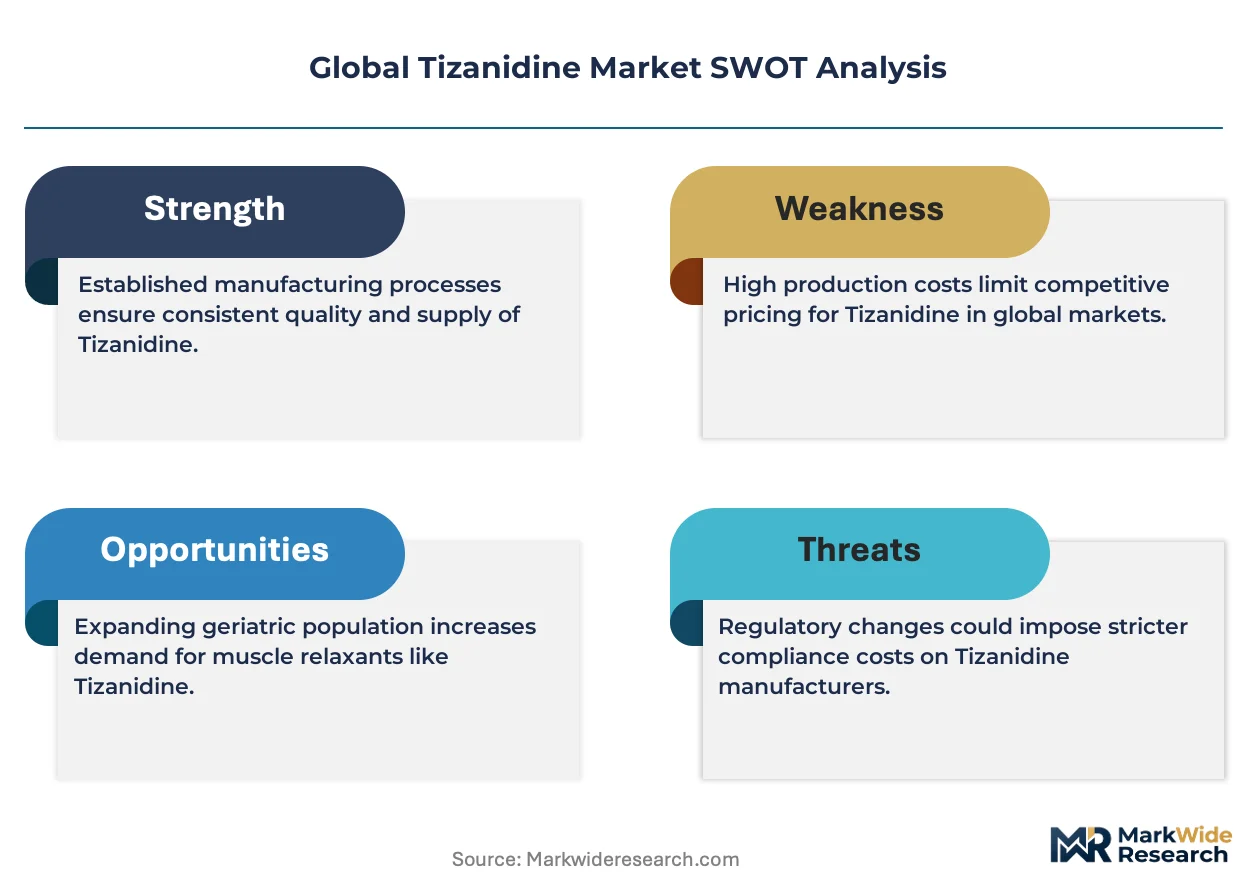
REACH compliance for active pharmaceutical ingredients is repositioning European supply chains toward audited Indian and Chinese manufacturers. Teva leverages backward integration into tizanidine hydrochloride API production to protect margin structure against generic erosion. Sun Pharmaceutical anchors its position through dedicated neurology formulation facilities serving North American hospital networks. Acorda Therapeutics differentiates via specialty distribution partnerships that secure shelf space in rehabilitation center pharmacies.
Tizanidine is a centrally acting alpha-2 adrenergic agonist with a molecular weight of 253.7 g/mol, formulated as the hydrochloride salt for oral administration with peak plasma concentration occurring one to two hours post-dose. It functions primarily as an antispasmodic agent for managing increased muscle tone associated with spasticity. Tablet formulations dominate current volume due to established reimbursement codes and physician familiarity with dose titration protocols. Extended release delivery systems represent the fastest-expanding product category as they reduce Cmax-related sedation and support twice-daily compliance profiles. Therapy area demand clusters around multiple sclerosis, where spasticity affects the majority of patients and oral tizanidine competes directly with baclofen and diazepam.
The FDA's bioequivalence standards for generic tizanidine tablets shape competitive entry timelines and ANDA approval thresholds. EMA's Good Manufacturing Practice inspections of API facilities in India and China determine which suppliers can serve European formulation sites. WHO prequalification programs for essential medicines influence procurement decisions in low-income markets. Stakeholders must monitor how FDA guidance on alcohol-induced dose dumping for extended-release formulations alters development priorities for next-generation delivery platforms.
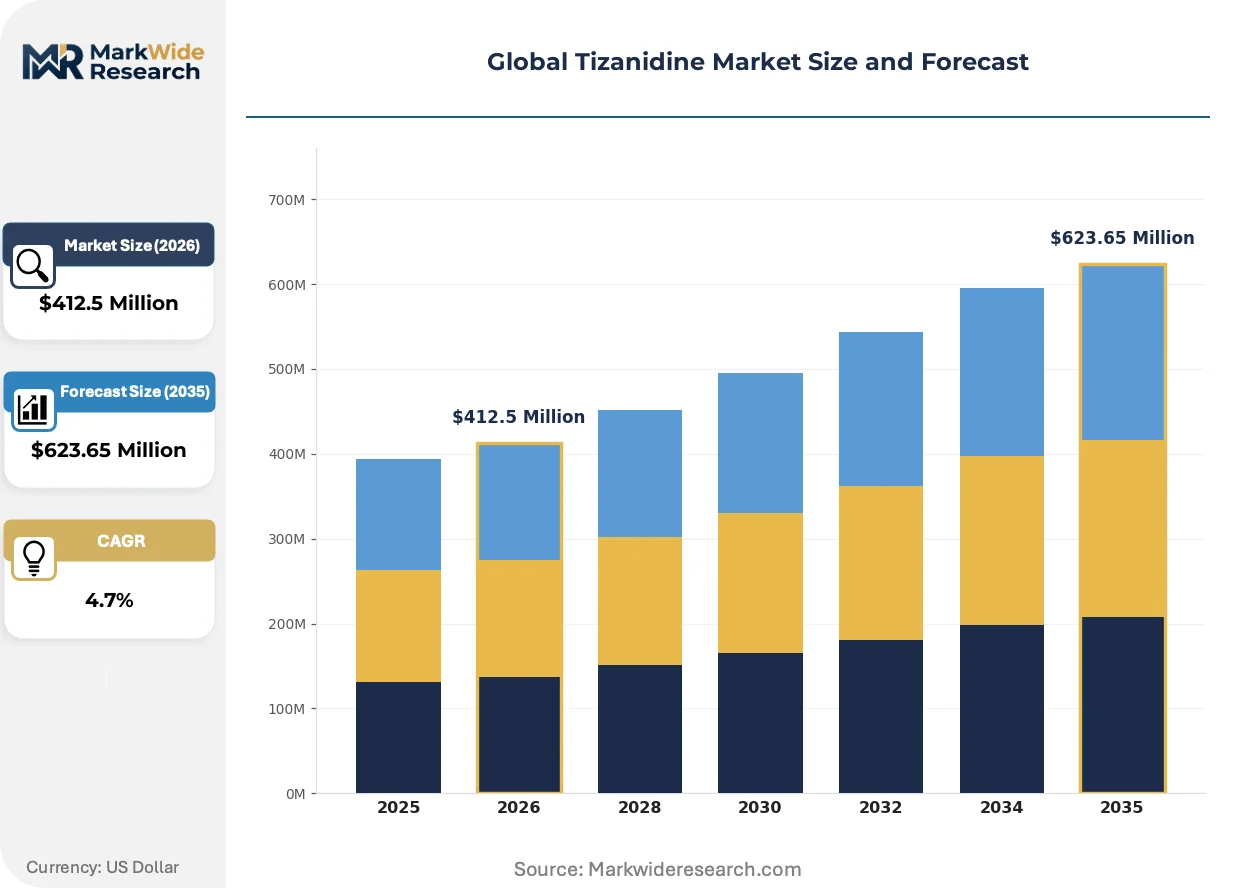
Market Dynamics
Generic erosion through FDA ANDA approvals is compressing pricing power while expanding patient access, forcing incumbents to defend margin structure through backward integration into active pharmaceutical ingredient production and specialty distribution partnerships.
Growth Catalysts
- Extended-release formulation uptake:Neurologists increasingly prescribe twice-daily tizanidine ER to reduce Cmax-related sedation and improve compliance in multiple sclerosis spasticity management.
- FDA abbreviated new drug application pathway:Streamlined bioequivalence standards accelerate generic entry timelines, expanding patient access to oral central alpha-2 agonists.
- REACH compliance repositioning:European supply chains are migrating toward audited Indian and Chinese API manufacturers to meet ECHA registration requirements.
Market Restraints
- API supply concentration:A limited base of audited hydrochloride salt producers in India and China creates vulnerability to EMA inspection outcomes and shipping disruptions.
- Baclofen pump substitution:Intrathecal delivery systems for severe spasticity capture refractory cases that oral tizanidine cannot address, capping addressable patient pools.
- Alcohol-induced dose dumping risk:FDA guidance on extended-release formulations with alcohol-susceptible polymers raises development costs and delays next-generation platform launches.
Strategic Opportunities
- Rehabilitation center pharmacy channels:Specialty distribution partnerships securing shelf space in post-acute care facilities bypass hospital formulary gatekeepers.
- WHO prequalification procurement:Essential medicines programs in low-income markets create volume opportunities for cost-optimized tablet formulations.
- Neurology-dedicated manufacturing:Purpose-built formulation facilities serving North American hospital networks command premium positioning through supply security guarantees.
Industry Challenges
- EMA GMP inspection backlog:Extended audit timelines for Indian and Chinese API sites delay European market entry and strain working capital.
- Legacy pump-to-pill switching protocols:Neurologist retraining requirements and reimbursement code complexity slow migration from implanted baclofen systems to oral therapy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tizanidine Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $623.65 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Extended Release, Oral Suspension Therapy Area: Muscle Spasticity, Multiple Sclerosis, Spinal Cord Injury, Stroke Recovery End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Neurology Clinics Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesalers |
| Companies Covered | Teva, Sandoz, Actavis, Acorda Therapeutics, Sun Pharmaceutical, Dr. Reddy's Laboratories, Apotex, Unichem Laboratories, Mylan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tizanidine Market Shifts & Advancements
Formulation science and regulatory science are converging to reshape competitive positioning, with delivery platform innovation and compliance architecture becoming primary differentiation vectors rather than molecular modification.
Extended-release matrix systems employing hydroxypropyl methylcellulose and polymethacrylate coatings are electrifying the tizanidine landscape by smoothing plasma concentration curves. Hospital networks and outpatient neurology practices in the United States are adopting these platforms at accelerating velocity to reduce nursing callbacks for sedation-related adverse events. The technology is electrifying margin structures by supporting premium pricing against immediate-release commoditized tablets.
EMA's intensified GMP inspection regime for Indian and Chinese API facilities is redrawing supplier qualification maps. European formulation sites now demand dual-sourced active pharmaceutical ingredients with complete REACH dossier documentation. Contract manufacturers in Germany and Italy are responding by consolidating procurement around audited suppliers with established EMA inspection histories.
Rehabilitation centers are unbundling pharmacy services from bundled post-acute care payments, creating direct procurement relationships with specialty distributors. This channel shift bypasses hospital group purchasing organizations and enables manufacturer-led patient adherence programs. The United States exhibits the most pronounced migration, where Medicare reimbursement changes favor site-of-care dispensing for oral spasticity medications.
Global Tizanidine Market Segmentation
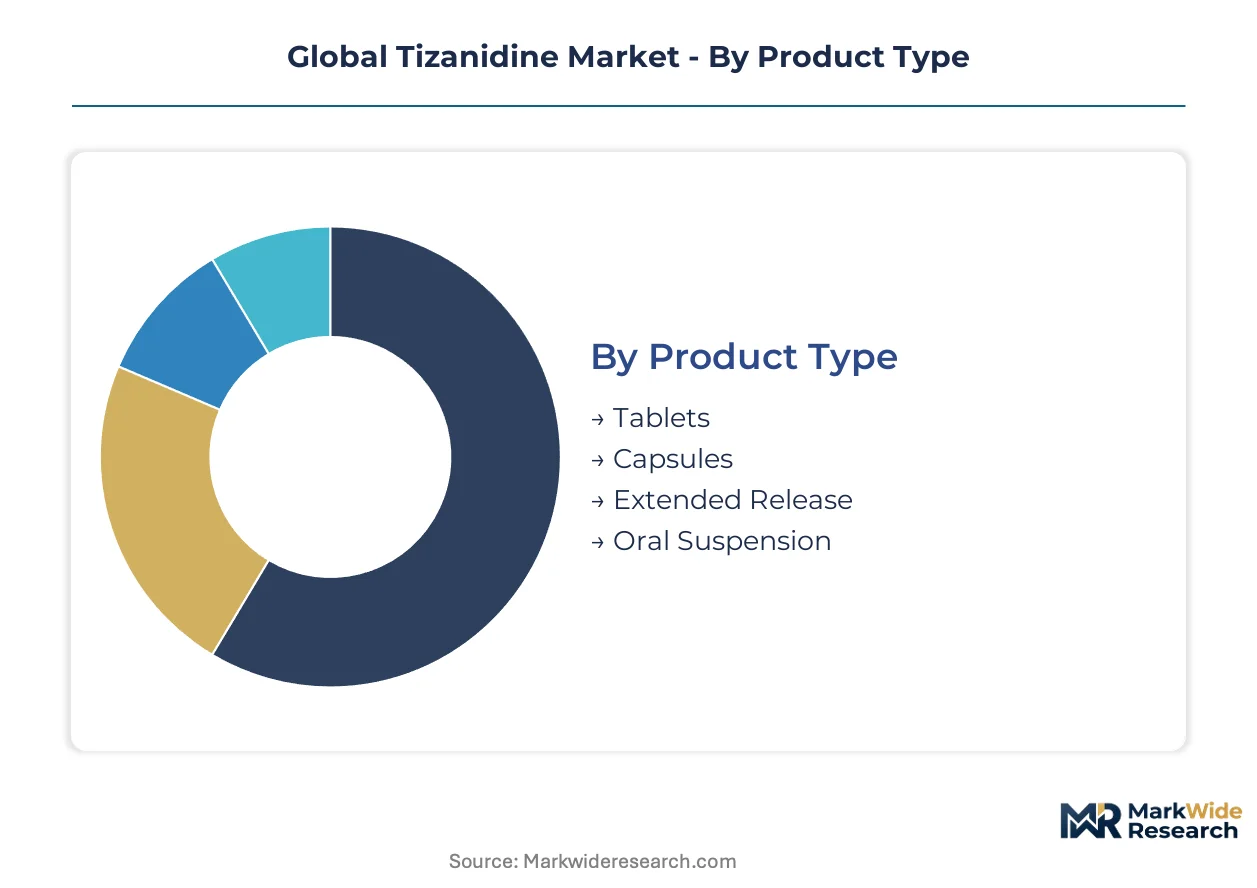
Formulation technology and delivery platform characteristics determine reimbursement codes, prescribing patterns, and competitive defensibility in tizanidine markets. Therapy area concentration and distribution channel structure further segment commercial opportunity across acute care, chronic disease management, and post-acute rehabilitation settings.
Product Type:
Release kinetics and dosage form architecture govern plasma concentration profiles, sedation liability, and compliance economics across the tizanidine portfolio.
- Tablets:Immediate-release hydrochloride salt formulations deliver peak plasma concentration within one to two hours post-dose. Hospital networks in the United States anchor volume through established reimbursement codes and physician familiarity with dose titration protocols for spasticity management.
- Extended Release:Matrix systems employing hydroxypropyl methylcellulose and polymethacrylate coatings smooth Cmax curves to reduce nursing callbacks for sedation-related adverse events. Neurology practices are adopting these platforms fastest to support twice-daily compliance in multiple sclerosis patients.
- Capsules:Gelatin-shell delivery enables taste masking and moisture protection for hydroscopic API, serving patients with dysphagia or tablet aversion in outpatient settings.
- Oral Suspension:Liquid formulation supports dose flexibility for pediatric populations and patients with feeding tubes, concentrated in rehabilitation center protocols.
Tablets lead on scale; Extended Release leads on momentum.
Therapy Area:
Pathophysiology severity and treatment algorithm positioning determine addressable patient pools and competitive substitution dynamics.
- Multiple Sclerosis:Spasticity affects the majority of MS patients, creating sustained demand for oral central alpha-2 agonists. FDA bioequivalence standards for generic tablets accelerate access expansion while compressing pricing power in this high-volume indication.
- Spinal Cord Injury:Traumatic and non-traumatic lesions generate refractory spasticity requiring long-term pharmacologic management. Intrathecal baclofen pumps capture severe cases, capping oral tizanidine penetration in the most disabled patient strata.
- Muscle Spasticity:Generalized spasticity from cerebral palsy and other upper motor neuron syndromes drives prescription volume through pediatric and adult neurology clinics.
- Stroke Recovery:Post-stroke spasticity management favors oral agents during acute rehabilitation phases, with demand clustering in the first six months post-cerebrovascular event.
Multiple Sclerosis concentrates the largest patient volume; Stroke Recovery is climbing fastest as acute rehabilitation protocols standardize oral spasticity pharmacotherapy.
End User:
Site-of-care economics and formulary gatekeeper structures fragment procurement authority across the care continuum.
- Hospitals:Inpatient neurology services and acute rehabilitation units drive initial prescription generation through standardized order sets for spasticity management.
- Rehabilitation Centers:Post-acute facilities are unbundling pharmacy services from bundled payments, creating direct procurement relationships with specialty distributors.
- Outpatient Clinics:Community-based practices manage chronic spasticity titration and refill authorization, concentrated in Medicare reimbursement zones.
- Neurology Clinics:Subspecialty practices in academic medical centers drive extended-release adoption through clinical trial exposure and protocol development.
Hospitals retain the deepest formulary influence; Rehabilitation Centers are gaining procurement autonomy fastest as Medicare reimbursement shifts favor site-of-care dispensing.
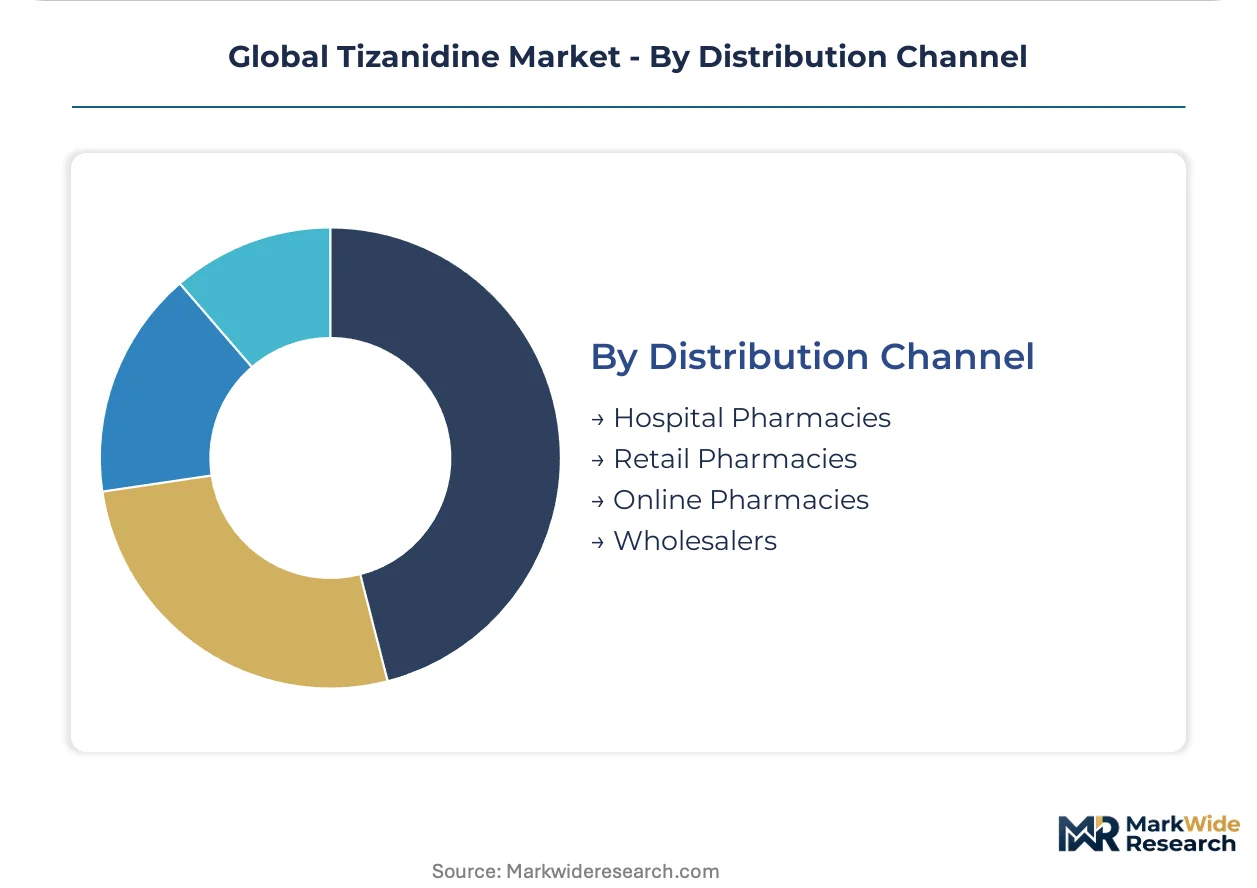
Distribution Channel:
Channel structure determines patient access speed, adherence program reach, and margin capture for manufacturers.
- Hospital Pharmacies:Captured dispensing within integrated delivery networks supports immediate initiation of therapy but limits manufacturer patient data access.
- Retail Pharmacies:CVS, Walgreens, and independent chains dominate chronic refill volume, with 90-day supply programs supporting compliance in stable spasticity patients.
- Online Pharmacies:Mail-order platforms capture Medicare Part D volume through auto-refill programs, expanding fastest in extended-release segments where stability concerns favor centralized distribution.
- Wholesalers:McKesson, AmerisourceBergen, and Cardinal Health consolidate procurement for institutional buyers, with specialty distribution arms serving rehabilitation center networks.
Retail Pharmacies command the highest prescription volume; Online Pharmacies are expanding most quickly as Medicare auto-refill penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurology-trained clinical pharmacists in the United States anchor global prescription volume for oral spasticity management. European formulation sites demand REACH-compliant active pharmaceutical ingredients from audited suppliers. Asian API manufacturers concentrate production in chemical manufacturing clusters serving both regulated and emerging markets.
United States
Medicare reimbursement changes favor site-of-care dispensing in post-acute rehabilitation settings. FDA bioequivalence standards for abbreviated new drug applications accelerate generic tizanidine entry timelines. The Southeast corridor from Florida to Georgia concentrates rehabilitation center pharmacy networks unbundling procurement from hospital systems.
Germany
EMA Good Manufacturing Practice inspections of Indian and Chinese API facilities determine qualified supplier lists for European formulation sites. REACH dossier documentation requirements reposition procurement toward audited manufacturers with established ECHA registration histories. The Rhine-Ruhr industrial belt hosts contract manufacturers consolidating dual-sourced active pharmaceutical ingredient supply chains.
India
CDSCO manufacturing facility inspections and WHO prequalification programs shape export eligibility for generic tizanidine hydrochloride. The country's national pharmaceutical regulator enforces data integrity standards for facilities supplying regulated markets. Gujarat and Maharashtra chemical manufacturing clusters concentrate hydrochloride salt production for North American and European formulation sites.
China
NMPA export certification requirements and EMA inspection outcomes determine API supplier qualification for international markets. The country's national medical products administration coordinates with overseas regulators on facility audit scheduling. Jiangsu and Zhejiang province chemical parks host tizanidine hydrochloride manufacturers seeking dual regulatory approval.
United Kingdom
NHS England commissioning frameworks for spasticity management influence oral central alpha-2 agonist prescribing patterns in multiple sclerosis pathways. The Medicines and Healthcare products Regulatory Agency enforces post-Brexit import controls on finished dosage forms. The Greater London academic medical center network drives extended-release formulation adoption through clinical protocol development.
Global Tizanidine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the tizanidine value chain. The market structure fragments between backward-integrated API producers, dedicated neurology formulation facilities, and specialty distribution platforms. Three archetypes dominate: Israeli-headquartered generic giants with captive chemical manufacturing, Indian pharmaceutical conglomerates with US-facing formulation sites, and North American specialty neurology companies with rehabilitation channel partnerships. Competitive moves concentrate on EMA inspection readiness for API sites and direct-to-pharmacy distribution agreements bypassing hospital group purchasing organizations.
Among Israeli-headquartered generic manufacturers, Teva anchors the backward-integrated archetype through in-house hydrochloride salt production. Sun Pharmaceutical exemplifies the Indian conglomerate model with dedicated neurology formulation capacity serving North American hospital networks. Acorda Therapeutics occupies the specialty distribution position through rehabilitation center pharmacy partnerships securing shelf space outside hospital formulary systems.
| Leading Market Players |
|---|
| Teva |
| Sandoz |
| Actavis |
| Acorda Therapeutics |
| Sun Pharmaceutical |
| Dr. Reddy's Laboratories |
| Apotex |
| Unichem Laboratories |
| Mylan |
| Others |
Supply & Pricing Matrix
Extended-release matrix formulation technology is compressing manufacturing cost curves while simultaneously concentrating production capacity among facilities with polymethacrylate coating expertise. This dual shift rewards backward-integrated API producers with captive hydrochloride salt supply and penalizes pure-play formulators exposed to Indian and Chinese API price volatility.
Pricing Analysis
Bundled hospital procurement through group purchasing organizations is fragmenting into unbundled direct relationships between rehabilitation centers and specialty distributors. Three-tier pricing structure across premium extended-release, standard immediate-release tablets, and economy generic capsules dominates the landscape, with price differentiation driven by FDA bioequivalence certification tier and volume scale commitments to Medicare Part D plans. Pricing pressure stems from FDA ANDA approval acceleration for generic immediate-release tablets, compressing margins fastest in the commoditized segment. Hospital networks exhibit lowest price sensitivity due to formulary lock-in, while independent retail pharmacies face highest sensitivity due to Medicare reimbursement compression.
Supply Chain Analysis
Single-source vulnerability sits with EMA-audited hydrochloride salt producers in Gujarat and Maharashtra, India, where CDSCO inspection backlogs delay European market qualification. Raw material dependencies include 4-chloroaniline precursors, hydrogen chloride gas, and hydroxypropyl methylcellulose excipients sourced from Jiangsu and Zhejiang chemical parks in China. Supply chain risk centers on REACH dossier documentation delays for European formulation sites. Distribution runs through McKesson, AmerisourceBergen, and Cardinal Health specialty arms serving rehabilitation center networks, with direct-to-pharmacy agreements bypassing hospital GPOs gaining share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on extended-release formulation premiumization and API production cost control through captive manufacturing. The shift from hospital-centric to rehabilitation-center dispensing creates pricing power for players with direct channel relationships.
For Market Incumbents: Deepen backward integration into tizanidine hydrochloride API production to insulate margin structure from generic erosion and Indian API price volatility. Secure dual-sourced active pharmaceutical ingredient supply chains with complete REACH dossier documentation for European formulation sites. Prioritize EMA inspection readiness at captive Indian facilities to preempt competitor qualification delays. For New Entrants and Emerging Players: Extended-release delivery platform innovation offers the most penetrable wedge against commoditized immediate-release tablets. Target rehabilitation center pharmacy channels unbundling from hospital systems in the United States Southeast corridor, where Medicare reimbursement changes favor site-of-care dispensing. Pursue WHO prequalification for essential medicines programs in low-income markets as a volume-building go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among Indian pharmaceutical conglomerates with US-facing neurology formulation facilities and pending EMA API site inspections. Long-term viability over the analysis window favors players with integrated API-to-formulation capabilities and rehabilitation channel control. Watch FDA guidance evolution on alcohol-induced dose dumping for extended-release formulations as the signal indicating next-generation platform development cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| EMA GMP Inspection Readiness | Qualifies Indian API sites for European formulation supply, unlocking REACH-compliant market access. |
| Extended-Release Platform Development | Captures premium pricing against immediate-release commoditization through Cmax smoothing technology. |
| Rehabilitation Center Distribution Partnerships | Bypasses hospital GPO gatekeepers to secure shelf space in post-acute dispensing settings. |
| Backward Integration into API Production | Protects margin structure against generic erosion through captive hydrochloride salt supply. |
| WHO Prequalification Procurement | Opens essential medicines volume in low-income markets through cost-optimized tablet formulations. |
Research Methodology
Coverage spans the United States, Germany, India, China, and the United Kingdom, with primary inputs from each regional cluster. The research combines structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors with secondary validation against FDA ANDA filings, EMA inspection records, ClinicalTrials.gov protocols, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulate demand estimates across the analysis window.
Granularity-level modeling disaggregates volume and value across formulation type, therapy area, end-user site of care, and distribution channel throughout the forecast period. CAGRs derive from segmented growth rate analysis incorporating therapy area prescription trends, generic entry timelines, and reimbursement policy shifts. Industry-specific inputs include FDA bioequivalence standard evolution, EMA GMP inspection scheduling patterns, and Medicare site-of-care dispensing incentive structures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance on extended-release alcohol-induced dose dumping, EMA inspection backlog resolution, and Medicare reimbursement recalibration. Forecasts reflect documented assumptions regarding generic entry velocity, API supplier qualification timelines, and rehabilitation center pharmacy unbundling penetration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Oxycodone Drugs Market
Pharmaceutical Ingredients
Global Cephalosporin Drugs Market
Pharmaceutical Ingredients
Cyprosin Market
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
Pharmaceutical Grade Hyaluronic Acid Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Glycylglycine Market
Pharmaceutical Ingredients
Diosmin API Market
Pharmaceutical Ingredients
Synthetic Small Molecule API Market
Pharmaceutical Ingredients
Pharmaceutical Propellants Market
Pharmaceutical Ingredients
Albumin (As Excipient) Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Global Fibrate Drugs Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
Heparin Sodium API Market
Pharmaceutical Ingredients
Global Tacrolimus Market