
 Aviation Engine MRO Market | 2026-2036
Aviation Engine MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Engine MRO Market Analysis
EASA Part 145 certification is redrawing competitive boundaries in aviation engine MRO. GE Aerospace leverages its OEM data analytics platforms to lock in long-term service agreements. Lufthansa Technik anchors European wide-body engine overhaul capacity through its Hamburg and Malta facilities. Rolls-Royce Holdings plc differentiates via TotalCare power-by-the-hour contracts that bundle maintenance with predictive diagnostics.
Aviation engine MRO encompasses the inspection, disassembly, repair, reassembly, and testing of turbine and piston engines to restore airworthiness and performance parameters such as exhaust gas temperature margins and compressor efficiency. Turbofan overhaul commands the largest value pool given the complexity of high-bypass architectures and life-limited rotating components. Military Aviation represents a structurally distinct segment where government depot maintenance competes with contractor logistics support programs, while Third-Party Providers are capturing share from OEM-affiliated channels as airlines seek cost arbitrage on mature engine types.
FAA airworthiness directives and EASA Part M continuing airworthiness requirements shape maintenance intervals and documentation standards across all operational jurisdictions. EPA and EU REACH regulations constrain the chemistries used in cleaning, plating, and non-destructive testing processes, forcing shops to qualify alternative surface treatments. Stakeholders must weigh the capital intensity of next-generation geared turbofan tooling against the declining volumes of legacy engine programs approaching fleet retirement.
Market Dynamics
Geared turbofan powerplants are compressing overhaul intervals and forcing MRO shops to retool for higher-bypass architectures while legacy engine programs face accelerated retirement timelines.
Growth Catalysts
- Life-Limited Parts Tracking Mandates:FAA and EASA directives on digital traceability for rotating components are expanding mandatory shop visits and documentation requirements across all operational jurisdictions.
- Southeast Asian Fleet Expansion:Low-cost carriers in Indonesia, Vietnam, and the Philippines are outsourcing engine maintenance to third-party providers rather than building captive capabilities.
- Predictive Maintenance Platforms:OEM-integrated sensor analytics are extending on-wing time and creating bundled service contract opportunities that lock in long-term revenue streams.
Market Restraints
- Titanium and Superalloy Input Volatility:Nickel-based alloy prices and forged titanium billet availability constrain repair component economics for high-pressure turbine sections.
- OEM Affiliated Network Concentration:GE Aerospace and Rolls-Royce captive service channels control proprietary technical data, limiting independent shop access to critical repair schemes.
- REACH Chemical Restrictions:EU regulations on hexavalent chromium plating and solvent-based cleaning chemistries force qualification of alternative surface treatments at substantial requalification cost.
Strategic Opportunities
- UAE Hub Capacity Buildout:Dubai's Al Maktoum Airport zone and Abu Dhabi MRO clusters are attracting European and Asian carriers seeking centralized wide-body engine overhaul capacity.
- Power-by-the-Hour Convergence:Airlines are unbundling traditional time-and-material contracts in favor of availability-guaranteed agreements that transfer operational risk to service providers.
- Military Contractor Logistics:Government depot maintenance privatization in NATO member states is opening long-term performance-based logistics contracts to commercial MRO operators.
Industry Challenges
- Specialized Technician Shortages:Certified non-destructive testing inspectors and turbine blade repair welders face generational workforce gaps as experienced personnel retire without adequate pipeline replacement.
- Multi-Platform Tooling Capital Requirements:Shops must simultaneously invest in geared turbofan fixture sets while maintaining legacy narrow-body engine capability, straining balance sheet capacity.
- EASA Part 145 Certification Timelines:New facility approvals and repair process authorizations face extended audit backlogs, delaying market entry for emerging competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Engine MRO Market |
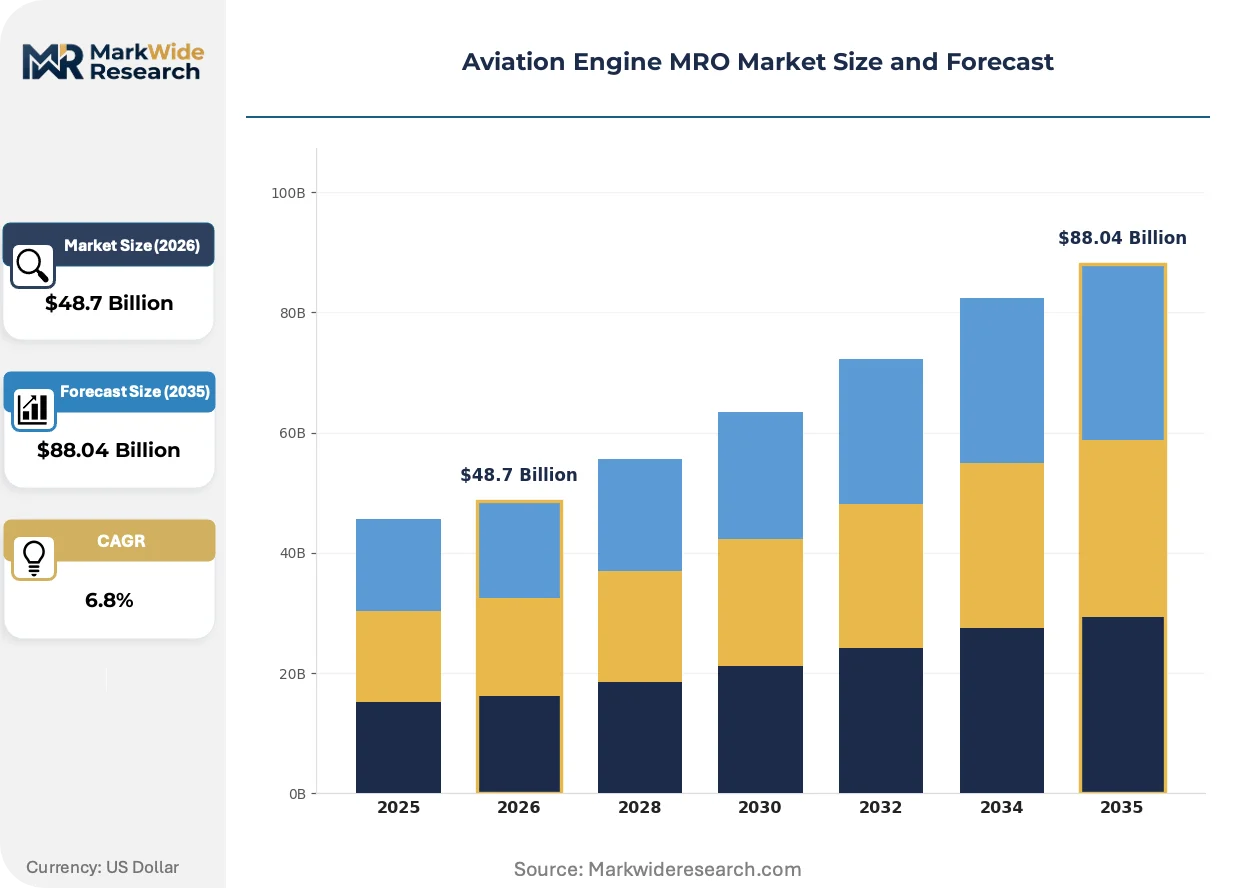
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Overhaul, Maintenance, Modification, Repair Engine Type: Turbofan, Turboprop, Piston, Auxiliary Power Unit End User: Commercial Aviation, Military Aviation, Cargo Operators, Business Aviation Distribution Channel: OEMs, Third-Party Providers, In-House, Online Platforms |
| Companies Covered | GE Aerospace, Lufthansa Technik, Rolls-Royce Holdings plc, Safran Aircraft Engines, RTX Corporation, Pratt & Whitney, Delta TechOps, MTU Aero Engines, AAR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Engine MRO Market Emerging Trajectories
Digital thread technologies and sustainable process chemistries are reconfiguring how engine shops validate airworthiness, manage component lifecycles, and contract with airline customers.
Additive repair processes using directed energy deposition are supplanting conventional weld restoration for high-pressure compressor blade tips. Major overhaul facilities in Germany and Singapore have adopted these systems for nickel superalloy component refurbishment. The technology is compressing turnaround times from weeks to days while reducing material waste streams.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating certain vapor degreasing chemistries from engine cleaning operations. MRO providers must qualify aqueous and plasma-based alternatives for oil path decontamination. Shops in the Netherlands and France are furthest along in process revalidation, creating regulatory arbitrage advantages.
Airline technical procurement departments are consolidating vendor panels and demanding integrated material-plus-labor contracts rather than discrete component repairs. This behavior concentrates spend with full-capability overhaul shops and marginalizes specialized single-process providers. The shift is most pronounced among Middle Eastern flag carriers and European network airlines.
Aviation Engine MRO Market Segmentation
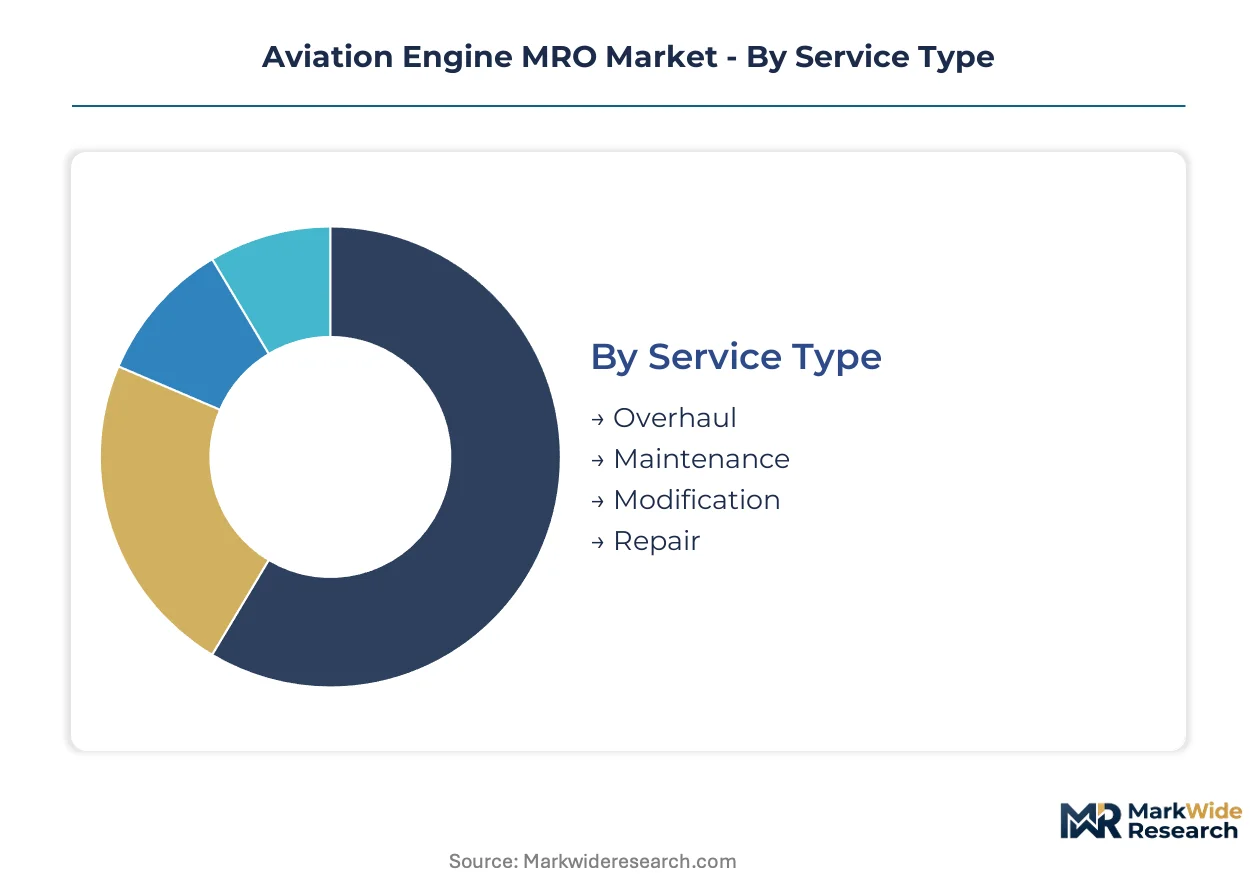
Aviation engine MRO segmentation reveals how service delivery models, powerplant architectures, and customer procurement patterns create distinct value pools with divergent margin profiles and capability requirements.
Service Type:
Overhaul commands the largest revenue share through OEM-affiliated networks, while repair and modification services flow increasingly through third-party channels seeking cost arbitrage on mature engine programs.
- Overhaul:Complete disassembly, inspection, and reassembly of turbine modules to restore exhaust gas temperature margins and compressor efficiency. Demand concentrates at Lufthansa Technik's Hamburg facility and Dubai's emerging MRO cluster as airlines outsource wide-body engine heavy maintenance.
- Maintenance:Scheduled line maintenance and borescope inspections preserving on-wing time between shop visits. Low-cost carriers in Indonesia and Vietnam are driving third-party adoption for narrow-body fleet support.
- Modification:Performance enhancement packages and service bulletin compliance upgrades. FAA airworthiness directives on life-limited parts tracking are expanding mandatory modification scopes across aging fleets.
- Repair:Component-level restoration of turbine blades, combustors, and casings using weld and additive processes. Independent shops in Poland and Turkey compete on turnaround time for legacy engine repairs.
By volume, Maintenance leads. By growth pace, Modification is climbing the fastest as regulatory mandates expand.
Engine Type:
Cost tiers separate high-bypass turbofan overhauls requiring specialized geared turbofan tooling from lower-complexity piston and auxiliary power unit services with commoditized repair schemes.
- Turbofan:High-bypass architectures powering commercial wide-body and narrow-body aircraft. Geared turbofan programs at Pratt & Whitney and CFM International are forcing MRO shops to retool for new fixture sets and blade geometries.
- Turboprop:Regional aircraft and cargo turboprop powerplants with lower cycle limits and more frequent hot section inspections. Demand clusters in Canada and New Zealand for regional fleet support.
- Piston:Reciprocating engines for general aviation and flight training aircraft. Repair economics favor replacement over overhaul for engines beyond mid-time status.
- Auxiliary Power Unit:Honeywell and Collins Aerospace turbine systems providing aircraft electrical and pneumatic power. Third-party providers capture share as airlines unbundle APU services from airframe contracts.
By revenue concentration, Turbofan dominates. By margin expansion, Auxiliary Power Unit is gaining share fastest as component commonality improves.
End User:
Customer type determines contract structure, with military aviation favoring performance-based logistics and commercial carriers shifting toward power-by-the-hour availability guarantees.
- Commercial Aviation:Scheduled passenger airlines representing the core demand base for engine overhaul capacity. Middle Eastern flag carriers consolidate vendor panels around integrated material-plus-labor contracts.
- Military Aviation:Government depot maintenance and contractor logistics support programs for fighter and transport engines. NATO member state privatization initiatives are opening depot functions to commercial operators.
- Cargo Operators:Dedicated freighter fleets with higher utilization rates and accelerated cycle accumulation. E-commerce volume growth is expanding dedicated cargo fleet engine demand.
- Business Aviation:Corporate and private jet operators with dispersed fleets and premium turnaround expectations. Mobile repair teams and on-wing services reduce aircraft downtime.
By shop visit volume, Commercial Aviation leads. By contract value growth, Military Aviation is expanding most quickly through performance-based logistics conversion.
Distribution Channel:
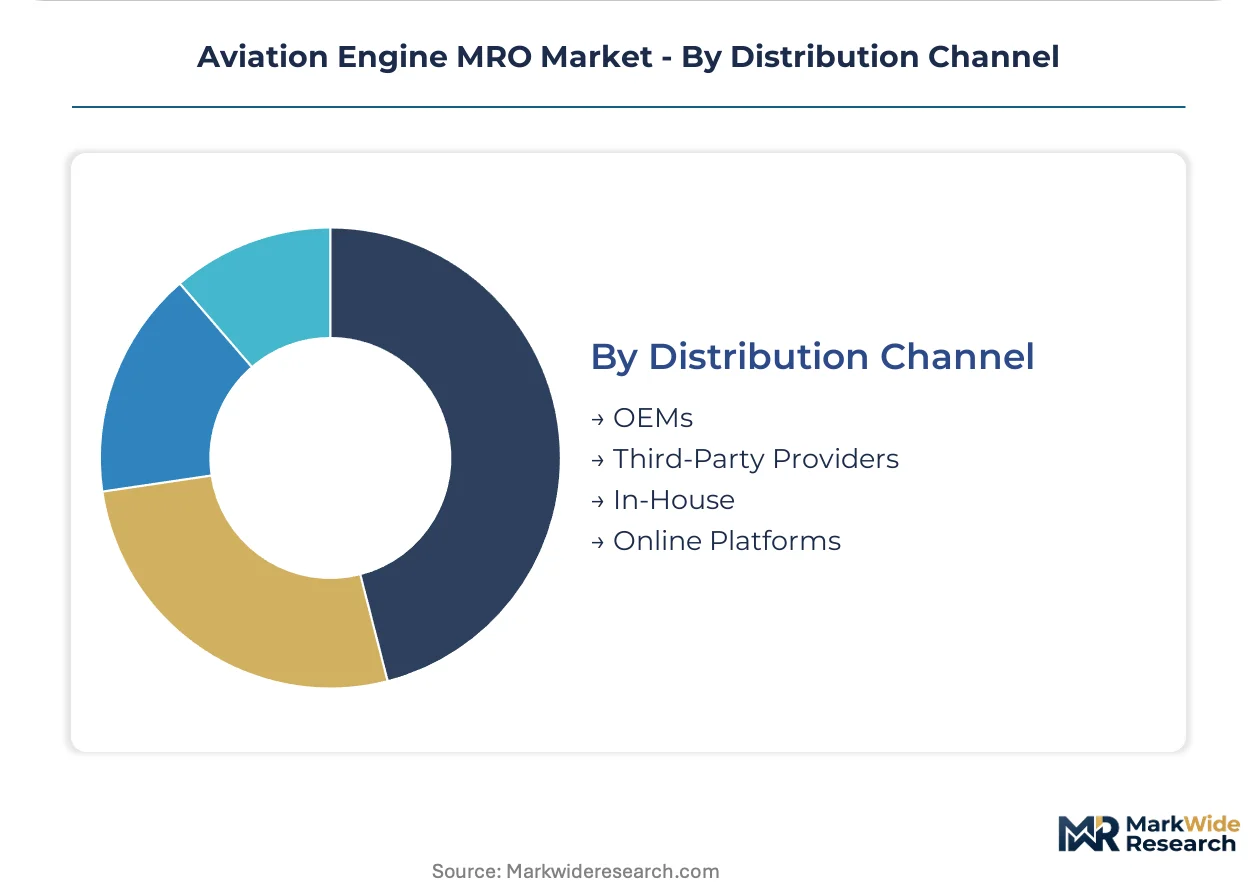
Supply concentration favors OEM-affiliated networks controlling proprietary technical data, while independent channels compete on cost for mature engine types approaching fleet retirement.
- OEMs:GE Aerospace and Rolls-Royce captive service channels with exclusive access to repair schemes and predictive analytics platforms. Long-term TotalCare and OnPoint agreements lock in airline customers.
- Third-Party Providers:Independent MRO shops capturing share from airlines seeking cost arbitrage. EASA Part 145 certification timelines constrain new market entry.
- In-House:Airline captive maintenance facilities at large network carriers. Capital intensity and technician shortages are accelerating outsourcing decisions.
- Online Platforms:Digital procurement interfaces for spare parts and component exchanges. Consolidation of vendor panels limits platform penetration for complex overhaul services.
By revenue capture, OEMs lead. By share gain trajectory, Third-Party Providers are climbing the fastest as low-cost carrier outsourcing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial carriers in the United Arab Emirates concentrate procurement authority for wide-body engine overhaul, while low-cost operators in Southeast Asia drive third-party maintenance outsourcing. FAA and EASA mandates on digital traceability reshape compliance investments across operational jurisdictions.
United States
Military depot privatization and cargo fleet expansion sustain engine MRO demand at Delta TechOps and AAR Corporation facilities. FAA airworthiness directives on life-limited parts tracking tighten documentation standards for domestic operators. The American Southeast clusters overhaul capacity near Atlanta and Dallas-Fort Worth as airlines consolidate vendor relationships.
Germany
Lufthansa Technik anchors European wide-body engine overhaul through Hamburg and Malta facilities serving network carriers. EASA Part 145 certification requirements constrain new market entry while favoring incumbent technical data holders. The Hamburg metropolitan area concentrates specialized non-destructive testing infrastructure for high-pressure turbine component inspection.
United Arab Emirates
Dubai's Al Maktoum Airport zone and Abu Dhabi MRO clusters attract European and Asian flag carriers seeking centralized overhaul capacity. MOHAP oversight aligns with EASA regulatory frameworks for repair station authorization. The Dubai South aerotropolis builds dedicated engine test cell infrastructure for next-generation geared turbofan programs.
Singapore
Pratt & Whitney and GE Aerospace affiliate shops process narrow-body engine volumes from Indonesian and Vietnamese low-cost carriers. The Civil Aviation Authority of Singapore enforces stringent repair process approvals that exceed baseline EASA requirements. Seletar Aerospace Park houses additive manufacturing capabilities for directed energy deposition blade tip restoration.
United Kingdom
Rolls-Royce TotalCare contracts lock in domestic network carrier engine maintenance through Derby and Bristol service centers. The UK Civil Aviation Authority implements EASA-aligned continuing airworthiness requirements post-Brexit through bilateral recognition agreements. The East Midlands aerospace cluster specializes in military transport engine overhaul for NATO contractor logistics programs.
Aviation Engine MRO Market Vendor Landscape
Player mix skews toward OEM-affiliated service networks controlling proprietary repair schemes and predictive analytics platforms. Independent third-party providers capture mature engine program share where technical data restrictions ease. Strategic archetypes separate captive OEM channels, independent overhaul specialists, and airline-affiliated maintenance divisions. Competitive moves concentrate on EASA Part 145 certification expansion and power-by-the-hour contract bundling.
Within the OEM-affiliated tier, GE Aerospace and Rolls-Royce Holdings plc exemplify integrated service models that combine original equipment manufacturing with long-term maintenance agreements. Lufthansa Technik occupies a position bridging independent third-party and airline-captive archetypes through its multi-customer Hamburg facility. These three entities represent the concentration of proprietary technical data access that shapes competitive boundaries across high-bypass turbofan overhaul markets.
| Leading Market Players |
|---|
| GE Aerospace |
| Lufthansa Technik |
| Rolls-Royce Holdings plc |
| Safran Aircraft Engines |
| RTX Corporation |
| Pratt & Whitney |
| Delta TechOps |
| MTU Aero Engines |
| AAR Corporation |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Hamburg and Dubai overhaul facilities shapes price floors across the wide-body engine segment, compressing margins for independent shops while OEM-affiliated networks extract premiums through bundled predictive analytics contracts.
Pricing Analysis
Cost-plus contracts with London Metal Exchange nickel indexation dominate high-pressure turbine section repairs, transferring raw material volatility to airline customers. Three-tier pricing structure across OEM-certified, EASA Part 145-approved, and uncertified independent shops reflects technical data access and turnaround reliability. Pricing pressure stems from low-cost carrier procurement consolidation in Southeast Asia. Cargo operators exhibit highest price sensitivity; Middle Eastern flag carriers prioritize availability guarantees over unit cost.
Supply Chain Analysis
Inbound logistics costs from Rotterdam port congestion and constrained forged titanium billet availability from Russia-Ukraine trade lanes strain component economics for turbine blade repairs. Supply concentrates in Germany, the United Arab Emirates, and Singapore for specialized non-destructive testing infrastructure. Nickel-based superalloys, forged titanium billets, and ceramic thermal barrier coatings constitute critical input dependencies. Single-source vulnerability runs through OEM-controlled repair scheme documentation. Distribution runs through direct OEM-affiliated service channels and certified third-party MRO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geared turbofan technology cycles and EASA digital traceability mandates are compressing competitive windows, rewarding rapid capability investments while punishing legacy tooling exposure.
For Market Incumbents: Fortify proprietary data positions by deepening repair scheme exclusivity and expanding predictive analytics platform penetration. GE Aerospace and Rolls-Royce should accelerate TotalCare contract bundling to lock out independent challengers. Capacity expansion at Dubai and Singapore hubs captures Southeast Asian outsourcing flows. For New Entrants and Emerging Players: EASA Part 145 certification fast-tracks through bilateral recognition with Singapore and UAE regulators offer lowest-friction market entry. Target auxiliary power unit overhaul and legacy narrow-body engine repair where technical data restrictions ease. Partner with Polish or Turkish component specialists for turnaround time arbitrage against Hamburg incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors independent shops with geared turbofan tooling commitments and established military contractor logistics relationships. Five-to-ten year viability hinges on exposure to next-generation engine programs versus legacy fleet retirement risk. Monitor Pratt & Whitney GTF shop visit frequency as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Part 145 Certification Expansion | Unlocks repair process authorizations for independent shops competing with OEM-affiliated networks. |
| Predictive Analytics Platform Integration | GE Aerospace leverages sensor data to extend on-wing time and lock in power-by-the-hour contracts. |
| Geared Turbofan Tooling Investment | Pratt & Whitney and CFM International fixture sets capture next-generation narrow-body overhaul demand. |
| Military Contractor Logistics Conversion | NATO depot privatization opens performance-based contracts to commercial MRO operators in East Midlands. |
| Directed Energy Deposition Adoption | Additive repair processes at Seletar Aerospace Park compress blade tip restoration from weeks to days. |
Methodological Framework
Operator-level perspectives from engine shop managers, airline technical procurement directors, EASA certification auditors, and military logistics officers anchored the qualitative base. Secondary validation drew from FAA airworthiness directive filings, EASA Part 145 repair station databases, OEM service contract disclosures, and customs records for titanium and superalloy trade flows. Bottom-up shop visit volume estimates triangulated against top-down fleet projection models.
Sensitivity analysis tested forecast outputs against variations in geared turbofan adoption pace, military depot privatization timelines, and REACH chemical restriction enforcement intensity. Segmentation dimensions modeled include service type, engine architecture, end-user contract structure, and distribution channel concentration. CAGRs derived from fitted growth curves applied to disclosed maintenance event intervals and fleet age profiles.
Decision-makers should treat outputs as directional under assumptions of steady EASA regulatory alignment and no disruptive engine technology substitution; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as titanium supply diversification and additive repair qualification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Exterior Strip and Repaint Services Market
Aircraft Maintenance and MRO Solutions
Global Degaussing System Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Aerospace and Defense MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Weight Scale Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Engine Hoists Market
Aircraft Maintenance and MRO Solutions
Military Aircraft Maintenance, Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Storage, Preservation and Reactivation Services Market