
 Aircraft Vacuum Cleaners Market | 2026-2036
Aircraft Vacuum Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Vacuum Cleaners Market Analytics
A shift from outsourced cleaning services to in-house fleet maintenance teams is consolidating procurement decisions at major airlines and MRO providers. Nilfisk Group leverages its industrial vacuum heritage to anchor European aviation contracts. Alfred Kärcher GmbH & Co. KG competes through specialized portable units designed for confined cabin spaces. Daimer Industries differentiates with steam-integrated systems targeting deep sanitization protocols.
Aircraft vacuum cleaners are purpose-built suction systems engineered to operate within narrow fuselage aisles and tight galley corners, typically incorporating HEPA filtration to capture particulates down to 0.3 microns and maintain cabin air quality standards. These units serve the critical function of removing debris, dust, and potential contaminants from passenger seating areas, cargo holds, and cockpit environments between flight cycles. Portable units dominate current airline procurement due to operational flexibility across varying aircraft configurations, while battery-powered technology represents the fastest-growing segment as carriers eliminate cord hazards and reduce turnaround times. Maintenance Facilities application channels command premium pricing through specialized pneumatic systems designed for heavy-duty hangar environments.
The FAA mandates specific cleaning protocols for Part 121 carriers through operational specifications tied to cabin safety standards, while EASA enforces comparable requirements under its airworthiness directives for EU-registered aircraft. OSHA workplace exposure limits and REACH chemical compliance further shape equipment specifications for ground-handling crews and cleaning contractors. Stakeholders must monitor evolving HEPA efficiency benchmarks and battery certification standards as regulatory bodies tighten alignment between cleaning equipment and broader aviation sustainability frameworks.
Market Dynamics
Aviation regulators in the United States, Germany, and Japan are tightening HEPA filtration mandates, forcing equipment upgrades across narrow-body and wide-body fleets while consolidating procurement authority at airline maintenance hubs.
Growth Catalysts
- FAA Operational Specifications:Part 121 carriers must meet escalating cabin safety standards, mandating HEPA-equipped cleaning systems for all passenger aircraft.
- Battery Chemistry Advancements:Lithium-ion power density improvements enable cordless operation without sacrificing suction performance, eliminating turnaround delays from cord management.
- Narrow-Body Fleet Expansion:Low-cost carriers across Southeast Asia and Latin America are adding single-aisle aircraft at rates exceeding wide-body procurement, concentrating demand for compact portable units.
Market Restraints
- Lithium Supply Concentration:Battery cell production clusters in China's Jiangsu and Fujian provinces create input vulnerability for cordless unit manufacturers outside Asia.
- REACH Chemical Compliance:ECHA restrictions on certain polymers and lubricants force reformulation of housing materials and motor seals, extending R&D cycles.
- Pneumatic System Lock-in:Legacy hangar infrastructure at major MRO facilities in the United States and Germany favors compressed-air units, slowing battery adoption in maintenance channels.
Strategic Opportunities
- India Fleet Modernization:IndiGo and Air India are expanding domestic and international routes, creating first-time demand for standardized cleaning protocols across newly acquired Airbus and Boeing fleets.
- Steam-Vacuum Convergence:Integration of high-temperature sanitization with HEPA extraction addresses post-pandemic deep-cleaning mandates without separate equipment passes.
- Direct Airline Procurement Portals:Carriers including Delta and Lufthansa are bypassing traditional distribution to negotiate fleet-wide service agreements directly with specialized equipment vendors.
Industry Challenges
- Aviation-Specific Technician Certification:Ground handling crews require training on aircraft interior configurations and damage prevention protocols, extending onboarding timelines.
- Battery Airworthiness Documentation:Lithium power systems demand extensive thermal runaway testing and UN 38.3 certification for cargo hold transport, complicating spare parts logistics.
- Legacy Pneumatic Integration:Hangar operators face capital expenditure requirements to retrofit electrical charging infrastructure while maintaining compressed-air redundancy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Vacuum Cleaners Market |
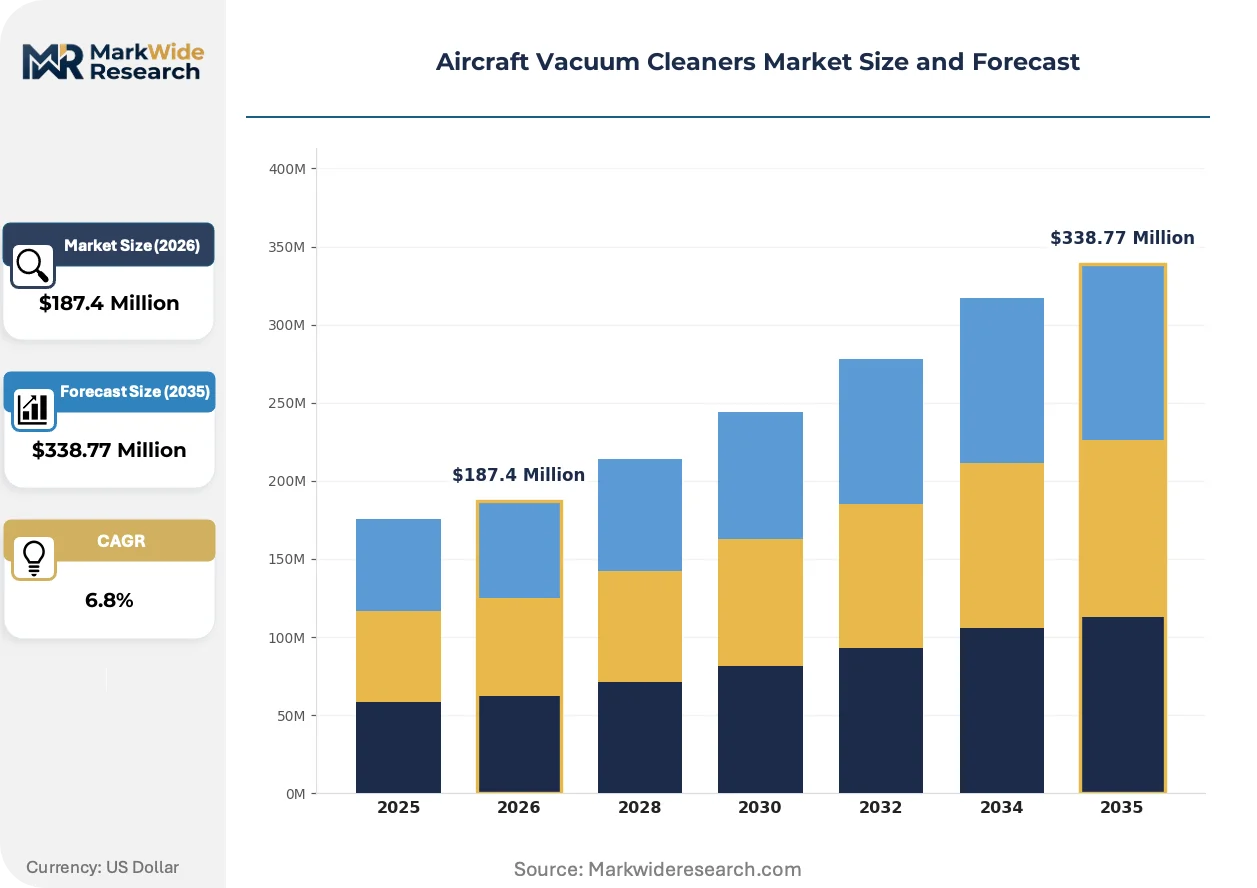
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Industrial, Handheld, Centralized Application: Commercial Aviation, Private Jets, Helicopters, Maintenance Facilities End User: Airlines, Private Operators, Maintenance Providers, Cleaning Services Technology: HEPA Filtration, Battery-Powered, Electric, Pneumatic |
| Companies Covered | Alfred Kärcher GmbH & Co. KG, Morclean Limited, Numatic International, Pacvac, Daimer Industries, Nilfisk Group, Delfin Industrial Corporation, Tiger-Vac Inc., Ghibli & Wirbel SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Vacuum Cleaners Market Evolving Landscape
Equipment manufacturers are converging on cordless architectures and sanitization-integrated designs as regulatory pressure and operational efficiency demands reshape procurement criteria across commercial aviation.
Lithium-ion battery packs with aviation-grade thermal management are electrifying portable vacuum architectures, replacing tethered units in turnaround cleaning protocols. Narrow-body operators at Dallas-Fort Worth and Atlanta hubs are completing fleet-wide cordless transitions within eighteen-month procurement cycles. This shift is compressing maintenance windows and eliminating trip hazards in confined cabin aisles.
EASA airworthiness directives now explicitly reference HEPA efficiency benchmarks for cabin cleaning equipment, aligning with FAA operational specification updates. European MRO providers must document filtration performance across all vacuum systems used on EU-registered aircraft. Wide-body operators at Frankfurt and Amsterdam Schiphol are prioritizing certified units to avoid audit penalties during regulatory inspections.
Airline technical procurement teams are consolidating vendor relationships through multi-year fleet agreements, displacing spot purchasing from ground handling contractors. Lufthansa Technik and Delta TechOps now specify standardized equipment across their entire narrow-body and wide-body portfolios. This concentration is most visible at North American maintenance hubs serving legacy carrier networks.
Aircraft Vacuum Cleaners Market Segmentation
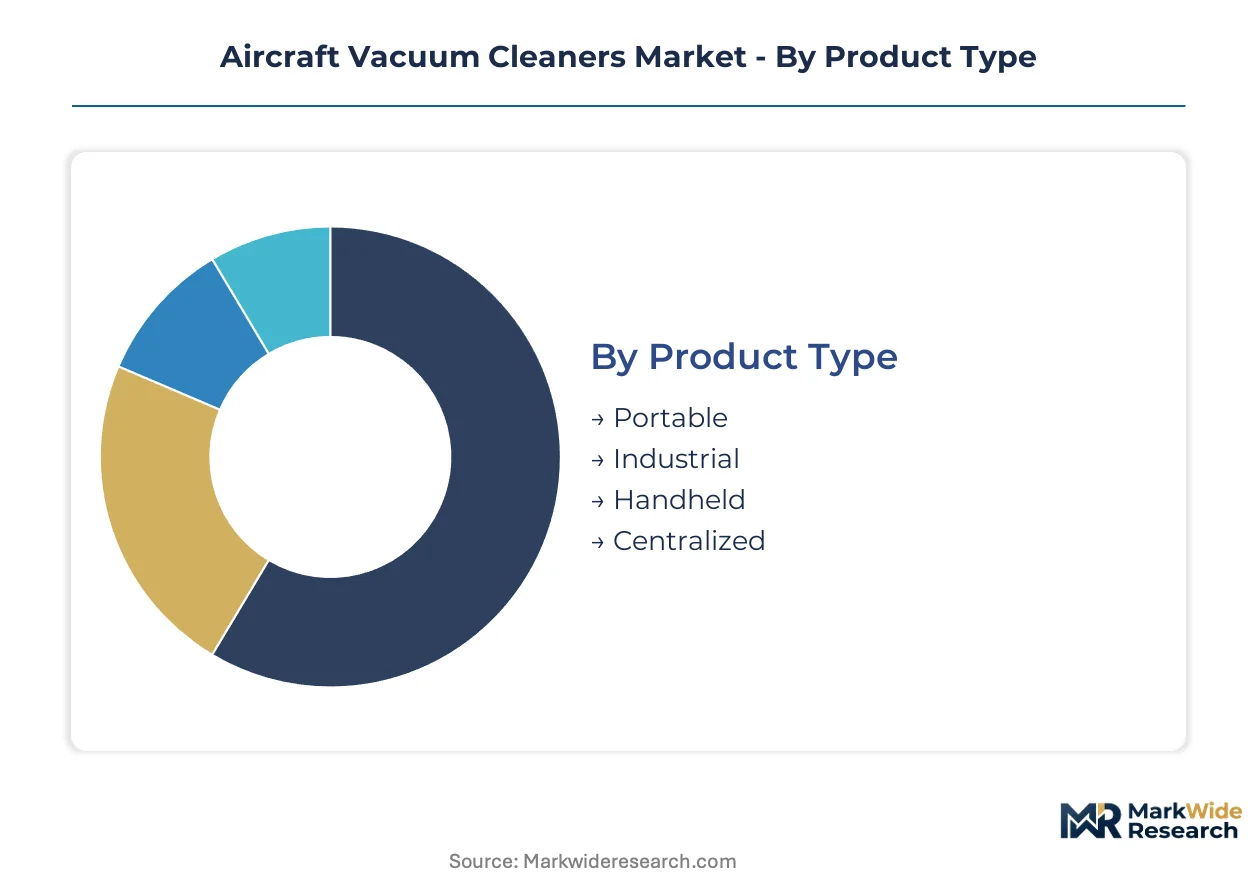
Segmentation in aircraft vacuum cleaners reflects divergent operational constraints across fleet types and ground-handling environments. Equipment specifications must reconcile cabin spatial limits, turnaround time pressures, and regulatory filtration mandates that vary by aviation segment.
Product Type:
Customization intensity spans from standardized centralized systems to purpose-built portable units, with cordless architectures commanding engineering investment.
- Portable:Cordless lithium-ion units with aviation-grade thermal management dominate narrow-body turnaround cleaning at Dallas-Fort Worth and Atlanta hubs. Delta TechOps and Lufthansa Technik specify these for fleet-wide standardization across single-aisle configurations.
- Industrial:High-capacity units with reinforced housings serve wide-body deep-cleaning cycles and cargo hold maintenance. Demand concentrates at Frankfurt and Amsterdam Schiphol MRO facilities facing EASA audit scrutiny on HEPA documentation.
- Handheld:Compact units target cockpit environments and premium cabin spot cleaning. Private jet operators at Teterboro and Van Nuys favor these for rapid deployment.
- Centralized:Fixed vacuum networks integrated into hangar infrastructure serve heavy maintenance bays. Legacy facilities in Germany retain pneumatic-fed centralized systems despite battery transition pressures.
Leading the category by volume: Portable units. Growing fastest: Battery-powered portable configurations.
Application:
Procurement authority shifts from ground contractors to airline technical teams as fleet standardization tightens.
- Commercial Aviation:Narrow-body fleets at IndiGo and Air India drive first-time standardized procurement across newly acquired Airbus and Boeing aircraft. FAA Part 121 mandates and EASA airworthiness directives enforce HEPA-equipped systems for all passenger configurations.
- Private Jets:Fragmented demand across fractional ownership fleets and charter operators favors handheld and compact portable units. Teterboro and Van Nuys FBOs specify quick-deployment equipment for 30-minute turnaround windows.
- Helicopters:Specialized units address confined cabin geometries and rotor-downwash contamination patterns. Offshore transport operators in the North Sea specify corrosion-resistant housings.
- Maintenance Facilities:Heavy-duty pneumatic and electric systems command premium pricing for hangar-based deep cleaning. German and US MRO providers face capital expenditure decisions on charging infrastructure retrofit.
Commercial Aviation generates the dominant revenue share. Maintenance Facilities show the steepest expansion trajectory as MRO standardization accelerates.
End User:
Direct procurement portals are displacing distributor channels as technical specifications consolidate at fleet level.
- Airlines:Legacy carriers including Delta and Lufthansa negotiate multi-year fleet agreements bypassing traditional ground-handling intermediaries. Technical procurement teams now specify standardized equipment across narrow-body and wide-body portfolios.
- Private Operators:Fractional ownership fleets and ultra-high-net-worth individuals drive demand for premium handheld units with concierge service integration.
- Maintenance Providers:Lufthansa Technik and independent MROs face EASA documentation requirements for all vacuum systems deployed on EU-registered aircraft.
- Cleaning Services:Contract ground handlers at Southeast Asian and Latin American hubs adopt portable units as low-cost carriers expand single-aisle fleets.
Airlines control the largest procurement volume. Maintenance Providers are gaining share fastest as technical certification requirements deepen.
Technology:
Regulatory filtration benchmarks and power system certification are reshaping R&D allocation across engineering teams.
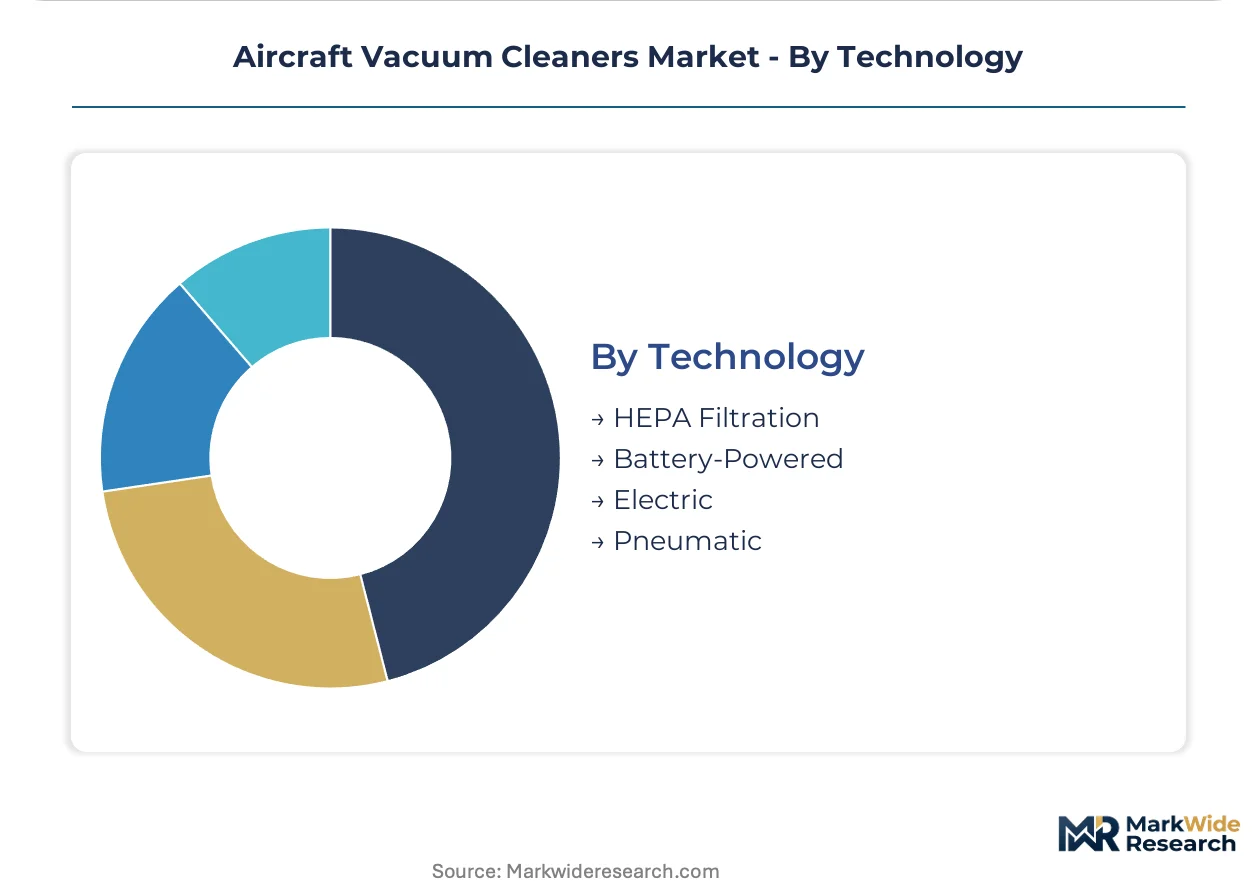
- HEPA Filtration:Systems capturing particulates down to 0.3 microns are now mandatory under FAA operational specifications and EASA airworthiness directives. Frankfurt and Amsterdam Schiphol operators prioritize certified units to avoid audit penalties.
- Battery-Powered:Lithium-ion architectures with UN 38.3 certification for cargo hold transport are eliminating cord hazards in confined cabin aisles. Thermal runaway testing requirements complicate spare parts logistics.
- Electric:Corded units retain share in hangar environments with established electrical infrastructure. US and German MRO facilities face retrofit decisions on charging systems.
- Pneumatic:Compressed-air systems dominate legacy maintenance facilities with existing infrastructure. Battery adoption in these channels slows due to capital expenditure requirements for electrical redundancy.
HEPA Filtration leads by regulatory mandate penetration. Battery-Powered technology climbs fastest as turnaround efficiency pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium cell production clusters in China's Jiangsu and Fujian provinces anchor battery supply chains for cordless aviation cleaning equipment. This concentration shapes procurement vulnerability and drives regional manufacturing partnerships across three continents.
United States
FAA Part 121 operational specifications mandate HEPA-equipped cleaning systems for all passenger aircraft, consolidating procurement authority at airline maintenance hubs. OSHA workplace exposure limits further shape equipment specifications for ground-handling crews. Dallas-Fort Worth and Atlanta hubs are completing fleet-wide cordless transitions within compressed procurement cycles.
Germany
EASA airworthiness directives enforce HEPA efficiency benchmarks for cabin cleaning equipment used on EU-registered aircraft. REACH chemical compliance restrictions force reformulation of housing materials and motor seals. Frankfurt and Amsterdam Schiphol MRO facilities prioritize certified units to avoid audit penalties during regulatory inspections.
China
Battery cell manufacturing concentrates in Jiangsu and Fujian provinces, creating input vulnerability for cordless unit manufacturers outside Asia. Domestic aviation fleet expansion drives first-time standardized cleaning protocol adoption. Low-cost carriers across Southeast Asia source equipment through Chinese manufacturing partnerships.
India
IndiGo and Air India fleet modernization creates first-time demand for standardized cleaning protocols across newly acquired Airbus and Boeing aircraft. The country's national aviation regulator aligns with international cabin safety standards. Domestic maintenance hubs in Delhi and Mumbai are establishing direct procurement relationships with specialized equipment vendors.
Japan
METI industrial standards influence aviation equipment certification processes for domestic and export markets. JIS filtration benchmarks align with international HEPA requirements. Aviation maintenance clusters in Tokyo and Osaka prioritize compact portable units for narrow-body turnaround operations.
Aircraft Vacuum Cleaners Market Competitive Landscape
Global majors compete with regional champions across industrial vacuum heritage and aviation-specific specialization. The vendor base stratifies between diversified cleaning equipment conglomerates and focused aviation maintenance suppliers. Three archetypes dominate: industrial heritage players leveraging existing airline relationships, specialized aviation equipment fabricators, and diversified cleaning technology conglomerates. Strategic moves concentrate on fleet-wide service agreements and cordless architecture transitions.
Within the industrial heritage tier, Nilfisk Group and Alfred Kärcher GmbH & Co. KG represent established European anchors competing through distinct positioning vectors. Nilfisk leverages its industrial vacuum heritage to secure aviation maintenance contracts, while Kärcher occupies a position emphasizing specialized portable configurations. Daimer Industries exemplifies the sanitization-integrated archetype, representing North American equipment differentiation through combined cleaning technologies. These three entities collectively illustrate the competitive tension between broad industrial capability and aviation-specific engineering focus.
| Leading Market Players |
|---|
| Alfred Kärcher GmbH & Co. KG |
| Morclean Limited |
| Numatic International |
| Pacvac |
| Daimer Industries |
| Nilfisk Group |
| Delfin Industrial Corporation |
| Tiger-Vac Inc. |
| Ghibli & Wirbel SpA |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between HEPA-validated aviation units and uncertified industrial alternatives manifests in both pricing premiums and supply chain sourcing patterns. Airlines and MRO providers face divergent procurement economics as FAA and EASA mandates force equipment upgrades while lithium cell concentration in East Asia shapes battery-powered unit availability.
Pricing Analysis
Service-bundling intensity separates fleet-wide maintenance agreements from transactional spot purchases in this market. Three-tier pricing structure across premium HEPA-certified, standard aviation-grade, and economy industrial-adapted levels reflects filtration validation investment and warranty duration. Cost compression in the economy tier is intensifying because ground-handling contractors face margin pressure from low-cost carrier procurement consolidation. Maintenance facilities show lowest price sensitivity due to audit penalty exposure, while independent cleaning services exhibit highest sensitivity to upfront capital requirements.
Supply Chain Analysis
Refurbishment and battery replacement flows anchor aftermarket revenue for cordless unit manufacturers serving narrow-body operators. Lithium-ion cell production concentrates in China, South Korea, and Japan, creating input dependency for Western equipment fabricators. Aviation-grade thermal management systems and UN 38.3 certified battery packs draw from specialized electronics clusters in Germany and the United States. Single-source vulnerability runs through Jiangsu province cell manufacturers exposed to export licensing shifts. Distribution runs through direct airline procurement portals and specialized aviation maintenance distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lithium cell capacity constraints in East Asia prop pricing power for battery-integrated equipment manufacturers, insulating premium tier margins despite contractor segment pressure.
For Market Incumbents: Deploy fleet-wide service agreement structures to lock out emerging competitors. Nilfisk Group and Alfred Kärcher GmbH & Co. KG should deepen certification investment for EASA documentation compliance, countering threat from sanitization-integrated entrants like Daimer Industries. Backward integration into battery pack assembly reduces exposure to Chinese cell supply volatility. For New Entrants and Emerging Players: The mid-tier price gap between premium cordless aviation units and reconditioned pneumatic equipment offers white-space opportunity. Target maintenance facilities in Germany and the United States facing capital expenditure constraints on charging infrastructure retrofit. Private jet operators at Teterboro and Van Nuys present penetrable demand for compact handheld configurations. Go-to-market through FBO concierge service integration bypasses airline procurement consolidation. For Investors and Strategic Acquirers: Re-rating potential sits with specialized aviation equipment fabricators given EASA and FAA regulatory alignment tightening. Long-term viability favors vendors with captive HEPA filtration technology and established airline technical relationships. Acquisition target archetype: mid-cap cordless specialists with UN 38.3 certification infrastructure and narrow-body operator reference accounts. Signal to watch: fleet standardization announcements from IndiGo and Air India triggering first-time procurement waves.| Strategic Initiative | Industry Significance |
|---|---|
| HEPA Certification Investment | EASA audit compliance at Frankfurt and Amsterdam Schiphol facilities prevents penalty exposure. |
| Battery Supply Agreement | Long-term lithium cell contracts with Jiangsu manufacturers secure cordless unit production continuity. |
| Fleet-Wide Service Contract | Delta TechOps and Lufthansa Technik standardization creates recurring revenue visibility. |
| Steam-Vacuum Integration | Daimer Industries' sanitization convergence addresses post-pandemic deep-cleaning protocol mandates. |
| Direct Procurement Portal | Bypassing traditional distribution captures margin from airline technical procurement consolidation. |
Research Methodology
Document review covered aviation regulatory filings from FAA and EASA, airline maintenance procurement disclosures, and lithium battery trade data, complemented by interviews with MRO operations directors, airline technical procurement managers, ground-handling contractor executives, and aviation equipment distribution specialists. Secondary validation drew from customs records, SEC 10-K filings of listed industrial equipment manufacturers, and IATA fleet data. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Cross-referencing historical fleet expansion patterns against panel input from maintenance facility operators shaped the projection framework. Segmentation dimensions modeled include product type, application channel, end-user procurement authority, and technology architecture across the projection horizon. CAGRs were derived from fitted growth curves against fleet delivery schedules and regulatory mandate implementation timelines. Industry-specific inputs incorporated narrow-body delivery backlogs and HEPA filtration adoption curves.
Inputs from airline technical procurement teams and MRO facility operators were available through the study window; gaps in private jet operator disclosure introduce uncertainty bands in the fractional ownership segment. Forecasts reflect assumptions on regulatory mandate enforcement consistency and lithium supply chain continuity. Material deviation in FAA Part 121 specification timing or Chinese export licensing protocols warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
United States Airframe MRO Market
Aircraft Maintenance and MRO Solutions
North America Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Component MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Weight Scale Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Air Transport MRO Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market