
 Military Aviation Maintenance, Repair, and Overhaul Market | 2026-2036
Military Aviation Maintenance, Repair, and Overhaul Market Size, Share, and Industry Trends Forecast 2026-2036
Military Aviation Maintenance, Repair, and Overhaul Market Insights
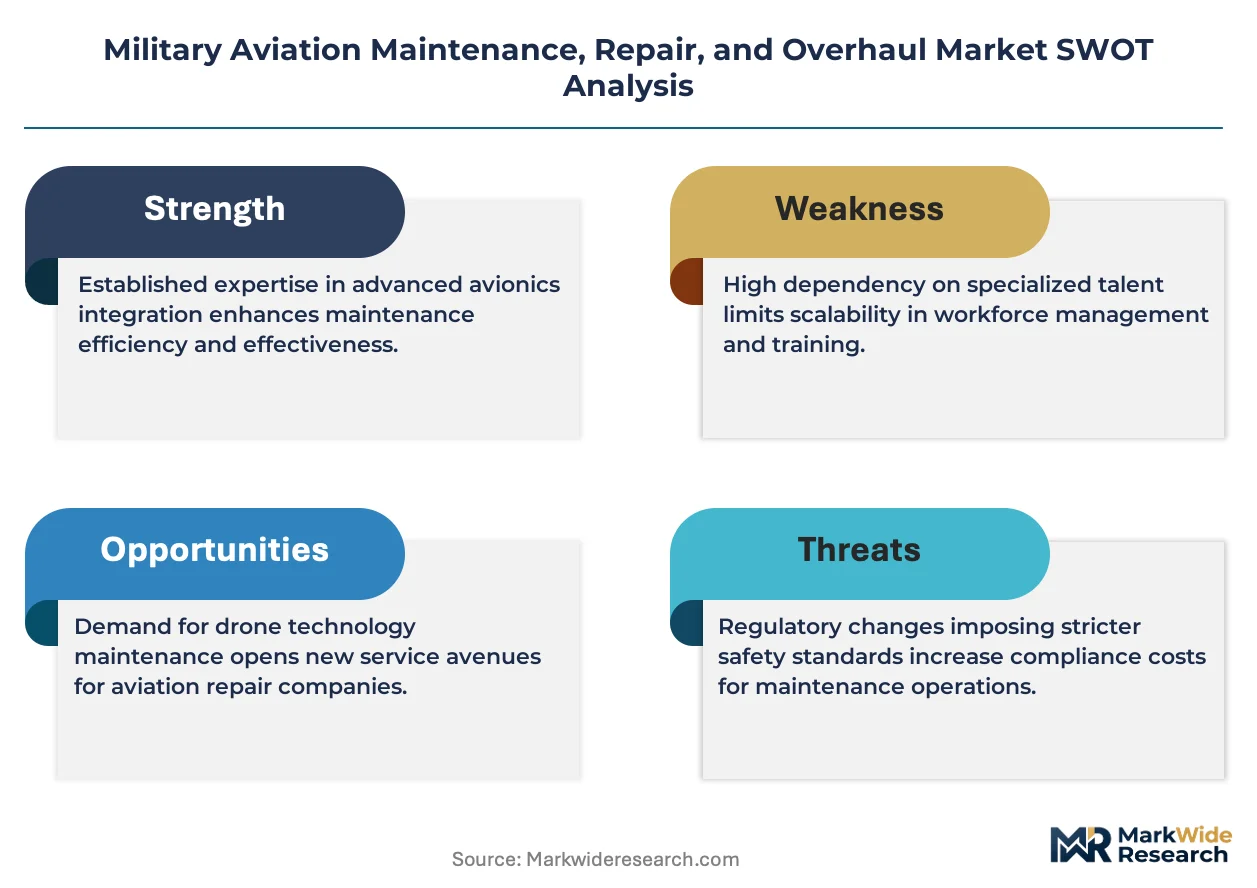
Digital twin integration is reconfiguring how military airframes and propulsion systems undergo condition-based overhaul rather than calendar-driven teardown. GE Aviation leverages its sensor-to-analytics pipeline to sustain long-term powerplant performance contracts with defense agencies. Rolls-Royce Holdings plc anchors its military aftermarket position through captive engine diagnostics networks spanning multiple allied fleets. BAE Systems plc differentiates via deep specialization in combat aircraft structural life-extension programs, occupying a niche with high technical barriers.
Military aviation maintenance, repair, and overhaul encompasses the technical inspection, refurbishment, and modification of defense aircraft, engines, and avionics to sustain airworthiness, mission readiness, and operational safety across flight-hour thresholds often exceeding commercial equivalents by three to five times. Scheduled maintenance and engine services command the largest current spend pools due to regulated inspection intervals and powerplant hot-section renewal cycles, while avionics upgrades and system repairs represent faster-expanding segments as software-defined warfare architectures demand continuous hardware refresh. Provider type dynamics reveal Original Equipment Manufacturers capturing margin-rich complex overhauls, whereas Third-Party Providers and Independent Shops compete on line maintenance and component turnaround velocity.
Defense procurement regulators including the FAA, EASA's military certification branch, and national military airworthiness authorities enforce stringent documentation and traceability standards that elevate compliance costs but also consolidate demand toward accredited providers. The EU AI Act's emerging classification of autonomous diagnostic systems will reshape how predictive maintenance algorithms gain operational approval across European air forces. Stakeholders must monitor how sovereignty-driven maintenance mandates and cross-border technical data-sharing restrictions redefine supplier eligibility and depot network geography.
Market Dynamics
Digital twin architectures are compressing maintenance intervals across NATO fighter fleets by enabling real-time structural health monitoring that replaces calendar-driven teardown protocols with condition-based interventions.
Growth Catalysts
- Powerplant hot-section renewal cycles:Fighter engine operating tempos exceed commercial equivalents by three to five times, mandating accelerated turbine blade and combustor replacement schedules that sustain depot-level throughput.
- FAA military airworthiness directive alignment:Digital record-keeping mandates are forcing defense agencies to modernize legacy documentation systems, creating pull-through demand for integrated maintenance management platforms.
- Predictive maintenance platforms:NATO air forces are embedding sensor-to-analytics pipelines across fourth- and fifth-generation fleets to reduce unscheduled downtime and extend mean time between overhauls.
Market Restraints
- Specialized alloy supply concentration:Nickel-based superalloys and titanium forgings for hot-section components depend on a limited supplier base concentrated in the United States and United Kingdom, exposing overhaul schedules to raw material bottlenecks.
- Technical data-sharing restrictions:Cross-border sovereignty mandates prevent allied depots from accessing proprietary engine diagnostic algorithms, fragmenting predictive maintenance networks across national boundaries.
- Skilled technician scarcity:Airframe and powerplant certificated mechanics with military security clearances face recruitment gaps that extend turnaround times at organic depot facilities.
Strategic Opportunities
- Unmanned combat aerial vehicle maintenance infrastructure:Drone fleet expansion outpaces dedicated MRO capacity, creating white space for specialized providers to establish low-observable material repair capabilities.
- EU AI Act autonomous diagnostic approval pathway:European air forces will require certified algorithmic maintenance systems, opening first-mover advantage for predictive analytics vendors meeting emerging conformity standards.
- Software-defined warfare hardware refresh cycles:Continuous avionics upgrades to support electronic warfare and networked combat architectures generate recurring modification demand separate from airframe overhaul intervals.
Industry Challenges
- Legacy platform technical data obsolescence:Original equipment manufacturers for aging fighter and transport fleets have dissolved or merged, leaving incomplete documentation that complicates structural life-extension engineering.
- Depot network geographic dispersion:The Pentagon's maintenance infrastructure spans multiple climate zones and security classifications, complicating standardized workforce training and tooling deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Aviation Maintenance, Repair, and Overhaul Market |
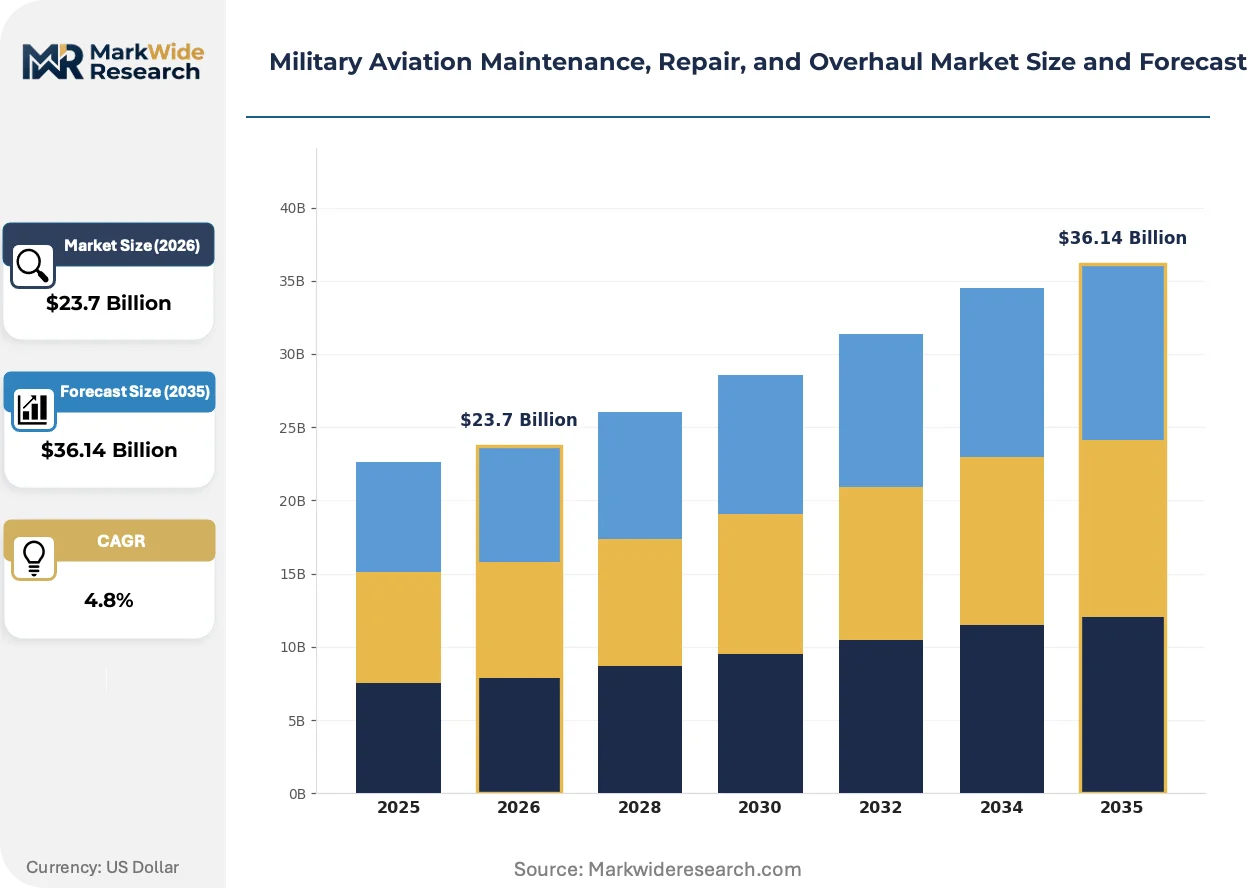
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Scheduled Maintenance, Unschedule Repairs, Component Overhaul, Avionics Upgrades Aircraft Type: Fixed-Wing, Rotary-Wing, Drones, Military Fighters Provider Type: Original Equipment Manufacturers, Third-Party Providers, Government Facilities, Independent Shops Maintenance Level: Airframe Services, Engine Services, System Repairs, Line Maintenance |
| Companies Covered | BAE Systems plc, GE Aviation, Lockheed Martin Corporation, Rolls-Royce Holdings plc, SAFRAN SA, RTX Corporation, Airbus SE, MTU Aero Engines AG, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Aviation Maintenance, Repair, and Overhaul Market Trends and Innovations
Maintenance execution is migrating from physical inspection protocols toward synthetic environments that replicate component behavior without disassembly, compressing diagnostic timelines and reducing invasive testing.
Digital twin technology is virtualizing how military airframes undergo structural assessment. Defense agencies in the United States and United Kingdom are deploying physics-based models that mirror fatigue accumulation across flight-hour histories. This virtualization enables depot planners to target inspections to specific airframe zones rather than conducting fleet-wide teardowns.
The EU AI Act's risk-based classification system is mandating conformity assessments for autonomous diagnostic algorithms before operational deployment across European air forces. National military airworthiness authorities must now verify algorithmic transparency and failure-mode predictability. Combat aircraft operators in France, Germany, and Italy are restructuring procurement specifications to require explainable AI documentation for predictive maintenance platforms.
Performance-based logistics contracts are displacing transactional spare-part purchases across allied defense procurement frameworks. Prime contractors now assume availability risk for engine and subsystem uptime rather than delivering discrete overhaul events. This reconfiguration concentrates most visibly in United States Department of Defense powerplant sustainment agreements, where contractors guarantee mission-capable rates against fixed fees.
Military Aviation Maintenance, Repair, and Overhaul Market Segmentation
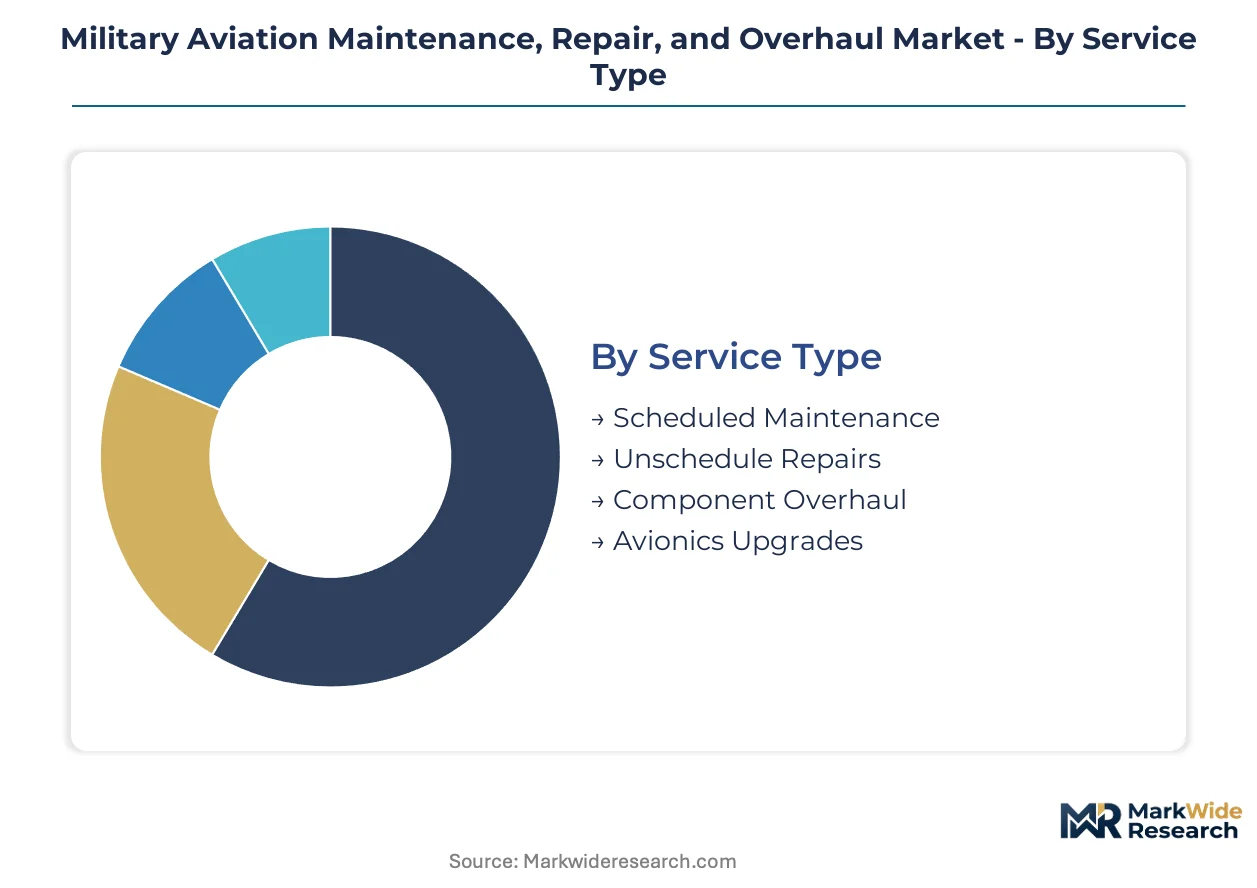
Military aviation MRO generates divergent margin profiles across service modalities, with scheduled interventions anchoring recurring revenue streams while unscheduled events and technology insertions capture premium pricing. Segment boundaries increasingly blur as performance-based logistics contracts bundle multiple service types under unified availability guarantees.
Service Type:
After-sales-service intensity varies dramatically across military aviation maintenance modalities, with powerplant and structural interventions demanding sustained technical engagement over multi-decade platform lifecycles.
- Scheduled Maintenance:Regulated inspection intervals mandated by FAA military airworthiness directives govern airframe teardowns, engine hot-section renewals, and landing gear overhauls. United States Air Force depot networks process the largest scheduled throughput volumes, with fighter engine operating tempos compressing maintenance cycles to fractions of commercial aviation equivalents.
- Unscheduled Repairs:Battle damage assessment, foreign object debris incidents, and mission-abort mechanical failures require rapid-response capabilities with security-cleared personnel. Demand concentrates at forward operating locations and continental United States sustainment hubs supporting deployed NATO fighter wings.
- Component Overhaul:Hydraulic actuators, fuel controls, and environmental systems undergo piece-part refurbishment rather than line-replaceable-unit discard.
- Avionics Upgrades:Software-defined warfare architectures mandate continuous hardware refresh for electronic warfare suites and networked combat systems.
By volume, scheduled maintenance leads. By growth pace, avionics upgrades are expanding most quickly.
Aircraft Type:
Platform complexity and operating environment dictate MRO cost structures, with manned combat aircraft consuming disproportionate technical labor hours relative to unmanned alternatives.
- Military Fighters:Fourth- and fifth-generation tactical aircraft impose the most intensive maintenance burdens through stealth coating restoration, radar cross-section preservation, and integrated avionics troubleshooting. United States F-35 sustainment contracts anchor regional demand concentration.
- Fixed-Wing:Strategic transport and tanker fleets emphasize engine services and structural corrosion programs over avionics refresh cycles.
- Rotary-Wing:Helicopter dynamic component replacement and transmission overhauls follow flight-hour accumulation patterns distinct from fixed-wing equivalents.
- Drones:Low-observable material repair capabilities remain underdeveloped relative to expanding unmanned combat aerial vehicle fleet sizes.
By revenue scale, military fighters dominate. By infrastructure gap, drones present the steepest expansion trajectory.
Provider Type:
Margin capture and risk allocation diverge sharply across organizational forms, with original equipment manufacturers leveraging proprietary technical data to secure long-term performance contracts.
- Original Equipment Manufacturers:Pratt & Whitney and GE Aviation sustain captive aftermarket positions through exclusive engine diagnostic algorithms and intellectual property control over hot-section component designs. Their powerplant availability guarantees displace transactional spare-part procurement across United States Department of Defense frameworks.
- Government Facilities:Organic depot maintenance networks retain classified repair capabilities for nuclear-certified platforms and specialized mission equipment beyond contractor access.
- Third-Party Providers:Component-level specialists compete on turnaround velocity for non-proprietary subsystems.
- Independent Shops:Line maintenance and pre-flight servicing operate at lowest margin thresholds with highest labor intensity.
By contract value, original equipment manufacturers lead. By competitive pressure, third-party providers are gaining share fastest.
Maintenance Level:
Technical depth and facility certification requirements stratify provider eligibility, with engine and airframe services demanding capital-intensive infrastructure that independent competitors cannot replicate.
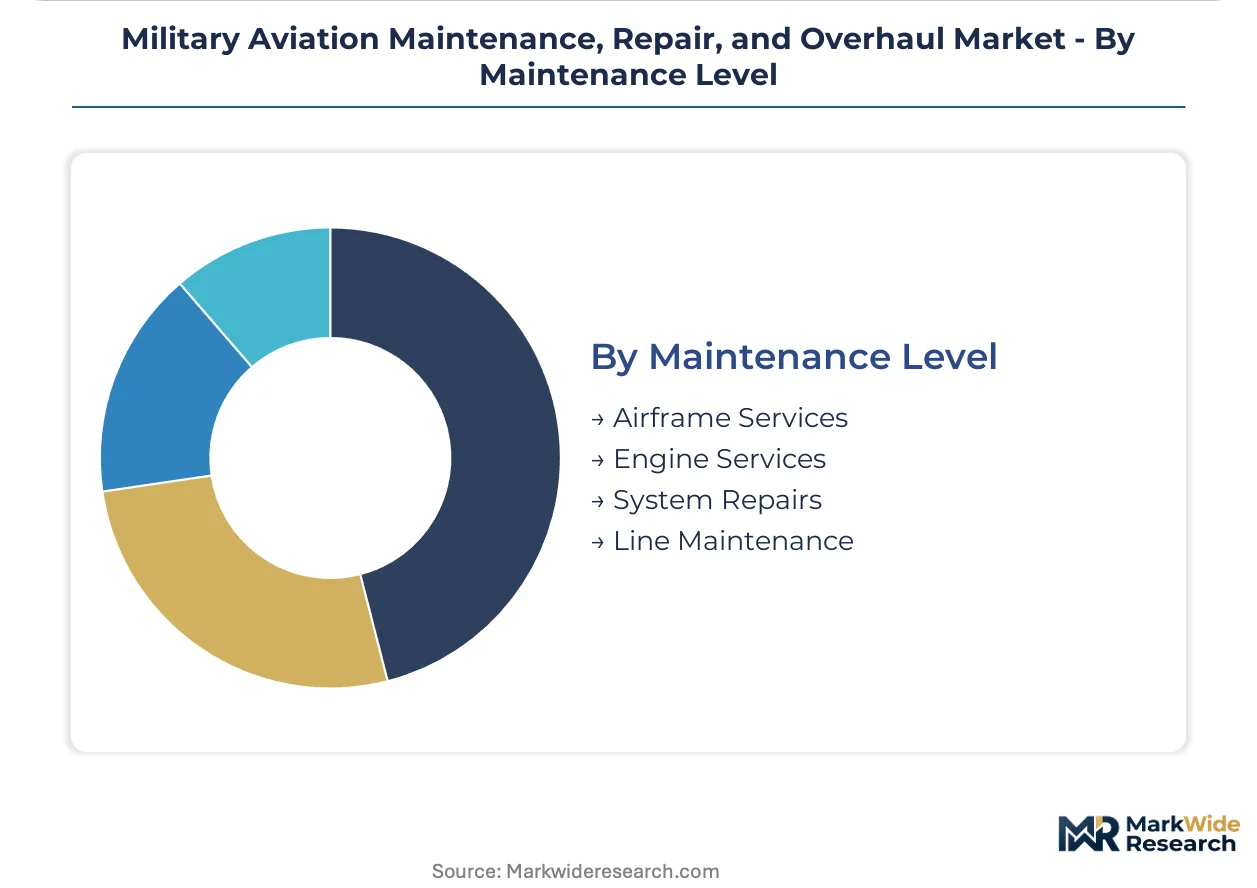
- Engine Services:Turbine blade renewal, combustor replacement, and full powerplant module exchanges require clean-room environments and specialized alloy handling capabilities. United Kingdom and United States supplier concentration for nickel-based superalloys exposes overhaul schedules to raw material bottlenecks.
- Airframe Services:Structural life-extension programs and fatigue-critical component replacement sustain platform operability beyond original design service lives.
- System Repairs:Hydraulic, pneumatic, and fuel subsystem troubleshooting occupies intermediate technical complexity.
- Line Maintenance:Flight-line servicing and minor discrepancy correction deploy lowest-skill labor pools with highest throughput velocity.
By labor hour consumption, engine services lead. By capability scarcity, airframe services command premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement agencies concentrate demand through multi-year sustainment contracts, with national airworthiness authorities shaping supplier eligibility through certification mandates and technical data access protocols.
United States
The Pentagon's depot maintenance network processes the highest scheduled throughput volumes globally, with fighter engine operating tempos compressing maintenance cycles to fractions of commercial equivalents. FAA military airworthiness directive alignment with digital record-keeping mandates is reshaping compliance workflows across organic and contractor facilities. Oklahoma City Air Logistics Complex and Warner Robins Air Logistics Complex anchor regional engine and airframe overhaul capacity.
United Kingdom
Rolls-Royce Holdings plc sustains captive aftermarket positions through exclusive engine diagnostic algorithms spanning multiple allied fleets. EASA's military certification branch enforces stringent documentation standards that consolidate demand toward accredited providers. RAF Brize Norton and RAF Marham cluster specialized structural life-extension capabilities for combat aircraft fleets.
France
Dassault Aviation's Rafale sustainment ecosystem generates concentrated demand for stealth coating restoration and radar cross-section preservation services. The EU AI Act's risk-based classification system is mandating conformity assessments for autonomous diagnostic algorithms before operational deployment. Istres-Le Tubé Air Base and Mont-de-Marsan Air Base host specialized avionics upgrade facilities supporting networked combat architectures.
Germany
Luftwaffe fleet modernization programs are expanding adoption of predictive maintenance platforms across fourth-generation fighter inventories. National military airworthiness authorities verify algorithmic transparency requirements under emerging EU regulatory frameworks. Manching Air Base and Laage Air Base concentrate depot-level structural assessment capabilities for NATO interoperable platforms.
Japan
Japan Air Self-Defense Force F-35 sustainment contracts are creating localized demand for low-observable material repair capabilities and integrated avionics troubleshooting. METI industrial policy supports domestic MRO capacity development through technology licensing arrangements. Gifu Air Base and Misawa Air Base anchor regional fighter fleet maintenance infrastructure with expanding contractor presence.
Military Aviation Maintenance, Repair, and Overhaul Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where original equipment manufacturers capture margin-rich complex overhauls through proprietary technical data control. The vendor base stratifies between prime contractors holding long-term performance-based logistics agreements and component-level specialists competing on turnaround velocity. Three archetypes dominate: engine OEMs with captive diagnostic networks, airframe specialists with structural life-extension expertise, and diversified defense primes with integrated platform sustainment capabilities. Competitive dynamics center on M&A activity consolidating component-level capabilities and strategic partnerships securing alloy supply chain access.
Within the engine OEM tier, GE Aviation and Rolls-Royce Holdings plc exemplify channel-controlling archetypes through sensor-to-analytics pipeline ownership. BAE Systems plc occupies a specialist position exemplifying deep technical concentration in combat aircraft structural programs. These three entities anchor the competitive landscape through differentiated control over diagnostic algorithms, hot-section component designs, and fatigue-critical engineering data that shapes procurement specifications across allied defense agencies.
| Leading Market Players |
|---|
| BAE Systems plc |
| GE Aviation |
| Lockheed Martin Corporation |
| Rolls-Royce Holdings plc |
| SAFRAN SA |
| RTX Corporation |
| Airbus SE |
| MTU Aero Engines AG |
| Northrop Grumman Corporation |
| Others |
Pricing and Supply Chain Analysis
Depot capacity utilization rates at Oklahoma City and Warner Robins Air Logistics Complexes sit above 85%, compressing turnaround timelines and emboldening original equipment manufacturers to push through cost-plus escalation clauses tied to labor-hour indices and specialty alloy price baskets.
Pricing Analysis
Cost-plus contracts with Producer Price Index escalation dominate engine overhaul agreements, with Pratt & Whitney and GE Aviation embedding titanium and nickel superalloy price adjusters that pass raw material volatility directly to defense agencies. Price differentiation rests on security clearance tier and proprietary technical data access, with cleared personnel commanding 40-60% labor premiums over commercial equivalents. Cost compression in component-level refurbishment is intensifying because third-party providers are undercutting OEM turnaround quotes by 15-25% on non-proprietary subsystems. Third-party component specialists exhibit highest price sensitivity due to thin margin pools and tooling amortization pressures, while prime contractors holding performance-based logistics agreements demonstrate lowest sensitivity through availability-guarantee fee structures.
Supply Chain Analysis
Upstream nickel-based superalloy and titanium forging feedstock anchors in United States, United Kingdom, and Russia, with ATI and Carpenter Technology controlling premium aerospace-grade material certification. Hot-section turbine blades, combustor liners, and single-crystal castings draw from this concentrated metallurgical base. Single-source vulnerability runs through Russian titanium sponge supply, now disrupted by cross-border sanctions that force substitution toward Japanese and Chinese feedstock with longer qualification timelines. Distribution runs through Pentagon-managed Defense Logistics Agency channels for organic depot networks, while contractor facilities receive direct mill shipments under long-term alloy offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military aviation MRO is approaching a platform-economics inflection where predictive maintenance algorithms and digital twin infrastructure create winner-take-most dynamics, with F-35's ALIS and ODIN ecosystems demonstrating how proprietary data architectures lock out non-integrated competitors.
For Market Incumbents: Entrench diagnostic algorithm control through exclusive sensor-to-analytics pipelines that fragment competitor access to engine health data. Lock in structural life-extension engineering capabilities for aging fighter fleets where original technical data has dissolved, creating irreplaceable intellectual property moats. Vertical integration into nickel-based superalloy recycling addresses raw material bottleneck threats from United States and United Kingdom supplier concentration. For New Entrants and Emerging Players: Pursue unmanned combat aerial vehicle low-observable material repair capabilities, where fleet expansion outpaces dedicated MRO infrastructure development by three to five years. Target forward-operating location rapid-response contracts that demand security-cleared personnel but lower capital barriers than depot-level engine services. Go-to-market leverage rests on partnering with defense primes as subcontracted specialty providers rather than competing head-to-head for platform sustainment agreements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among engine OEMs holding performance-based logistics contracts with decade-long availability guarantees, compared to transactional component overhauls with lumpy demand patterns. Long-term viability favors providers controlling proprietary diagnostic algorithms and cleared engineering workforces that cannot be replicated through capital deployment alone. Watch for EU AI Act autonomous diagnostic certification approvals as the signal indicating which predictive maintenance platforms will capture European air force procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | GE Aviation and Rolls-Royce leverage physics-based models to displace calendar-driven teardown protocols across NATO fighter fleets. |
| Performance-Based Logistics Conversion | Pratt & Whitney's powerplant availability guarantees replace transactional spare-part procurement in Pentagon sustainment frameworks. |
| EU AI Act Certification Pathway | Autonomous diagnostic algorithm approval creates first-mover advantage for predictive analytics vendors in European air force procurement. |
| Specialty Alloy Supply Security | Backward integration into nickel-based superalloy recycling mitigates raw material bottleneck exposure from United States and United Kingdom concentration. |
| Unmanned Aerial Vehicle MRO Buildout | Dedicated low-observable material repair capabilities capture white-space demand from expanding drone fleet operating tempos. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with depot maintenance officers, engine OEM aftermarket directors, defense procurement officials, and third-party MRO facility managers; and secondary validation through FAA military airworthiness directive filings, Pentagon budget justification documents, EASA military certification branch guidance, and EU AI Act regulatory texts. Bottom-up triangulation across service type, aircraft platform, and provider type segmentation combined with top-down demand validation against national defense expenditure patterns.
Forecast inputs span engine operating tempo projections, fleet modernization program timelines, and regulatory compliance cost escalations across the analysis window. Segmentation dimensions modeled include service modality, aircraft type, provider organizational form, and maintenance technical depth, with additional weighting for sovereign maintenance mandate proliferation. CAGRs derive from fitted trend analysis against historical depot throughput data and projected platform sustainment contract awards. Industry-specific inputs incorporate fighter flight-hour accumulation rates and predictive maintenance platform adoption curves.
Sensitivities concentrate around alloy supply disruption scenarios, cross-border technical data-sharing restriction intensification, and autonomous diagnostic algorithm regulatory approval timeline slippage. Cross-checking against Pentagon depot maintenance expenditure actuals and national military airworthiness authority certification databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Southeast Asia Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Refurbishing Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
North America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market