
 Airline Maintenance Software Market | 2026-2036
Airline Maintenance Software Market Size, Share, and Industry Trends Forecast 2026-2036
Airline Maintenance Software Market Insights
Modular solution bundling is recalibrating how Maintenance Repair Organizations evaluate vendor proposals, shifting procurement from standalone modules toward integrated platforms. IFS AB leverages its aerospace heritage to anchor enterprise-scale deployments across European flag carriers. Ramco Systems Limited competes through aviation-specific configurability, while SAP SE extends its dominance by embedding maintenance workflows within broader enterprise resource planning ecosystems.
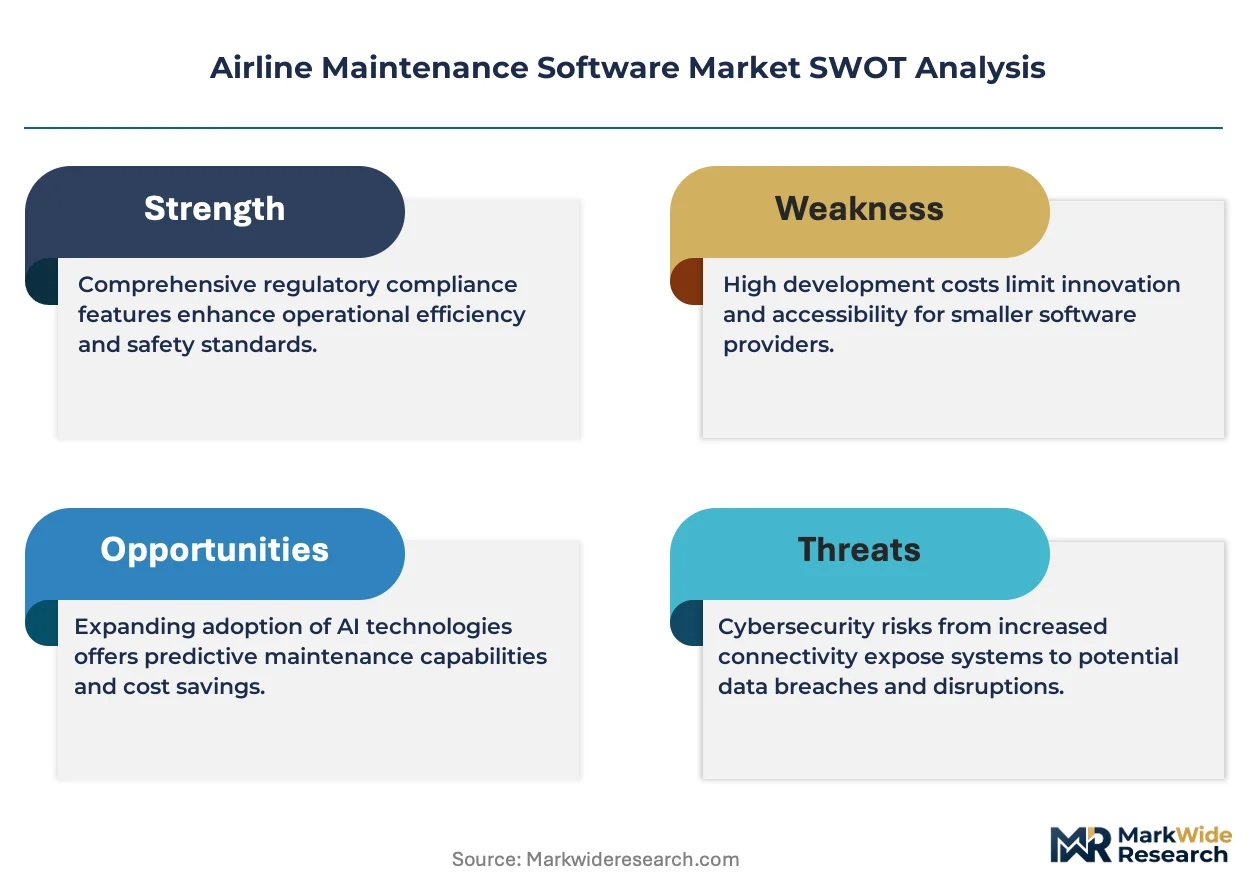
Airline maintenance software comprises specialized information systems that manage aircraft airworthiness records, maintenance scheduling, and component traceability through centralized digital platforms. These systems typically integrate with ATA chapter coding structures and MSG-3 methodology to ensure regulatory compliance and operational continuity. Cloud-based deployment is capturing accelerated interest as operators seek elastic infrastructure for distributed fleet operations, while predictive maintenance solutions command premium positioning due to their direct impact on aircraft availability metrics. Work order management retains stable share as the foundational layer across all operator tiers, though margin pools increasingly concentrate in compliance management modules where regulatory complexity creates vendor stickiness.
FAA airworthiness directives and EASA Part-M requirements shape product development roadmaps, with both agencies mandating enhanced digital record retention and audit trail capabilities. ISO 27001 and SOC 2 frameworks further govern vendor qualification for cloud-hosted deployments, effectively filtering market access for smaller providers. Stakeholders must monitor evolving cybersecurity mandates from aviation regulators, as supply chain digitization expands attack surfaces across interconnected maintenance networks.
Market Dynamics
Fleet-wide predictive maintenance mandates are compressing procurement cycles as full-service carriers replace legacy point solutions with integrated platforms. The FAA's updated airworthiness directive automation requirements are forcing operators to accelerate software refresh timelines beyond traditional five-year cycles.
Growth Catalysts
- FAA Airworthiness Directive Automation:The FAA's 2024 directive requiring automated compliance tracking has triggered immediate procurement of integrated maintenance platforms across Part 121 operators.
- Cloud Migration:Elastic infrastructure demand from distributed fleet operations is pulling operators toward SaaS-based maintenance systems with real-time component traceability.
- MSG-3 Methodology Standardization:Universal adoption of MSG-3 decision logic across maintenance programs is creating vendor stickiness for platforms with native ATA chapter integration.
Market Restraints
- Legacy System Integration Costs:Proprietary data formats in installed base systems impose heavy migration expenses that freeze mid-tier operator upgrade decisions.
- Vendor Concentration Risk:Enterprise-scale deployments cluster among three dominant platform providers, creating single-source dependency for critical airworthiness functions.
- Cybersecurity Certification Friction:ISO 27001 and SOC 2 compliance timelines extend vendor qualification cycles by 8-14 months, filtering market access.
Strategic Opportunities
- Narrow-Body Fleet Digitization:Low-cost carriers operating aging narrow-body fleets represent underserved demand for modular, non-enterprise maintenance solutions.
- Blockchain Component Traceability:Convergence of distributed ledger technology with existing maintenance platforms enables immutable part history records for resale value protection.
- EASA Part-M Harmonization:Alignment between FAA and EASA digital record standards creates dual-certification efficiency for vendors serving transatlantic operators.
Industry Challenges
- Aviation Software Engineering Talent Scarcity:Specialized expertise in ATA chapter coding and airworthiness logic sits concentrated among aging practitioner pools with limited pipeline replenishment.
- Multi-Platform Data Synchronization:Operators running mixed fleets face complex harmonization requirements when integrating OEM-specific maintenance data feeds into unified systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airline Maintenance Software Market |
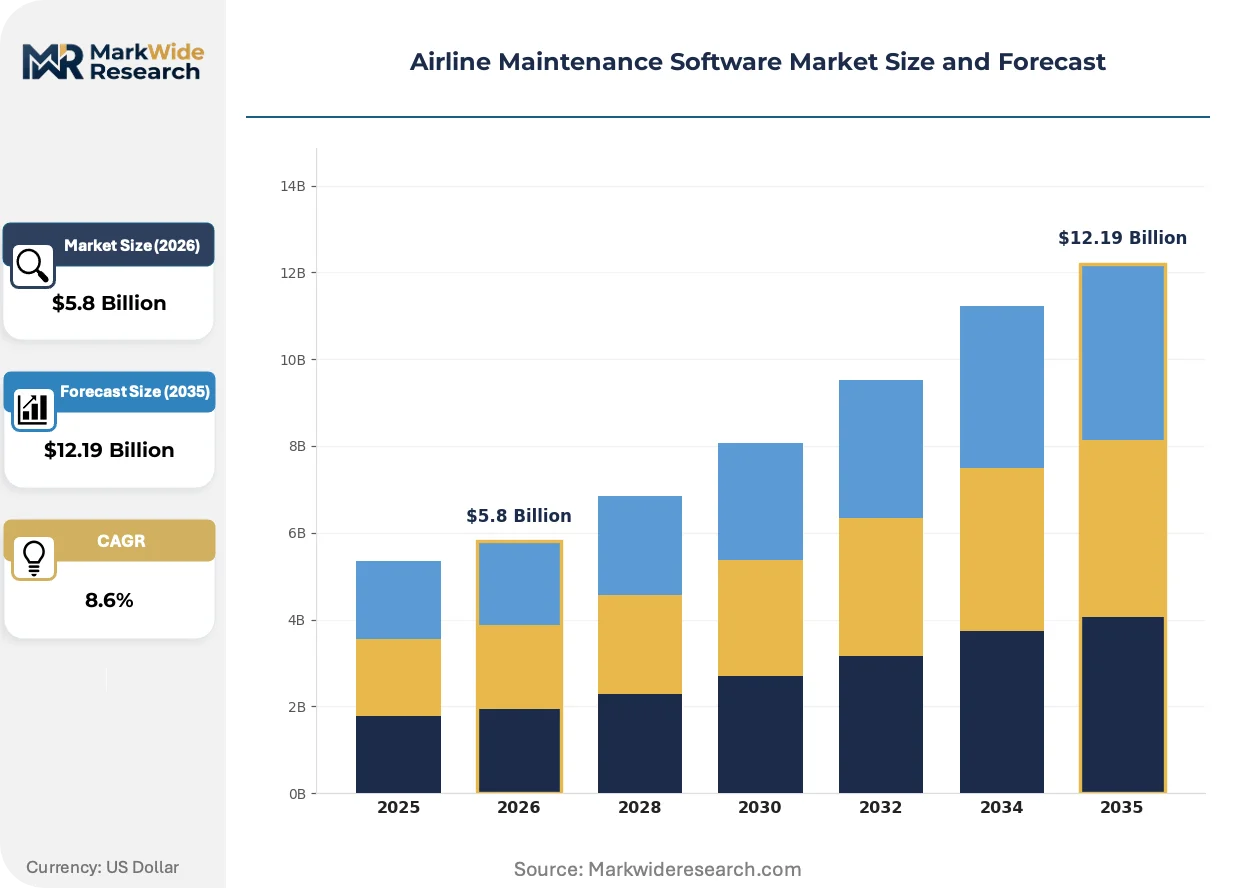
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Hosted, Edge Computing Solution Type: Predictive Maintenance, Asset Tracking, Inventory Management, Compliance Management, Work Order Management Application: Aircraft Maintenance Scheduling, Engine Health Monitoring, Parts Lifecycle Management, Maintenance Reporting, Quality Assurance End User: Airlines, Maintenance Repair Organizations, Airports, Aircraft Manufacturers, Leasing Companies |
| Companies Covered | IFS AB, Ramco Systems Limited, Swiss AviationSoftware Ltd., Ultramain Systems, Inc., Rusada, CAMP Systems International Inc., AeroSoft Systems Inc., Mxi Technologies, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airline Maintenance Software Market Trends and Innovations
Digital twin technology is reshaping how maintenance programs simulate component degradation before physical inspection. The convergence of sensor telemetry with artificial intelligence is compressing the gap between predictive alerts and actual failure events.
Digital twin architectures are expanding into engine health monitoring and landing gear fatigue analysis. Regional carriers and cargo operators are adopting these systems faster than expected, driven by insurance premium incentives for predictive maintenance documentation. The technology is expanding into line maintenance operations, compressing turnaround times by pre-positioning replacement components before aircraft arrival.
EASA's Part-M amendment requiring enhanced audit trail capabilities is mandating blockchain-verified maintenance records for all commercial operators above 5,700kg maximum takeoff weight. The regulation forces legacy system upgrades or complete replacement across European flag carriers and wet-lease operators. Narrow-body fleets with high cycle counts face the steepest compliance costs, accelerating consolidation toward integrated platform vendors with native compliance modules.
Outcome-based maintenance contracts are displacing traditional time-and-material service agreements among major leasing companies. Lessors now demand guaranteed availability metrics tied to software-enabled predictive intervention, shifting vendor compensation from license fees to performance guarantees. This restructuring is most visible in Ireland and Singapore, where aircraft lessor concentration drives contract innovation that subsequently diffuses to operator procurement templates.
Airline Maintenance Software Market Segmentation
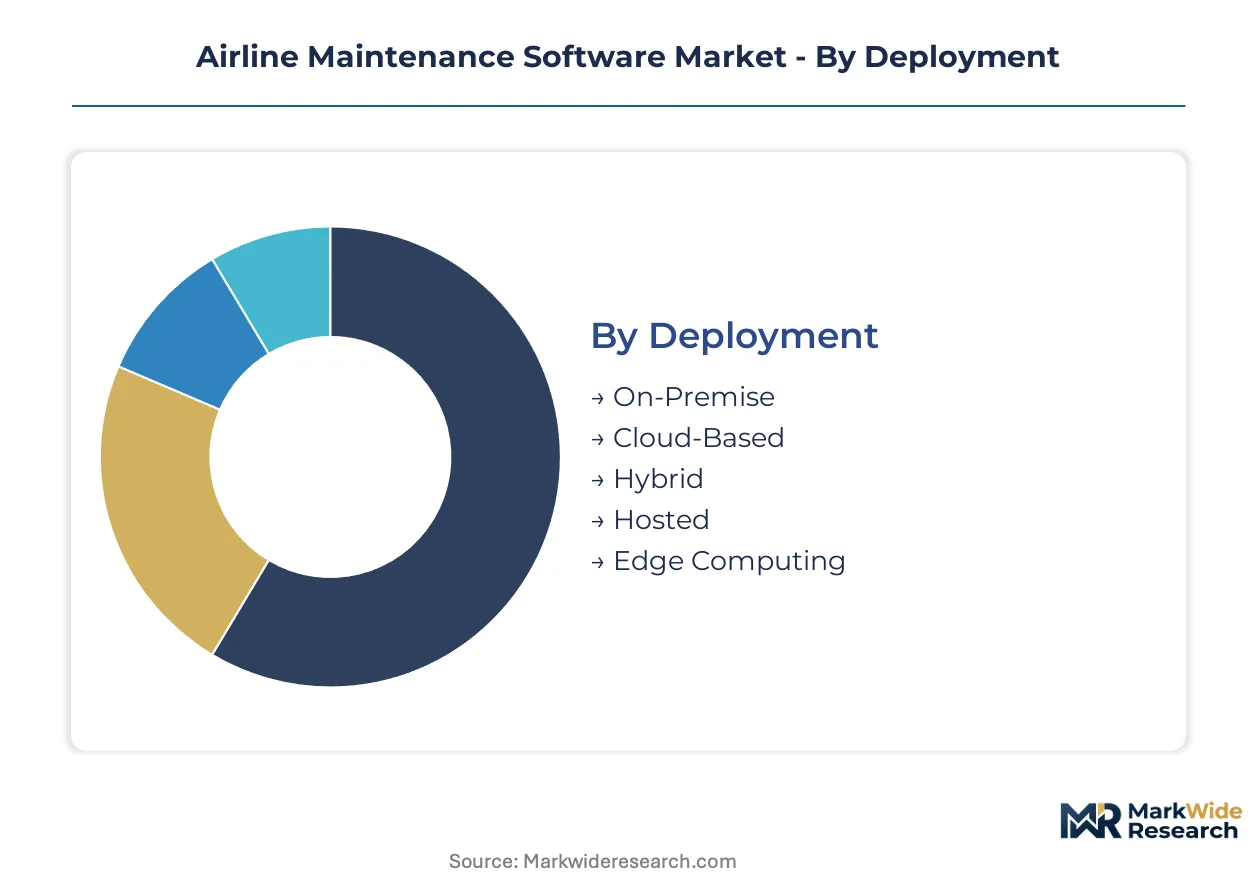
Segmentation in airline maintenance software reveals how procurement priorities diverge between legacy operators seeking incremental upgrades and digital-native carriers demanding elastic infrastructure. Each dimension—deployment architecture, solution functionality, operational application, and end-user category—carries distinct vendor qualification requirements and margin structures.
Deployment:
Customization intensity varies sharply across this category, from rigid on-premise installations to configurable cloud-native environments.
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic compute for distributed fleet operations. Demand concentrates among United States-based Part 121 operators responding to FAA airworthiness directive automation mandates, with procurement cycles compressing below traditional five-year refresh timelines.
- On-Premise:Dedicated infrastructure within operator data centers maintains air-gapped security for classified military conversions and sensitive cargo operations. European flag carriers with legacy ERP investments favor this model for controlled integration with existing financial systems.
- Hybrid:Split workloads between local processing and cloud burst capacity accommodate regulatory data residency requirements.
- Hosted:Single-tenant managed deployments reduce capital expenditure while preserving configuration autonomy.
- Edge Computing:On-aircraft processing units enable real-time anomaly detection without satellite connectivity dependency.
Leading the category by volume: Cloud-Based. Expanding most quickly: Edge Computing.
Solution Type:
Cost tier stratification separates enterprise platforms with integrated modules from point solutions targeting specific compliance gaps.
- Predictive Maintenance:Machine learning models ingest sensor telemetry to forecast component degradation before failure thresholds. Full-service carriers in Germany and Singapore deploy these systems fleet-wide, driven by insurance premium incentives for documented intervention protocols.
- Compliance Management:Automated audit trails and regulatory submission workflows address EASA Part-M and FAA directive requirements. Narrow-body operators face the steepest compliance costs, accelerating consolidation toward vendors with native certification modules.
- Work Order Management:Core scheduling and resource allocation functions remain foundational across all operator tiers.
- Asset Tracking:Real-time location systems monitor high-value rotable components through maintenance facilities.
- Inventory Management:Automated reorder points and shelf-life monitoring reduce aircraft-on-ground incidents from parts unavailability.
Commanding highest margins: Compliance Management. Steepest expansion trajectory: Predictive Maintenance.
Application:
Volume concentration follows aircraft utilization intensity, with high-cycle operations demanding more sophisticated monitoring capabilities.
- Engine Health Monitoring:Continuous vibration analysis and oil debris detection extend time-between-overhaul intervals. Low-cost carriers operating aging narrow-body fleets in India and Indonesia represent underserved demand for modular, non-enterprise implementations of this capability.
- Aircraft Maintenance Scheduling:Optimized hangar slot allocation and manpower routing minimize downtime during C-check intervals. United States legacy carriers with mixed fleet types prioritize this application for harmonizing OEM-specific maintenance data feeds.
- Parts Lifecycle Management:Component traceability from installation through repair and resale protects asset residual values.
- Maintenance Reporting:Standardized documentation for regulatory submissions and internal performance metrics.
- Quality Assurance:Non-conformance tracking and corrective action verification ensure continuous airworthiness.
Most mature penetration: Aircraft Maintenance Scheduling. Gaining share fastest: Engine Health Monitoring.
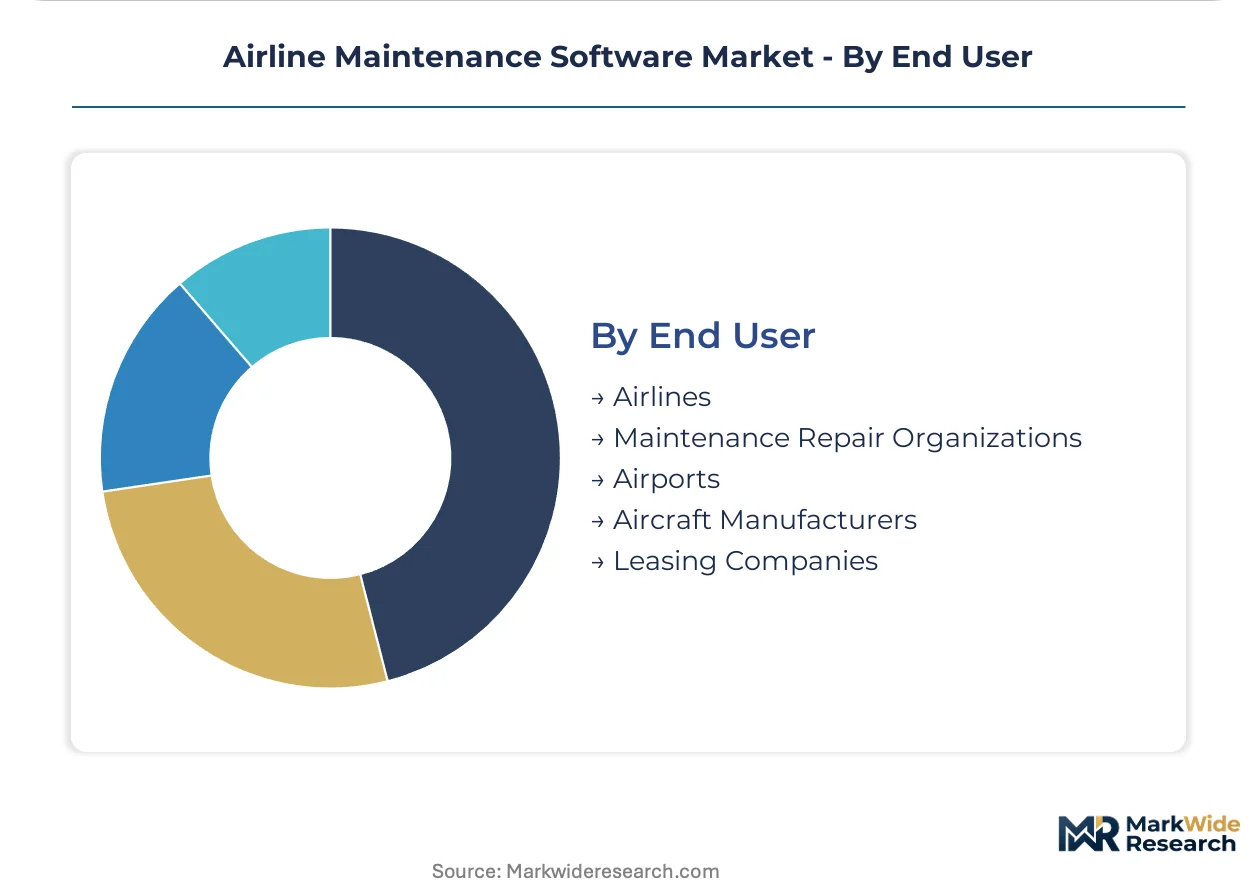
End User:
Customer type determines contract structure, from perpetual licenses for capital-constrained operators to outcome-based agreements with performance guarantees.
- Airlines:Fleet operators require integrated platforms spanning line maintenance through heavy checks. Full-service carriers in France and Japan are expanding digital adoption for predictive programs, replacing legacy point solutions with unified systems.
- Leasing Companies:Asset owners demand guaranteed availability metrics tied to software-enabled intervention. Ireland and Singapore-based lessors drive contract innovation that diffuses to operator procurement templates worldwide.
- Maintenance Repair Organizations:Third-party providers seek modular solutions for multi-client contract flexibility.
- Airports:Ground handling integration and gate allocation optimization for turnaround efficiency.
- Aircraft Manufacturers:OEMs embed maintenance logic into delivered aircraft digital ecosystems.
Driving procurement volume: Airlines. Restructuring contract terms most aggressively: Leasing Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise software parks in Bangalore and Hyderabad concentrate development capacity for aviation-specific modules, drawing engineering talent from maintenance repair organizations seeking digital transformation partnerships.
United States
Legacy fleet modernization across Part 121 operators drives sustained procurement momentum for integrated maintenance platforms. FAA airworthiness directive automation requirements compress software refresh timelines below traditional five-year cycles. Dallas-Fort Worth and Seattle-Tacoma anchor the densest concentrations of airline IT procurement decision-makers.
Germany
Full-service carriers expand predictive maintenance programs fleet-wide, supported by insurance premium incentives for documented intervention protocols. EASA Part-M harmonization with FAA standards enables dual-certification efficiency for vendors serving transatlantic routes. Hamburg and Munich host specialized aviation software engineering clusters serving Lufthansa Group operators.
Singapore
Aircraft lessor concentration in Ireland and Singapore drives outcome-based contract innovation that diffuses to operator procurement templates worldwide. The Civil Aviation Authority of Singapore mandates enhanced digital record retention for wet-lease operators above 5,700kg maximum takeoff weight. Changi Aviation Park clusters lessor technical management teams demanding guaranteed availability metrics.
India
Low-cost carriers operating aging narrow-body fleets represent underserved demand for modular, non-enterprise maintenance solutions. The Directorate General of Civil Aviation pushes digitization timelines for regional operators through revised airworthiness surveillance protocols. Bangalore and Hyderabad software development centers export aviation-specific configurability to Middle Eastern and Southeast Asian carriers.
United Kingdom
Maintenance repair organizations evaluate vendor proposals through modular solution bundling, shifting procurement from standalone modules toward integrated platforms. The UK Civil Aviation Authority aligns with EASA Part-M amendments requiring blockchain-verified maintenance records. London Heathrow and Manchester anchor MRO procurement decision-making for European flag carrier technical operations.
Airline Maintenance Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment architecture and solution functionality tiers. Enterprise resource planning ecosystems embed maintenance workflows within broader financial and supply chain systems, while aviation-native platforms emphasize ATA chapter coding structures and MSG-3 methodology compliance. Three strategic archetypes dominate: aerospace heritage specialists, configurable modular providers, and enterprise software conglomerates with aviation verticals. Competitive moves concentrate on strategic partnerships for sensor telemetry integration and geographic expansion through lessor relationship networks.
Among European aerospace heritage specialists, IFS AB anchors enterprise-scale deployments with native fleet management integration, while Swiss AviationSoftware Ltd. occupies a position within the compliance management tier emphasizing EASA Part-M certification efficiency. SAP SE represents the diversified conglomerate archetype, embedding maintenance logic within broader enterprise resource planning ecosystems that appeal to operators with existing financial system investments. These three exemplify how vendor positioning stratifies between aviation-native depth and cross-industrial scale.
| Leading Market Players |
|---|
| IFS AB |
| Ramco Systems Limited |
| Swiss AviationSoftware Ltd. |
| Ultramain Systems, Inc. |
| Rusada |
| CAMP Systems International Inc. |
| AeroSoft Systems Inc. |
| Mxi Technologies |
| SAP SE |
| Others |
Pricing and Supply Chain Analysis
EASA's blockchain-verified maintenance record mandate gates qualified supply and premium-tier pricing access, as compliance certification costs filter vendor participation and stratify contract values across European flag carriers and wet-lease operators.
Pricing Analysis
Margin tightening in cloud-native tiers reflects ISO 27001 and SOC 2 certification timelines that extend vendor qualification cycles. Three-tier pricing structure across enterprise, mid-market, and modular levels separates perpetual license operators from SaaS subscribers and point-solution buyers. Cost-down pressure on on-premise deployments accelerates because legacy system integration expenses freeze mid-tier upgrade decisions. Low-cost carriers in India and Indonesia exhibit highest price sensitivity, while full-service carriers in Germany and Singapore absorb premiums for predictive maintenance documentation.
Supply Chain Analysis
Refurbishment flows for rotable components create secondary value streams that compress new module pricing. Software engineering talent concentrates in India, Germany, and the United States, with Bangalore and Hyderabad anchoring development capacity for aviation-specific configurability. Raw material dependencies include sensor telemetry hardware, cloud compute infrastructure, and specialized ATA chapter coding expertise. Single-source vulnerability sits with three dominant platform providers controlling enterprise-scale deployments. Distribution runs through direct vendor-operator relationships and lessor technical management networks in Ireland and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based predictive maintenance platforms are displacing legacy point solutions across Part 121 operators, compressing procurement cycles below traditional refresh timelines.
For Market Incumbents: Cement market position through native MSG-3 methodology integration and EASA-FAA dual-certification efficiency. Deepen backward integration into sensor telemetry partnerships to defend against modular specialists. Prioritize compliance management module stickiness as regulatory complexity creates switching costs for European flag carriers. For New Entrants and Emerging Players: Begin with narrow-body fleet digitization in India and Southeast Asia, where aging aircraft and underserved low-cost carriers seek non-enterprise solutions. Target modular work order management for regional operators facing DGCA digitization mandates. Lead with aviation-specific configurability rather than horizontal ERP extension. For Investors and Strategic Acquirers: Outcome-based contract adoption by Ireland and Singapore-based lessors is the leading indicator that performance-guarantee compensation structures will diffuse to operator procurement templates. Acquire aviation-native platforms with ATA chapter depth over horizontal software conglomerates. Monitor FAA airworthiness directive automation procurement velocity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies line maintenance through heavy check workflows for full-service carriers replacing point solutions. |
| Strategic Partnership | Sensor telemetry alliances with engine OEMs compress predictive alert-to-failure gaps for fleet operators. |
| Acquisition of Specialist Firm | Aviation-native configurability from regional developers extends reach into narrow-body digitization demand. |
| Geographic Expansion | Lesser technical management presence in Ireland and Singapore captures outcome-based contract innovation. |
| Product Launch | Edge computing modules enable real-time anomaly detection without satellite dependency for cargo operators. |
Research Methodology
Independent corroboration across airline IT procurement officers, MRO technical directors, lessor asset managers, and aviation software engineers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from FAA airworthiness directive filings, EASA Part-M amendment records, and operator capital expenditure disclosures anchors supply-side assessment. Bottom-up triangulation across deployment architecture segments and top-down reconciliation against fleet modernization announcements ensures dimensional consistency.
Comparable-period anchoring to legacy system refresh cycles and predictive maintenance adoption curves shaped the projection horizon. The analytical framework models deployment mode, solution functionality tier, aircraft application type, and end-user category throughout the forecast period. CAGRs derive from elasticity-adjusted replacement demand and regulatory mandate acceleration curves, with fleet age distributions and insurance premium incentive diffusion serving as aviation-specific inputs.
Underlying measurement precision varies by segment; cloud-based deployment and predictive maintenance solution forecasts carry tighter precision than on-premise legacy integration projections. Forecasts reflect assumptions about regulatory harmonization timelines and cybersecurity certification friction that could revise trajectories if FAA-EASA alignment stalls or ISO 27001 timelines extend. Practitioners should monitor Part 121 operator procurement velocity and lessor contract template diffusion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Aircraft Storage, Preservation and Reactivation Services Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Cloud MRO Software Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market
Aircraft Maintenance and MRO Solutions
Digital Aerospace MRO Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Washing Systems Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Global Degaussing System Market
Aircraft Maintenance and MRO Solutions
Narrowbody Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Exterior Strip and Repaint Services Market