
 Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market | 2026-2036
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market Insights
The commercial aircraft MRO sector is restructuring around a widening capability gap between premium engine overhaul and commodity line maintenance. Lufthansa Technik anchors the high-value engine segment through captive OEM partnerships. AAR Corp competes aggressively in component repair via distributed third-party service centers. ST Engineering dominates the Asia-Pacific hangar network through integrated base maintenance operations.
Commercial aircraft maintenance, repair, and overhaul encompasses scheduled inspection, defect rectification, and restoration of airworthiness for turbine-powered fixed-wing aircraft, typically requiring cycle-limited component tracking and non-destructive testing protocols to preserve flight safety margins and dispatch reliability. Engine overhaul commands the deepest margin pool among service types due to specialized tooling and proprietary technical data. Independent MRO providers now lead capacity expansion for narrow-body fleets, while OEM-affiliated facilities retain structural repair advantages through original design authority. Airlines remain the largest end-user category, though leasing companies increasingly specify maintenance reserves and redelivery conditions.
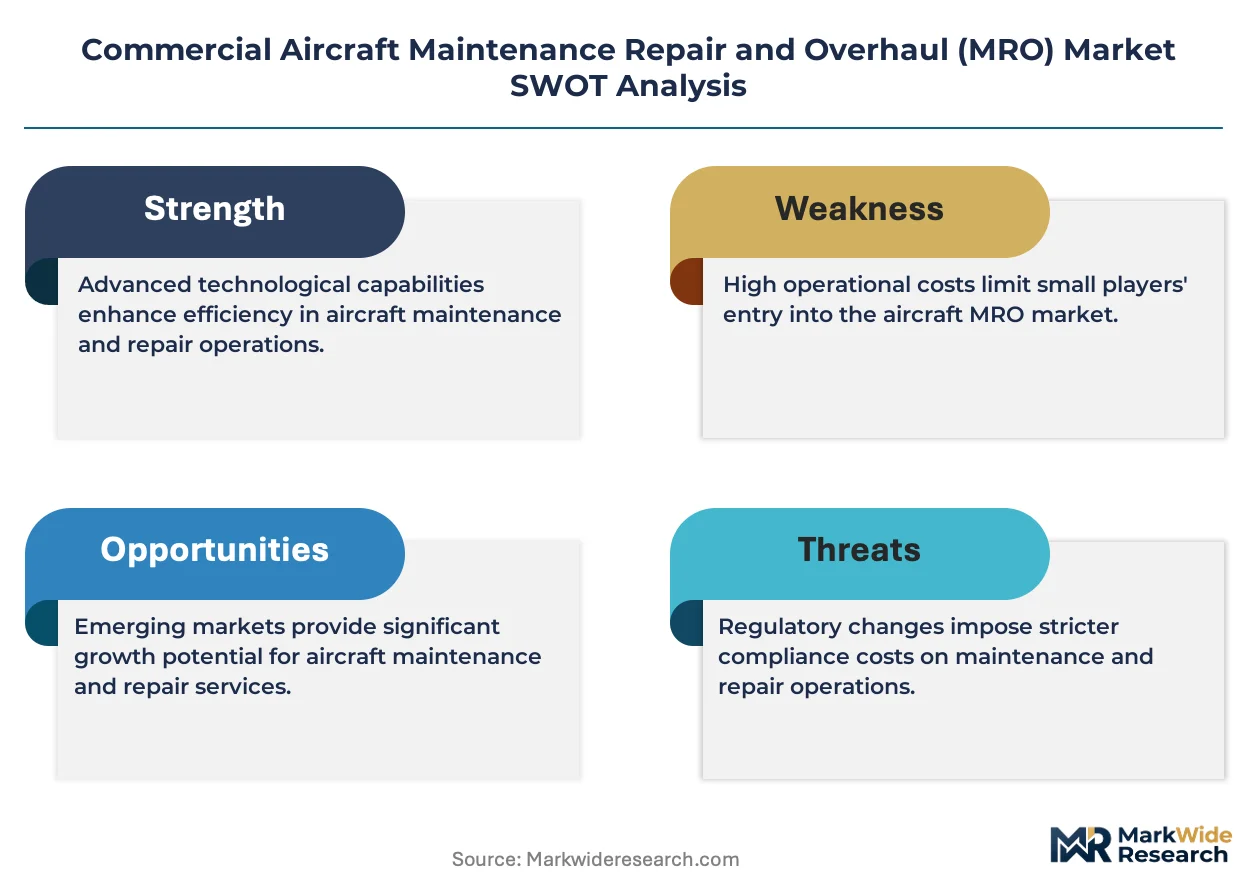
FAA airworthiness directives and EASA Part-M maintenance program requirements shape inspection intervals and documentation standards across all facility types. The EU Green Deal's sustainable aviation fuel mandates and emerging carbon accounting rules will alter engine performance benchmarking and residue testing protocols. Stakeholders must weigh regulatory compliance costs against fleet age profiles when selecting between in-house hangars and outsourced third-party arrangements.
Market Dynamics
The commercial aircraft MRO sector is bifurcating around engine overhaul complexity, where proprietary OEM technical data creates captive supply chains for high-thrust turbofan servicing while commodity line maintenance faces price compression from independent facility expansion.
Growth Catalysts
- FAA Aging Aircraft Directives:Mandatory structural inspection intervals for fuselage fatigue are extending heavy check dwell times and increasing component replacement rates across narrow-body and wide-body fleets.
- Sustainable Aviation Fuel Mandates:The EU Green Deal's carbon accounting rules are forcing residue testing protocol upgrades that favor MRO providers with integrated engine performance analytics capabilities.
- Southeast Asian Fleet Renewal:Low-cost carrier expansion in Indonesia, Vietnam, and the Philippines is compressing maintenance cycles and accelerating demand for quick-turnaround line maintenance stations.
Market Restraints
- Titanium and Superalloy Input Volatility:Specialized aerospace-grade material pricing swings directly compress margin pools for component repair shops lacking long-term OEM purchasing agreements.
- OEM Technical Data Concentration:Pratt & Whitney, GE Aerospace, and Rolls-Royce restrict proprietary engine manuals and diagnostic software, structurally limiting independent MRO capability depth.
- REACH Chemical Restrictions:ECHA substance authorization requirements are eliminating chromate-based corrosion inhibitors and cadmium plating processes, forcing capital-intensive process requalification.
Strategic Opportunities
- India MRO Infrastructure Gap:The country's PLI scheme for aerospace manufacturing is creating parallel demand for indigenous heavy maintenance hangars at Bengaluru and Hyderabad airport zones.
- Predictive Maintenance Convergence:Edge computing and vibration sensor fusion are enabling condition-based engine monitoring that shifts revenue models from scheduled overhauls to flight-hour-based contracts.
- Leasing Company Redelivery Specifications:Aircraft lessors are tightening maintenance reserve clauses and end-of-lease inspection standards, creating specialized technical consulting demand.
Industry Challenges
- Certified AMT Pipeline Shortage:FAA Airframe and Powerplant mechanic graduation rates lag fleet expansion, particularly for non-destructive testing and composite repair specializations.
- Dual Certification Timeline Compression:Simultaneous FAA and EASA approval requirements for cross-border MRO operations are extending facility qualification periods and deferring revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market |
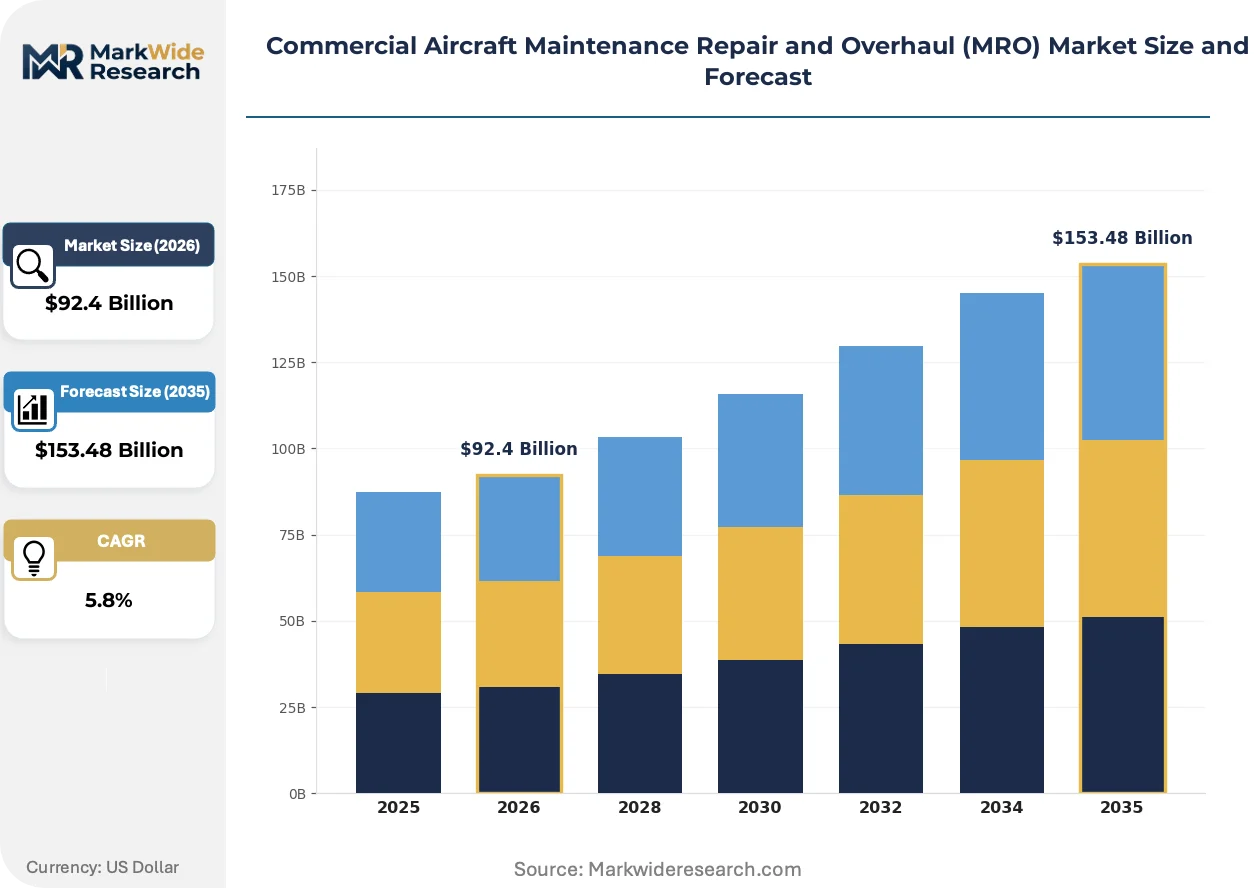
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $153.48 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Line Maintenance, Base Maintenance, Component Maintenance, Engine Overhaul, Avionics Repair, Structural Repair Application: Passenger Planes, Cargo Aircraft, Business Jets, Military Transports, Regional Aircraft, Helicopters Facility Type: Independent MRO Providers, OEM-Affiliated Facilities, Airline-Owned Hangars, Third-Party Service Centers End User: Airlines, Leasing Companies, Charter Operators, Aircraft Manufacturers, Government Agencies |
| Companies Covered | Lufthansa Technik, AAR Corp, GE Aviation, Delta TechOps, ST Engineering, Airbus SE, Rolls-Royce, Pratt & Whitney, SAFRAN Aircraft Engines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market Trends and Innovations
Digital thread technologies and sustainable process chemistry are actively restructuring how maintenance programs are authorized, executed, and documented across the commercial aviation aftermarket.
Automated borescope inspection systems equipped with machine learning defect classification are absorbing routine turbine blade assessment tasks previously requiring human technician interpretation. Full-service MRO networks in Singapore and Dubai are deploying these systems at engine reception docks to compress preliminary damage mapping from days to hours. The technology is absorbing lower-skill visual inspection labor while elevating demand for AI-augmented diagnostic engineers.
EASA Part-M maintenance program amendments now mandate electronic continuing airworthiness record exchange between operators, MRO providers, and national aviation authorities. This regulatory shift is eliminating paper logbook retention and forcing legacy facility management system upgrades. Component repair stations in Germany and France are most affected, with compliance deadlines driving consolidated software procurement across multi-site operations.
Airline technical procurement departments are unbundling heavy maintenance packages into discrete engine, airframe, and component work scopes awarded to specialized providers. This behavioral shift is fragmenting previously consolidated single-source contracts and elevating third-party logistics coordination requirements. The pattern is most visible among European network carriers restructuring post-pandemic cost bases, with Lufthansa and Air France-KLM leading modular sourcing adoption.
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market Segmentation
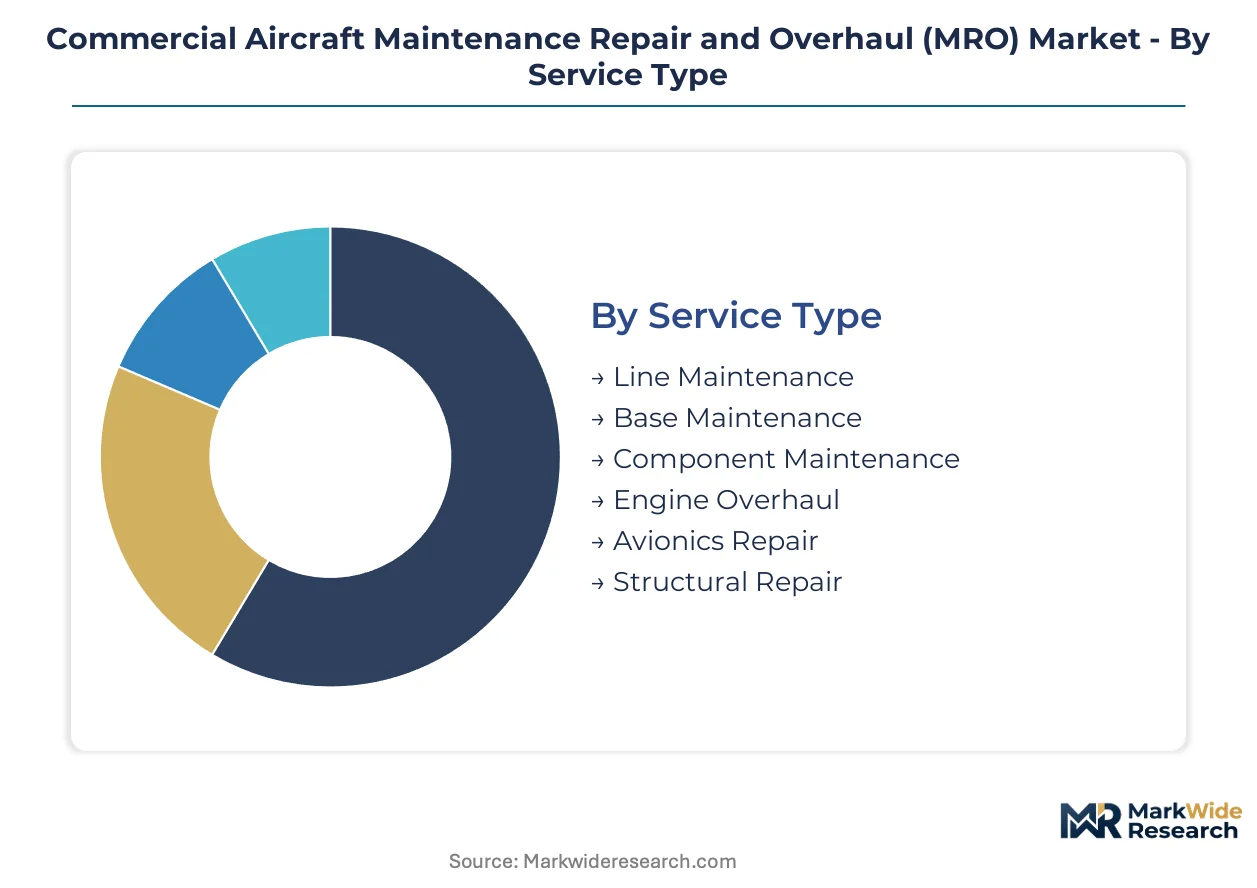
The commercial aircraft MRO market segments across technical complexity tiers, operational deployment modes, and ownership structures. Each axis reveals distinct margin profiles, capability requirements, and competitive dynamics that shape provider positioning and investment allocation.
Service Type:
Technical sophistication and proprietary data access define competitive moats across the service spectrum.
- Line Maintenance:Routine pre-flight and transit inspections performed at airport gates and remote stands. Demand concentrates at Jakarta, Manila, and Ho Chi Minh City hubs where low-cost carrier turnaround compression requires 24/7 rapid-response stations.
- Engine Overhaul:Complete disassembly, inspection, and reassembly of turbofan powerplants requiring specialized borescope equipment and proprietary OEM technical manuals. Singapore's Seletar aerospace cluster anchors regional capacity for high-thrust engine servicing, driven by FAA airworthiness directive compliance timelines.
- Base Maintenance:Heavy airframe checks involving structural inspection and system overhaul in dedicated hangar facilities.
- Component Maintenance:Repair and restoration of landing gear, actuators, and auxiliary power units.
- Avionics Repair:Troubleshooting and recertification of flight control computers and navigation systems.
- Structural Repair:Fuselage skin replacement, corrosion treatment, and composite panel restoration.
Mature deployment sits with Engine Overhaul. Newer deployment is concentrated in Line Maintenance.
Application:
Operational intensity and utilization patterns drive maintenance cycle frequency and contract structure.
- Passenger Planes:High-cycle narrow-body fleets operated by low-cost carriers generate the densest line maintenance demand. Indonesia's Lion Air and Vietnam's VietJet compress inspection intervals through intensive daily utilization.
- Cargo Aircraft:Freighter conversions and dedicated cargo fleets require specialized heavy check programs. Singapore's Changi cargo precinct and Leipzig's DHL hub anchor dedicated MRO capacity for overnight express operations.
- Business Jets:Fragmented ownership structures and dispersed home bases create mobile maintenance team demand.
- Military Transports:Government procurement cycles and security-cleared technician requirements structure contract awards.
- Regional Aircraft:Turboprop and small jet fleets serving thin routes drive component pooling arrangements.
- Helicopters:Offshore energy and emergency medical services dictate specialized rotor track and balance expertise.
Utilization intensity peaks with Passenger Planes. Contract complexity concentrates with Cargo Aircraft.
Facility Type:
Ownership structure determines access to proprietary technical data and capital investment scale.
- OEM-Affiliated Facilities:Boeing, Airbus, and engine manufacturer-owned service centers retain original design authority and exclusive technical documentation. These facilities command structural repair and modification work requiring engineering approval privileges.
- Independent MRO Providers:Third-party operators compete on cost and turnaround speed for commodity services. ST Engineering's Asia-Pacific hangar network demonstrates how independent scale can challenge OEM-affiliated positions in base maintenance.
- Airline-Owned Hangars:Captive maintenance operations at fortress hubs protect core fleet availability.
- Third-Party Service Centers:Specialized component shops and avionics repair stations serving multiple operator types.
Technical authority concentrates with OEM-Affiliated Facilities. Capacity expansion is accelerating fastest among Independent MRO Providers.
End User:
Procurement sophistication and contract duration vary sharply across buyer categories.
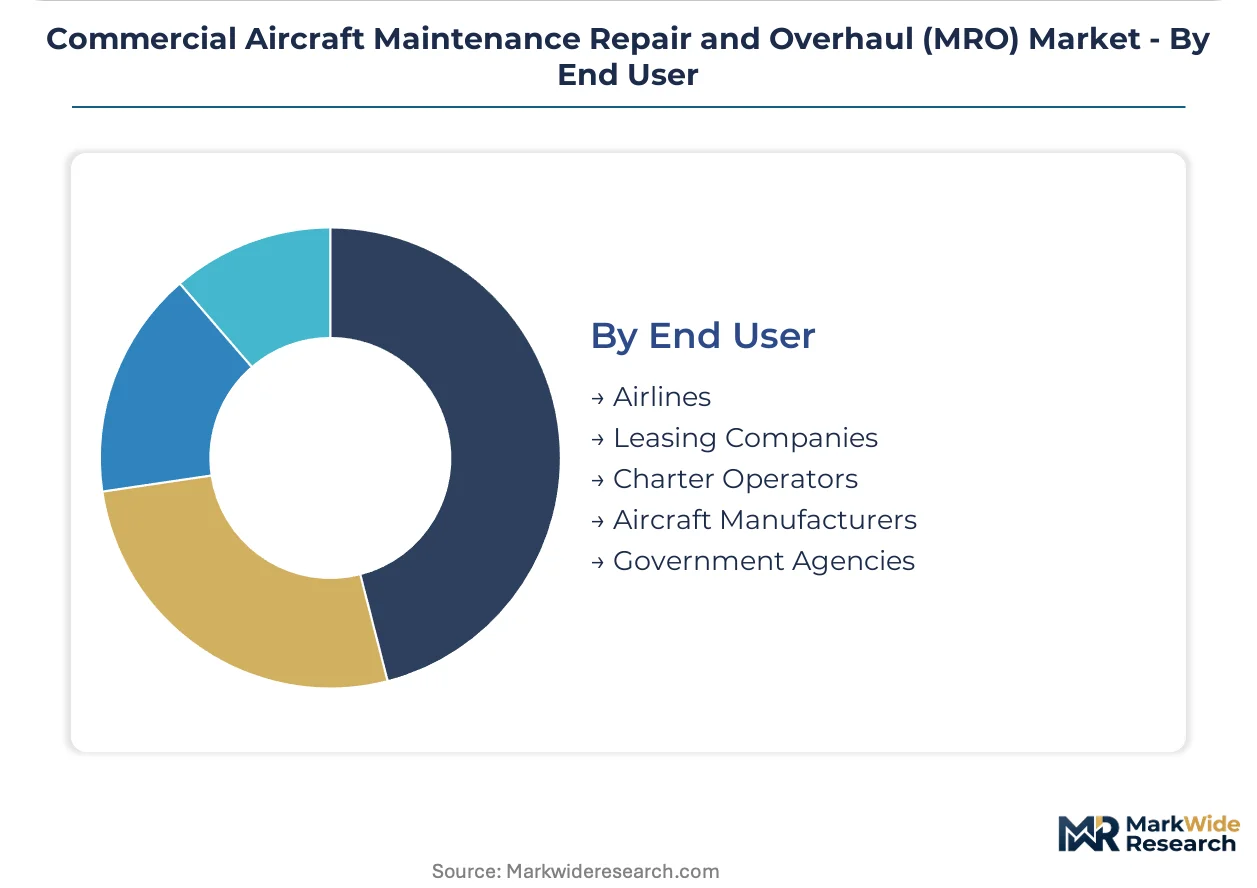
- Airlines:Full-service and low-cost carriers remain the largest demand source, with procurement departments unbundling heavy maintenance into discrete work scopes. European network carriers now modularize engine, airframe, and component awards across specialized providers.
- Leasing Companies:Aircraft lessors specify maintenance reserves and redelivery conditions that create specialized technical consulting demand. Dublin and Singapore lessor headquarters drive inspection standardization across global portfolios.
- Charter Operators:Ad-hoc scheduling and seasonal demand patterns favor flexible contract terms.
- Aircraft Manufacturers:Delivery support and warranty programs require transitional maintenance handoffs.
- Government Agencies:Military and coast guard fleets impose security clearance and sovereign capability requirements.
Contract volume anchors with Airlines. Specification tightening is advancing fastest among Leasing Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Seletar aerospace cluster anchors regional MRO capacity through integrated heavy maintenance hangars and engine overhaul facilities serving Southeast Asian fleet operators.
Singapore
Changi Airport's cargo precinct and Seletar Aerospace Park concentrate engine overhaul demand from low-cost carriers across Indonesia and Vietnam. The country's Economic Development Board incentivizes aerospace investments through tax concessions and skills training grants. ST Engineering operates integrated base maintenance facilities at Seletar, handling narrow-body heavy checks for regional airline clients.
United States
Domestic airline fleet density and aging aircraft populations drive structural inspection demand at Atlanta, Dallas-Fort Worth, and Miami maintenance hubs. FAA airworthiness directives on fuselage fatigue compel heavier check schedules for Boeing 737 and 757 fleets. Delta TechOps maintains captive overhaul capacity in Georgia, while independent providers expand component repair networks across the Southeast.
Germany
Lufthansa Technik anchors European engine overhaul capacity at Hamburg and Frankfurt facilities, serving Middle Eastern and Asian carrier contracts. EASA Part-M maintenance program amendments mandate electronic continuing airworthiness record exchange, forcing facility management system upgrades. Component repair stations in Bavaria and North Rhine-Westphalia face REACH chemical restrictions eliminating chromate-based corrosion inhibitors.
India
Bengaluru and Hyderabad airport zones attract heavy maintenance investment under the national PLI scheme for aerospace manufacturing. Airframe and powerplant mechanic shortages constrain capacity expansion despite fleet growth from IndiGo and SpiceJet. The Directorate General of Civil Aviation processes dual certification timelines for cross-border MRO operations, extending facility qualification periods.
United Arab Emirates
Dubai International Airport and Al Maktoum International anchor dedicated freighter MRO capacity for overnight express operations across Europe-Asia trade lanes. Emirates Engineering operates airline-owned hangars protecting core A380 and 777 fleet availability. The General Civil Aviation Authority enforces maintenance reserve documentation standards that align with Dublin and Singapore lessor headquarters requirements.
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across engine overhaul complexity, where proprietary OEM technical data creates captive supply chains for high-thrust turbofan servicing. The sector consolidates around three strategic archetypes: OEM-affiliated facilities retaining original design authority, independent MRO providers competing on turnaround speed, and airline-owned hangars protecting fleet availability. Dominant competitive moves include strategic partnerships for technical data access and geographic expansion into Southeast Asian growth markets.
Among European-based service integrators, Lufthansa Technik exemplifies the premium-tier engine overhaul archetype through captive OEM partnerships. AAR Corp occupies a position within the independent component repair segment, operating distributed third-party service centers. ST Engineering anchors the Asia-Pacific independent provider tier, demonstrating how scale challenges OEM-affiliated positions in base maintenance. These three entities represent distinct capability-depth strategies across the technical complexity spectrum.
| Leading Market Players |
|---|
| Lufthansa Technik |
| AAR Corp |
| GE Aviation |
| Delta TechOps |
| ST Engineering |
| Airbus SE |
| Rolls-Royce |
| Pratt & Whitney |
| SAFRAN Aircraft Engines |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's sustainable aviation fuel mandates and emerging carbon accounting rules gate both qualified supply and premium-tier pricing access. MRO providers with integrated engine performance analytics and residue testing capabilities command pricing premiums, while facilities lacking environmental certification face exclusion from European airline procurement rosters.
Pricing Analysis
Flight-hour-based contracts anchored on engine uptime guarantees now dominate the high-thrust turbofan overhaul segment. Three-tier pricing structure across OEM-authorized, independent certified, and non-certified service levels reflects technical data access and regulatory approval depth. Cost compression in commodity line maintenance intensifies because independent facility expansion outpaces demand growth in Southeast Asian hubs. Low-cost carriers exhibit acute price sensitivity for transit inspections, while aircraft lessors prioritize technical compliance over unit cost in redelivery preparation.
Supply Chain Analysis
Reverse-logistics flows for engine core returns and life-limited part refurbishment anchor aftermarket material circulation. Titanium sponge and nickel-based superalloy supplies concentrate in Russia, China, and Japan, with specialized aerospace-grade forgings sourced from Germany and the United States. Chromate-free corrosion inhibitor alternatives draw from limited qualified chemical suppliers, creating single-source vulnerability amid REACH substance restrictions. Distribution runs through OEM-controlled technical data portals and independent parts broker networks serving third-party repair stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial aircraft MRO is transitioning from scheduled overhaul cycles to predictive condition-based maintenance, with automated borescope inspection and vibration sensor fusion displacing legacy visual assessment protocols.
For Market Incumbents: Anchor premium positioning through exclusive OEM technical data partnerships that protect engine overhaul margin pools. Expand captive supply of specialized aerospace-grade materials via long-term purchasing agreements with Russian and Japanese titanium producers. Invest in AI-augmented diagnostic engineering talent to defend against independent providers acquiring automated inspection capabilities. For New Entrants and Emerging Players: Regional turboprop operators in secondary Indian cities represent an underserved buyer archetype with unmet heavy maintenance demand. Target Bengaluru and Hyderabad airport zones where PLI scheme incentives reduce facility capital intensity. Pursue quick-turnaround line maintenance contracts with Vietnamese and Indonesian low-cost carriers as the initial go-to-market pathway. For Investors and Strategic Acquirers: FAA airworthiness directive issuance acceleration is the leading indicator that structural inspection demand will outpace certified mechanic supply. Long-term viability favors acquisition targets with dual FAA-EASA certification infrastructure and established lessor redelivery consulting relationships. Monitor EASA Part-M electronic record exchange compliance deadlines for facility upgrade investment triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Inspection Technology Deployment | Machine learning borescope systems at Singapore and Dubai reception docks compress damage mapping timelines. |
| Dual Certification Infrastructure Investment | Simultaneous FAA and EASA approvals reduce cross-border facility qualification periods for revenue recognition. |
| Predictive Maintenance Platform Integration | Edge computing sensor fusion enables flight-hour-based contracts shifting from scheduled overhauls. |
| Sustainable Process Chemistry Transition | Chromate-free corrosion inhibitor adoption satisfies REACH restrictions while qualifying for EU Green Deal procurement. |
| India Heavy Maintenance Hangar Expansion | Bengaluru and Hyderabad zones under PLI scheme capture indigenous capacity demand from IndiGo and SpiceJet. |
Research Methodology
FAA airworthiness directive filings, EASA Part-M regulatory amendments, and airline maintenance procurement disclosures formed the secondary backbone. Primary interviews with MRO facility operations directors, airline technical procurement managers, aircraft leasing company asset managers, and certified airframe and powerplant mechanics validated demand assumptions. Bottom-up facility capacity estimates and top-down fleet projection models were triangulated against customs data for aerospace-grade titanium and superalloy trade flows.
Historical trendline analysis of engine shop visit intervals and heavy check dwell times informed the projection framework. Segmentation across service type, application, facility ownership structure, and end-user procurement sophistication was modeled throughout the forecast period. CAGRs were derived from fleet age profile trajectories and regulatory inspection interval compression. Industry-specific inputs included low-cost carrier fleet expansion schedules in Indonesia, Vietnam, and the Philippines, plus sustainable aviation fuel mandate implementation timelines under EU Green Deal carbon accounting rules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to certified AMT graduation rates and REACH chemical authorization timelines. Forecasts reflect assumptions regarding OEM technical data access continuity and dual certification regulatory stability. Practitioners should monitor FAA aging aircraft directive issuance frequency and ECHA substance restriction expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Engine Hoists Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Training Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Refurbishing Market
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
On-Premises MRO Software Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Buffing Wheel Market