
 Aluminum Titanate Market | 2026-2036
Aluminum Titanate Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Titanate Market Analytics
The EU Green Deal is expanding the addressable market for low-thermal-expansion ceramics in automotive exhaust systems. CeramTec GmbH leverages its European manufacturing footprint to supply OEM-qualified aluminum titanate components. Kyocera Corporation anchors its position through R&D intensity in electronic substrate applications. Morgan Advanced Materials competes via specialized refractory formulations for aerospace thermal protection.
Aluminum titanate is a ceramic oxide compound synthesized from alumina and titania, exhibiting exceptionally low thermal expansion and high thermal shock resistance up to 1000°C, making it indispensable for molten metal handling and engine exhaust components. The refractories segment dominates volume due to entrenched demand from steel and aluminum foundries, while crucibles for semiconductor crystal pulling represents the fastest-growing margin pool. Electronics applications sustain premium pricing through exacting purity requirements for wafer processing equipment.
The EPA enforces particulate emissions standards that mandate durable thermal barrier materials in diesel aftertreatment systems, while REACH compliance in Europe restricts hazardous additives in ceramic binders. ISO 9001 and IATF 16949 certifications function as de facto market access requirements for automotive supply chain entry. Stakeholders must monitor evolving carbon border adjustment mechanisms and decide between regional production qualification versus centralized export strategies.
Market Dynamics
Automotive OEMs are consolidating aluminum titanate substrate procurement around single-source qualification programs, compressing supplier margins while elevating IATF 16949 certification to a non-negotiable barrier. This structural concentration is reshaping competitive positioning among European precision ceramics specialists.
Growth Catalysts
- EU Green Deal thermal specifications:Tighter emissions benchmarks mandate low-thermal-expansion ceramics in exhaust aftertreatment systems, expanding addressable demand for aluminum titanate substrates.
- Semiconductor wafer processing:Crucibles for silicon crystal pulling require ultra-high-purity aluminum titanate, creating premium-margin demand pools distinct from commodity refractories.
- German automotive clusters:Precision ceramics manufacturing concentrates around Stuttgart and Munich, co-locating production with Tier 1 supplier engineering centers.
Market Restraints
- Raw material cost volatility:Rutile and synthetic rutile prices fluctuate with titanium dioxide pigment demand, squeezing compounder margins without pass-through mechanisms.
- Substitution by silicon nitride:Higher-temperature engine applications above 1000°C favor silicon nitride thermal barriers, capping aluminum titanate's addressable temperature range.
- REACH binder restrictions:ECHA limitations on phenolic resin systems complicate green body formulation, forcing reformulation investments.
Strategic Opportunities
- India automotive emissions compliance:Bharat Stage VI implementation creates first-mover advantage for aluminum titanate diesel particulate filter substrate suppliers establishing local qualification.
- Additive manufacturing convergence:Binder jet printing of aluminum titanate enables near-net-shape exhaust components, reducing machining waste and lead times.
- US EPA heavy-duty truck standards:Phase 3 greenhouse gas rules extend thermal management material lifecycles, favoring aluminum titanate's thermal shock resistance.
Industry Challenges
- Ceramic process engineering talent scarcity:Specialized knowledge in reaction sintering and controlled thermal expansion engineering concentrates among retiring European technicians.
- OEM qualification timeline compression:IATF 16949 certification cycles extend 18-24 months, freezing new entrants during demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Titanate Market |
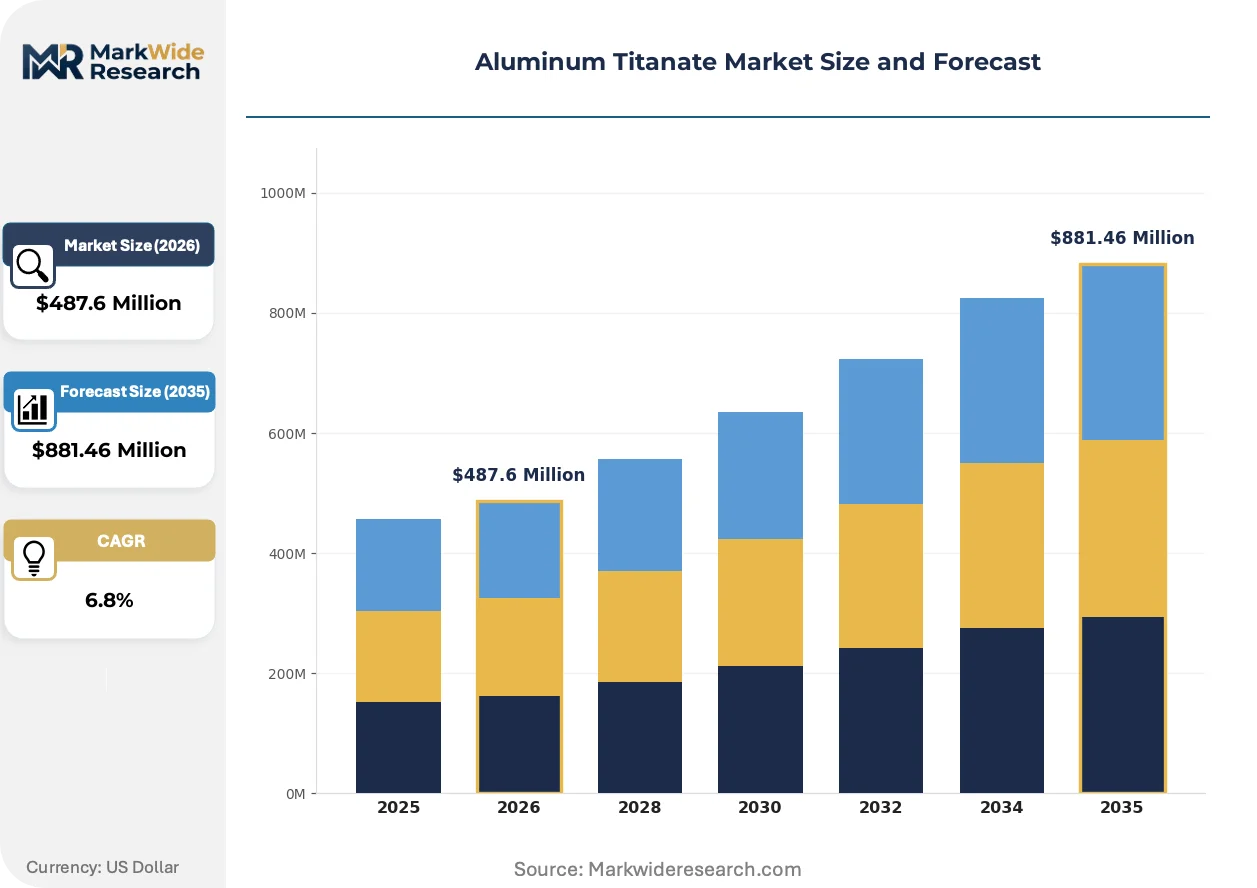
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crucibles, Refractories, Coatings, Ceramics Application: Automotive, Aerospace, Electronics, Construction End User: Manufacturers, OEMs, Research Institutions, Contractors Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | CeramTec GmbH, Blasch Precision Ceramics, Kyocera Corporation, Morgan Advanced Materials, Saint-Gobain Ceramics, H.C. Starck GmbH, CoorsTek Inc., Nippon Chemical Industrial Co., Ltd., Titan Kogyo, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Titanate Market Evolving Landscape
Material science advances are converging with emissions compliance deadlines to accelerate aluminum titanate formulation diversity. Process innovations and procurement model evolution are simultaneously reshaping supply relationships.
Advanced aluminum titanate composites incorporating zirconia toughening are absorbing thermal cycling loads in gasoline particulate filters. Continental and Bosch Tier 1 suppliers are qualifying these formulations for 2027 platform launches. The technology is absorbing market share from cordierite in applications exceeding 900°C sustained operation.
REACH authorization procedures for titanium compounds are tightening traceability requirements across European supply chains. Compounders must now document smelter origins for titania feedstocks. Automotive exhaust component manufacturers in Germany and Czechia are responding by qualifying dual-source raw material strategies.
Consolidated procurement portals operated by Volkswagen Group and Stellantis are disintermediating traditional ceramics distributors. Direct supplier-OEM engineering relationships are replacing tiered purchasing structures. This concentration is most visible in southern Germany, where CeramTec and Morgan Advanced Materials maintain dedicated technical service teams at OEM development centers.
Aluminum Titanate Market Segmentation
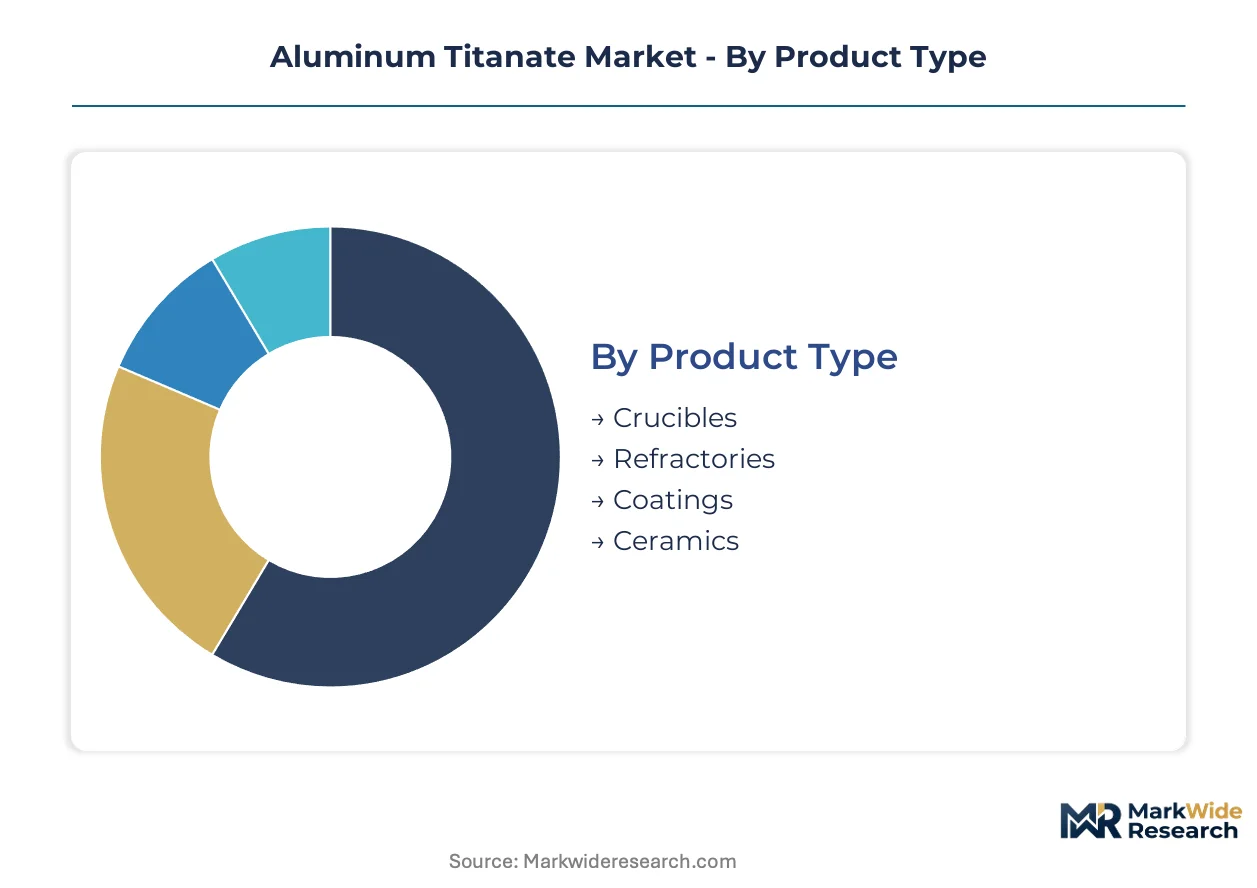
Aluminum titanate's thermal properties create divergent value pools across product forms and buyer categories. Segmentation reveals where technical specifications command premium pricing versus where commodity refractory grades compete on volume scale.
Product Type:
Buyers in this category separate by operating temperature ceiling and purity tolerance rather than unit economics alone.
- Refractories:High-alumina titanate linings for molten metal containment dominate tonnage demand from steel foundries in Germany and Japan. Specifications prioritize thermal shock survival over dimensional precision, locking in entrenched supply relationships with integrated mills.
- Crucibles:Ultra-high-purity aluminum titanate crucibles for silicon crystal pulling command the steepest margin premiums. Semiconductor equipment OEMs in Taiwan and South Korea specify sub-50ppm iron content, creating qualification barriers that protect incumbent suppliers.
- Ceramics:Engineered components span diesel particulate filter substrates and thermal barrier tiles for aerospace.
- Coatings:Plasma-sprayed aluminum titanate layers protect turbine blades and exhaust manifolds from oxidation.
Volume sits with refractories; growth tilts toward crucibles.
Application:
End-use differentiation tracks regulatory stringency and thermal cycling severity rather than absolute temperature requirements.
- Automotive:Diesel particulate filter substrates and gasoline particulate filters absorb the majority of European demand. EU Green Deal emissions benchmarks mandate low-thermal-expansion materials surviving 1000°C regeneration cycles, favoring aluminum titanate over cordierite above 900°C sustained operation.
- Electronics:Wafer processing equipment and crystal pulling systems sustain premium pricing through exacting purity standards. Japanese semiconductor equipment manufacturers specify aluminum titanate for its thermal stability during silicon ingot growth.
- Aerospace:Thermal protection systems for engine components and re-entry vehicles demand zirconia-toughened aluminum titanate composites.
- Construction:Kiln furniture and high-temperature insulation represent mature demand with price-sensitive procurement.
Procurement scale concentrates in automotive; margin expansion accelerates fastest in electronics.
End User:
Customer type determines certification burden and technical service intensity more than order size.
- OEMs:Volkswagen Group and Stellantis operate consolidated procurement portals that disintermediate traditional ceramics distributors. Direct engineering relationships replace tiered purchasing, compressing supplier margins while elevating IATF 16949 certification to market entry condition.
- Manufacturers:Tier 1 automotive suppliers and foundry operators purchase on long-term contracts indexed to rutile feedstock costs.
- Research Institutions:National laboratories and university materials science programs drive formulation innovation through small-batch qualification orders.
- Contractors:Installation and maintenance services for refractory linings represent fragmented, locally competitive demand.
Contractor volume dominates unit count; OEM relationships capture strategic value.
Distribution Channel:
Channel selection reflects buyer technical sophistication and order fragmentation.
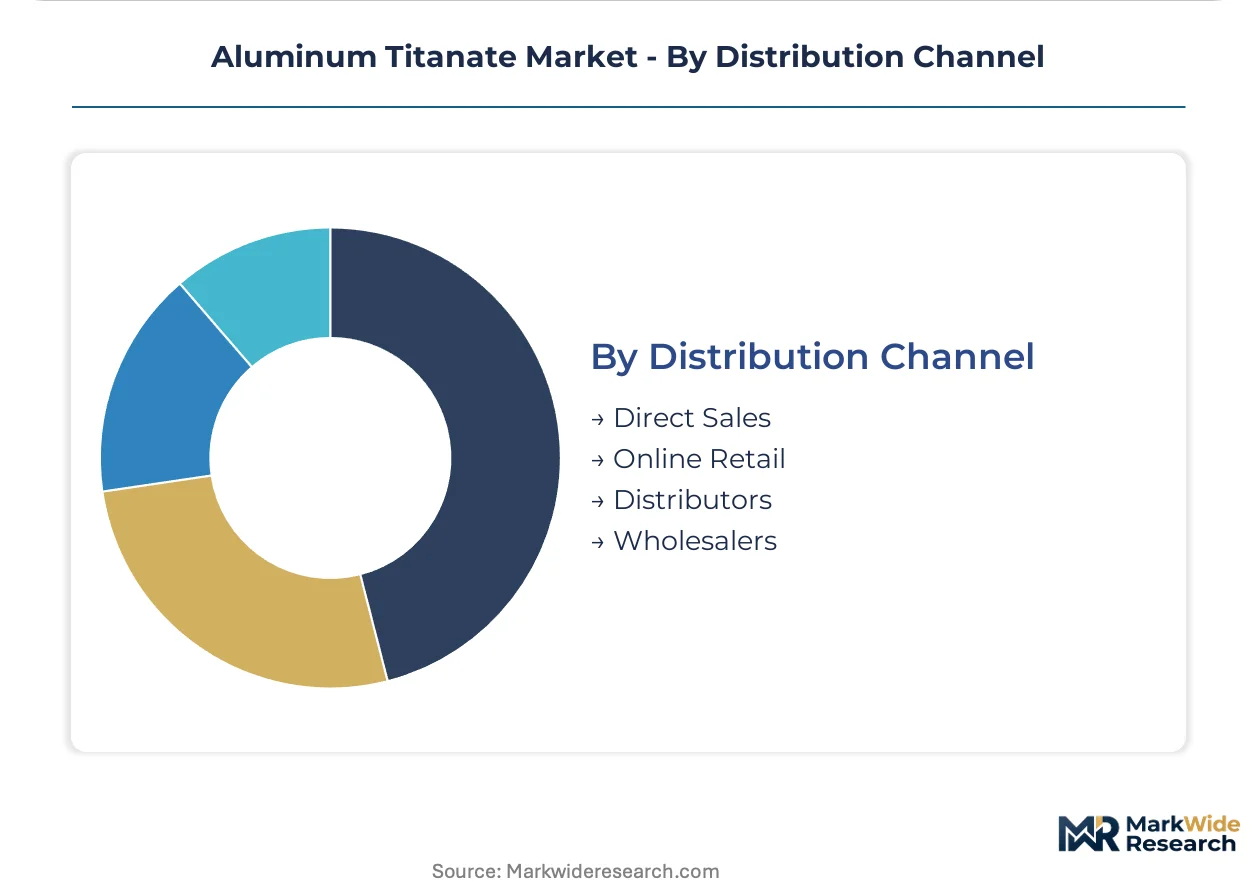
- Direct Sales:OEM qualification programs and semiconductor equipment manufacturers require dedicated technical service teams co-located at development centers. CeramTec and Morgan Advanced Materials maintain engineering presence in Stuttgart and Munich to support direct relationships.
- Distributors:Regional ceramics distributors serve foundries and smaller manufacturers with standardized refractory grades.
- Online Retail:Catalog sales of crucibles and laboratory ceramics target research institutions and small-scale processors.
- Wholesalers:Bulk refractory materials move through construction supply channels for kiln furniture and insulation applications.
Direct sales anchor premium positioning; distributor networks handle commodity volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and Japan while consumption tilts toward automotive manufacturing clusters in Germany, the United States, and China. Foundry demand in India and semiconductor processing in South Korea create divergent consumption patterns.
Germany
Automotive exhaust component demand from Stuttgart and Munich engineering centers absorbs premium-grade aluminum titanate substrates. EU Green Deal emissions benchmarks tighten thermal barrier specifications for diesel aftertreatment systems. Precision ceramics clusters in Baden-Württemberg co-locate production with Tier 1 supplier engineering centers.
United States
EPA Phase 3 greenhouse gas standards for heavy-duty trucks extend thermal management material lifecycles. The agency enforces particulate emissions standards that mandate durable thermal barriers in diesel aftertreatment systems. Midwest foundry operations in Ohio and Indiana sustain refractory demand from steel and aluminum casting.
China
Domestic automotive production scales drive substrate consumption for gasoline particulate filters. The Ministry of Ecology and Environment implements dual carbon goals that tighten industrial emissions standards. Yangtze River Delta manufacturing bases concentrate crucible production for semiconductor wafer processing equipment.
Japan
Semiconductor equipment manufacturers specify ultra-high-purity aluminum titanate for silicon ingot growth systems. METI industrial standards govern ceramic material qualifications for electronics applications. Kyushu and Kansai industrial corridors host precision ceramics R&D facilities serving crystal pulling equipment OEMs.
India
Bharat Stage VI emissions compliance creates first-mover opportunity for diesel particulate filter substrate suppliers. The Bureau of Indian Standards certifies automotive component materials for domestic qualification programs. Maharashtra and Gujarat automotive corridors attract technical service teams from European ceramics specialists.
Aluminum Titanate Market Competitive Landscape
The competitive structure tilts toward European precision ceramics specialists with IATF 16949 automotive certification. German and Japanese players dominate premium substrate supply through entrenched OEM qualification programs. Three archetypes define positioning: vertically integrated refractory compounders, semiconductor-grade purity specialists, and automotive-qualified substrate manufacturers. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers secure raw material traceability under REACH authorization procedures.
Among Germany-based precision ceramics manufacturers, CeramTec GmbH occupies a position exemplifying automotive-qualified substrate supply. Japanese specialists including Kyocera Corporation and Nippon Chemical Industrial Co., Ltd. represent the semiconductor-grade purity archetype, anchoring the premium tier for wafer processing applications. Morgan Advanced Materials and Saint-Gobain Ceramics sit within the vertically integrated compounder category, leveraging refractory scale economies across foundry and aerospace thermal protection segments.
| Leading Market Players |
|---|
| CeramTec GmbH |
| Blasch Precision Ceramics |
| Kyocera Corporation |
| Morgan Advanced Materials |
| Saint-Gobain Ceramics |
| H.C. Starck GmbH |
| CoorsTek Inc. |
| Nippon Chemical Industrial Co., Ltd. |
| Titan Kogyo, Ltd. |
| Others |
Value Network & Pricing Analysis
Automotive IATF 16949 certification tiers split aluminum titanate procurement into parallel pricing and supply architectures. OEM direct qualification programs command 40-60% premiums over distributor-served foundry grades, while rutile feedstock volatility propagates unevenly through these channels.
Pricing Analysis
Margin tightening in semiconductor-grade crucibles reflects sub-50ppm iron purity thresholds and multi-year qualification cycles with Taiwan equipment OEMs. Three-tier pricing structure across premium, standard, and economy levels separates automotive-qualified substrates from industrial refractories and research-laboratory catalog sales. Cost-down pressure on commodity refractory grades accelerates because German steel foundries index contracts to synthetic rutile pigment-market volatility. Semiconductor equipment manufacturers exhibit lowest price sensitivity; construction kiln furniture buyers drive hardest bargain.
Supply Chain Analysis
Freight cost differentials between German precision ceramics clusters and Asian semiconductor equipment hubs shape regional sourcing decisions. Supply concentrates in Germany, Japan, and China, with Baden-Württemberg hosting co-located production and Tier 1 engineering centers. Feedstock draws from Australian rutile mines, Ukrainian titanium slag processors, and Chinese synthetic titania producers. Single-source vulnerability concentrates in Ukrainian titanium feedstock channels disrupted by conflict. Distribution runs through OEM direct technical service teams for automotive, regional ceramics distributors for foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum titanate supply remains constrained by 18-24 month IATF 16949 qualification cycles, propping pricing for incumbent substrate manufacturers while freezing new capacity during demand surges.
For Market Incumbents: Hedge silicon nitride substitution above 1000°C by accelerating zirconia-toughened composite R&D for gasoline particulate filter platforms. Lock rutile supply through backward integration into Australian or African feedstock offtake agreements. Defend automotive margins by embedding technical service teams at Stuttgart and Munich OEM development centers. For New Entrants and Emerging Players: Indian Tier 2 automotive suppliers represent the most penetrable buyer archetype given Bharat Stage VI implementation timelines and absent local IATF 16949-qualified substrate capacity. Target crucible aftermarket for research institutions requiring small-batch qualification orders with compressed certification burdens. Pursue additive manufacturing partnerships for near-net-shape exhaust components to bypass machining-capital intensity. For Investors and Strategic Acquirers: Re-rating potential sits with semiconductor-grade purity specialists given wafer processing equipment capex cycles and Taiwan-Japan supply concentration. Five-to-ten year viability hinges on automotive electrification pace versus internal combustion thermal management persistence. Monitor EPA Phase 3 heavy-duty truck standard implementation as inflection signal for North American substrate demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rutile Feedstock | Secures titania supply traceability under REACH authorization procedures. |
| IATF 16949 Certification Investment | Unlocks Volkswagen Group and Stellantis direct procurement portal access. |
| Additive Manufacturing Capability Buildout | Enables binder jet printing of near-net-shape diesel particulate filter substrates. |
| Dual-Source Raw Material Strategy | Qualifies Australian and African rutile origins to mitigate Ukrainian supply risk. |
| Technical Service Team Co-Location | Places CeramTec and Morgan engineering staff at Stuttgart OEM development centers. |
Research Methodology
Multi-period observation of rutile price indices, automotive platform launch schedules, and semiconductor equipment capex cycles anchored the trend analysis, supplemented by interviews with refractory plant managers, Tier 1 automotive procurement leads, semiconductor equipment OEM technical directors, and ECHA regulatory affairs specialists. Secondary validation drew from EPA enforcement actions, EU Green Deal implementation progress reports, SEC filings of listed ceramics manufacturers, and Japanese METI industrial standards documentation. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Input-output matrices mapped alumina and titania feedstock flows through reaction sintering processes to end-use demand across automotive exhaust, semiconductor wafer processing, and foundry refractory segments. Modeled dimensions spanned product purity grade, application temperature ceiling, OEM certification status, and regional manufacturing cluster. CAGRs derived from regression analysis of historical capacity utilization against emissions regulation implementation timelines, with semiconductor capital equipment order backlogs and automotive platform lifecycle transitions as industry-specific forecast inputs.
Revisions become necessary when REACH authorization procedures tighten titanium compound traceability, Ukrainian rutile supply disruptions extend, or silicon nitride thermal barrier adoption accelerates beyond 1000°C engine applications. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Europe Aerospace Composites Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Space Electronics Market
Aerospace and Aircraft Materials
Aviation Carbon Fiber Market
Aerospace and Aircraft Materials
Global Aerospace and Defense Elastomers Market
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Global Aerospace Insulation Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Russia Space Electronics Market
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Stealth Coating Market