
 Energy Management Systems (EMS) Market | 2026-2036
Energy Management Systems (EMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Management Systems (EMS) Market Analysis
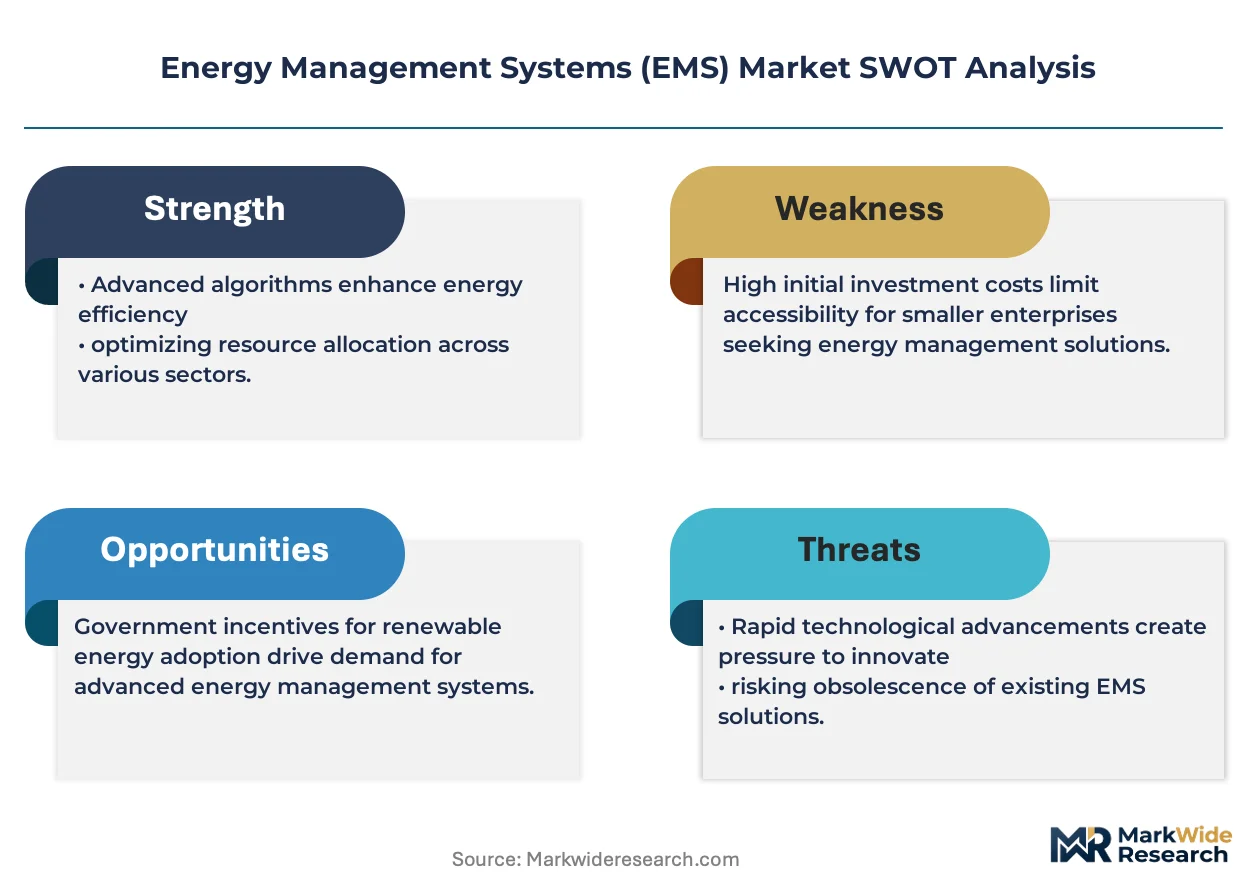
Project finance for energy-as-a-service contracts is reshaping competitive entry in the EMS landscape, allowing facility operators to deploy advanced systems without capital expenditure burdens. Schneider Electric SE leverages its integrated hardware-software stack to anchor large commercial building deployments across Europe. Siemens AG sustains technology leadership through its digital twin platforms for grid optimization. Honeywell International Inc. competes on building automation convergence, bundling HVAC controls with real-time energy analytics.
Energy Management Systems encompass software platforms, control hardware, and communication infrastructure that monitor, control, and optimize energy consumption across distributed assets, typically processing data streams from sub-15-minute intervals to enable automated load dispatch. These systems serve the primary commercial purpose of reducing kilowatt-hour intensity while maintaining operational uptime for energy-intensive facilities. Grid optimization applications now dominate value capture as utilities modernize distribution networks, while artificial intelligence technology represents the fastest-expanding capability layer as predictive algorithms displace rule-based load scheduling. Demand response systems remain structurally mature with compressed margins, whereas energy storage management commands premium pricing due to battery cycling complexity and grid interconnection standards.
The US Inflation Reduction Act and EPA building performance standards are tightening efficiency mandates for commercial structures above 25,000 square feet, directly expanding addressable demand for integrated EMS platforms. The EU Green Deal and F-Gas Regulation are accelerating refrigerant-linked energy audits across member states, pulling building management systems into compliance workflows. China's MIIT dual carbon targets and GB standards are forcing industrial facilities to adopt submetering granularity that exceeds prior voluntary benchmarks. Stakeholders must monitor how evolving carbon accounting rules redefine which EMS data streams qualify for regulatory credit.
Market Dynamics
Grid modernization mandates are compressing EMS deployment cycles as utilities accelerate distribution automation investments to manage distributed energy resource penetration and voltage instability risks.
Growth Catalysts
- Carbon Border Adjustment Mechanism:Germany's industrial manufacturers deploy submetering infrastructure to document embodied emissions for EU CBAM compliance, pulling granular EMS platforms into steel and chemical facilities.
- Data center power intensity caps:Hyperscale operators in Northern Virginia and Frankfurt face utility interconnection limits that force real-time load orchestration through advanced EMS stacks.
- AI-driven predictive dispatch:Machine learning algorithms now forecast 15-minute ahead demand spikes with sufficient accuracy to automate battery cycling and peak shaving protocols.
Market Restraints
- Semiconductor supply concentration:Industrial control hardware depends on power management ICs sourced predominantly from Taiwan-based foundries, exposing EMS OEMs to foundry allocation volatility.
- Legacy protocol fragmentation:BACnet, Modbus, and proprietary building automation standards create integration friction that extends commissioning timelines and inflates professional services costs.
- Skilled technician scarcity:Certified building systems integrators capable of configuring multi-vendor EMS deployments remain concentrated in mature metropolitan markets, constraining rural and secondary city rollout velocity.
Strategic Opportunities
- India industrial corridor electrification:Maharashtra and Gujarat textile clusters face CEA mandatory energy audits that create first-mover openings for submetering-as-a-service platforms.
- Electrification of thermal processes:Heat pump integration with process control systems opens EMS adjacencies in food processing and pharmaceutical manufacturing previously served by standalone HVAC controllers.
- FERC Order 2222 implementation:US wholesale market participation rules for aggregated distributed energy resources enable EMS providers to capture capacity payment revenue streams beyond efficiency savings.
Industry Challenges
- Cybersecurity certification timelines:IEC 62443 compliance validation for grid-connected control systems extends product release schedules by 8-14 months, compressing competitive windows.
- Interoperability testing burden:Multi-vendor system validation requires physical hardware-in-the-loop facilities that strain R&D budgets for mid-scale EMS developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Management Systems (EMS) Market |
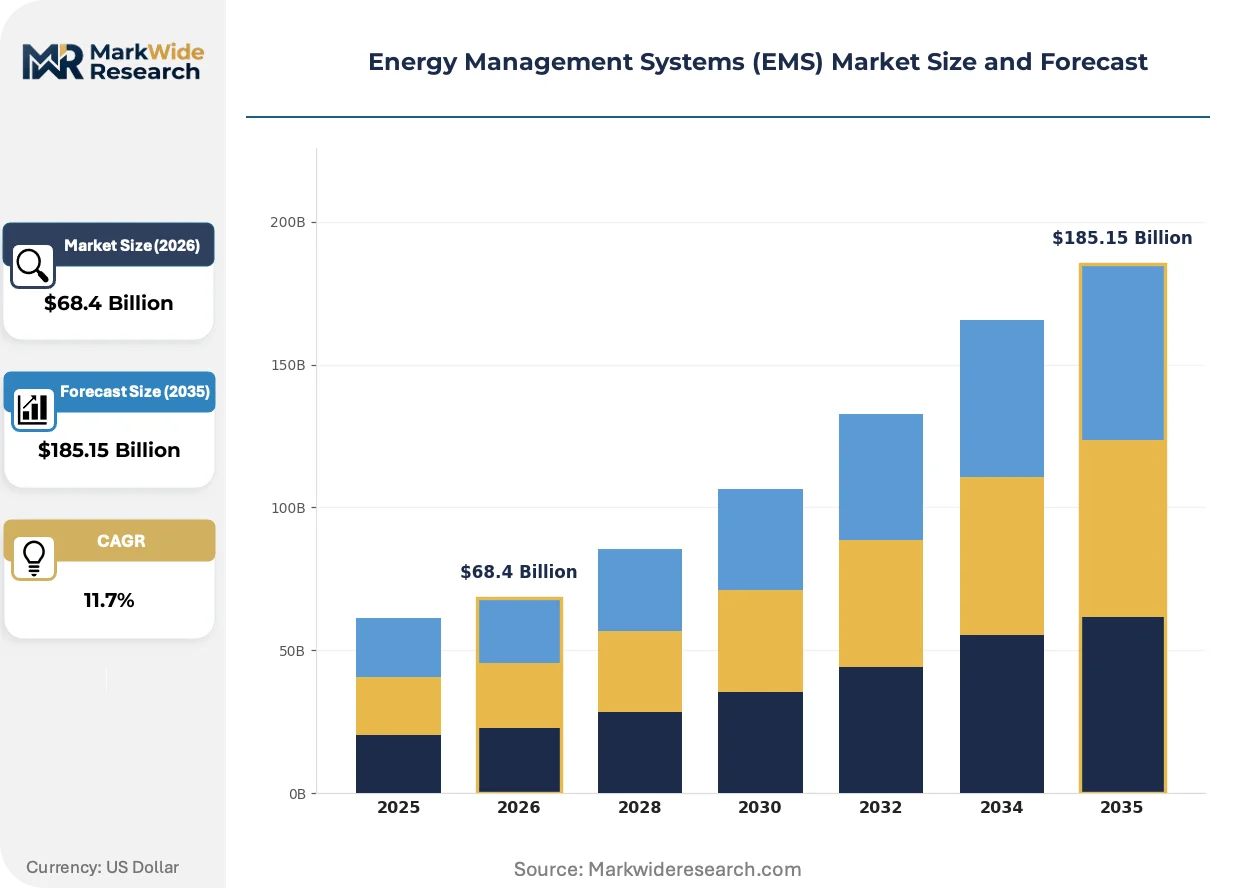
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Demand Response, Grid Optimization, Renewable Integration, Energy Storage Management Application: Industrial Automation, Building Management, Smart Grids, Residential Management Technology: IoT Solutions, Cloud Computing, Artificial Intelligence, Big Data Analytics End User: Utilities, Commercial Buildings, Manufacturing Facilities, Data Centers |
| Companies Covered | Schneider Electric SE, Siemens AG, General Electric Company, Honeywell International Inc., Johnson Controls International PLC, ABB, Emerson Electric Co., Eaton Corporation PLC, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Management Systems (EMS) Market Emerging Trajectories
Digital twin architectures are collapsing the boundary between physical asset management and software-based optimization, enabling continuous simulation of energy flows without disrupting operational uptime.
Edge computing nodes with embedded AI inference engines are virtualizing control logic that previously required centralized SCADA servers. Manufacturing facilities in Michigan and Bavaria deploy these distributed controllers to achieve sub-100-millisecond load response latencies. This virtualization is compressing hardware consolidation cycles and displacing rack-mounted server infrastructure from plant floors.
The EU F-Gas Regulation mandates refrigerant leak detection and energy performance documentation for commercial cooling systems above specific charge thresholds. Building operators in France and Spain now integrate refrigerant monitoring into EMS dashboards to satisfy ANSM audit requirements. This regulatory pull is accelerating convergence between traditional BMS and energy analytics platforms in Mediterranean climate zones.
Facility managers increasingly unbundle long-term service contracts from initial EMS procurement, selecting specialized software vendors for optimization algorithms while sourcing hardware through separate electrical contractors. This disintermediation is fragmenting vendor relationships in the US commercial real estate sector, where property investment trusts now maintain vendor scorecards across six to eight specialized providers rather than single-source building automation contracts.
Energy Management Systems (EMS) Market Segmentation
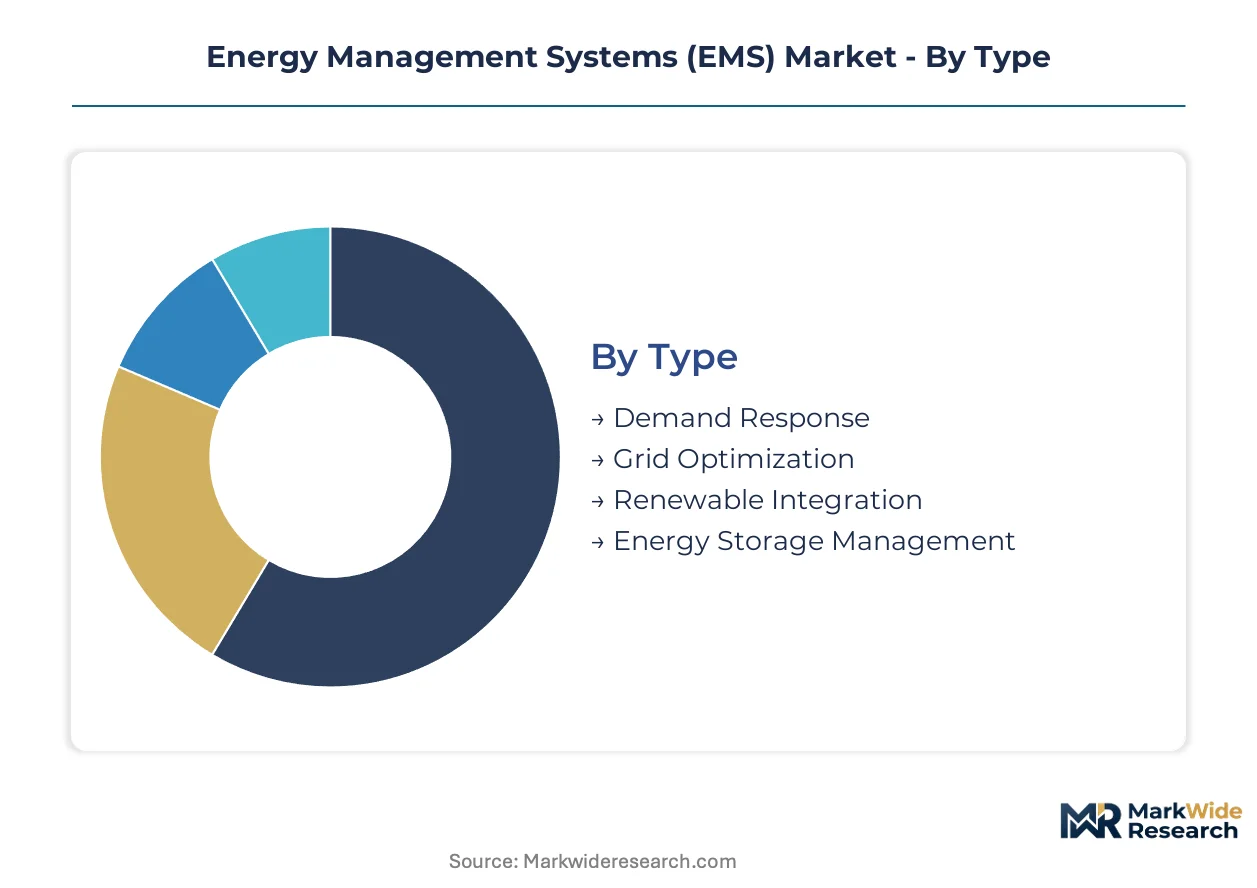
EMS segmentation reflects divergent procurement cycles across control hardware, software platforms, and service layers. Understanding these temporal patterns reveals where vendors can capture recurring revenue versus one-time equipment sales.
Type:
Grid Optimization platforms turn over fastest as utilities refresh SCADA architectures every 7-10 years, while Energy Storage Management contracts extend 15-20 years tied to battery asset lifecycles.
- Grid Optimization:Distribution automation software with voltage regulation algorithms and DER coordination protocols. German utilities facing TenneT congestion management mandates drive replacement demand as legacy SCADA reaches end-of-life.
- Energy Storage Management:Battery cycling optimization with state-of-charge forecasting and grid interconnection compliance. California ISO market participation rules force independent power producers to upgrade control logic for FERC Order 841 compliance.
- Demand Response:Automated load curtailment systems for peak shaving and frequency regulation. Mature margins compress as aggregation models commoditize.
- Renewable Integration:Forecasting and inverter control for solar and wind asset dispatch. Grid code harmonization across EU member states creates specification fragmentation.
Grid Optimization anchors the volume base while Energy Storage Management gains share at the steepest rate.
Application:
Cost tier stratification separates high-touch Building Management deployments from standardized Smart Grid infrastructure.
- Building Management:HVAC integration, lighting control, and occupancy-based load scheduling for commercial structures. US EPA performance standards for structures above 25,000 square feet pull integrated platforms into compliance workflows.
- Smart Grids:Distribution feeder automation, AMI backhaul, and outage management for electric utilities. Grid modernization mandates in Michigan and Texas compress procurement timelines.
- Industrial Automation:Process control integration with submetering granularity for energy-intensive manufacturing. China's MIIT dual carbon targets force steel and cement facilities to exceed prior voluntary benchmarks.
- Residential Management:Home energy displays, smart thermostat networks, and behind-the-meter solar optimization. Utility rebate programs in France and Spain accelerate mass-market penetration.
Building Management commands premium pricing while Smart Grids deliver volume scale through utility tender programs.
Technology:
Application maturity separates proven IoT deployments from experimental AI layers still navigating validation cycles.
- Artificial Intelligence:Predictive load forecasting, anomaly detection, and automated dispatch optimization using neural networks. Northern Virginia data centers deploy 15-minute ahead demand spike prediction to manage interconnection limits.
- IoT Solutions:Sensor networks, edge gateways, and wireless protocols for distributed asset monitoring. BACnet and Modbus protocol fragmentation extends commissioning timelines in multi-vendor environments.
- Cloud Computing:Centralized data aggregation, remote diagnostics, and software-as-a-service delivery models. Cybersecurity certification under IEC 62443 extends release schedules.
- Big Data Analytics:Historical consumption patterning, benchmark reporting, and regulatory compliance documentation. EU CSRD carbon accounting rules redefine which data streams qualify for audit credit.
IoT Solutions generate the installed base volume while Artificial Intelligence climbs the fastest on replacement demand.
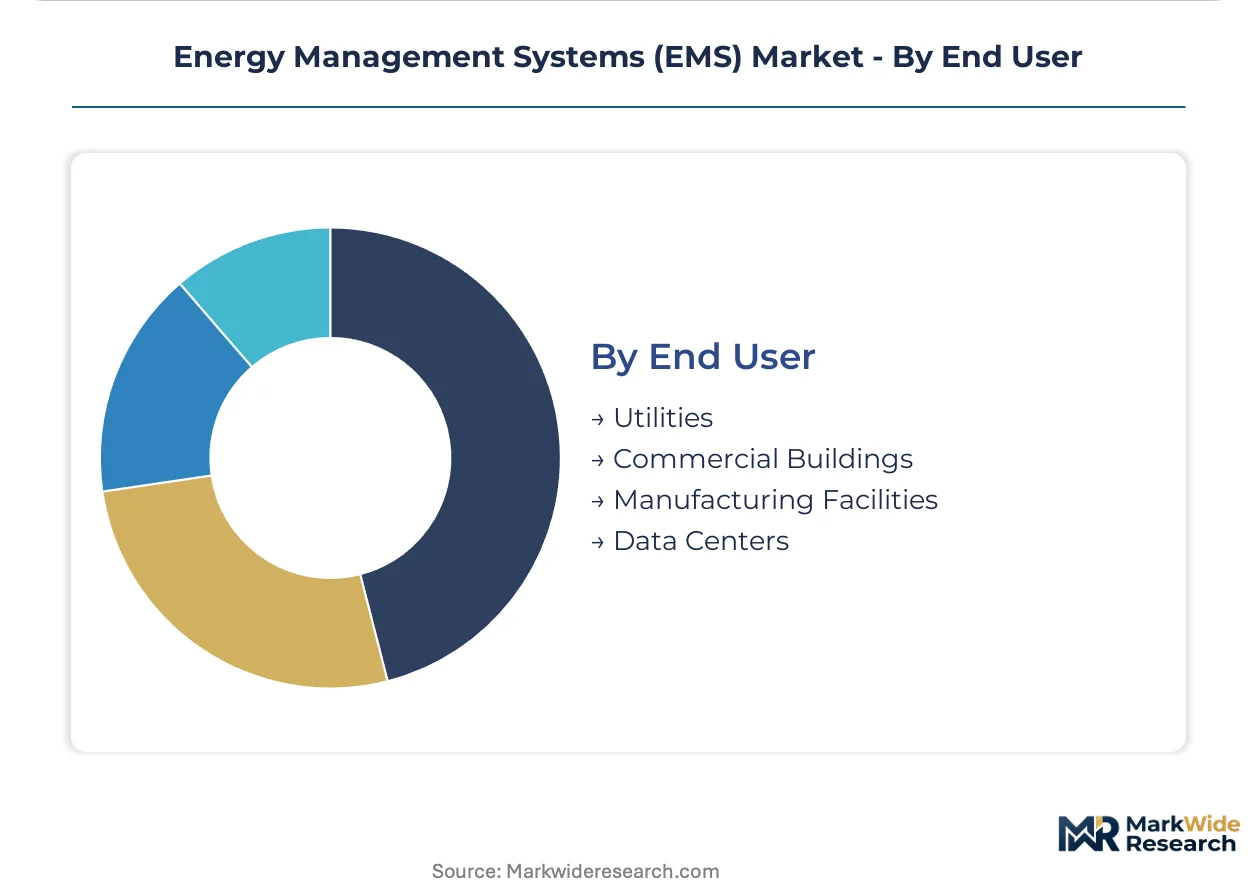
End User:
Customer type determines contract structure, with Utilities favoring long-term service agreements and Data Centers demanding performance guarantees.
- Data Centers:Real-time power usage effectiveness tracking, cooling optimization, and workload migration for hyperscale facilities. Frankfurt and Amsterdam operators face utility interconnection caps that force load orchestration investment.
- Manufacturing Facilities:Process energy monitoring, equipment-level submetering, and carbon border documentation for export compliance. Germany's industrial corridor drives CBAM-linked EMS adoption in steel and chemical plants.
- Utilities:Grid-scale DER management, volt-var optimization, and wholesale market participation platforms. FERC Order 2222 implementation enables capacity payment revenue capture.
- Commercial Buildings:Tenant billing allocation, LEED certification support, and operational efficiency reporting. US Inflation Reduction Act tax credits channel capital toward efficiency retrofits.
Manufacturing Facilities anchor procurement volume while Data Centers expand most quickly on power density constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing economies drive EMS adoption as carbon border documentation requirements reshape facility investment priorities. Import-dependent regions accelerate grid modernization to manage distributed energy resource penetration. Trade-exposed industrial clusters face the steepest compliance pressure.
United States
Data center power density constraints in Northern Virginia and Dallas-Fort Worth force real-time load orchestration investments. The EPA's building performance standards for structures above 25,000 square feet pull integrated EMS platforms into compliance workflows. Midwest manufacturing facilities in Michigan and Ohio deploy submetering granularity to satisfy corporate carbon accounting requirements.
Germany
Steel and chemical manufacturers in the industrial corridor deploy granular EMS platforms to document embodied emissions for EU CBAM compliance. The F-Gas Regulation mandates refrigerant-linked energy audits across commercial cooling systems. Bavarian automotive suppliers integrate process control systems with energy analytics to meet OEM Scope 3 reporting requirements.
China
MIIT dual carbon targets force steel and cement facilities to adopt submetering granularity exceeding prior voluntary benchmarks. GB standards for industrial energy consumption tighten measurement requirements for energy-intensive sectors. Yangtze River Delta manufacturing clusters upgrade control hardware to satisfy provincial emissions trading scheme verification protocols.
India
Maharashtra and Gujarat textile clusters face CEA mandatory energy audits that create first-mover openings for submetering-as-a-service platforms. The country's national energy efficiency bureau mandates periodic consumption assessments for designated consumers. Karnataka's electronics manufacturing zone deploys edge computing nodes to manage intermittent renewable penetration.
Japan
Commercial building operators in Tokyo and Osaka integrate EMS with existing building automation infrastructure to satisfy METI efficiency reporting requirements. The national standards body certifies submetering equipment for industrial facility deployment. Kyushu semiconductor fabrication plants deploy predictive load forecasting to manage grid interconnection limits.
Energy Management Systems (EMS) Market Vendor Landscape
On the supply side, the industry is consolidating around integrated hardware-software stacks that reduce multi-vendor integration friction. European and North American conglomerates anchor the premium tier through digital twin and grid optimization platforms. Three archetypes dominate: full-stack industrial conglomerates, specialized software vendors, and electrical equipment manufacturers extending into control systems. Competitive moves center on strategic partnerships with utility operators and portfolio diversification into energy-as-a-service contracting models.
Within the full-stack tier, Schneider Electric SE and Siemens AG exemplify integrated platform providers that span control hardware through cloud analytics. Honeywell International Inc. occupies a position bridging building automation convergence with real-time energy analytics. These three anchors represent distinct geographic origins—French, German, and American respectively—while sitting within the premium-service archetype that bundles long-term optimization contracts with initial system deployment.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Siemens AG |
| General Electric Company |
| Honeywell International Inc. |
| Johnson Controls International PLC |
| ABB |
| Emerson Electric Co. |
| Eaton Corporation PLC |
| IBM Corporation |
| Others |
Supply Flow & Price Mechanics
Taiwan-based foundry concentration for power management ICs funnels margin pools toward EMS vendors with captive semiconductor sourcing or long-term allocation agreements. Industrial control hardware pricing reflects this upstream chokepoint, with tier-one OEMs capturing service premiums that offset component cost volatility.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade under IEC 62443 and UL 508A standards separates premium-tier grid optimization platforms from commodity building automation controllers. Cost compression in the standard tier is intensifying because mid-scale developers lack scale to amortize cybersecurity validation overhead. Data center operators show least price sensitivity due to interconnection limit constraints, while municipal utilities in secondary markets remain most cost-conscious.
Supply Chain Analysis
Extended payment terms from Taiwanese foundries and supply-chain finance facilities strain working capital for mid-tier EMS developers. Hardware assembly concentrates in China, Mexico, and Germany, with control logic IP development anchored in France and the USA. Semiconductor supply draws from Taiwan, South Korea, and Japan, while copper busbars and magnetic components feed from Chinese and Indian metal processors. Single-source vulnerability for power management ICs exposes OEMs to foundry allocation volatility. Distribution runs through electrical wholesale channels and direct utility tender programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where switching costs lock facility operators into multi-vendor integration ecosystems. Regulatory entrenchment through IEC 62443 certification timelines extends incumbent advantage.
For Market Incumbents: Build switching-cost moats through deep integration of digital twin platforms with client SCADA architectures. Schneider Electric and Siemens should extend certification pipelines to compress competitive windows for mid-scale challengers. Capacity addition in India and Southeast Asia addresses procurement localization mandates from CEA and MIIT regulators. Threat substitution from AI-native software vendors demands accelerated edge computing R&D investment. For New Entrants and Emerging Players: Pursue submetering-as-a-service openings in Maharashtra and Gujarat textile clusters where CEA audits create first-mover whitespace. Target heat pump integration adjacencies in food processing and pharmaceutical manufacturing previously served by standalone HVAC controllers. Go-to-market through energy-as-a-service contracting bypasses capital expenditure barriers that favor incumbent full-stack providers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed building automation specialists seeking platform consolidation. Five-to-ten year viability hinges on software revenue mix and recurring service contract tenure. Acquisition targets should demonstrate FERC Order 2222 compliance readiness and utility-scale DER aggregation capabilities. Watch California ISO market participation rule evolution as capacity payment revenue inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Schneider Electric and Siemens collapse physical-software boundaries for continuous energy flow simulation. |
| Edge Computing Node Deployment | Michigan and Bavaria manufacturing facilities achieve sub-100-millisecond load response latencies. |
| Cybersecurity Certification Acceleration | IEC 62443 compliance validation compresses product release schedules for competitive positioning. |
| Energy-as-a-Service Contracting | Project finance structures allow facility operators to deploy advanced EMS without capital expenditure. |
| FERC Order 2222 Compliance Buildout | Aggregated DER participation rules enable capacity payment revenue capture beyond efficiency savings. |
Methodological Framework
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation. Primary fieldwork drew from structured interviews with EMS procurement leads at hyperscale data centers and industrial facility energy managers. Secondary sources encompassed FERC filings, EIA generation data, IEA grid modernization reports, and project development databases tracking DER deployment. Bottom-up unit economics triangulated against top-down utility capex forecasts across the analysis window.
Demand-supply balance modeling anchored volume projections, with segmentation across grid optimization, energy storage management, demand response, and renewable integration platforms. Deployment model, facility scale tier, integration complexity, and regional regulatory framework dimensions structured the analytical framework. CAGRs derived from installed base turnover rates and replacement demand curves. Forecast inputs incorporated utility interconnection queue data and carbon border compliance timeline assumptions.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity demand, semiconductor foundry capacity allocation, or EU CBAM enforcement stringency would shift the trajectory. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory implementation schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
Mobile Metering System Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
Smart Thermostat Market
Energy Management Systems
Europe Advanced Distribution Management System Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
District Cooling Market
Energy Management Systems
Bed Cooling System Market
Energy Management Systems
Data Center Power Management Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
India Home Ventilation System Market
Energy Management Systems
Global Smart Air Conditioning Market