
 Smart Utilities Management Market | 2026-2036
Smart Utilities Management Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Utilities Management Market Analytics
Fragmentation among municipal and cooperative utilities is repositioning vendor account strategies toward smaller deployment footprints with faster implementation cycles. Siemens AG leverages its hardware-software integration depth to anchor large-scale grid modernization contracts across European markets. Honeywell International Inc. sustains competitive pressure through building-to-grid connectivity platforms that extend its automation franchise into utility operations. ABB Ltd differentiates via digital substation and distributed energy resource management systems that occupy the intersection of power infrastructure and IT.
Smart utilities management encompasses the integrated hardware, software, and communication layers that enable real-time monitoring, automated control, and predictive optimization of electricity, water, and gas distribution networks, typically operating through SCADA-adjacent architectures with sub-second telemetry refresh rates and AES-256 encrypted data pipelines. Its primary commercial purpose centers on reducing non-revenue losses, deferring capital-intensive infrastructure replacement, and enabling demand-response participation in wholesale energy markets. Smart meters and grid management systems together constitute the dominant revenue pool, though energy management software carries the fastest expansion trajectory as utilities seek cloud-native platforms for distributed energy resource orchestration. IoT and data analytics form the technology backbone where margin pools concentrate, since sensor deployment costs have fallen while algorithmic value extraction from operational data remains vendor-proprietary.
The US Federal Energy Regulatory Commission and the EPA shape utility investment through grid reliability mandates and emissions compliance timelines that directly determine capital allocation priority. Europe's CSRD and EU Green Deal disclosure requirements are forcing utilities to document infrastructure resilience and carbon intensity, which redirects procurement toward vendors with certified sustainability reporting capabilities. Stakeholders must monitor how regulatory divergence between jurisdictions affects platform interoperability standards and cross-border vendor qualification.
Market Dynamics
Grid decentralization and the proliferation of distributed energy resources are forcing utilities to abandon centralized control architectures in favor of edge-computing-enabled orchestration platforms that manage bidirectional power flows at substation granularity.
Growth Catalysts
- EU Green Deal decarbonization mandates:Binding emissions reduction targets are compelling municipal utilities to accelerate smart meter deployment and grid automation investments across member states.
- F-Gas Regulation phase-down schedules:Restrictions on fluorinated greenhouse gases are driving replacement of conventional switchgear with digitally monitored, SF6-free alternatives that require integrated sensor networks.
- German grid modernization timelines:The most advanced distribution network upgrade schedules in Europe are concentrating vendor engineering resources and reference architecture development.
Market Restraints
- Semiconductor component volatility:Persistent shortages in industrial-grade microcontrollers and power electronics are extending smart meter production lead times and inflaming procurement costs.
- Municipal utility fragmentation:Thousands of small-scale water and electric cooperatives lack capital scale to standardize on single-vendor platforms, forcing expensive customization.
- Legacy SCADA interoperability constraints:Proprietary communication protocols in installed base systems resist seamless integration with cloud-native analytics platforms.
Strategic Opportunities
- Cloud-native DERMS platforms:Distributed energy resource management systems are penetrating underdigitized water utilities seeking unified visibility across pumping, treatment, and distribution assets.
- CSRD-mandated sustainability disclosure:Corporate Sustainability Reporting Directive requirements are creating certified vendor qualification advantages for platforms with embedded carbon accounting modules.
- AI-driven predictive maintenance convergence:Machine learning algorithms trained on operational telemetry are compressing outage response windows and enabling condition-based asset replacement.
Industry Challenges
- Cybersecurity certification complexity:IEC 62443 compliance timelines for critical infrastructure protection are delaying product releases and fragmenting vendor development roadmaps.
- SCADA-to-cloud integration friction:Utilities struggle to reconcile sub-second latency requirements of physical control systems with asynchronous data pipelines of enterprise analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Utilities Management Market |
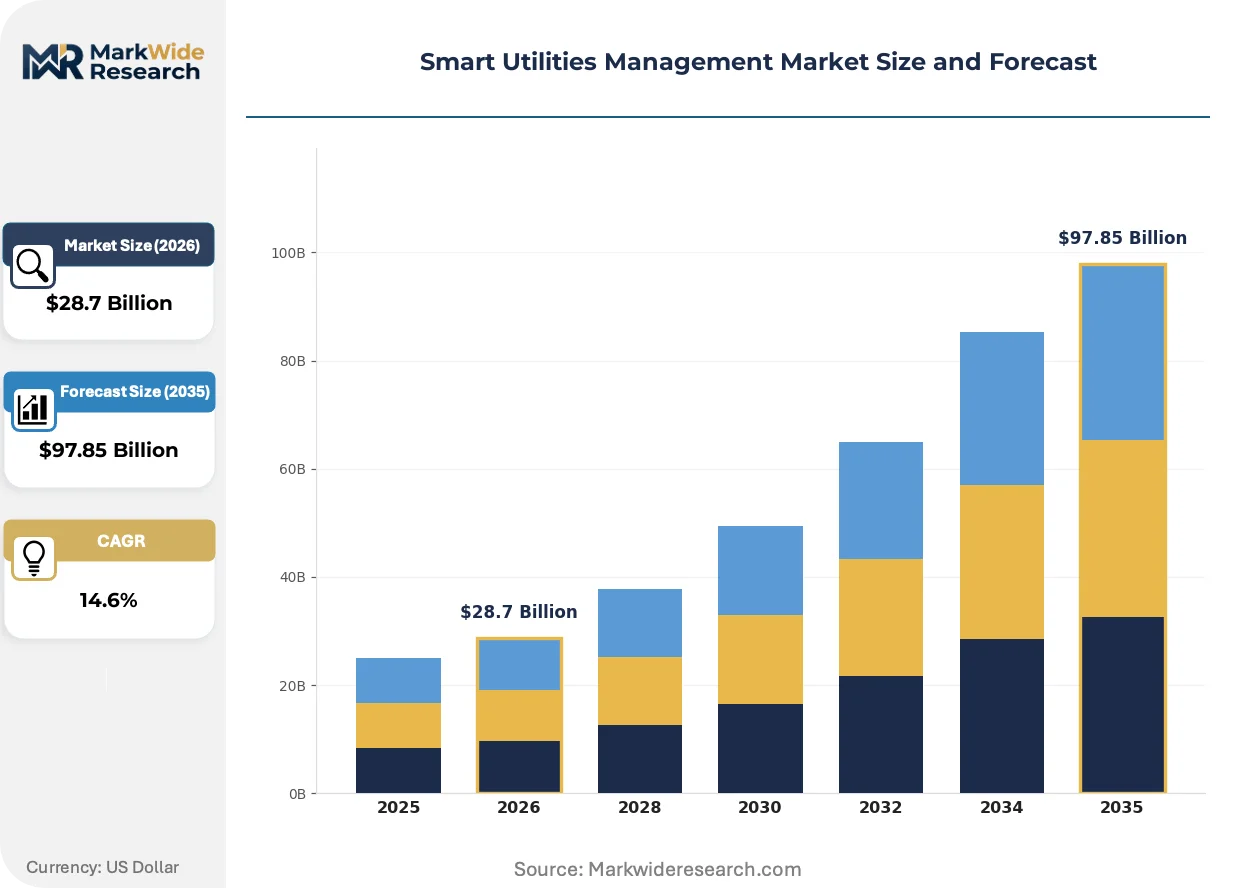
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $97.85 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meters, Grid Management Systems, Asset Management Solutions, Energy Management Software End User: Utilities, Industrial, Commercial, Residential Technology: IoT, Cloud Computing, AI, Data Analytics Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | IBM Corporation, Honeywell International Inc., ABB Ltd, Siemens AG, Schneider Electric SE, Itron Inc., Atos SE, Cisco Systems Inc., Landis+Gyr Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Utilities Management Market Evolving Landscape
Edge intelligence and software-defined substations are displacing hardware-centric grid architectures, compressing the boundary between operational technology and information technology layers in utility control rooms.
Digital twin technology is expanding into distribution network planning, enabling German utilities to simulate voltage fluctuation scenarios before physical asset deployment. Municipal operators in the Netherlands are adopting these platforms at accelerated procurement cycles. The technology is expanding into real-time operational decision support, collapsing the traditional separation between engineering design tools and live grid management systems.
The EPA's power plant emissions standards and FERC Order 2222 aggregation rules are reshaping capital allocation toward demand-response-enabling infrastructure. Compliance deadlines are compressing procurement timelines for advanced metering infrastructure. Battery storage developers in Texas and California are responding by bundling grid-edge control software with hardware proposals.
Outcome-based service contracts are displacing traditional equipment-purchase models in European municipal utilities, unbundling hardware ownership from performance guarantees. Vendors are absorbing operational risk through availability-based fee structures. This shift is most visible in French water utilities, where Veolia and Suez are restructuring vendor relationships around guaranteed leakage reduction metrics.
Smart Utilities Management Market Segmentation
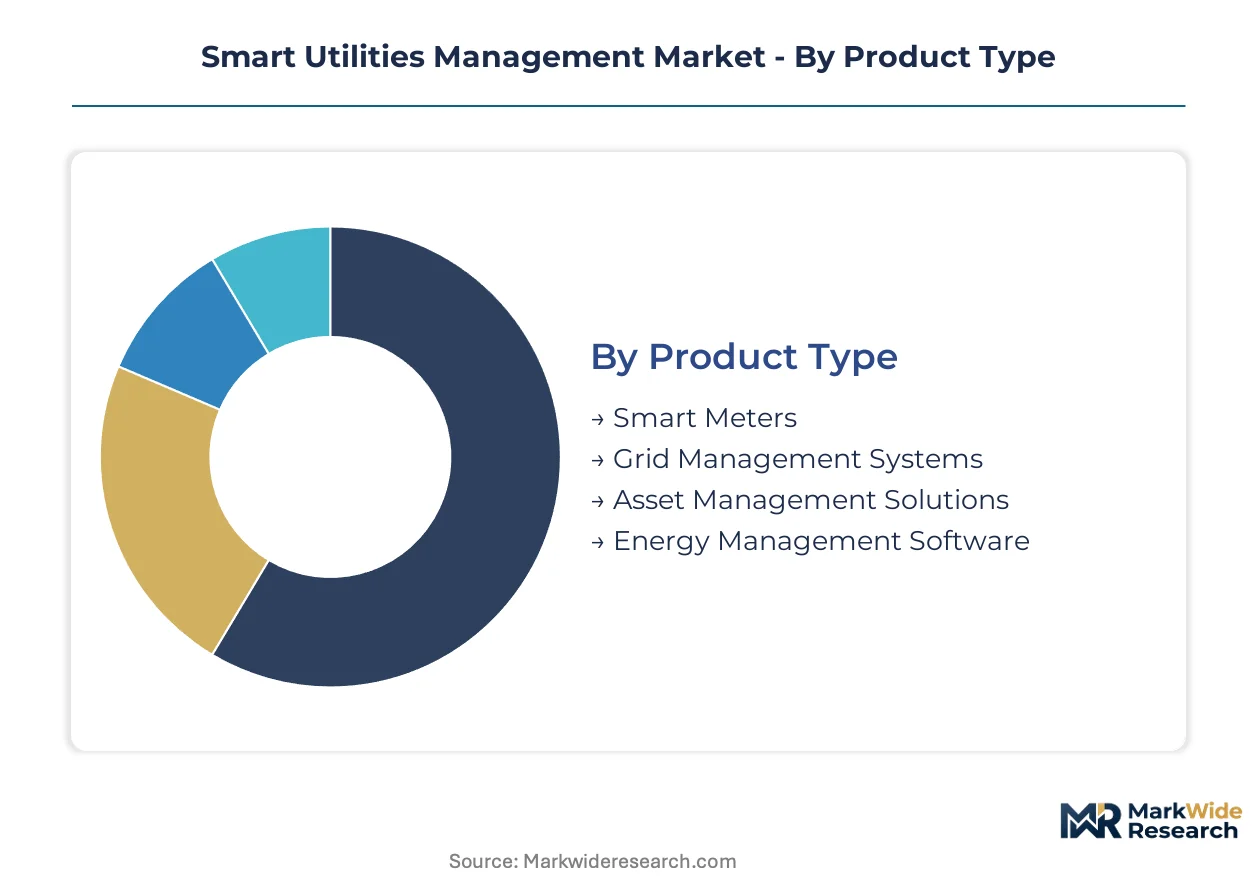
Segmentation in smart utilities management reveals how procurement priorities diverge between capital-intensive infrastructure replacement and software-driven optimization. Vendor positioning and margin capture depend heavily on which technology layer and deployment model utilities prioritize.
Product Type:
Smart meters anchor volume procurement while energy management software commands premium pricing expansion.
- Smart Meters:These devices measure consumption in real time and transmit encrypted telemetry through RF mesh or cellular networks. Deployment concentrates in Germany and the Netherlands where EU Green Deal mandates accelerate replacement cycles.
- Grid Management Systems:SCADA-adjacent platforms orchestrate distribution network operations with sub-second control loop latency. German municipal utilities dominate procurement as their modernization timelines outpace other member states.
- Asset Management Solutions:Condition monitoring systems track transformer health and switchgear performance across transmission hierarchies.
- Energy Management Software:Cloud-native platforms for distributed energy resource orchestration are climbing the fastest as utilities seek unified visibility across DER portfolios.
Today's leader: Smart Meters. Tomorrow's challenger: Energy Management Software.
End User:
Utility procurement scales through centralized tenders while commercial and industrial segments drive software attach rates.
- Utilities:Municipal electric and water cooperatives purchase integrated hardware-software stacks under multi-year service contracts. Fragmentation across thousands of small operators forces vendor customization investment.
- Industrial:Manufacturing facilities deploy behind-the-meter analytics to optimize demand charge management and participate in wholesale demand response markets.
- Commercial:Building portfolios leverage building-to-grid connectivity platforms for automated load flexibility.
- Residential:Smart thermostat and home energy management adoption spreads through utility rebate programs and time-of-use rate structures.
Utilities consume the hardware volume. Industrial buyers generate the software margin expansion.
Technology:
IoT and data analytics concentrate vendor margin pools while AI adoption accelerates in predictive maintenance applications.
- IoT:Sensor networks with AES-256 encrypted pipelines form the physical layer for telemetry collection. Sensor deployment costs have collapsed while algorithmic value extraction remains proprietary.
- Data Analytics:Operational intelligence platforms process sub-second telemetry into actionable grid optimization recommendations. German utilities lead adoption for voltage fluctuation scenario modeling.
- Cloud Computing:Elastic infrastructure supports distributed energy resource management systems across geographically dispersed assets.
- AI:Machine learning algorithms trained on historical outage data compress response windows through predictive failure classification.
IoT and data analytics dominate current procurement. AI represents the steepest expansion trajectory as utilities automate operational decision-making.
Deployment:
Cloud-based platforms gain share in new deployments while hybrid architectures bridge legacy SCADA investments.
- Cloud-Based:SaaS delivery models unbundle hardware ownership from performance guarantees under outcome-based contracting structures visible in French water utility procurement.
- Hybrid:Split architectures reconcile sub-second latency requirements of physical control systems with asynchronous enterprise analytics pipelines.
- On-Premise:Air-gapped installations persist in critical infrastructure where IEC 62443 compliance demands localized security boundaries.
- Edge Computing:Substation-level processing enables bidirectional power flow management without round-trip latency to centralized data centers.
Hybrid deployments protect installed base value. Edge computing captures the fastest-growing architecture preference as grid decentralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in smart meter deployment density, while the United States and China pursue divergent regulatory pathways for grid decentralization. National policy frameworks and utility ownership structures create distinct procurement rhythms across major markets.
United States
FERC Order 2222 aggregation rules and EPA power plant emissions standards compress procurement timelines for advanced metering infrastructure. Texas and California battery storage developers bundle grid-edge control software with hardware proposals. The Southeast sees accelerating utility investment in outage management systems following recent weather resilience mandates.
Germany
EU Green Deal decarbonization targets and the national Grid Expansion Acceleration Act drive the continent's most aggressive distribution network upgrade schedules. Municipal utilities in Bavaria and North Rhine-Westphalia concentrate vendor engineering resources through multi-year service contracts. Berlin-Brandenburg serves as the primary testbed for digital twin-enabled voltage fluctuation modeling.
China
Dual carbon goals and provincial smart city initiatives expand procurement of integrated water-electricity management platforms. State Grid Corporation tenders in the Yangtze River Delta prioritize edge-computing substations for renewable integration. Shenzhen and Shanghai municipal utilities lead adoption of AI-driven predictive maintenance for transformer fleets.
France
CSRD-mandated sustainability disclosure redirects procurement toward vendors with certified carbon accounting modules. Outcome-based service contracts restructure vendor relationships around guaranteed leakage reduction metrics in Paris and Lyon water utilities. The national Linky smart meter program enters its final deployment phase.
Netherlands
EU F-Gas Regulation phase-down schedules accelerate replacement of SF6 switchgear with digitally monitored alternatives. Municipal operators in Randstad cities adopt digital twin platforms at procurement cycles faster than European peers. Rotterdam's port utility pilots bidirectional power flow management for electrified shipping infrastructure.
Smart Utilities Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and integration service layers. The market exhibits tiered concentration where large-scale grid modernization contracts cluster with integrated vendors, while fragmentation persists in municipal utility segments. Three archetypes dominate: industrial automation conglomerates with hardware-software depth, IT-centric platform providers with cloud-native architectures, and metering specialists with embedded communication expertise. Competitive moves center on outcome-based contracting structures and edge-computing capability acquisition.
Among industrial automation conglomerates, Siemens AG and ABB Ltd exemplify integrated hardware-software positioning across European grid modernization programs. Honeywell International Inc. sits within the building-to-grid connectivity tier, extending automation franchises into utility operations. Schneider Electric SE anchors the digital energy management archetype through distributed resource orchestration platforms.
| Leading Market Players |
|---|
| IBM Corporation |
| Honeywell International Inc. |
| ABB Ltd |
| Siemens AG |
| Schneider Electric SE |
| Itron Inc. |
| Atos SE |
| Cisco Systems Inc. |
| Landis+Gyr Group AG |
| Others |
Value Network & Pricing Analysis
EU Green Deal procurement mandates for certified carbon accounting modules are forcing vendors to absorb compliance costs upfront, compressing margins on standardized hardware while creating pricing premiums for integrated software-telemetry bundles. Municipal utilities in Germany and the Netherlands concentrate demand through multi-year service contracts that shift risk to vendors through availability-based fee structures.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for industrial-grade microcontrollers and power electronics that anchor smart meter production. Three-tier pricing structure across premium, standard, and economy levels separates vendors with IEC 62443 cybersecurity certification from uncertified competitors, with customization depth and after-sales service bundling as secondary differentiation drivers. Pricing pressure stems from semiconductor component volatility extending production lead times. Municipal water cooperatives exhibit highest price sensitivity due to capital constraints, while German grid operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and China coordinate hub-and-spoke patterns for sensor network components and encrypted communication modules. Manufacturing concentration in Germany and China for switchgear assemblies, with South Korea supplying advanced power semiconductors, creates dependency on cross-border component flows. Raw material exposure runs through rare earth elements for magnetics, lithium-ion cells for substation backup systems, and copper for grid infrastructure. Single-source vulnerability in industrial microcontroller supply presents structural risk. Distribution runs through authorized system integrators serving fragmented municipal utility bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart utilities management functions as a stable compounder where regulatory decarbonization mandates create predictable procurement cycles across European and North American markets.
For Market Incumbents: To counter cloud-native platform entrants from IT-centric providers, Siemens AG and ABB Ltd should deepen hardware-software integration through edge-computing substation acquisitions, while locking municipal accounts via CSRD-compliant sustainability reporting modules that entrench switching costs. For New Entrants and Emerging Players: Small-scale water cooperatives in France and the American Southeast represent underserved buyer archetypes with unmet demand for unified pumping-treatment-distribution visibility. Entry through SaaS-based DERMS platforms with rapid deployment cycles bypasses capital-intensive hardware competition, with French outcome-based contracting structures offering the most penetrable procurement channel. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play AI-driven predictive maintenance specialists holding proprietary outage classification algorithms. Five-to-ten year viability hinges on regulatory durability of EU Green Deal enforcement and FERC Order 2222 aggregation rules. Signal to monitor: German municipal utility adoption velocity for digital twin-enabled voltage fluctuation modeling as inflection indicator for platform standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Substation Acquisition | Captures bidirectional power flow management capability as grid decentralization accelerates in Germany. |
| CSRD Compliance Module Development | Creates vendor qualification advantage for EU Green Deal-mandated sustainability disclosure requirements. |
| Outcome-Based Service Contract Expansion | Mirrors Veolia and Suez restructuring in French water utilities around guaranteed leakage reduction metrics. |
| AI Predictive Maintenance Platform Launch | Compresses outage response windows through machine learning trained on historical transformer failure telemetry. |
| SF6-Free Switchgear Manufacturing Scale-Up | Aligns production with EU F-Gas Regulation phase-down schedules accelerating replacement demand. |
Research Methodology
Coverage spans Germany, the United States, China, France, and the Netherlands, with primary inputs from each market through structured interviews with utility planning officers, grid operations directors, smart metering procurement leads, and EPC contractors specializing in distribution automation. Secondary validation draws from FERC filings, EPA emissions compliance databases, EU CSRD disclosure registries, and State Grid Corporation tender announcements. Bottom-up segment sizing triangulates against top-down macroeconomic indicators.
Granularity-level modeling operates at product-type, end-user, technology, and deployment dimension intersections, with additional disaggregation by regulatory framework cluster. CAGRs derive from segment-level growth rate reconciliation across the projection horizon. Forecast inputs incorporate German Grid Expansion Acceleration Act implementation timelines and FERC Order 2222 aggregation rule adoption curves.
Underlying measurement precision varies by segment; smart meter deployment volumes carry tighter precision than AI-driven software adoption curves. Forecasts reflect documented assumptions around EU Green Deal enforcement durability and semiconductor supply normalization trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
North America Residential Lighting Control System Market
Energy Management Systems
Global Data Center Energy Management Solution Market
Energy Management Systems
Asia-Pacific Energy Management System Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Advanced Server Energy Monitoring Tools Market
Energy Management Systems
India Home Ventilation System Market
Energy Management Systems
Home Energy Management System Market
Energy Management Systems
Smart Thermostat Market
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
Global Personal Cooling Device Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
District Cooling Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
Cooling Management System Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
IoT Smart Gas Meter Market