
 Outage Management System (OMS) Market | 2026-2036
Outage Management System (OMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Outage Management System (OMS) Market Intelligence
Platform licensing revenue is tilting toward cloud-native architectures as utilities abandon perpetual licenses for subscription models. Oracle Corporation leverages its enterprise database dominance to embed OMS within broader utility IT ecosystems. Schneider Electric anchors its position through deep integration with grid hardware and SCADA portfolios. Siemens AG competes by extending its digital twin capabilities into predictive outage forecasting.
An outage management system integrates fault detection algorithms, network topology processors, and geographic information systems to automate power restoration workflows and minimize customer-minutes interrupted. The platform typically processes SCADA feeds, AMI meter pings, and customer calls through rules-based engines to isolate faults and dispatch repair crews. Cloud-based deployment now captures the fastest expansion as utilities seek elastic compute for storm-scale event processing, while on-premises installations retain dominance among security-sensitive nuclear and defense-adjacent operators. Fault detection solutions lead solution-type revenue due to mandatory NERC reliability standards, whereas analytics modules represent the emerging margin pool as predictive maintenance contracts proliferate.
FERC Order 2222 in the United States compels grid operators to integrate distributed energy resources, forcing OMS vendors to accommodate bidirectional power flows and prosumer endpoints. The EU Cybersecurity Act and IEC 62351 standards mandate encrypted utility communications, raising product certification barriers for non-compliant entrants. Stakeholders must monitor how AI-driven storm damage prediction reshapes procurement criteria before the next major regulatory refresh cycle.
Market Dynamics
Cloud-native architectures are compressing deployment cycles from months to weeks, forcing incumbent vendors to restructure licensing models and forcing utilities to retrain IT personnel for containerized operations.
Growth Catalysts
- FERC Order 2222:US grid operators must integrate distributed energy resources, compelling OMS platforms to process bidirectional power flows and prosumer endpoints.
- AMI meter penetration:Advanced metering infrastructure generates real-time fault signals that feed directly into automated restoration algorithms, shortening outage duration.
- Storm intensity patterns:Severe weather frequency in the southeastern United States drives elastic compute demand for event-scale processing during peak disruption periods.
Market Restraints
- Cybersecurity certification costs:IEC 62351 compliance requires encrypted utility communications, raising product certification barriers for smaller software entrants.
- Legacy SCADA lock-in:Decades-old control system investments at municipal utilities create technical debt that slows API-based integration timelines.
- Specialized talent scarcity:The intersection of power systems engineering and cloud DevOps expertise concentrates in competitive labor markets near technology hubs.
Strategic Opportunities
- Rural cooperative utilities:Federally-backed rural electrification programs in India create first-mover advantages for SaaS OMS providers serving under-digitized distribution networks.
- Predictive maintenance contracts:AI-driven storm damage forecasting enables vendors to shift from perpetual licenses to recurring revenue models tied to outcome metrics.
- Digital twin convergence:Integration between OMS platforms and grid simulation engines opens adjacent revenue streams in asset health monitoring and capacity planning.
Industry Challenges
- Multi-vendor integration complexity:Utilities operating hybrid environments must reconcile proprietary data models between GIS, SCADA, and AMI systems without standard middleware.
- Operational technology cybersecurity:NERC CIP compliance mandates air-gapped networks for critical cyber assets, complicating cloud migration roadmaps for transmission operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outage Management System (OMS) Market |
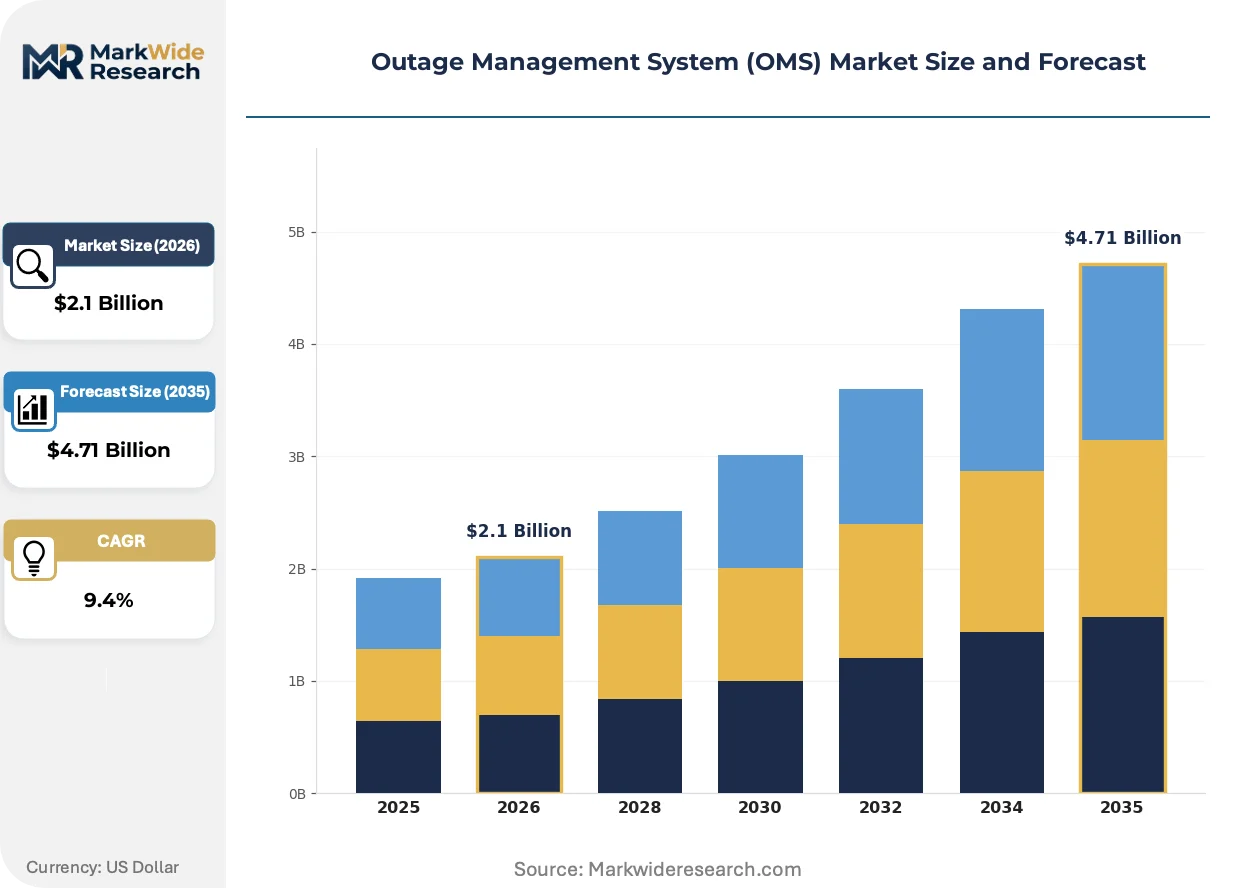
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge, Virtual Solution Type: Fault Detection, Outage Restoration, Customer Information, Network Monitoring, Analytics Application: Electric Utilities, Water Utilities, Gas Distribution, Renewable Microgrids, Smart Cities End User: Distribution Companies, Transmission Operators, Service Providers, Regulatory Bodies, System Integrators |
| Companies Covered | Oracle Corporation, CGI Inc, ABB Ltd, Futura Systems Inc, Advanced Control Systems Inc, General Electric Company, Schneider Electric, S&C Electric Company, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outage Management System (OMS) Market Strategic Shifts & Innovations
Artificial intelligence is rewriting outage prediction and response protocols, compressing the gap between fault detection and crew dispatch while forcing vendors to retrain algorithms on region-specific vegetation and infrastructure patterns.
Fault detection algorithms are migrating from rules-based engines to machine learning models trained on historical storm damage and vegetation encroachment data. Mid-sized municipal utilities in the Great Plains region are piloting these systems to reduce patrol-based line inspection costs. The technology is migrating from pilot deployments to standard procurement requirements in RFP evaluations.
The EU Cybersecurity Act mandates encrypted utility communications and product certification for critical infrastructure software. Vendors must submit OMS platforms to third-party security evaluation before deployment in EU member states. German distribution system operators are advancing procurement timelines to meet 2025 compliance deadlines, compressing vendor sales cycles.
Subscription pricing is displacing perpetual licensing across North American electric cooperatives and investor-owned utilities. Buyers now prioritize total cost of ownership metrics over upfront capital expenditure in vendor selection processes. This preference shift is most visible in competitive RFPs issued by mid-Atlantic states seeking storm resilience upgrades.
Outage Management System (OMS) Market Segmentation
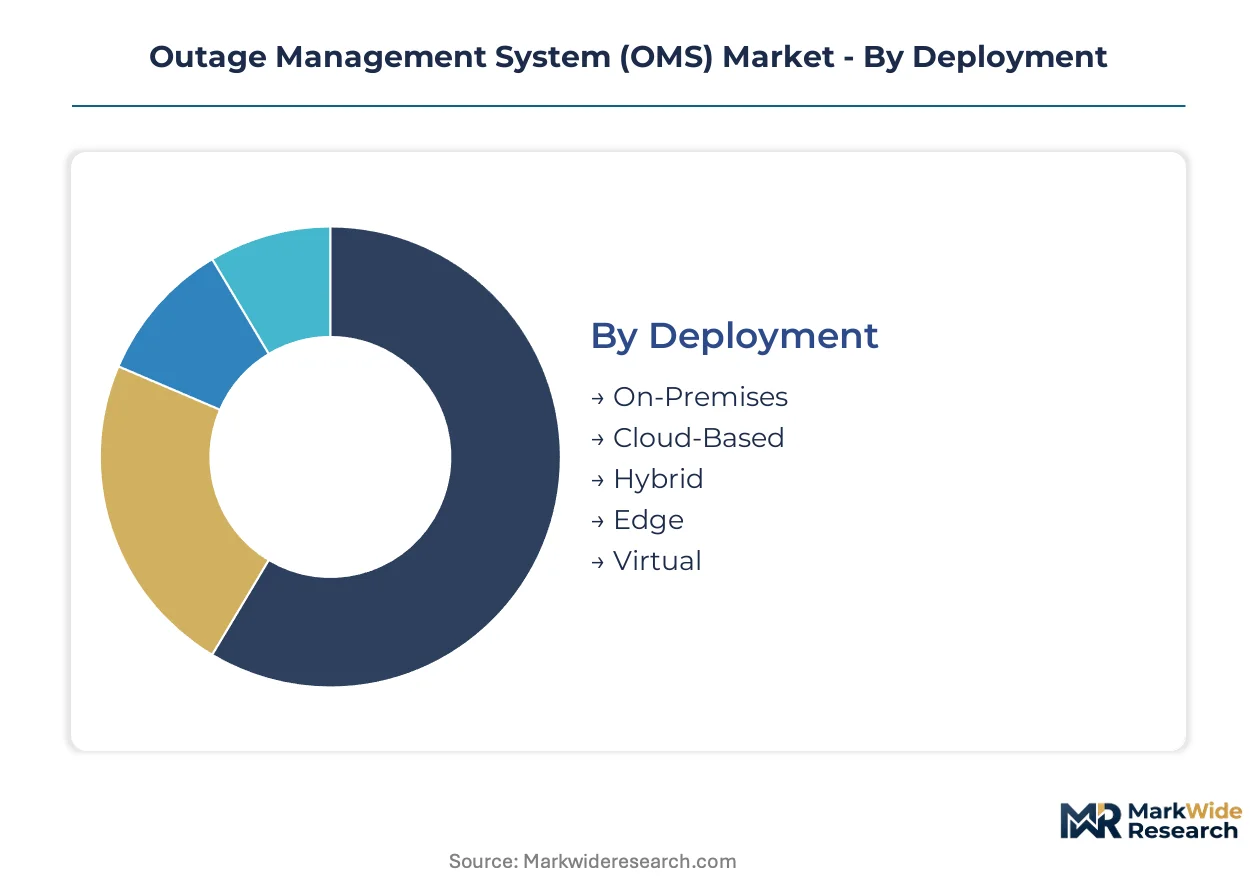
OMS procurement patterns diverge sharply across deployment architectures and utility operational models. Vendors must align product roadmaps with distinct compliance requirements, integration timelines, and cybersecurity postures that vary by segment.
Deployment:
After-sales service intensity escalates with deployment complexity, as edge and hybrid configurations demand sustained field engineering support that perpetual-license vendors struggle to provision.
- Cloud-Based:Elastic compute resources enable storm-scale event processing without capital-intensive infrastructure. United States electric cooperatives in hurricane-prone southeastern states are migrating fastest, driven by FERC resilience mandates and subscription budgeting flexibility.
- On-Premises:Air-gapped installations serve nuclear-adjacent transmission operators and defense-critical substations where NERC CIP mandates prohibit external network connectivity. Germany's distribution system operators maintain these configurations to satisfy EU Cybersecurity Act certification timelines.
- Hybrid:Split architectures partition sensitive SCADA control from customer-facing analytics workloads.
- Edge:Localized processing reduces latency for automated feeder reconfiguration in remote distribution networks.
- Virtual:Containerized deployments accelerate patch cycles for municipal utilities with limited IT staff.
By volume, On-Premises leads. By growth pace, Cloud-Based is ahead.
Solution Type:
Cost tier stratification separates mandatory compliance modules from discretionary analytics investments, with fault detection commanding premium pricing due to NERC reliability standard enforcement.
- Fault Detection:Real-time algorithms process SCADA feeds and AMI meter pings to isolate network faults automatically. This segment concentrates revenue among United States investor-owned utilities facing mandatory SAIDI/SAIFI performance targets.
- Analytics:Predictive maintenance modules leverage vegetation encroachment data and historical storm damage patterns. Indian distribution companies under the rural electrification program are piloting these systems to reduce patrol-based inspection costs.
- Outage Restoration:Crew dispatch optimization engines integrate with mobile workforce management platforms.
- Customer Information:Outage notification portals and interactive voice response systems reduce call center load.
- Network Monitoring:Topology processors maintain real-time connectivity models for switching operations.
Fault Detection generates the highest absolute revenue. Analytics exhibits the steepest expansion trajectory.
Application:
Application diversity reflects infrastructure digitization maturity, with electric utilities commanding deployment sophistication that water and gas operators are only beginning to replicate.
- Electric Utilities:Comprehensive platforms integrate GIS, SCADA, AMI, and workforce management for automated restoration workflows. Demand concentrates in Germany, where distribution system operators are advancing procurement to meet EU Green Deal resilience requirements.
- Smart Cities:Converged platforms coordinate streetlight control, traffic signal backup power, and public safety communications during grid disruptions. Municipal deployments in India are expanding fastest under federally-backed urban infrastructure programs.
- Water Utilities:Pump station power reliability and pressure management during outages drive adoption.
- Gas Distribution:Valve automation and pressure monitoring systems require hardened communication protocols.
- Renewable Microgrids:Bidirectional power flow management accommodates prosumer endpoints and battery storage dispatch.
Electric Utilities dominates procurement volume. Smart Cities is climbing the fastest.
End User:
Customer type determines procurement authority and integration complexity, with transmission operators imposing the most stringent cybersecurity and latency requirements.
- Distribution Companies:Mid-sized municipal utilities and rural cooperatives represent the broadest addressable base, particularly in the United States Great Plains region where vegetation management costs drive predictive analytics demand.
- Transmission Operators:Regional transmission organizations and independent system operators require NERC CIP-compliant architectures with air-gapped critical cyber assets. These buyers concentrate in North America where FERC enforcement carries statutory penalties.
- Service Providers:Third-party maintenance contractors procure white-label platforms for multi-utility contracts.
- Regulatory Bodies:Government agencies commission OMS for grid resilience auditing and compliance verification.
- System Integrators:Engineering firms bundle OMS with broader SCADA and AMI deployment projects.
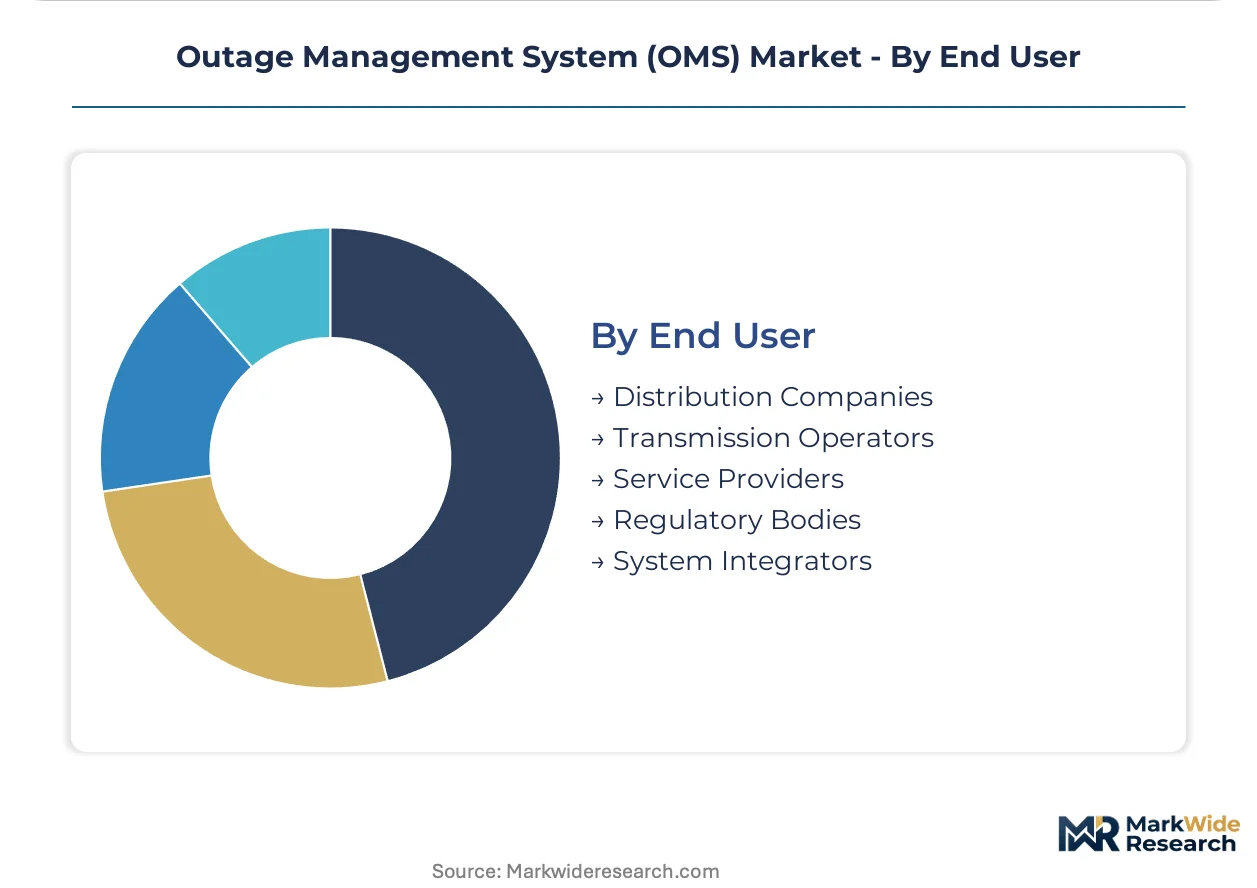
Distribution Companies account for the largest transaction volume. Transmission Operators are gaining share fastest as NERC CIP refresh cycles accelerate replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor engineering resources concentrate in Germany, the United States, and India where grid modernization timelines compress procurement cycles. These three markets generate disproportionate platform deployment velocity due to overlapping regulatory mandates and infrastructure investment programs.
United States
FERC Order 2222 compels regional transmission organizations to integrate distributed energy resources into OMS workflows. NERC CIP cybersecurity standards enforce air-gapped architectures for critical substation assets. Southeast electric cooperatives in Florida and Georgia are migrating fastest to cloud-native platforms for hurricane-scale event processing.
Germany
Distribution system operators are advancing procurement timelines to satisfy EU Cybersecurity Act certification deadlines. The EU Green Deal's resilience requirements mandate automated restoration capabilities for renewable-heavy grids. Industrial clusters in North Rhine-Westphalia and Bavaria host concentrated vendor implementation teams serving Central European utilities.
India
Rural electrification programs under the central government's infrastructure initiative create first-mover advantages for SaaS OMS providers. Central Electricity Authority regulations push distribution companies toward digitized outage tracking. Maharashtra and Gujarat distribution utilities are piloting predictive analytics modules to reduce vegetation management patrol costs.
United Kingdom
Ofcom's critical infrastructure resilience guidelines pressure distribution network operators to shorten customer-minutes interrupted metrics. The country's net-zero grid transition requires OMS platforms to accommodate bidirectional power flows from residential solar and battery storage. London and Southeast England utilities lead procurement sophistication for storm damage prediction systems.
Japan
METI's grid resilience investment programs fund outage management upgrades for earthquake-prone distribution networks. The country's nuclear restart timeline maintains demand for air-gapped, NERC-equivalent control system architectures. Tokyo Electric Power and regional utilities in the Kansai corridor are standardizing on hybrid cloud-edge deployments for automated feeder reconfiguration.
Outage Management System (OMS) Market Key Industry Players
Enterprise software conglomerates and industrial automation specialists split the market along integration-depth lines. The vendor base organizes into three strategic archetypes: database-centric platform providers leveraging enterprise IT ecosystems, hardware-integrated specialists bundling OMS with grid equipment portfolios, and pure-play utilities software firms competing on sector-specific functionality. Dominant competitive moves include cloud-native architecture transitions and predictive analytics capability acquisitions.
Within the enterprise software tier, Oracle Corporation represents the database-centric archetype with enterprise utility IT embedding strategies. Schneider Electric and Siemens AG exemplify the industrial automation model, anchoring competitive positioning through SCADA and grid hardware integration. These three companies occupy the premium tier where procurement decisions hinge on existing vendor relationships and ecosystem lock-in rather than standalone feature comparison.
| Leading Market Players |
|---|
| Oracle Corporation |
| CGI Inc |
| ABB Ltd |
| Futura Systems Inc |
| Advanced Control Systems Inc |
| General Electric Company |
| Schneider Electric |
| S&C Electric Company |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
Undercapacity in cloud-native software engineering across Germany and the United States drives premium pricing for subscription OMS platforms while compressing margins for legacy on-premises vendors struggling to retrain workforces. Utilities respond by consolidating procurement around fewer suppliers with proven containerization expertise, amplifying pricing power for SaaS-native vendors and squeezing hardware-integrated incumbents into defensive bundling strategies.
Pricing Analysis
NERC CIP compliance mandates dictate the pricing tier structure across North American transmission operators, with air-gapped certification commanding substantial premiums over standard cloud deployments. Three-tier pricing structure across premium, standard, and economy levels separates NERC-validated platforms from FERC Order 2222-compliant mid-tier offerings and basic municipal utility packages. Cost compression in the economy tier intensifies because Indian distribution companies leverage federal rural electrification subsidies to negotiate volume SaaS contracts. Municipal utilities in the United States Great Plains exhibit highest price sensitivity due to constrained capital budgets, while German distribution system operators show lowest sensitivity as EU Cybersecurity Act deadlines eliminate negotiation leverage.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize procurement between United States electric cooperatives and OMS vendors, straining working capital for smaller software firms. Engineering talent concentrates in Germany, the United States, and India, with container orchestration specialists drawing premium compensation in North Rhine-Westphalia and Bavaria industrial clusters. The supply chain draws from Taiwan for edge-computing hardware, Ireland for EU data residency infrastructure, and domestic development centers for customization layers. Single-source vulnerability runs through specialized SCADA protocol translators controlled by legacy industrial automation conglomerates. Distribution runs through direct enterprise sales teams for large investor-owned utilities and regional system integrators for mid-market municipal deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OMS adoption sits in early-cycle expansion as FERC Order 2222 and EU Green Deal resilience mandates force utilities to replace legacy fault detection systems before compliance deadlines. Cloud-native architectures penetration remains below saturation across municipal utilities, creating runway for subscription revenue conversion.
For Market Incumbents: Insulate recurring revenue streams by embedding predictive analytics modules into existing SCADA integration contracts before pure-play AI vendors achieve technical parity. Prioritize backward integration into vegetation encroachment data services to lock out specialized analytics entrants. Accelerate certification investment for IEC 62351 compliance to exploit EU Cybersecurity Act deadline compression.
For New Entrants and Emerging Players: Mid-market municipal utilities in the United States Great Plains represent the most penetrable entry point given vegetation management cost pressures and limited incumbent customization flexibility. Rural electrification distribution companies in Maharashtra and Gujarat offer white-label SaaS opportunities through channel partnerships with federally-backed infrastructure consultants. Target outcome-based pricing tied to SAIDI/SAIFI improvement metrics to differentiate from perpetual-license incumbents.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native OMS vendors serving United States electric cooperatives with hurricane-scale elastic compute contracts. Long-term viability centers on platforms with proven AI model training pipelines for region-specific storm damage prediction. Monitor NERC CIP refresh cycle announcements as inflection indicators for replacement demand acceleration among transmission operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Migration | Elastic compute provisioning enables Florida and Georgia cooperatives to process hurricane-scale outages without capital infrastructure. |
| Predictive Analytics Acquisition | Machine learning for vegetation encroachment prediction shifts vendor economics from licenses to recurring outcome-based contracts. |
| EU Cybersecurity Certification | IEC 62351 compliance opens German distribution operator procurement timelines compressed by 2025 regulatory deadlines. |
| SCADA Protocol Integration | Deep embedding with legacy control systems creates switching costs that protect incumbent positioning against SaaS challengers. |
| Rural Cooperative Channel Partnership | Federally-backed electrification programs in India create first-mover advantages for SaaS providers serving under-digitized networks. |
Research Approach
Initial hypotheses were tested against primary input from utility planning officers, grid operators, EPC contractors, and integration specialists and refined through secondary validation across regulatory filings and infrastructure databases. Primary interviews captured procurement authority structures, RFP evaluation criteria, and cloud migration timelines at investor-owned utilities, electric cooperatives, and municipal distribution companies. Secondary sources included FERC orders, NERC reliability standards documentation, EU Cybersecurity Act implementation guidance, and Central Electricity Authority regulations. Bottom-up deployment forecasts triangulated against top-down grid modernization budget allocations.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation by deployment architecture, solution type, utility operational model, and regional regulatory framework. CAGRs derived from utility capital expenditure trajectories, AMI meter penetration curves, and storm damage frequency patterns. Forecast inputs incorporated FERC Order 2222 implementation timelines, EU Green Deal resilience procurement acceleration, and Indian rural electrification program milestones.
Practitioners should monitor NERC CIP refresh cycle announcements, EU Cybersecurity Act enforcement actions, and FERC distributed energy resource integration deadlines for early signals of procurement acceleration or delay. Forecasts reflect assumptions regarding regulatory timeline adherence, cloud workforce availability, and storm intensity pattern continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
Smart Air Cleaners Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Shared Power Bank Market
Energy Management Systems
Advanced Server Energy Monitoring Tools Market
Energy Management Systems
Data Center Power Management Market
Energy Management Systems
North America Residential Lighting Control System Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
Global Digital Thermostats Market
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
Meter Data Management System Market
Energy Management Systems
Smart Cooling Systems Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Grid Operations Management Software Market